
 Acetyl Serine Market | 2026-2036
Acetyl Serine Market Size, Share, and Industry Trends Forecast 2026-2036
Acetyl Serine Market Outlook
Buyer concentration among pharmaceutical manufacturers is consolidating as large-scale peptide drug developers reduce supplier counts to secure batch consistency. Merck KGaA leverages its analytical standards portfolio to anchor quality assurance relationships with formulation clients. Thermo Fisher Scientific Inc. competes through distribution density in North American research channels. Wuxi Jinghai Amino Acid Co., Ltd. dominates captive production for regional pharmaceutical intermediates.
Acetyl serine refers to N-acetyl-L-serine, an acetylated amino acid derivative with a molecular formula of C5H9NO4, typically synthesized through acetylation of L-serine using acetic anhydride or enzymatic acetyltransferase processes, serving primarily as a building block in peptide synthesis and cell culture media formulations. Powder formulations lead volume due to bulk intermediate demand from pharmaceutical manufacturers, while solutions represent the fastest-growing format as ready-to-use reagents reduce compounding labor in research laboratories. Nutraceutical applications sit in a mature phase with stable margin pools, whereas pharmaceutical-grade segments command premium positioning through certification requirements.
China's NMPA enforces amino acid purity thresholds through GB standards that filter subscale producers from pharmaceutical supply chains. The EPA and FDA jointly shape US market access through residual solvent limits and current good manufacturing practice audits of foreign active ingredient facilities. REACH registration obligations in Europe add compliance cost layers that favor incumbent suppliers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving pharmacopeial monograph revisions across jurisdictions to anticipate qualification timeline shifts.
Market Dynamics
Peptide therapeutic developers are consolidating supplier bases to secure batch-to-batch consistency, compressing vendor counts from fragmented amino acid sourcing toward qualified single-source relationships anchored by pharmacopeial certification.
Growth Catalysts
- Peptide drug pipeline expansion:Contract manufacturers in Jiangsu and Zhejiang provinces are scaling acetyl serine procurement to serve GLP-1 agonist and oligonucleotide conjugate programs.
- NMPA purity enforcement:China's GB standards for amino acid pharmaceutical intermediates are filtering subscale producers, redirecting volume toward certified suppliers.
- Enzymatic acetylation:Biocatalytic processes are displacing chemical acetylation in high-purity grades, reducing residual solvent burdens and simplifying FDA pre-approval inspections.
Market Restraints
- L-serine feedstock volatility:Fermentation-derived L-serine supply concentrates among Chinese and Japanese producers, exposing formulators to glycerol and glucose input cost swings.
- Pharmaceutical-grade certification barriers:USP and EP monograph compliance requires 18-24 month qualification timelines that lock out regional chemical suppliers.
- Cell culture media substitution:Chemically defined serum-free formulations are reducing acetyl serine loading per liter compared to legacy protein hydrolysate systems.
Strategic Opportunities
- Indian CDMO penetration:PLI scheme incentives for active pharmaceutical ingredient manufacturing are drawing acetyl serine demand toward Maharashtra and Gujarat contract development clusters.
- Continuous flow synthesis:Microreactor technology convergence with in-line PAT analytics is enabling real-time release testing that compresses batch release cycles.
- Research reagent channel expansion:Direct-to-laboratory e-commerce platforms are bypassing traditional distributor markups for gram-scale orders.
Industry Challenges
- Analytical method transfer gaps:Pharmacopeial monograph updates for N-acetyl amino acid identity testing are outpacing QC team training at mid-scale manufacturers.
- Multi-jurisdiction dossier maintenance:Simultaneous NMPA, FDA, and EMA filing requirements are straining regulatory affairs capacity without dedicated amino acid specialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetyl Serine Market |
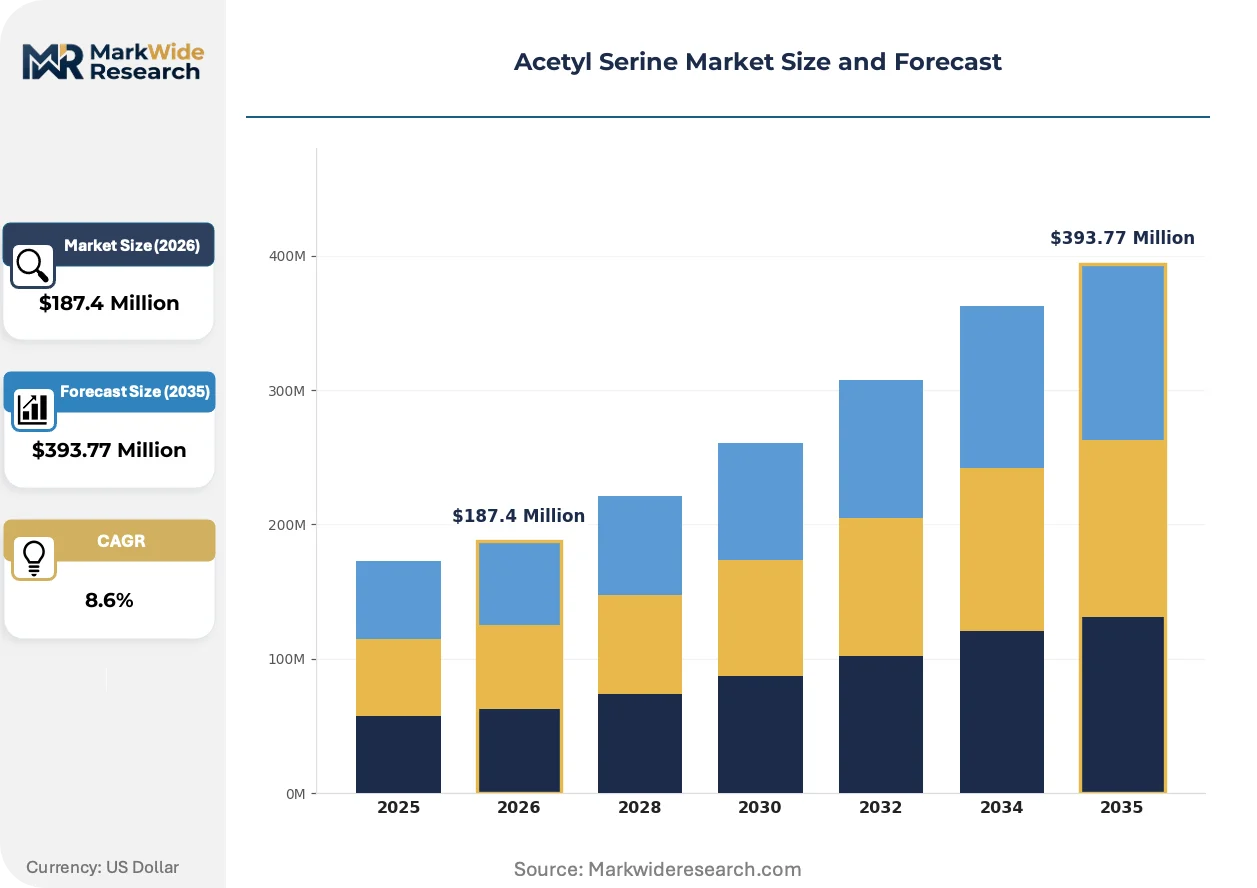
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Tablets, Solutions Application: Nutraceuticals, Pharmaceuticals, Dietary Supplements, Cosmetics End User: Healthcare Providers, Research Institutions, Consumers, Manufacturers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Hanhong Scientific, Tianjin Pharmaceutical Co. Ltd., Merck KGaA, WUHAN DONG KANG YUAN TECHNOLOGY CO., LTD., Wuxi Jinghai Amino Acid Co., Ltd., Guangzhou LES Biological Technology Co., Ltd., Shanghai Bide Pharmaceutical Technology Co., Ltd., Qingdao Samin Chemical Co., Ltd., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetyl Serine Market Strategic Shifts
Process intensification and regulatory data integrity requirements are converging to reshape how acetyl serine manufacturers validate and release production batches.
Continuous manufacturing equipment is integrating into acetyl serine production lines, replacing batch-wise acetylation with plug-flow reactor systems that reduce solvent inventory and enable tighter temperature control. Thermo Fisher Scientific and Merck KGaA are qualifying these platforms for pharmaceutical-grade output. The technology is integrating process analytical technology sensors that transmit real-time purity data directly into regulatory submission packages.
REACH registration obligations for acetylated amino acid derivatives are tightening substance volume tracking across European formulators, forcing non-EU suppliers to appoint only representatives or establish EU-based legal entities. ECHA enforcement of updated safety data sheet requirements is redirecting procurement toward registrants with full dossier compliance. Laboratory chemical distributors in Germany and Switzerland are responding by consolidating supplier panels to reduce downstream compliance liability.
Formulation clients are consolidating annual purchase agreements into multi-year supply contracts with locked pricing and dedicated manufacturing slots. Large-scale peptide developers are displacing spot-market purchasing through master service agreements that bundle acetyl serine with other protected amino acids. This pattern concentrates most visibly among US-based biotechs with IND-stage programs seeking supply security for clinical trial material campaigns.
Acetyl Serine Market Segmentation
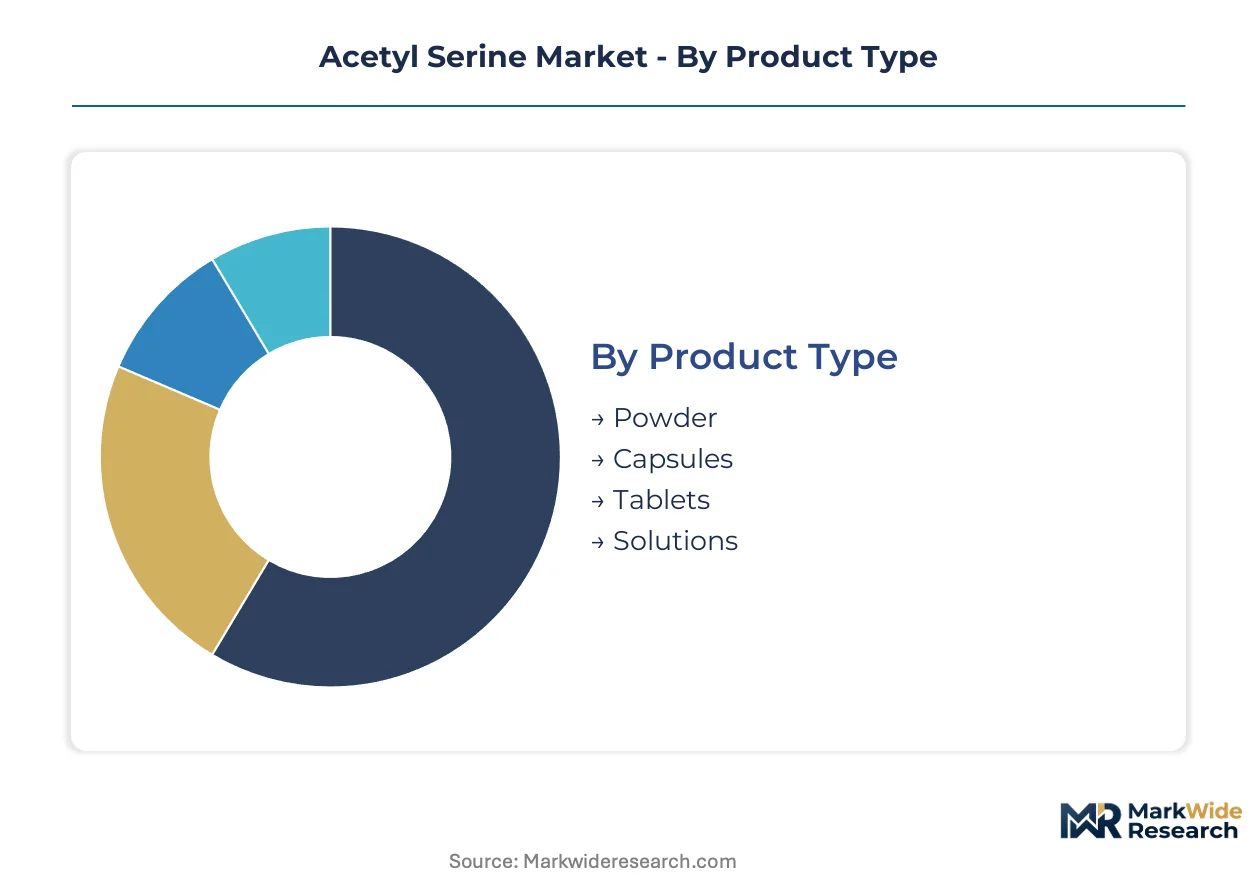
Acetyl serine market segmentation reveals how specification grades, formulation formats, and channel structures align with divergent buyer requirements across pharmaceutical synthesis, research applications, and consumer wellness. Understanding these divides exposes where margin pools concentrate and where supplier qualification barriers create defensive positioning.
Product Type:
Specification purity and physical state determine handling protocols, stability profiles, and regulatory qualification pathways for downstream users.
- Powder:Bulk crystalline or lyophilized material with defined particle size distributions serves pharmaceutical intermediate procurement from peptide manufacturers in Jiangsu and Zhejiang provinces. Powder formulations dominate volume throughput as contract manufacturers stockpile certified lots for multi-kilogram campaigns.
- Solutions:Ready-to-use aqueous or buffer-based preparations eliminate compounding steps in research laboratories, reducing contamination risk and labor overhead. Solutions gain share fastest among academic core facilities and CROs prioritizing workflow efficiency over per-gram economics.
- Capsules:Pre-measured oral dosage forms target nutraceutical and dietary supplement channels with standardized potency claims and convenience positioning.
- Tablets:Compressed solid dosage formats suit high-volume consumer wellness applications with extended shelf-life requirements and portable consumption patterns.
Powder leads on scale; solutions lead on momentum.
Application:
End-use maturity and certification intensity create tiered margin structures that reshape supplier portfolio priorities.
- Pharmaceuticals:USP and EP monograph-compliant grades for active pharmaceutical ingredient synthesis command premium positioning through 18-24 month qualification timelines. Peptide therapeutic developers in North America and Europe consolidate procurement toward single-source relationships with pharmacopeial certification.
- Nutraceuticals:Mature demand segment with stable margin pools and lower regulatory barriers, serving wellness brands with formulation flexibility rather than batch documentation intensity.
- Dietary Supplements:Consumer-facing finished products with label claim verification requirements under FDA and FSSAI jurisdiction, emphasizing cGMP compliance over synthesis-grade purity.
- Cosmetics:Skin-conditioning and humectant applications in topical formulations, where INCI listing and safety dossier completeness determine supplier access.
Pharmaceuticals concentrate value capture; nutraceuticals anchor volume baselines.
End User:
Procurement scale and technical sophistication fragment buying behavior across institutional and consumer channels.
- Manufacturers:Pharmaceutical and nutraceutical formulators with multi-kilogram annual requirements negotiate master service agreements bundling acetyl serine with protected amino acid portfolios.
- Research Institutions:Universities and CROs purchasing gram-to-kilogram quantities through distributor channels or direct e-commerce platforms, prioritizing certificate of analysis availability and lot traceability.
- Healthcare Providers:Hospital pharmacies and specialty clinics with compounded preparation needs, typically sourcing through GPO-negotiated pharmaceutical distribution networks.
- Consumers:Direct purchasers of finished dietary supplement products through retail and online channels, price-sensitive and brand-driven with minimal technical specification engagement.
Manufacturers dominate procurement scale; research institutions drive format innovation.
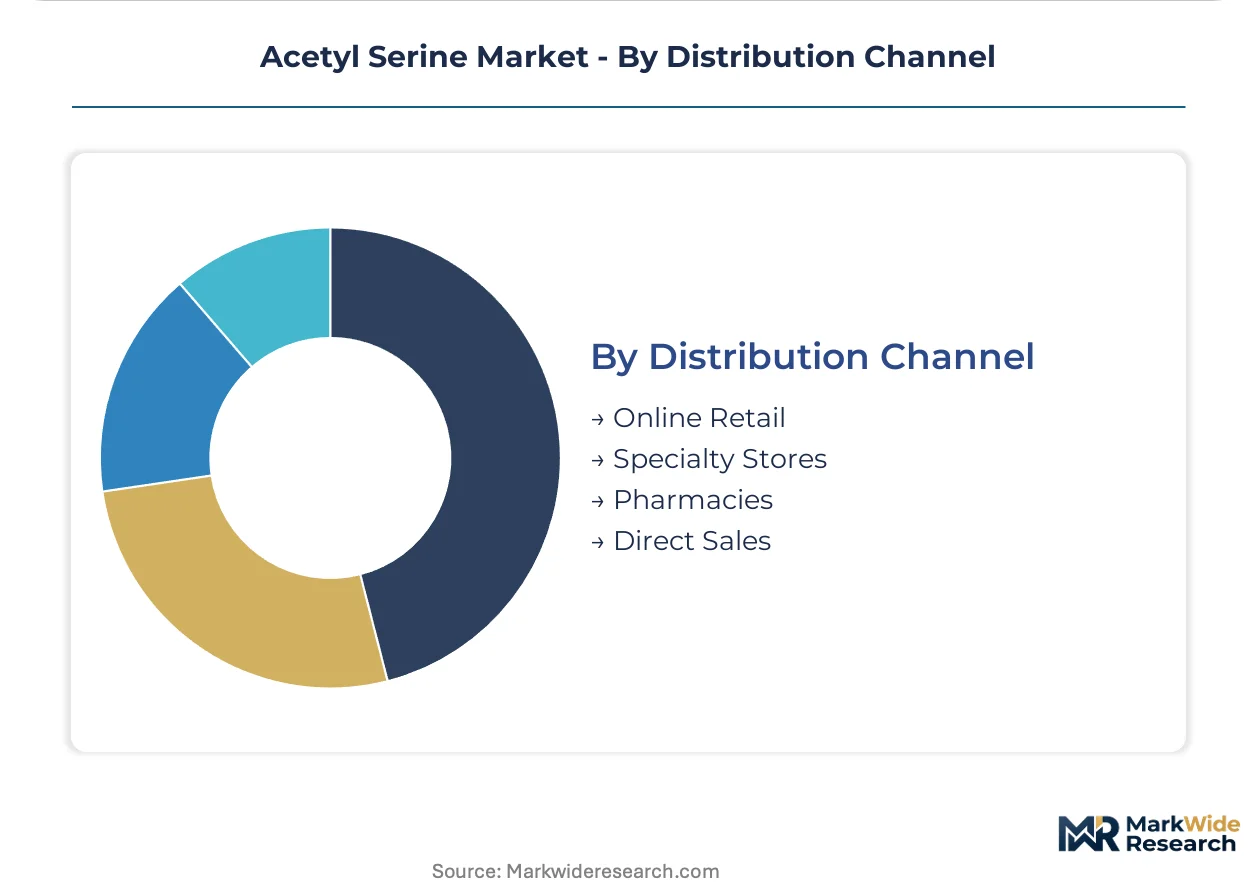
Distribution Channel:
Channel selection reflects buyer urgency, technical support requirements, and regulatory documentation needs.
- Direct Sales:Manufacturer-to-formulator relationships for pharmaceutical-grade material, enabling custom specification negotiation and dedicated regulatory affairs support for multi-jurisdiction dossier filing.
- Pharmacies:Brick-and-mortar and hospital-based dispensaries for finished dosage forms, operating under national pharmaceutical distribution licensing with cold chain and traceability requirements.
- Specialty Stores:Nutraceutical retailers and compounding pharmacy suppliers with trained staff capable of technical consultation on amino acid supplementation protocols.
- Online Retail:E-commerce platforms and direct-to-laboratory marketplaces bypassing traditional distributor markups for small-volume research reagent orders.
Direct sales secure pharmaceutical relationships; online retail expands research access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA enforcement of GB purity standards has accelerated supplier consolidation faster than the FDA's residual solvent guidelines in the United States, creating divergent qualification timelines across major pharmaceutical manufacturing hubs.
China
Jiangsu and Zhejiang provinces host contract manufacturing clusters serving GLP-1 agonist and oligonucleotide conjugate programs. The NMPA's tightened GB standards for amino acid pharmaceutical intermediates are filtering subscale producers from supply chains. Wuxi Jinghai Amino Acid Co., Ltd. anchors captive production for regional pharmaceutical intermediates in these coastal manufacturing zones.
United States
Peptide therapeutic developers in Greater Boston and San Francisco consolidate procurement toward single-source relationships with pharmacopeial certification. The FDA's current good manufacturing practice audits of foreign active ingredient facilities shape market access requirements. Thermo Fisher Scientific Inc. competes through distribution density in North American research channels.
Germany
Merck KGaA leverages its analytical standards portfolio to anchor quality assurance relationships with formulation clients across Baden-Württemberg and Bavaria. ECHA enforcement of updated REACH registration obligations and safety data sheet requirements redirects procurement toward registrants with full dossier compliance. Laboratory chemical distributors in Germany consolidate supplier panels to reduce downstream compliance liability.
India
The PLI scheme incentives for active pharmaceutical ingredient manufacturing are drawing acetyl serine demand toward Maharashtra and Gujarat contract development clusters. CDSCO filing requirements for pharmaceutical-grade amino acids create parallel qualification pathways to FDA and EMA standards. Indian CDMOs penetrate peptide synthesis supply chains as Western formulators diversify sourcing beyond Chinese suppliers.
Japan
Fermentation-derived L-serine supply concentrates among Japanese producers, exposing formulators to glycerol and glucose input cost swings. METI industrial policy supports domestic amino acid manufacturing capacity for pharmaceutical applications. PMDA pharmacopeial monograph alignment with USP and EP standards enables integrated qualification for export-oriented peptide drug developers.
Acetyl Serine Market Competitive Environment
Chinese producers anchor one tier; German and American specialists hold certification-driven positions in pharmaceutical-grade supply. The vendor base fragments across fermentation-derived feedstock controllers, acetylation process specialists, and distribution-anchored reagent suppliers. Three archetypes dominate: captive amino acid manufacturers with backward integration into L-serine fermentation, analytical standards houses with regulatory affairs depth, and research channel distributors with e-commerce density. Competitive moves concentrate on multi-year supply contract consolidation and enzymatic acetylation technology licensing.
Within the certification-driven tier, Merck KGaA and Thermo Fisher Scientific Inc. exemplify analytical standards houses leveraging regulatory affairs capacity for pharmaceutical-grade positioning. Wuxi Jinghai Amino Acid Co., Ltd. occupies a position among Chinese captive manufacturers with regional concentration in Jiangsu province. These three entities represent distinct strategic archetypes: the German multinational with pharmacopeial dossier depth, the American distributor with research channel penetration, and the Chinese specialist with intermediate-scale fermentation integration.
| Leading Market Players |
|---|
| Hanhong Scientific |
| Tianjin Pharmaceutical Co. Ltd. |
| Merck KGaA |
| WUHAN DONG KANG YUAN TECHNOLOGY CO., LTD. |
| Wuxi Jinghai Amino Acid Co., Ltd. |
| Guangzhou LES Biological Technology Co., Ltd. |
| Shanghai Bide Pharmaceutical Technology Co., Ltd. |
| Qingdao Samin Chemical Co., Ltd. |
| Thermo Fisher Scientific Inc. |
| Others |
Value Chain & Pricing Dynamics
Fermentation-derived L-serine feedstock costs cascade through acetyl serine pricing tiers, with glycerol and glucose input volatility from Chinese and Japanese producers compressing margins at the pharmaceutical-grade level while propagating cost advantages to certified suppliers with captive fermentation capacity.
Pricing Analysis
Capacity additions in Jiangsu and Zhejiang provinces are reshaping price floors for standard-grade material, though pharmaceutical-grade segments maintain premium-mid-economy pricing differentiation anchored by USP and EP certification timelines. Price differentiation rests on purity thresholds and pharmacopeial dossier completeness, with peptide drug developers least sensitive to per-kilogram costs and nutraceutical formulators most responsive to spot-market fluctuations. Cost compression in research-grade solutions is intensifying as direct-to-laboratory platforms bypass traditional distributor markups.
Supply Chain Analysis
Refurbishment flows for fermentation equipment and solvent recovery systems extend asset utilization among Chinese acetylation specialists, reducing capital intensity for mid-scale entrants. Supply concentrates in China, Japan, and India, with L-serine fermentation capacity anchoring upstream control and acetic anhydride or enzymatic acetyltransferase processes feeding downstream purification. Single-source vulnerability runs through fermentation-derived amino acid supply, particularly where METI industrial policy in Japan and NMPA GB standards in China gate export qualification. Distribution runs through direct manufacturer-to-formulator relationships for pharmaceutical grades and e-commerce platforms for research reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acetyl serine functions as a regulatory compounder where NMPA's tightened GB purity standards for amino acid pharmaceutical intermediates are accelerating supplier consolidation and redirecting procurement toward certified incumbents.
For Market Incumbents: Anchor pharmacopeial certification depth against enzymatic acetylation technology licensing from emerging biocatalysis specialists. Defensive consolidation moves center on backward integration into L-serine fermentation capacity in Jiangsu province and multi-year supply contract lock-in with GLP-1 agonist developers. Certification investment in simultaneous NMPA, FDA, and EMA dossier maintenance counters regulatory affairs capacity constraints that strain mid-scale competitors.
For New Entrants and Emerging Players: Continuous flow microreactor technology with in-line PAT analytics offers entry into research-grade solutions where workflow efficiency commands premium positioning. White-space targets concentrate on Maharashtra and Gujarat CDMO clusters drawing demand under India's PLI scheme, plus direct-to-laboratory e-commerce channels bypassing incumbent distributor networks. Go-to-market execution prioritizes gram-scale reagent partnerships with academic core facilities over bulk intermediate competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory affairs specialization intersects with fermentation capacity scarcity, favoring acquisition targets with dual NMPA and FDA qualification track records. Long-term viability frames around enzymatic process substitution displacing chemical acetylation and continuous manufacturing adoption compressing batch release cycles. Monitor pharmacopeial monograph revision timelines across USP, EP, and PMDA as early signals of qualification barrier shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Acetylation Technology Licensing | Biocatalytic processes reduce residual solvent burdens and simplify FDA pre-approval inspections. |
| Backward Integration into L-Serine Fermentation | Captive amino acid supply insulates against glycerol and glucose input cost swings from Japanese producers. |
| Continuous Flow Manufacturing Scale-Up | Microreactor integration with PAT analytics enables real-time release testing for pharmaceutical-grade output. |
| Multi-Jurisdiction Pharmacopeial Dossier Filing | Simultaneous NMPA, FDA, and EMA qualification secures access to peptide therapeutic developer procurement. |
| Direct-to-Laboratory E-Channel Expansion | Gram-scale research reagent platforms bypass traditional distributor markups in North American academic markets. |
Study Parameters
Bottom-up peptide therapeutic pipeline modeling reconciled against top-down amino acid intermediate production tracking forms the analytical core, combining primary interviews with regulatory affairs leads at contract manufacturers, procurement directors at peptide drug developers, and plant managers at fermentation facilities with secondary validation through NMPA GB standard filings, FDA cGMP audit records, and ECHA REACH registration databases.
Historical trendline analysis across pharmaceutical synthesis, nutraceutical formulation, and research reagent consumption established baseline growth patterns, with segmentation modeling across specification grade, physical format, and end-use application informing volume and value projections over the analysis window. CAGRs derive from fitted growth curves adjusted for enzymatic process substitution rates and NMPA enforcement intensity, with peptide drug pipeline expansion and CDMO geographic diversification as key forecast inputs.
The model holds under stable pharmacopeial monograph alignment across USP, EP, and PMDA standards; deviation in NMPA GB standard revision timing or L-serine feedstock supply disruption would shift supplier qualification timelines and pricing tier boundaries. Practitioners should monitor enzymatic acetylation technology licensing activity and continuous manufacturing equipment deployment rates for early signals of process economics inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Chromatography Silica Resins Market
Specialty Compounds
Global Customized Premixes Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Silicone Masterbatches Market
Specialty Compounds
North America Lithium Compound Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Conductive Plastic Compounds Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Superacids Market