
 Uninhibited Transformer Oil Market | 2026-2036
Uninhibited Transformer Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Uninhibited Transformer Oil Market Intelligence
Performance specification for high-voltage applications is decoupling the market from the price-sensitive commodity segment for standard distribution transformers. Nynas AB specializes in high-purity naphthenic oils for demanding electrical insulation needs. In contrast, major integrated oil companies like Shell plc and PetroChina Company Limited leverage their vast refining scale to compete in the high-volume mineral oil segments. This creates a clear divide in product strategy and target applications.
Uninhibited transformer oil is a purified mineral or synthetic fluid used as a dielectric coolant in electrical transformers. It is characterized by the absence of antioxidant additives, relying on its inherent chemical stability and high refinement level for performance. Mineral oil-based products dominate the power transformers application due to their proven performance and cost-effectiveness. However, natural ester fluids represent the fastest-growing product type, gaining share in distribution transformers due to their high fire point and biodegradability.
Global product specifications are governed by standards such as the IEC 60296 and ASTM D3487, which define performance criteria for mineral insulating oils. In China, compliance with national GB standards is mandatory for market access, influencing formulation and testing protocols. Key decisions for asset managers revolve around balancing the initial cost of the fluid against the long-term reliability and maintenance requirements of their transformer fleet.
Market Dynamics
The central dynamic in the uninhibited transformer oil market is the bifurcation driven by performance requirements. Grid modernization and high-voltage applications demand premium, specialized fluids, separating this segment from the price-driven, high-volume market for standard distribution transformers.
Growth Catalysts
- Grid Infrastructure Expansion:Major investments in China's power transmission and distribution networks, aimed at enhancing capacity and reliability, directly increase the consumption of transformer oil for new and upgraded installations.
- International Standards Adherence:The mandatory application of standards like IEC 60296 for mineral insulating oils forces utilities to procure compliant fluids, sustaining demand for high-purity, refined products that meet strict dielectric and thermal criteria.
- Renewable Energy Integration:The connection of large-scale solar and wind farms to national grids necessitates new transformers and substations, creating consistent demand for dielectric fluids capable of handling variable loads.
Market Restraints
- Substitution by Alternative Fluids:The rapid adoption of natural ester fluids, prized for their high fire safety and biodegradability, presents a significant substitution threat, particularly in distribution transformers located in sensitive areas.
- Crude Oil Price Volatility:As the primary feedstock for mineral-based transformer oils, fluctuations in crude oil prices directly impact production costs, creating price instability and margin pressure for manufacturers.
- Regulatory Compliance Complexity:Manufacturers face the challenge of meeting a diverse array of international and national standards, such as IEC, ASTM, and China's GB standards, which increases testing costs and complicates global supply chains.
Strategic Opportunities
- High-Performance Synthetic Esters:There is a growing opportunity to develop and market advanced synthetic ester fluids for niche, high-stress applications like traction transformers in railways or offshore wind turbines where performance outweighs cost.
- Emerging Market Grid Development:Electrification projects and grid improvements in developing regions, particularly in Southeast Asia and Africa, offer new geographic markets for uninhibited transformer oils as their power infrastructure expands.
- Fluid Lifecycle Management Services:Offering services for oil testing, reclamation, and end-of-life management provides a new revenue stream and deepens relationships with utility customers focused on asset longevity.
Industry Challenges
- Maintaining Fluid Purity:Preventing moisture and particulate contamination throughout the supply chain, from refinery to the transformer tank, is a persistent operational challenge that requires specialized logistics and handling protocols. *Management of Aging Transformer Fleets: Asset managers face the technical challenge of servicing and topping up older transformers, which may contain degraded oil, without compromising the performance of the new fluid or the equipment itself.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uninhibited Transformer Oil Market |
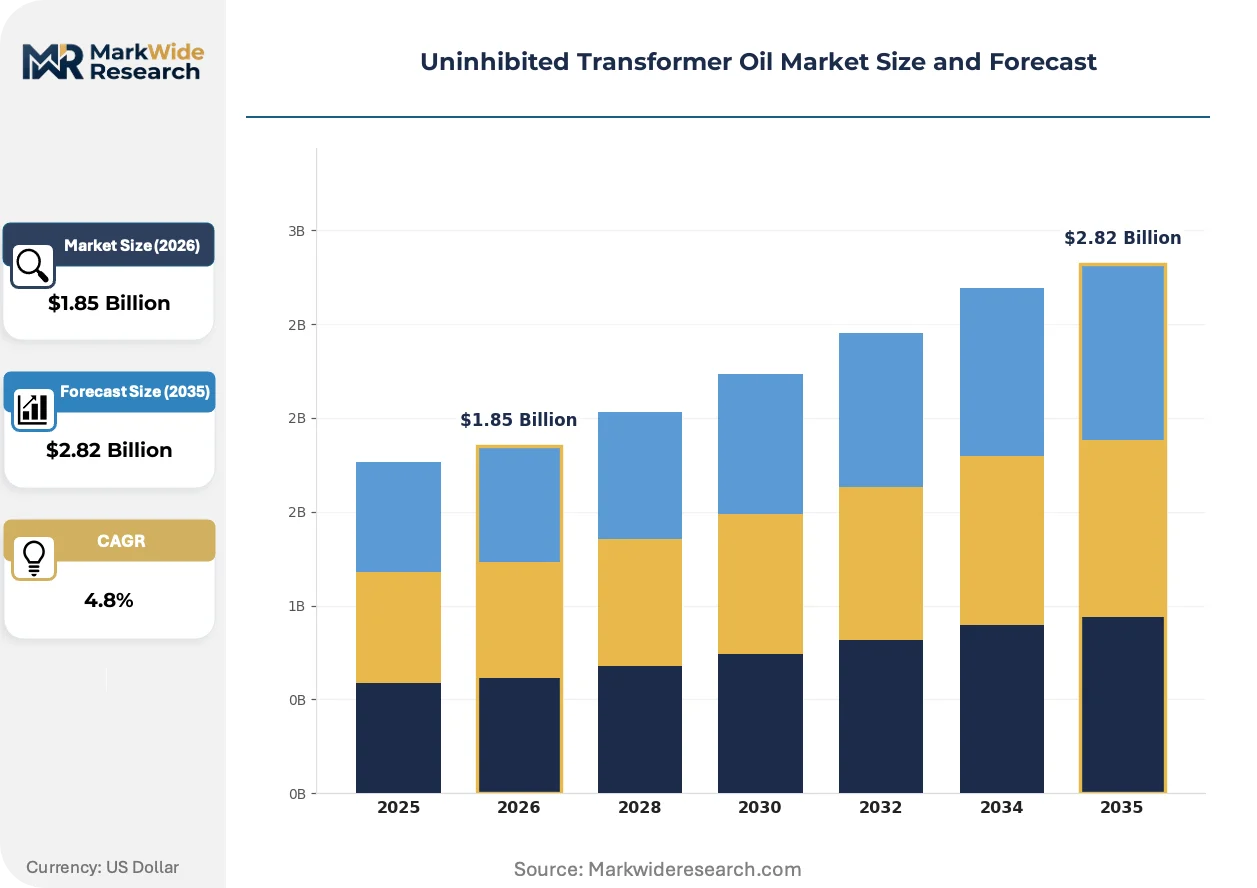
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Natural Ester, Silicone Fluid, Hydrocarbon Oil Application: Power Transformers, Distribution Transformers, Instrument Transformers, Reactors, Switchgear Equipment End User: Electric Utilities, Power Generation Plants, Renewable Energy Facilities, Industrial Manufacturing, Electrical Contractors Packaging Type: Drums, Barrels, Totes, Cylinders, Bulk Tankers |
| Companies Covered | PetroChina Company Limited, Cargill Incorporated, Nynas AB, Chevron Corporation, APAR Industries Limited, Shell plc, Ergon Inc., Exxon Mobil Corporation, Sinopec Lubricant Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uninhibited Transformer Oil Market Strategic Shifts & Innovations
Performance differentiation and sustainability are the primary forces guiding innovation. The market is shifting from a commodity focus towards specialized formulations that address specific operational demands like fire safety, environmental impact, and extreme temperature stability.
Natural ester fluids are a key product evolution, serving as a biodegradable and high-fire-point dielectric coolant. Utilities and industrial clients are adopting these fluids for distribution transformers in dense urban and environmentally sensitive locations. The demand for these high-performance, safer fluids is consolidating the market's focus on application-specific formulations over general-purpose mineral oils.
Harmonization of performance standards is influencing product development globally. Stricter criteria within norms like IEC 60296 for thermal stability and gassing tendency compel refiners to enhance their purification and processing capabilities. This affects all producers, particularly smaller regional players who must invest significantly in quality control and testing to retain access to regulated markets.
Asset managers are increasingly adopting a total cost of ownership (TCO) model for fluid procurement. This behavioral shift de-emphasizes the initial purchase price in favor of long-term fluid stability, reduced maintenance needs, and the potential for extending transformer operational life. This trend is most prominent among large electric utilities in North America and Europe managing aging and extensive grid assets.
Uninhibited Transformer Oil Market Segmentation
The uninhibited transformer oil market segments across diverse product compositions, applications, end-user types, and packaging formats. Understanding these distinct segments is critical for manufacturers to tailor product specifications and for utilities to optimize procurement strategies based on operational demands and environmental considerations.
Product Type:
What differentiates buyers in this category is the fundamental chemical composition of the dielectric fluid and its inherent performance characteristics, such as flash point, biodegradability, and thermal stability.
- Mineral Oil:This product type, derived from petroleum, offers proven dielectric strength and thermal performance for power transformers. Its cost-effectiveness and long track record ensure continued high demand in established grid infrastructures in regions like North America and Europe.
- Natural Ester:Sourced from vegetable oils, natural ester fluids provide high fire safety and biodegradability, making them suitable for distribution transformers in urban and environmentally sensitive areas. Utilities in countries like Germany and Japan increasingly adopt these fluids for enhanced safety.
- Synthetic Oil:Engineered for specific performance needs, synthetic oils deliver superior thermal stability and oxidation resistance in demanding applications.
- Silicone Fluid:Characterized by excellent high-temperature performance and fire resistance, silicone fluid finds niche applications where extreme thermal conditions are present.
- Hydrocarbon Oil:These highly refined mineral oils offer enhanced purity and stability for specialized electrical insulation requirements.
Mineral Oil leads volumes today; Natural Ester is gaining share fastest.
Application:
Application-specific demands dictate the choice of transformer oil, influencing fluid properties like dielectric strength and thermal management for optimal equipment function and longevity.
- Power Transformers:These large, critical assets in transmission networks require substantial volumes of uninhibited transformer oil for insulation and cooling. Grid modernization projects in China and India drive significant demand for these high-voltage applications.
- Distribution Transformers:Located closer to end-users, these transformers increasingly utilize fluids with enhanced fire safety and environmental profiles, particularly in densely populated urban centers. The adoption of natural esters is notable in this segment.
- Instrument Transformers:These devices require highly stable dielectric fluids to ensure accurate measurement and protection in substations.
- Reactors:Used for voltage regulation and fault current limitation, reactors depend on high-quality insulating fluids for reliable operation.
- Switchgear Equipment:Transformer oil provides insulation and arc quenching capabilities within various types of switchgear components.
Power Transformers represent the largest application volume, while Distribution Transformers are seeing significant fluid innovation.
End User:
Customer operational scale and asset management strategies differentiate end-user procurement of uninhibited transformer oil, impacting volume requirements and service needs.
- Electric Utilities:These entities operate extensive transmission and distribution networks, driving the largest volume demand for transformer oils for new installations and maintenance. Major utilities in countries like the United States and France prioritize fluid reliability and long-term performance.
- Renewable Energy Facilities:Solar and wind farms require specialized transformers and oils to handle intermittent power generation and grid integration. The expansion of these facilities in Australia and Brazil creates a new growth trajectory for fluids.
- Power Generation Plants:Conventional power plants use transformer oil for their step-up transformers connecting to the grid.
- Industrial Manufacturing:Large industrial complexes with their own substations consume transformer oil for internal power distribution.
- Electrical Contractors:These firms procure transformer oil for installation, repair, and maintenance projects across various client types.
Electric Utilities are the largest consumer segment, with Renewable Energy Facilities showing strong expansion.
Packaging Type:
Logistical efficiency and volume requirements primarily determine the preferred packaging type for transformer oil, influencing handling costs and delivery methods.
- Bulk Tankers:This packaging method facilitates the most cost-effective transportation and delivery of large volumes of transformer oil directly to major substations or storage facilities. Large utilities in Russia and Canada frequently utilize bulk tanker deliveries.
- Drums:Drums provide a versatile and manageable packaging solution for smaller volumes required for maintenance, topping-up, or smaller-scale installations. Many regional distributors and contractors rely on drums for their operational flexibility.
- Barrels:Similar to drums, barrels offer a standardized container size for medium-volume deliveries to diverse customer sites.
- Totes:Intermediate bulk containers (IBCs), or totes, offer a reusable option for transporting larger quantities than drums but less than bulk tankers.
- Cylinders:Specialized gases or very small volumes of fluids for niche applications may be transported in cylinders, though less common for bulk transformer oil.
Bulk Tankers facilitate large-scale deliveries, while Drums serve widespread maintenance and smaller project needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A robust talent pool in chemical engineering and power systems design underpins the global uninhibited transformer oil market. This specialized workforce drives innovation in fluid formulations and supports the complex grid infrastructure. Strategic investments in grid modernization and renewable energy integration further stimulate regional demand.
China
China's rapid grid infrastructure expansion and electrification projects create substantial demand for transformer oil. The mandatory compliance with national GB standards influences product formulations and testing protocols for market access. Major power transmission and distribution network developments in the Yangtze River Delta region consistently drive high-volume consumption.
United States
The United States market is characterized by significant investments in aging grid infrastructure upgrades and renewable energy integration. Federal Energy Regulatory Commission (FERC) guidelines encourage reliable and efficient power delivery, impacting fluid procurement decisions. The Texas energy corridor, with its extensive utility operations, represents a key concentration of demand for high-performance dielectric fluids.
Germany
Germany exhibits strong demand for uninhibited transformer oil, particularly for advanced distribution transformers and renewable energy connections. The EU Green Deal and stringent environmental regulations promote the adoption of biodegradable natural ester fluids. Industrial clusters in Bavaria, known for their advanced manufacturing and engineering, require specialized insulating oils for their sophisticated electrical systems.
India
India's ongoing electrification initiatives and industrial growth are significant demand drivers for transformer oil. The Bureau of Indian Standards (BIS) mandates specific quality and performance criteria for insulating oils used in the national grid. Industrial hubs in Maharashtra, with their expanding power generation and distribution networks, consistently procure large volumes of these essential fluids.
Uninhibited Transformer Oil Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in the uninhibited transformer oil sector. The market shows a tiered structure, with integrated oil majors dominating high-volume mineral oil segments. Specialized chemical companies focus on premium synthetic and natural ester formulations, catering to niche performance requirements. Key competitive moves include strategic partnerships for supply chain resilience and continuous portfolio diversification into advanced fluid types.
At the scale-driven end of the market, integrated oil companies like PetroChina Company Limited and Shell plc leverage extensive refining capabilities. These global entities command significant market presence in the high-volume mineral oil segment, serving broad industrial and utility needs across continents. Their vast supply chains and established distribution networks allow them to compete effectively on cost and accessibility for standard applications. Nynas AB, conversely, represents a specialized player, focusing on high-purity naphthenic oils designed for demanding electrical insulation applications in critical infrastructure. This company targets performance-sensitive segments where fluid specifications are paramount.
| Leading Market Players |
|---|
| PetroChina Company Limited |
| Cargill Incorporated |
| Nynas AB |
| Chevron Corporation |
| APAR Industries Limited |
| Shell plc |
| Ergon Inc. |
| Exxon Mobil Corporation |
| Sinopec Lubricant Company |
| Others |
Cost & Logistics Intelligence
Performance specifications for high-voltage applications create a distinct market tier, decoupling pricing and supply chains from the price-sensitive commodity segment for standard distribution transformers. This bifurcation drives specialized sourcing and cost structures across the uninhibited transformer oil market.
Pricing Analysis
Bundled after-sales services often influence procurement decisions for uninhibited transformer oil, moving beyond transactional per-unit pricing. The market exhibits premium-mid-economy pricing differentiation, with high-performance fluids for critical applications commanding higher rates. Quality grade and adherence to IEC 60296 or GB standards are key differentiation drivers. Crude oil price volatility creates cost compression, particularly in mineral oil segments, though electric utilities prioritize reliability over initial cost.
Supply Chain Analysis
Logistics costs for bulk tanker deliveries to major substations represent a significant supply chain component for uninhibited transformer oil. Supply of mineral oil primarily centers on countries with large refining capacities, including China, the United States, and Europe, where major integrated oil companies operate. The supply chain relies on crude oil as a primary feedstock, creating commodity price volatility risk. Distribution runs through a dual model of bulk tankers for utilities and drums for maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The uninhibited transformer oil market exhibits characteristics of a stable compounder, driven by continuous demand from electric utilities for essential grid modernization projects. This steady growth trajectory reflects the critical role of dielectric fluids in maintaining and expanding power infrastructure.
For Market Incumbents: Deepen relationships with major electric utilities by offering comprehensive fluid lifecycle management services, including oil testing and reclamation. Incumbents should invest in advanced natural ester fluid formulations to counter substitution threats from alternative dielectric coolants. Securing long-term supply contracts for high-purity naphthenic crude oil mitigates raw material price volatility.
For New Entrants and Emerging Players: Digital sales platforms offer a direct channel for new entrants to reach smaller utilities and electrical contractors, bypassing established distribution networks. Focus on high-performance synthetic ester fluids for niche, high-stress applications like offshore wind turbines presents a white-space opportunity. Targeting distribution transformers in emerging markets, particularly with natural ester fluids for enhanced fire safety, offers significant penetration potential.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized performance requirements intersect with fragmented regional supply chains for uninhibited transformer oil. The market offers long-term viability as a critical component of global power infrastructure, driven by ongoing grid modernization. Investors should target specialized chemical companies with strong R&D in synthetic or natural ester fluids, or those with robust fluid lifecycle management service offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Natural Ester Production | Meets growing demand for high fire-point, biodegradable fluids in distribution transformers. |
| Acquire Fluid Lifecycle Services Provider | Deepens customer relationships and creates new revenue streams for asset managers. |
| Invest in High-Purity Naphthenic Refining | Supports demand for specialized oils in high-voltage and critical applications. |
| Secure Long-Term Crude Oil Supply Contracts | Mitigates raw material price volatility for mineral oil producers like Shell plc. |
| Develop Synthetic Fluids for Extreme Conditions | Addresses niche applications requiring superior thermal stability and oxidation resistance. |
Research Approach
Bottom-up electric utility end-use modeling reconciled against top-down refinery output tracking forms the analytical core for this uninhibited transformer oil market study. Primary interviews with electric utility asset managers, refinery operations directors, R&D chemists, and electrical contractors provided qualitative insights. Secondary validation drew from IEC standards documents, national energy agency reports, and trade association publications. This dual approach ensured robust data triangulation.
An input-output matrix underpins the quantitative forecast model, projecting market trajectory across the analysis window. Segmentation dimensions modeled include product type, application, end user, packaging type, and regional compliance. Compound annual growth rates were derived through regression analysis on historical data. Grid modernization investment and renewable energy capacity additions serve as key forecast inputs.
Crude oil price volatility, regulatory shifts favoring alternative fluids, and unforeseen grid infrastructure delays are the dominant revision risks for these forecasts. The projections reflect assumptions documented at the time of analysis, acknowledging inherent market uncertainties. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Green Power Transformers Market
Transformers
China Transformer Market
Transformers
Latin America Transformer Market
Transformers
Asia-Pacific Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Rectifier Transformers Market
Transformers
Neon Transformer Market
Transformers
Electric Vehicle Charging Station Transformer Market
Transformers
Single Phase Power Transformer Market
Transformers
Rail Traction Transformers Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
Smart Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
Box Transformer Substation Market
Transformers
Cast Resin Transformers Market
Transformers
Current Transformer Market