
 Electric Vehicle Charging Station Transformer Market | 2026-2036
Electric Vehicle Charging Station Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Charging Station Transformer Market Insights
Project finance and power-purchase agreement structures is fragmenting the competitive landscape for charging infrastructure assets. Siemens leverages its grid automation portfolio to anchor utility-scale transformer deployments across European corridors. ABB sustains technology leadership in liquid-cooled transformer designs for ultra-fast charging hubs. Schneider Electric competes through integrated microgrid solutions that bundle power conversion with energy management software.
An electric vehicle charging station transformer is a static electromagnetic device that converts grid-level voltage to the specific input requirements of EV supply equipment, typically operating at frequencies of 50-60 Hz with insulation classes rated for continuous outdoor duty. Its primary purpose is to enable safe, efficient power delivery while isolating charging loads from distribution network disturbances. Step-down configurations dominate current installations given the voltage reduction from medium-voltage distribution to Level 2 and DC fast charging inputs. DC fast charging and ultra-fast charging segments are capturing disproportionate investment as highway corridor electrification demands higher power density transformers with advanced thermal management. Ground-mounted installations remain the default for public charging depots, though wall-mounted units are gaining traction in constrained urban footprints where real estate premiums reshape site design.
US utilities coordinate with NHTSA corridor designations and EPA emissions targets to prioritize transformer capacity additions along designated alternative fuel corridors. IEC and IEEE standards govern insulation coordination, short-circuit withstand, and efficiency minimums that determine product qualification for grid interconnection across multiple jurisdictions. Stakeholders must weigh stranded asset risk against modular upgrade paths as charging power ratings escalate beyond current transformer specifications.
Market Dynamics
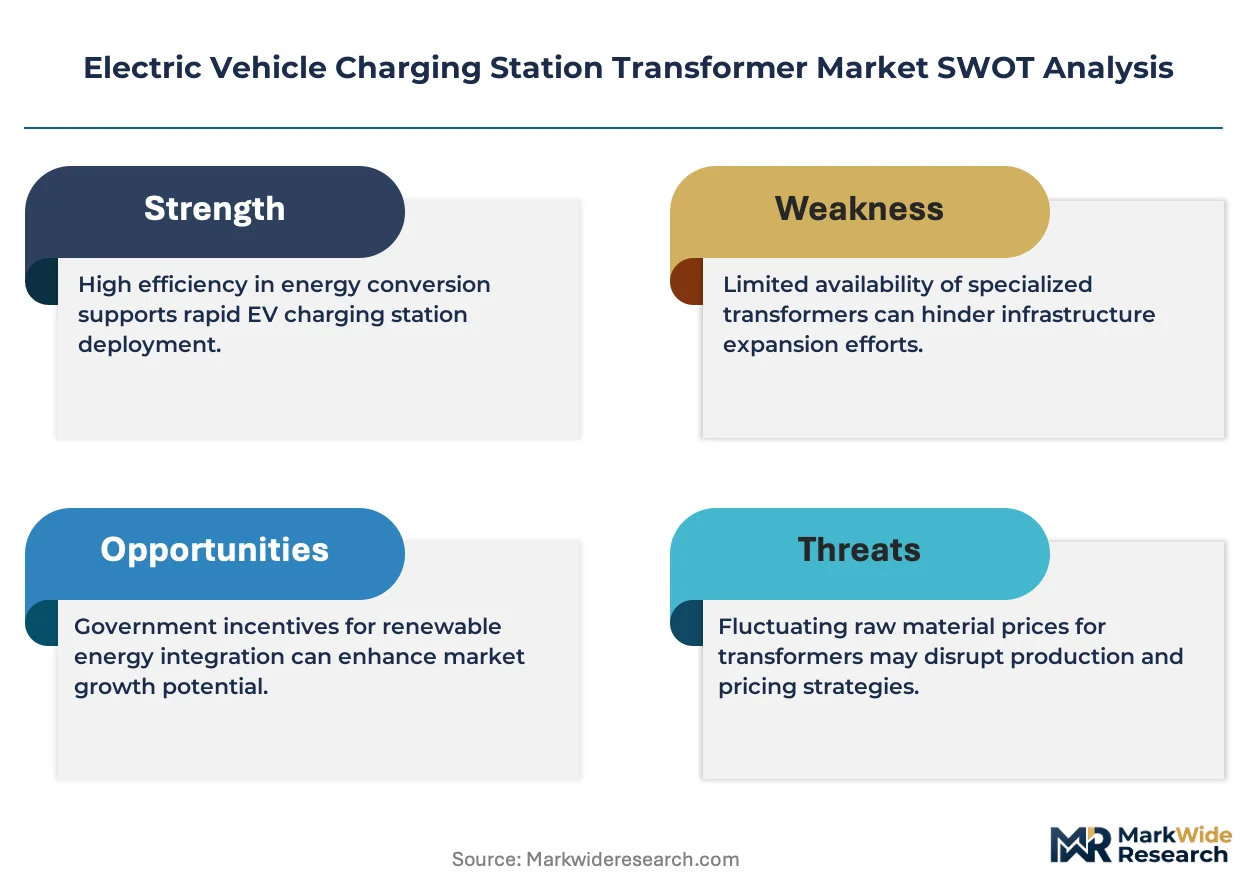
Power density escalation in highway corridor charging is forcing transformer specifications upward faster than utility procurement cycles can absorb, creating a structural mismatch between equipment lead times and deployment deadlines.
Growth Catalysts
- NHTSA corridor electrification mandates:The Federal Highway Administration coordinates with state DOTs to designate alternative fuel corridors, triggering utility transformer capacity reservations along interstate highway networks.
- Fleet electrification programs:Commercial vehicle operators in California, Texas, and New York are consolidating charging depots into high-capacity hubs requiring dedicated substation infrastructure.
- Liquid-cooled thermal management:Advanced cooling systems enable continuous operation at 350kW+ output levels, supporting ultra-fast charging without thermal derating.
Market Restraints
- Grain-oriented electrical steel supply concentration:Transformer core material production clusters in China and Japan, exposing procurement to trade policy volatility and shipping bottlenecks.
- Utility interconnection queue delays:Distribution system impact studies and grid upgrade sequencing extend project timelines 18-36 months beyond equipment delivery.
- Copper and aluminum price volatility:Winding conductor costs constitute 25-35% of transformer bill-of-materials, compressing margins when commodity markets spike.
Strategic Opportunities
- Modular transformer architectures:Scalable designs allow capacity additions without full replacement, protecting against stranded asset risk as charging power ratings climb.
- Integrated microgrid bundling:Schneider Electric and competitors combine power conversion with on-site solar and battery storage, capturing full-stack project value.
- Urban wall-mounted installations:Real estate constraints in Manhattan, London, and Tokyo are accelerating demand for compact, pad-mount alternatives in dense commercial districts.
Industry Challenges
- Medium-voltage technician scarcity:Utilities and contractors face acute shortages of lineworkers qualified for 15-35kV distribution equipment installation and maintenance.
- IEC-IEEE dual certification complexity:Manufacturers serving both European and North American markets must maintain parallel testing programs for insulation coordination and short-circuit withstand standards.
- Legacy grid integration friction:Aging distribution infrastructure in older metropolitan areas requires extensive upstream reinforcement before high-capacity charging loads can connect.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Charging Station Transformer Market |
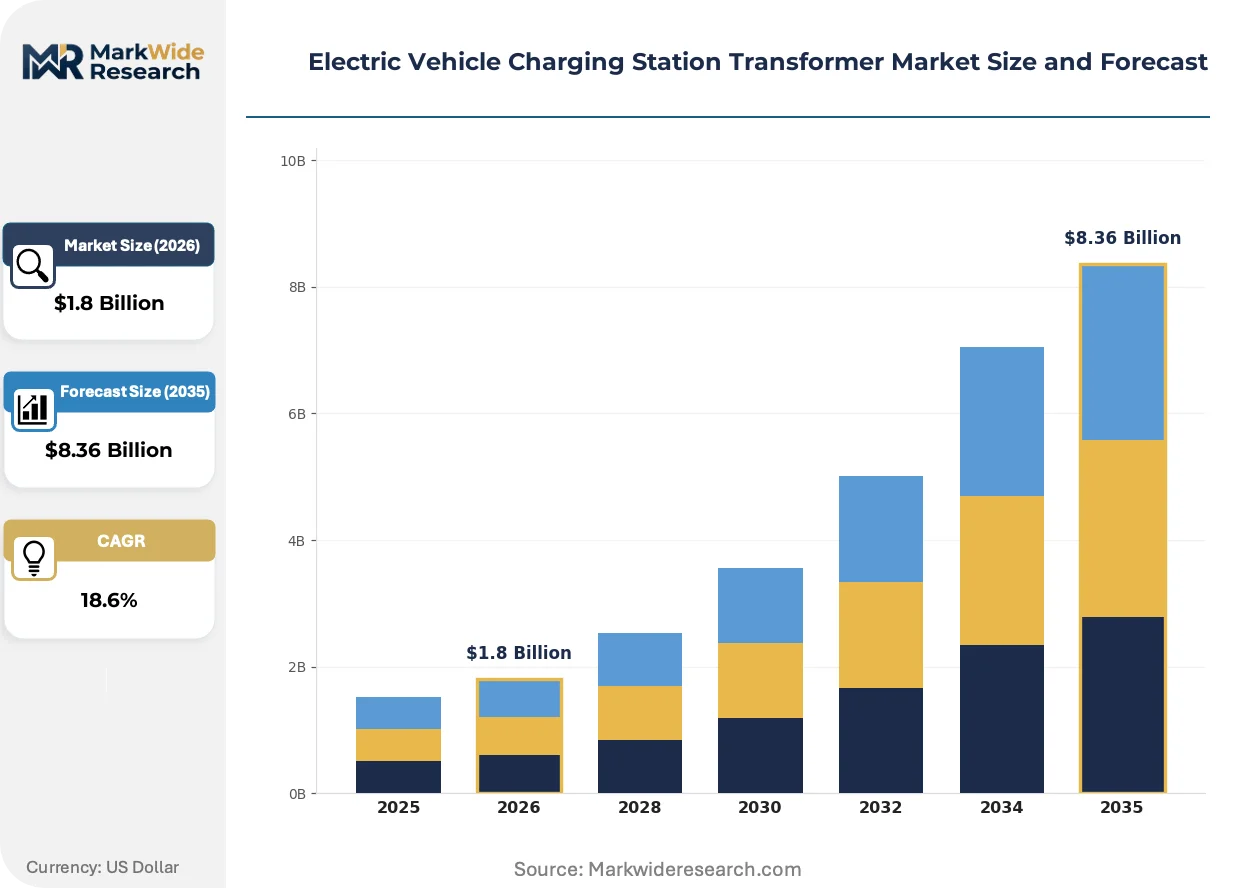
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transformer Type: Step-Up, Step-Down, Isolation, Multi-Tap Charging Speed: Level 1, Level 2, DC Fast Charging, Ultra-Fast Charging Mounting Type: Ground-Mounted, Wall-Mounted, Pole-Mounted, Mobile Power Rating: 10 kW, 22 kW, 50 kW, 150 kW |
| Companies Covered | Siemens, ABB, Schneider Electric, GE, Eaton, Legrand, Delta Electronics, Tritium, Robert Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Charging Station Transformer Market Trends and Innovations
Transformer engineering is pivoting from passive voltage conversion toward intelligent, thermally adaptive systems that synchronize with dynamic load management platforms. This evolution redefines how grid infrastructure interfaces with distributed charging assets.
Dry-type cast resin insulation is migrating from indoor substation applications to outdoor charging depot installations. Fleet operators in Germany and the Netherlands prefer these units for reduced fire risk and elimination of oil containment requirements. The technology is migrating from premium urban sites toward standard highway corridor deployments as manufacturing scale drives cost convergence with conventional oil-filled designs.
The EPA's tightened tailpipe standards for commercial vehicles are compressing compliance timelines for freight operators. This regulatory pressure accelerates charging infrastructure procurement ahead of vehicle fleet turnover, pulling transformer demand forward by 12-24 months. Heavy-duty corridor segments in California and the Pacific Northwest are responding with preemptive substation upgrades to secure grid capacity.
Charging network operators are consolidating procurement under long-term power-purchase agreements with utilities, bypassing traditional equipment ownership models. This financial structuring shifts transformer specification authority from site developers to utility engineering departments. The pattern is most visible in Texas and Florida, where independent system operators facilitate direct wholesale market participation for large charging loads.
Electric Vehicle Charging Station Transformer Market Segmentation
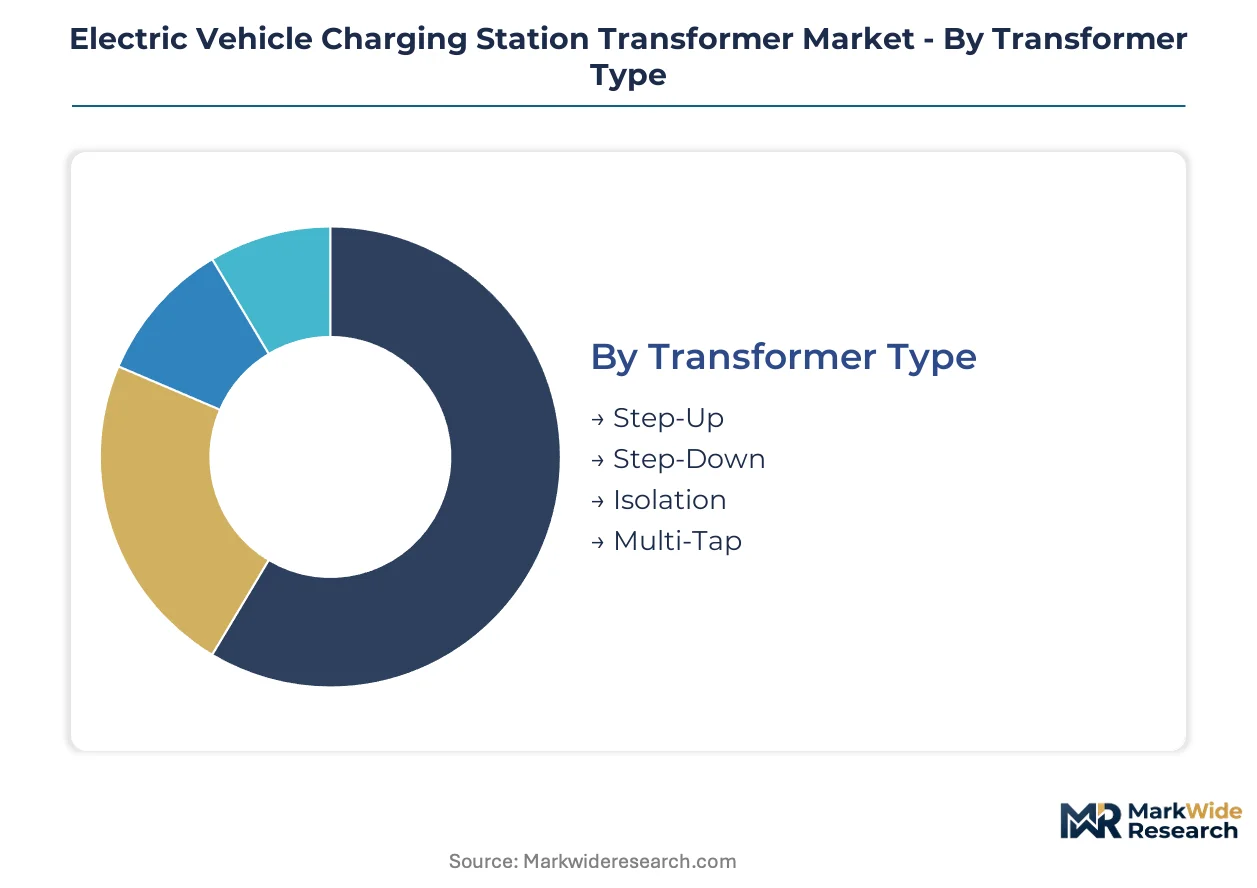
Transformer specifications diverge sharply across charging applications. Procurement cycles for highway corridor infrastructure run 18-24 months, while urban depot retrofits complete in 6-9 months. Understanding these velocity differences shapes inventory positioning and manufacturing allocation strategies.
Transformer Type:
Step-down configurations turn over fastest due to widespread Level 2 deployment, while multi-tap units face extended validation cycles for utility-scale corridor projects.
- Step-Up:Elevates voltage from low-voltage generation sources to medium-voltage distribution levels. Demand concentrates in solar-integrated charging depots across California and Texas, where on-site photovoltaic arrays feed directly into DC fast charging infrastructure.
- Step-Down:Reduces medium-voltage distribution inputs to the 208-480V range required by EV supply equipment. Fleet operators in Germany and the Netherlands specify these units for dedicated substations serving 50+ vehicle charging depots.
- Isolation:Provides galvanic separation between grid and load without voltage transformation. Critical for marine and mining applications where ground fault protection mandates electrical segregation.
- Multi-Tap:Delivers selectable output voltages through multiple winding ratios. Utility engineering departments in Texas and Florida specify these for corridor sites anticipating phased power upgrades.
Step-down dominates installed base. Multi-tap is where expansion concentrates.
Charging Speed:
Cost tier differentiation separates commodity transformer procurement from engineered thermal management systems.
- Level 1:Residential-grade 120V alternating current delivery through standard distribution transformers. Margins compress as utilities treat these as standard distribution equipment rather than specialized charging assets.
- Level 2:208-240V alternating current systems requiring dedicated 40-100A circuits. Workplace charging installations in Manhattan and London drive specification diversity due to constrained electrical room footprints.
- DC Fast Charging:Direct current delivery at 50-350kW through rectifier-integrated transformer stations. Highway corridor buildouts in California, Oregon, and Washington prioritize these units for 30-minute charge cycles.
- Ultra-Fast Charging:Liquid-cooled systems sustaining continuous 350kW+ output. ABB and Schneider Electric compete for specifications at megawatt-scale truck charging hubs along Interstate 5 and European TEN-T corridors.
Level 2 captures highest unit volumes. Ultra-fast charging commands the steepest expansion trajectory.
Mounting Type:
Application context determines structural requirements, with mobile units serving temporary construction sites and permanent installations anchoring revenue-grade infrastructure.
- Ground-Mounted:Pad-mounted enclosures housing oil-filled or dry-type units in outdoor environments. Default specification for public charging depots in suburban and highway locations across the United States.
- Wall-Mounted:Compact designs reducing footprint for indoor electrical rooms and constrained urban sites. Tokyo and London commercial districts accelerate adoption as real estate premiums reshape site design.
- Pole-Mounted:Overhead distribution transformers adapted for curbside charging integration. Municipal utilities in France and Spain deploy these for streetlight-conversion charging programs.
- Mobile:Trailer-mounted substations providing temporary capacity for events, construction, or emergency response. Mining and forestry operations in Canada and Australia specify these for remote workforce electrification.
Ground-mounted retains dominant share. Wall-mounted is gaining share fastest in dense commercial districts.
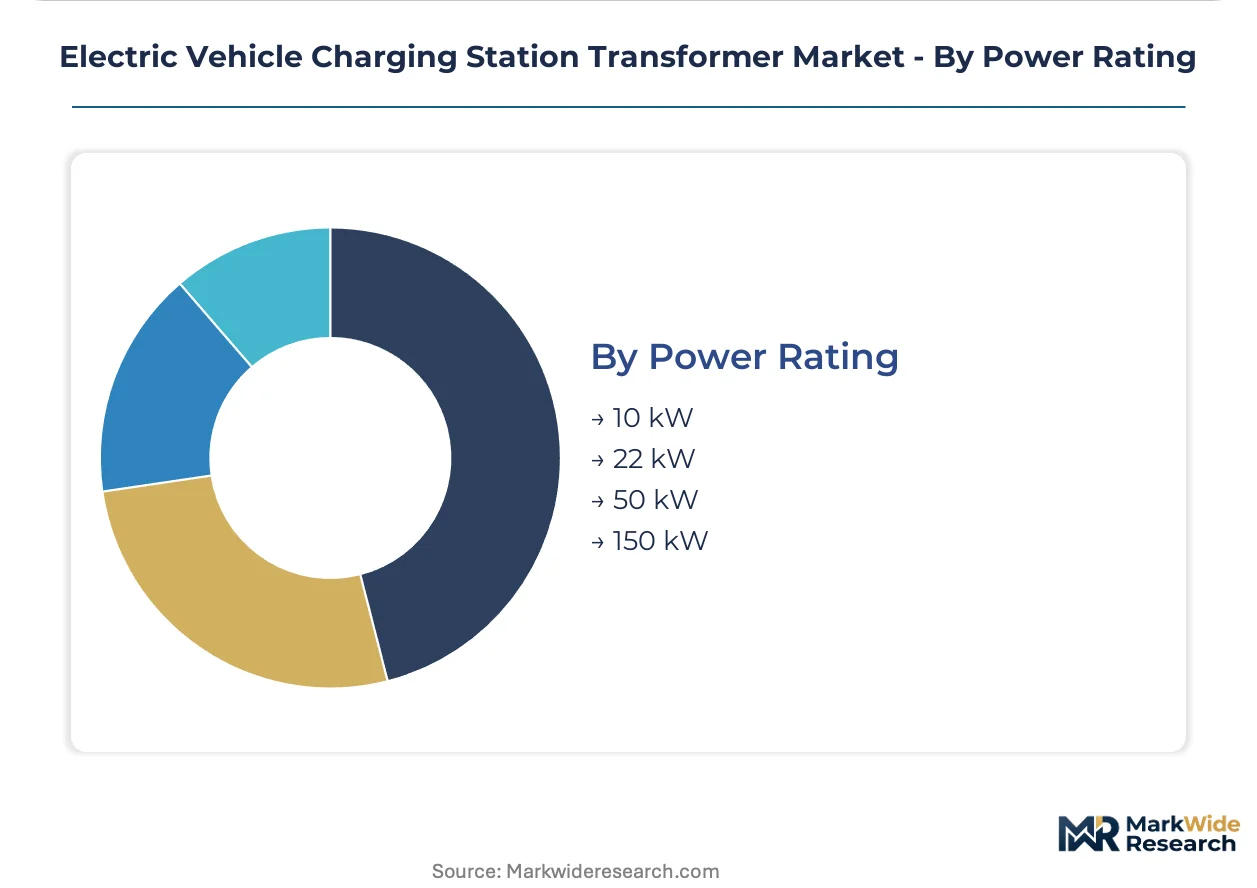
Power Rating:
Customer type segmentation separates residential single-family installations from fleet-scale commercial procurement with divergent specification authority.
- 10 kW:Single-residence or small multi-family building capacity. Standard distribution transformer sizing in European residential developments with underground parking integration.
- 22 kW:Commercial workplace and retail destination charging. German automotive manufacturers specify these for employee parking facilities at Stuttgart and Munich assembly plants.
- 50 kW:Entry-level DC fast charging for urban mobility hubs. Transit agencies in New York and Chicago deploy these for electric bus opportunity charging at terminal layover points.
- 150 kW:Highway corridor and fleet depot backbone capacity. California's electric truck corridor program mandates these minimums for alternative fuel corridor certification.
22 kW leads European installed base. 150 kW is where North American fleet electrification concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and highway corridor developers concentrate transformer procurement across four distinct national markets. Each geography presents unique regulatory timing and infrastructure buildout velocity.
United States
California's electric truck corridor program and Texas fleet depot electrification drive procurement volumes. NHTSA alternative fuel corridor designations trigger utility transformer capacity reservations along Interstate 5 and Interstate 10. The Pacific Northwest corridor from Seattle to Portland anchors ultra-fast charging hub development with preemptive substation upgrades.
Germany
Automotive manufacturer charging depots and TEN-T corridor electrification create dual demand streams. The EU Green Deal and national fleet electrification mandates compress compliance timelines for commercial vehicle operators. Stuttgart and Munich assembly plants specify dedicated substation infrastructure for employee and logistics fleet charging.
China
State Grid Corporation highway charging network expansion and urban fleet electrification programs scale transformer deployments. MIIT new energy vehicle mandates and GB standards for charging infrastructure govern equipment qualification. The Yangtze River Delta corridor from Shanghai to Nanjing concentrates ultra-fast charging hub construction with integrated grid automation.
Netherlands
Rotterdam port electrification and Amsterdam metropolitan charging networks prioritize dry-type transformer specifications. REACH compliance for insulation materials and national carbon reduction targets accelerate oil-free technology adoption. The Randstad urban corridor drives wall-mounted installation demand where real estate constraints reshape site design.
Japan
Tokyo commercial district charging retrofits and Osaka industrial fleet hubs split procurement between compact urban and ground-mounted highway specifications. METI carbon neutrality roadmaps and JIS standards for distribution equipment determine product qualification. The Kanto region's dense commercial districts accelerate wall-mounted transformer adoption for constrained electrical room footprints.
Electric Vehicle Charging Station Transformer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority. Utility engineering departments and charging network operators split specification influence, preventing any single vendor from dominating upstream transformer supply. Three archetypes dominate: diversified industrial conglomerates with grid automation portfolios, power equipment specialists with thermal management expertise, and integrated microgrid bundlers combining hardware with energy management software. Competitive moves center on modular architecture development and long-term power-purchase agreement structuring with utilities.
Within the diversified industrial tier, Siemens and ABB occupy positions anchored by legacy grid infrastructure relationships. Schneider Electric exemplifies the integrated solutions archetype through microgrid bundling strategies. These three entities represent distinct competitive vectors: Siemens leverages utility-scale deployment experience, ABB sustains technology positioning in liquid-cooled thermal management, and Schneider Electric competes through software-integrated energy management platforms.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| Schneider Electric |
| GE |
| Eaton |
| Legrand |
| Delta Electronics |
| Tritium |
| Robert Bosch |
| Others |
Pricing and Supply Chain Analysis
Shanghai's Yangtze River Delta manufacturing cluster concentrates grain-oriented electrical steel capacity, feeding transformer core production that shapes downstream pricing power for utilities and charging network operators across North America and Europe.
Pricing Analysis
Cost-plus contracts indexed to LME copper and aluminum benchmarks dominate procurement between utilities and transformer OEMs. Price differentiation rests on IEC versus IEEE dual certification tiers and liquid-cooled thermal management integration. Cost compression in standard step-down units is intensifying because fleet operators consolidate procurement under long-term power-purchase agreements. Municipal utilities exhibit highest price sensitivity due to rate-case scrutiny, while private charging network operators absorb premium pricing for modular upgrade paths.
Supply Chain Analysis
Contract manufacturing for transformer cores concentrates among Japanese and Chinese specialty steel producers with limited alternative sourcing. Winding conductor supply draws from Chilean copper cathode and Australian bauxite refining into aluminum rod. Single-source vulnerability in grain-oriented electrical steel exposes procurement to tariff escalation and shipping bottlenecks. Distribution runs through utility engineering departments and EPC contractors serving charging depot developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: NHTSA corridor designations and utility interconnection standards create switching costs that lock in incumbent transformer specifications across decade-long asset lifecycles.
For Market Incumbents: Entrench utility relationships through preemptive substation capacity reservations along designated alternative fuel corridors. Invest in backward integration into grain-oriented electrical steel sourcing to offset commodity volatility. Siemens and ABB already anchor this position; challengers must match utility-scale deployment credibility or cede highway corridor specifications.
For New Entrants and Emerging Players: Secondary metropolitan markets in Texas and Florida present underpenetrated demand where interconnection queue delays have stalled incumbent deployments. Target wall-mounted transformer specifications for Manhattan and Tokyo commercial retrofits where real estate constraints favor compact designs. Partner with solar integrators on step-up configurations for solar-integrated charging depots as a channel wedge.
For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure play because utility interconnection standards and NHTSA corridor mandates create durable demand visibility independent of EV sales velocity. Acquisition targets should display microgrid bundling capabilities or liquid-cooled thermal management IP. Monitor utility transformer procurement announcements along Interstate 5 and Interstate 10 as inflection signals for capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Transformer Architecture Development | Scalable designs protect against stranded asset risk as 350kW+ charging proliferates along highway corridors. |
| Long-term Power Purchase Agreement Structuring | Utility partnerships bypass traditional equipment ownership and shift specification authority to grid operators. |
| Liquid-cooled Thermal Management Investment | Continuous 350kW+ operation capability differentiates specifications at megawatt-scale truck charging hubs. |
| Microgrid Integration Bundling | Combined power conversion with solar and battery storage captures full-stack project value in fleet depots. |
| Dual IEC-IEEE Certification Maintenance | Parallel testing programs enable qualification across European and North American procurement channels. |
Research Methodology
Operator-level perspectives from utility planning officers, charging network procurement directors, EPC contractors, and transformer OEM sales engineers anchored the qualitative base. Secondary validation drew from FERC interconnection filings, EIA transformer import data, NHTSA corridor designation records, and utility rate-case documentation. Bottom-up equipment deployment estimates triangulated against top-down infrastructure investment forecasts.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling transformer type, charging speed tier, mounting configuration, and power rating as core segmentation dimensions. CAGRs derived from utility capital expenditure trajectories and fleet electrification program timelines. Forecast inputs incorporated grain-oriented electrical steel capacity utilization and medium-voltage technician labor availability as industry-specific constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated microgrid bundlers or Chinese state-backed manufacturers would shift outcomes. Quarterly review of utility interconnection queue lengths and NHTSA corridor designation expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
Phase-Shifting Transformer Market
Transformers
Liquid Filled Transformer Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
Middle East and Africa Transformer Market
Transformers
Oil Filled Transformer Market
Transformers
North America Dry Type Transformer Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Europe Distribution Transformer Market
Transformers
Asia Pacific Smart Transformers Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
North America Smart Transformers Market
Transformers
United Arab Emirates Transformer Market
Transformers
Middle-East Smart Transformer Market
Transformers
India Power Transformer Market
Transformers
United States Transformer Market