
 Asia-Pacific Power Transformer (Below 100 MVA) Market | 2026-2036
Asia-Pacific Power Transformer (Below 100 MVA) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Power Transformer (Below 100 MVA) Market Analytics
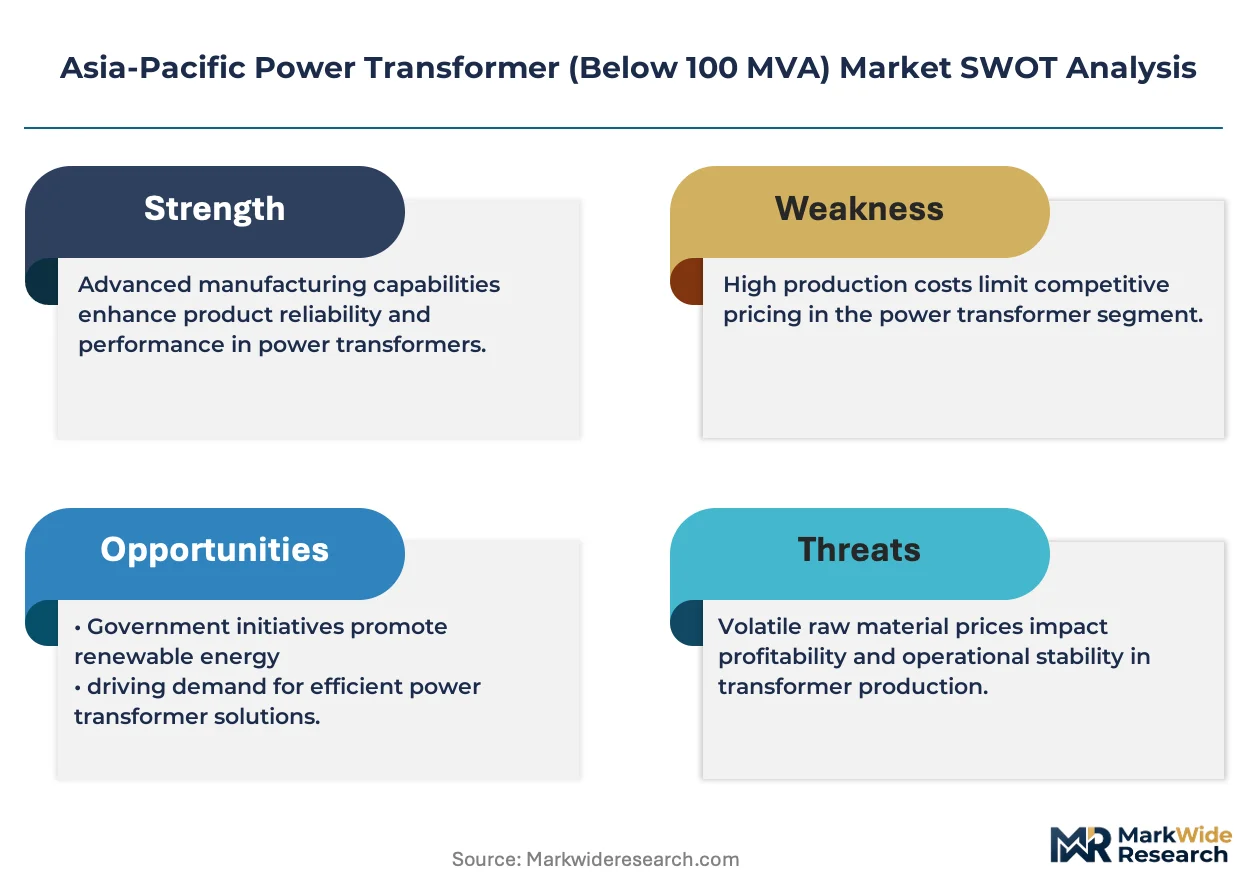
Renewable energy developers are reorganizing procurement priorities across the Asia-Pacific power transformer landscape. Industrial consumers and utility buyers still anchor volume, but solar and wind farm operators are gaining share as grid interconnection projects multiply. TBEA Co., Ltd. leverages its Xinjiang manufacturing base to dominate regional exports of step-up units for photovoltaic installations. Hitachi Energy competes through technology leadership in compact, high-efficiency designs tailored for space-constrained Japanese substations. Bharat Heavy Electricals Limited anchors Indian public-sector procurement with in-house production of 50 MVA and 75 MVA ratings for state transmission utilities.
Asia-Pacific power transformers below 100 MVA are electromagnetic devices that transfer electrical energy between circuits through mutual induction, typically operating at frequencies of 50 Hz or 60 Hz with oil-immersed or dry-type insulation systems depending on fire-safety and thermal constraints. Their primary purpose is voltage step-up or step-down for distribution networks, industrial plants, and renewable generation interconnection points where load centers sit at varying distances from generation assets. Step-down transformers occupy the largest volume share because urban densification and industrial park expansion require reliable medium-voltage distribution across sprawling metropolitan areas from Jakarta to Ho Chi Minh City. Outdoor installations lead the installation-type dimension due to lower capital costs and simpler maintenance access, though indoor variants are gaining traction in flood-prone coastal zones and dense commercial districts where space premiums override ventilation economics. The 50 MVA and 75 MVA power rating bands represent the fastest-growing tiers, driven by mid-scale solar farms and captive power needs of cement, steel, and chemical complexes that fall below grid-scale thresholds but exceed simple distribution transformer capacities.
India's Central Electricity Authority mandates BIS certification for all power transformers deployed in interstate transmission, while China's SAMR enforces GB standards that govern no-load loss limits and short-circuit withstand tests for equipment connected to State Grid Corporation networks. Japan's METI maintains JIS standards that impose stricter efficiency tiers than regional baselines, effectively segmenting export-accessible products from premium domestic-market designs. Australia's TGA-equivalent electrical safety frameworks and South Korea's MFDS-aligned energy efficiency labeling create additional compliance layers that filter supplier participation. Stakeholders must monitor how India's PLI scheme revisions and China's dual carbon goals recalibrate local content requirements and loss-reduction trajectories before committing to capacity expansion or partnership structures.
Market Dynamics
India's PLI scheme for power infrastructure is accelerating domestic manufacturing requirements, forcing foreign suppliers to localize core-winding and tank fabrication operations or exit interstate transmission procurement channels.
Growth Catalysts
- Renewable interconnection mandates:State transmission utilities in Gujarat and Maharashtra now require step-up transformers for mid-scale solar farms, pulling 50 MVA and 75 MVA ratings into rapid deployment cycles.
- CEA BIS certification expansion:India's Central Electricity Authority tightened interstate transmission standards, creating certified-supplier scarcity that rewards early compliance investments by domestic manufacturers.
- Urban densification clusters:Metropolitan expansion across Jakarta, Ho Chi Minh City, and Manila is multiplying medium-voltage distribution nodes that demand reliable step-down capacity.
Market Restraints
- Grain-oriented electrical steel concentration:Premium core material supply concentrates among Japanese and South Korean mills, exposing transformer producers to input cost volatility and allocation rationing during demand surges.
- Dual carbon goal compliance costs:China's MEE enforcement of no-load loss limits under GB standards forces design retooling that extends product development timelines and raises unit costs for export-oriented facilities.
- Dry-type insulation performance ceiling:Thermal constraints in high-humidity coastal environments limit dry-type transformer ratings, preserving oil-immersed dominance despite fire-safety preferences in dense commercial districts.
Strategic Opportunities
- Vietnam manufacturing corridor emergence:Industrial park electrification in Binh Duong and Dong Nai provinces is outpacing local transformer supply, opening channels for regional exporters with rapid-delivery capabilities.
- Digital twin integration:Convergence of IoT sensors with transformer monitoring platforms enables predictive maintenance contracts that unbundle hardware sales from long-term service revenue streams.
- Australia grid resilience programs:TGA-equivalent electrical safety frameworks and state-level bushfire hardening mandates are accelerating replacement cycles for aging distribution assets in Victoria and New South Wales.
Industry Challenges
- Skilled winding technician scarcity:Precision coil fabrication expertise concentrates among aging workforces in Japan and South Korea, constraining quality throughput at new facilities in India and Southeast Asia.
- Multi-standard certification timelines:Simultaneous pursuit of BIS, JIS, and GB approvals for regional product platforms stretches engineering resources and delays market entry by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Power Transformer (Below 100 MVA) Market |
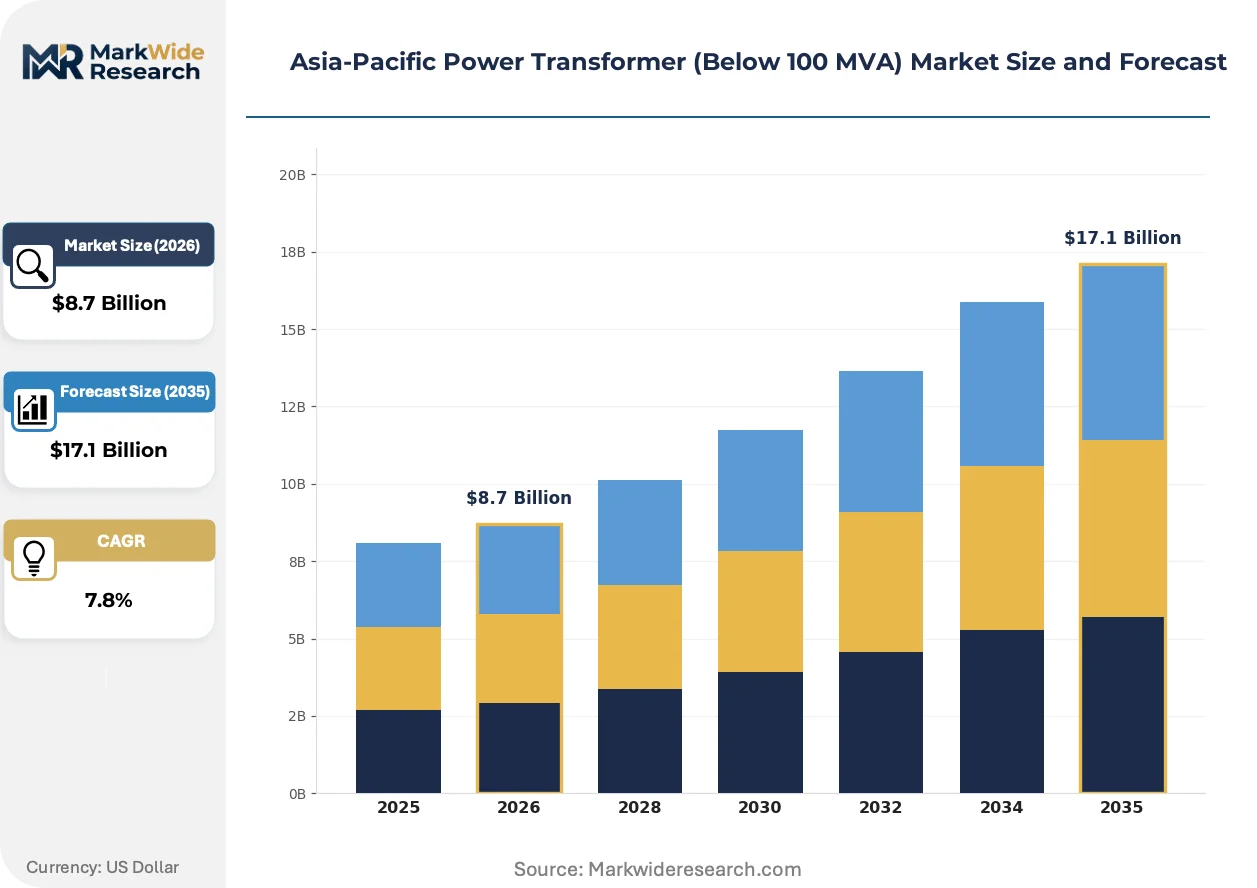
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-Up, Step-Down, Autotransformers, Isolated Transformers End User: Utilities, Industrial Consumers, Commercial Buildings, Renewable Energy Installation Type: Onshore, Offshore, Indoor, Outdoor Power Rating: 20 MVA, 50 MVA, 75 MVA, 100 MVA |
| Companies Covered | Siemens AG, ABB Ltd, Hitachi Energy, Mitsubishi Electric Corporation, Toshiba Energy Systems & Solution Corporation, Bharat Heavy Electricals Limited, TBEA Co., Ltd., Hyosung Heavy Industries, CG Power and Industrial Solutions, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Power Transformer (Below 100 MVA) Market Evolving Landscape
Transformer design and sourcing patterns across the Asia-Pacific region are fragmenting along efficiency-versus-cost axes as regulatory thresholds diverge and renewable integration pressures intensify.
Amorphous metal core technology is bifurcating the efficiency-tier landscape. These advanced alloys reduce no-load losses by 60-70% compared to conventional grain-oriented silicon steel. Japanese utilities and premium industrial buyers in South Korea are absorbing 25-35% cost premiums for METI JIS-compliant units. The technology is bifurcating supplier bases into export-accessible standard-efficiency producers and domestic-market premium specialists with captive amorphous metal supply.
China's SAMR is tightening GB standard no-load loss limits in phases through 2027, compressing allowable efficiency bands for equipment connecting to State Grid Corporation networks. Domestic manufacturers are redesigning core laminations and cooling systems to maintain certification eligibility. The 50 MVA rating band faces the steepest compliance cost escalation as it bridges distribution and small-transmission applications with diverging loss-calculation methodologies.
Captive power operators in India's western industrial corridor are consolidating procurement through engineering-procurement-construction contractors rather than direct utility relationships. Cement, steel, and chemical complexes now bundle transformer specifications into turnkey substation contracts that transfer specification risk to EPC firms. This concentration is most visible in Gujarat, where state industrial development corporations channel funding through single-window clearance mechanisms that favor integrated solution providers over component vendors.
Asia-Pacific Power Transformer (Below 100 MVA) Market Segmentation
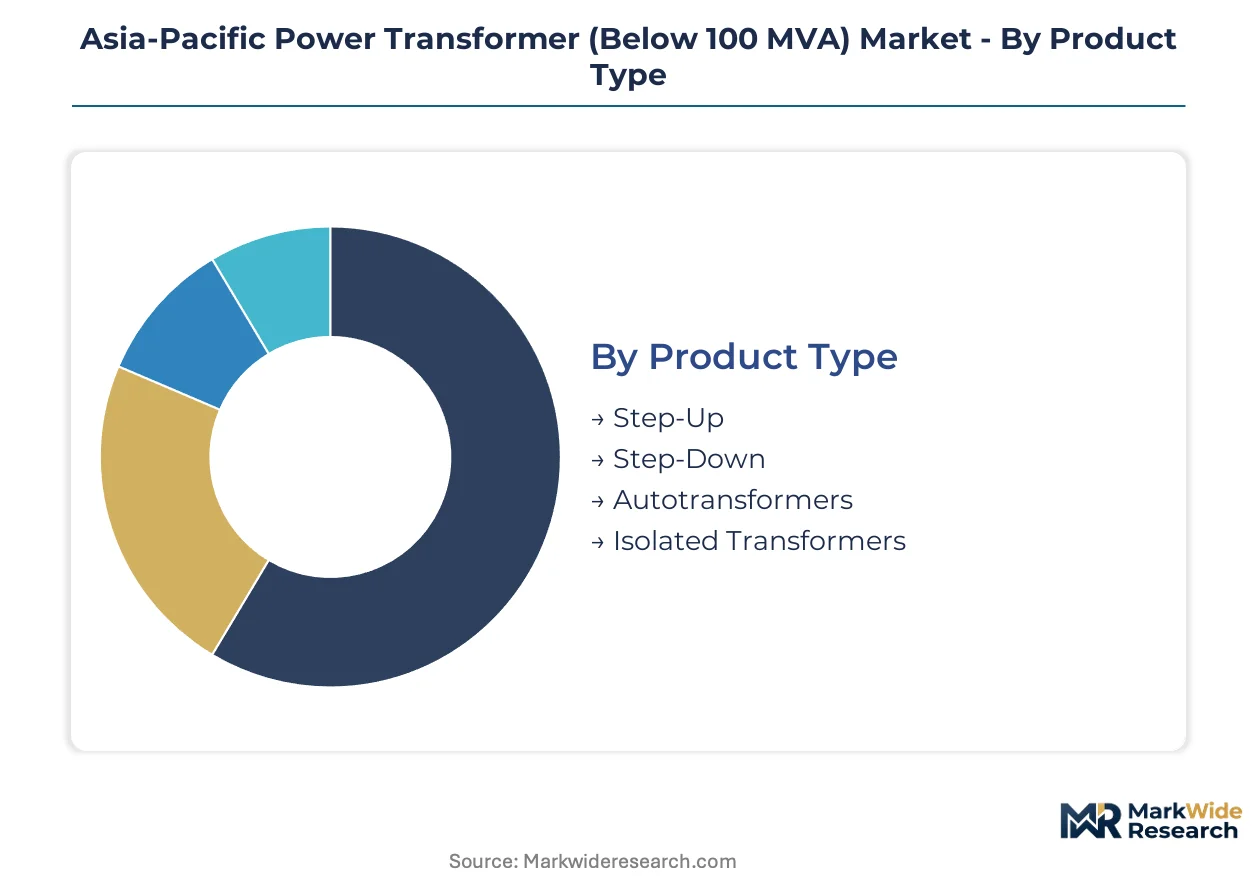
Segmentation in the Asia-Pacific power transformer market reflects divergent regulatory pressures across India, China, and Japan. Procurement specifications for State Grid Corporation networks, CEA-mandated BIS certification, and METI efficiency tiers each reshape demand patterns across product categories.
Product Type:
Regulatory differentiation across CEA BIS standards, SAMR GB requirements, and METI JIS tiers fragments product specifications by voltage transformation function.
- Step-Up:These units elevate generator output voltage for transmission across distance. Solar farms in Gujarat and Maharashtra anchor regional demand as renewable interconnection mandates multiply.
- Step-Down:Distribution networks from Jakarta to Ho Chi Minh City deploy these for medium-voltage delivery to industrial parks and dense urban clusters. Metropolitan densification multiplies node requirements.
- Autotransformers:Shared winding designs reduce copper content and physical footprint. Japanese utilities specify these for space-constrained substations under METI efficiency programs.
- Isolated Transformers:Separate primary and secondary windings eliminate electrical continuity. Mining and chemical facilities in Australia's resource corridors specify these for personnel protection.
Step-down transformers handle the majority of throughput; step-up units are gaining share fastest as solar and wind farm deployment accelerates.
End User:
Customer type determines specification rigor, with utility procurement governed by interstate transmission standards and industrial buyers prioritizing total cost of ownership over first cost.
- Utilities:State transmission utilities in India and provincial grid companies in China specify loss-optimized designs under CEA and SAMR mandates. BIS certification creates supplier scarcity.
- Industrial Consumers:Cement, steel, and chemical complexes across India's western corridor procure through EPC contractors. Captive power requirements favor 50 MVA and 75 MVA ratings.
- Commercial Buildings:Shopping complexes and data centers in flood-prone coastal zones specify dry-type insulation despite thermal constraints. Fire-safety premiums override ventilation economics.
- Renewable Energy:Wind and solar developers reorganize procurement priorities as grid interconnection projects multiply. Photovoltaic installations in Vietnam's central provinces drive step-up transformer demand.
Utilities anchor volume procurement; renewable energy developers are expanding most quickly as share shifts from conventional generation.
Installation Type:
Site constraints and capital cost trade-offs segment deployment patterns, with coastal exposure and space premiums reshaping technology selection.
- Onshore:Standard ground-mounted installations dominate utility-scale deployment. Lower capital costs and simpler maintenance access preserve this preference across India and Southeast Asia.
- Offshore:Specialized marine-grade enclosures and corrosion-resistant coatings address salt spray exposure. Offshore wind projects in South Korean waters and Japanese coastal zones drive niche specification.
- Indoor:Dense commercial districts in Tokyo, Singapore, and Sydney specify these where space premiums override ventilation economics. Flood-prone coastal zones in Vietnam and the Philippines increasingly require elevated indoor deployment.
- Outdoor:Unenclosed installations with weatherproofing dominate transmission and distribution networks. Capital efficiency and crane access for maintenance sustain this preference.
Outdoor installations handle the majority of throughput; indoor variants are climbing the fastest as urban densification intensifies.
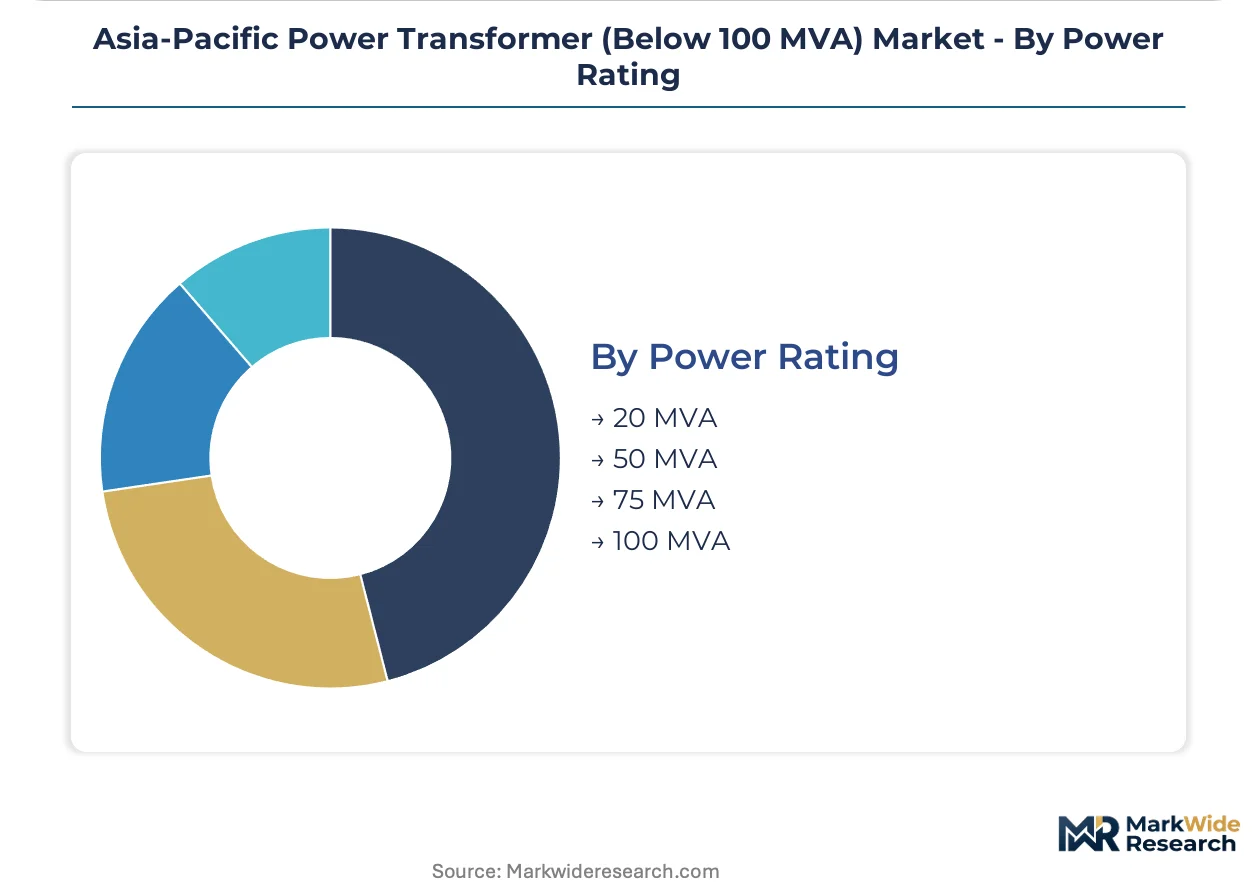
Power Rating:
Capacity bands align with application thresholds, with mid-scale ratings bridging distribution and small-transmission functions under diverging loss-calculation methodologies.
- 20 MVA:Distribution-level capacity serves secondary substations and small industrial loads. Urban ring networks in Indonesian and Philippine cities deploy these for redundancy.
- 50 MVA:Mid-scale solar farms and captive power facilities specify this band. China's SAMR compliance cost escalation is steepest here as GB standards tighten through 2027.
- 75 MVA:Larger industrial complexes and grid-scale renewable interconnection points anchor demand. State transmission utilities in Maharashtra and Gujarat specify these for solar evacuation infrastructure.
- 100 MVA:The upper threshold of this market segment serves small transmission substations. Japanese utilities under METI JIS standards specify premium-efficiency designs with amorphous metal cores.
50 MVA and 75 MVA ratings handle the majority of new throughput; 100 MVA units are expanding most quickly as transmission utilities upgrade substation capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ultra High Voltage (UHV) transmission backbone connecting Xinjiang to eastern load centers underwrites China's central role in regional transformer demand. India's Green Energy Corridors and Japan's grid hardening programs against seismic risk complete the infrastructure triangle shaping procurement patterns.
China
State Grid Corporation's 800 kV UHV projects drive step-up transformer demand for remote renewable evacuation. SAMR's phased GB standard tightening through 2027 forces core lamination redesigns. Manufacturing concentrates in Shandong and Jiangsu provinces where domestic mills supply grain-oriented electrical steel.
India
CEA-mandated BIS certification for interstate transmission creates certified-supplier scarcity rewarding early compliance. The PLI scheme for power infrastructure accelerates domestic manufacturing requirements. Demand concentrates in Gujarat and Maharashtra where solar farms and cement complexes specify 50 MVA and 75 MVA ratings.
Japan
METI JIS standards impose stricter efficiency tiers than regional baselines, segmenting export-accessible from premium domestic products. Space-constrained Tokyo substations favor compact autotransformer designs. Aging winding technician workforces constrain quality throughput at legacy facilities.
South Korea
MFDS-aligned energy efficiency labeling creates compliance layers filtering supplier participation. Offshore wind projects in coastal waters drive marine-grade enclosure specifications. Premium industrial buyers absorb cost premiums for amorphous metal core technology.
Vietnam
Industrial park electrification in Binh Duong and Dong Nai provinces outpaces local transformer supply. Flood-prone coastal zones increasingly require elevated indoor deployment despite ventilation economics. Central province solar farms pull step-up transformer demand from regional exporters.
Asia-Pacific Power Transformer (Below 100 MVA) Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The vendor base stratifies into three layers: global conglomerates with multi-standard portfolios, regional champions anchored to domestic procurement channels, and emerging specialists targeting renewable interconnection niches. Two dominant competitive moves define positioning: backward integration into core material supply to secure grain-oriented electrical steel allocation, and rapid multi-standard certification investments to compress 18-24 month approval timelines.
Among Asia-Pacific-based fabricators, TBEA Co., Ltd. and Bharat Heavy Electricals Limited occupy positions on opposite ends of the public-private spectrum. TBEA represents the state-linked specialist archetype with Xinjiang manufacturing dominance for photovoltaic step-up units. Bharat Heavy Electricals Limited exemplifies the public-sector anchor model, supplying state transmission utilities through in-house production of mid-range ratings. Hitachi Energy sits within the premium technology tier, competing through compact high-efficiency designs tailored for Japanese regulatory requirements.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Hitachi Energy |
| Mitsubishi Electric Corporation |
| Toshiba Energy Systems & Solution Corporation |
| Bharat Heavy Electricals Limited |
| TBEA Co., Ltd. |
| Hyosung Heavy Industries |
| CG Power and Industrial Solutions |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Indian state transmission utilities and domestic manufacturers lock in grain-oriented electrical steel allocation while freezing price visibility across multi-year procurement cycles. These contracts transfer raw material volatility risk to suppliers who must hedge against Japanese and South Korean mill pricing fluctuations.
Pricing Analysis
Volume-discount tiering structures separate CEA BIS-certified suppliers from uncertified competitors through 15-20% contract premiums. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the standard-efficiency tier is intensifying because China's SAMR is forcing redesign cycles that extend engineering timelines. State transmission utilities exhibit lowest price sensitivity; captive industrial buyers in Gujarat's cement corridor negotiate hardest on first cost.
Supply Chain Analysis
Japan and South Korea anchor grain-oriented electrical steel production, while China dominates core lamination fabrication and tank manufacturing. Transformer assembly draws from copper winding wire, insulating oil, and amorphous metal alloy feedstocks. Single-source vulnerability concentrates in premium core material allocation during demand surges. Distribution runs through EPC contractors in India's western corridor and direct utility procurement elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Renewable interconnection mandates across India and Vietnam are disrupting established procurement patterns, with CEA certification requirements and solar farm deployment timelines compressing supplier qualification windows.
For Market Incumbents: Consolidate backward integration into grain-oriented electrical steel supply channels to defend against Japanese and South Korean mill allocation rationing. Accelerate multi-standard certification investments to compress 18-24 month BIS-JIS-GB approval timelines before PLI scheme revisions harden local content thresholds. For New Entrants and Emerging Players: Anchor in Vietnam's Binh Duong and Dong Nai industrial corridor where electrification demand outpaces local transformer supply. Target 50 MVA step-up specifications for central province solar farms through rapid-delivery contracts that incumbent logistics networks cannot match. For Investors and Strategic Acquirers: Amorphous metal core specialists with captive alloy supply and METI JIS certification represent the highest-conviction acquisition archetype for premium-efficiency exposure. Watch for India's PLI scheme expansion into downstream winding and tank fabrication as the signal for domestic manufacturing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel | Captive grain-oriented electrical steel supply insulates against Japanese mill allocation rationing during demand surges. |
| Multi-Standard Certification Investment | Simultaneous BIS, JIS, and GB approvals compress market entry timelines for regional product platforms. |
| Digital Twin Platform Development | IoT-enabled predictive maintenance contracts unbundle hardware sales from recurring service revenue streams. |
| Vietnam Manufacturing Footprint | Local assembly presence captures industrial park electrification demand outpacing domestic transformer supply. |
| Amorphous Metal Core Scale-Up | Advanced alloy production capacity targets METI JIS efficiency tiers with 60-70% no-load loss reduction. |
Research Methodology
Initial hypotheses were tested against primary input from utility procurement officers, EPC contract managers, transformer plant engineers, and renewable project developers and refined through secondary validation against CEA transmission statistics, SAMR GB standard filings, customs trade data for grain-oriented electrical steel, and State Grid Corporation capex disclosures. Bottom-up unit economics triangulated against top-down infrastructure spending forecasts.
Variance-decomposition framing isolates segment-level growth contributions across power rating tiers, installation types, and end-user categories throughout the forecast period. CAGRs derive from installed base replacement cycles, renewable interconnection mandates, and industrial electrification trajectories. Modeling incorporates CEA certification timelines, PLI scheme revision schedules, and SAMR efficiency standard phase-ins as structural parameters.
Underlying assumptions cover regulatory enforcement continuity, raw material allocation stability, and grid interconnection project execution rates, with deviation risk concentrated in India's PLI localization requirements and China's dual carbon goal compliance costs. Recalibration cycles align with material shifts in CEA mandate revisions, SAMR standard updates, and renewable capacity auction outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
United States Transformer Market
Transformers
United States Dry-Type Transformer Market
Transformers
Global Transformer Market
Transformers
Europe Distribution Transformer Market
Transformers
Rail Traction Transformers Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
India Power Transformer Market
Transformers
Air Cooled Transformer Market
Transformers
Green Power Transformers Market
Transformers
Europe Smart Transformers Market
Transformers
High Frequency Transformer Market
Transformers
Electric Vehicle Charging Station Transformer Market
Transformers
Transformer Steel Market
Transformers
Oil Filled Transformer Market
Transformers
United Arab Emirates Transformer Market
Transformers
Single Phase Power Transformer Market