
 Solar Tracker Installation Market | 2026-2036
Solar Tracker Installation Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Tracker Installation Market Analysis
Aftermarket service revenue is reconfiguring margin pools away from pure hardware supply toward predictive maintenance contracts and software subscriptions. Nextracker leverages its proprietary monitoring platform to capture recurring revenue streams across installed fleets. Array Technologies anchors its competitive position through domestic steel fabrication capabilities that insulate project timelines from import volatility. Soltec specializes in terrain-adaptive designs that reduce civil engineering costs on uneven sites.
A solar tracker installation comprises electromechanical structures that orient photovoltaic modules toward the sun throughout the day, typically achieving 20-35% energy yield improvement over fixed-tilt systems through single-axis or dual-axis rotation mechanisms. The primary commercial purpose centers on maximizing levelized cost of electricity for utility-scale and commercial solar assets. Ground-mounted installations dominate project pipelines due to economies of scale in open terrain development, while bifacial tracker configurations command premium positioning as module technology evolves. Single-axis systems sustain the largest installed base, though dual-axis designs retain niche appeal in concentrated solar power applications where precise focal alignment drives thermal efficiency.
FERC interconnection standards and state-level renewable portfolio obligations in California, Texas, and Arizona shape deployment timelines and grid-access prioritization for tracker-backed projects. The EPA's greenhouse gas reporting requirements and evolving ISO 14001 environmental management expectations pressure developers toward lower-embodied-carbon steel sourcing and end-of-life recyclability planning. Stakeholders must monitor evolving domestic content thresholds in federal incentive programs, as tariff and trade policy adjustments could abruptly restructure cost competitiveness between integrated domestic manufacturers and importers of tracker subassemblies.
Market Dynamics
The solar tracker installation market is being restructured by bifacial module penetration, which demands redesigned torque tube spacing and control algorithms to capture rear-side irradiance gains. This technological inflection is forcing hardware suppliers to recalibrate mechanical tolerances and software architectures simultaneously.
Growth Catalysts
- Investment Tax Credit extension:The IRA's production and investment incentives in the United States compress project payback periods for utility-scale deployments, accelerating procurement timelines for single-axis systems.
- Steel fabrication clustering:Domestic torque tube manufacturing capacity in India and Vietnam is expanding to serve Southeast Asian solar parks, reducing lead times for regional EPC contractors.
- Bifacial module compatibility:Tracker architectures optimized for dual-glass panels with elevated rear clearance are capturing incremental yield premiums in high-albedo desert installations.
Market Restraints
- Steel price volatility:Galvanized steel coil costs fluctuate with scrap metal and zinc input markets, compressing fabrication margins for torque tube producers without long-term offtake contracts.
- Control system concentration:Motor drive and sensor assembly capacity concentrates in Ningbo industrial corridors, exposing project timelines to shipping congestion and customs processing delays.
- Interconnection queue saturation:FERC study backlogs in Texas and California extend commercial operation dates for tracker-backed projects, stranding capital in pre-revenue phases.
Strategic Opportunities
- Agrivoltaic integration:Elevated tracker configurations enabling simultaneous crop cultivation and energy generation are penetrating agricultural zones in Italy and Japan where land-use restrictions constrain conventional solar.
- Predictive maintenance platforms:IoT-enabled failure prediction for drive motors and bearings is creating recurring revenue streams that decouple vendor economics from pure hardware shipment cycles.
- Floating solar adaptation:Corrosion-resistant tracker mechanisms for reservoir-mounted installations address unmet demand in Brazil and Thailand where land availability is constrained.
Industry Challenges
- Control software talent scarcity:Embedded systems engineers with photovoltaic tracking algorithm expertise command premium compensation, constraining R&D velocity for mid-tier hardware suppliers.
- Foundation standardization gaps:Geotechnical variability across desert, agricultural, and landfill sites forces project-specific civil engineering, preventing modular installation cost reductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Tracker Installation Market |
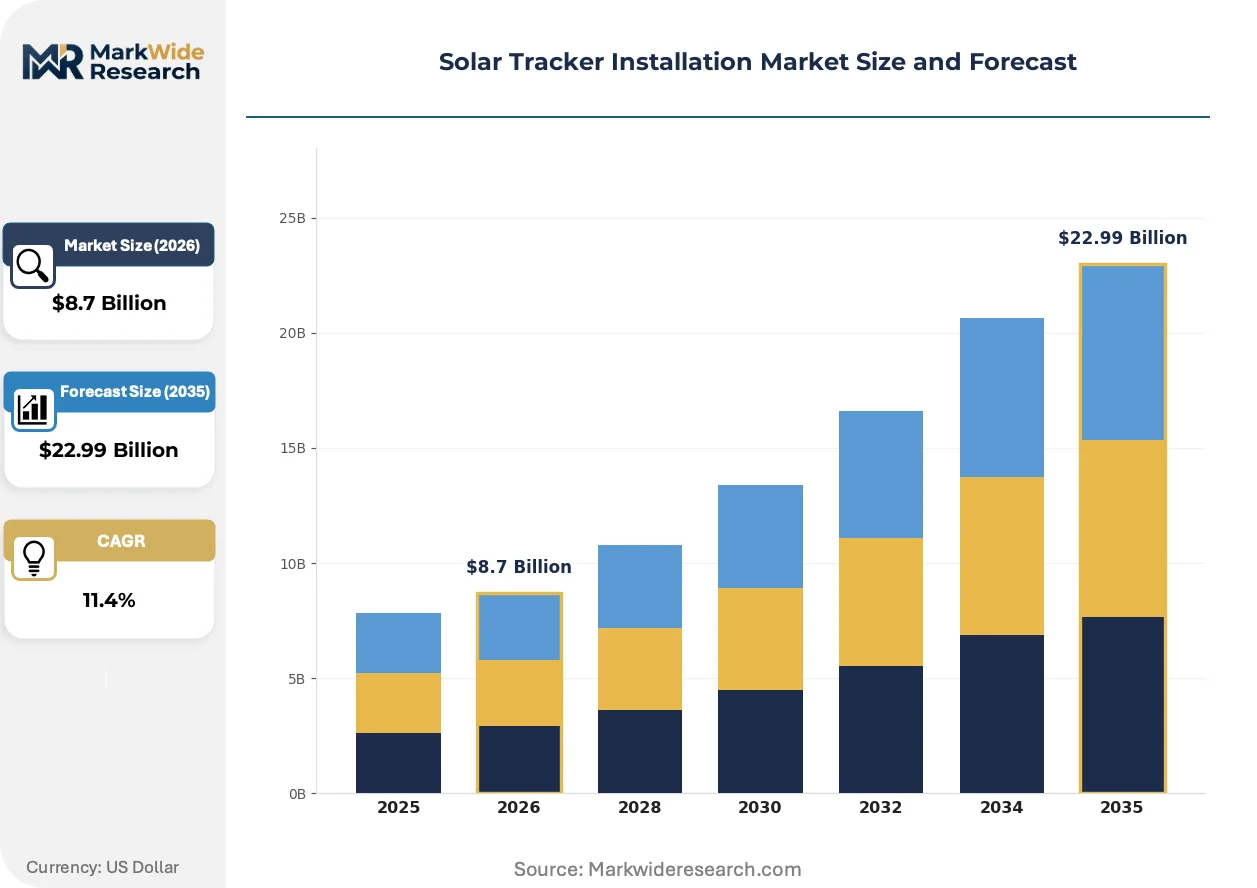
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Installation Type: Ground-mounted, Rooftop, Bifacial, Hybrid System Type: Single-axis, Dual-axis, Active, Passive End User: Commercial, Industrial, Utility, Residential Technology: Photovoltaic, Concentrated Solar Power, Solar Thermal, Others |
| Companies Covered | GameChange Solar, PV Hardware, Nextracker, Trina Tracker, Versolsolar, Arctech Solar, Soltec, FTC Solar, Array Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Tracker Installation Market Emerging Trajectories
Tracker technology is converging with module and inverter intelligence to create self-optimizing solar assets. Three developments are compressing traditional boundaries between hardware, software, and O&M services.
Self-cleaning coating integration is collapsing the distinction between module and tracker maintenance cycles. Hydrophobic surface treatments applied to torque tubes and module glass reduce soiling losses in arid climates. Saudi solar developers are specifying these coatings for Neom gigaprojects, compressing labor requirements for manual washing operations.
EU Green Deal carbon border adjustments are reshaping steel sourcing protocols for tracker manufacturers. The CBAM transitional phase requires embedded emissions documentation for imported torque tubes, favoring electric-arc-furnace producers with renewable energy power purchase agreements. German project developers are now auditing mill certificates for Scope 1 and 2 emissions intensity.
Long-term service contracting is displacing transactional spare parts sales as the dominant aftermarket model. Predictive analytics platforms enable performance guarantees that bundle hardware replacement with uptime commitments. This shift is most visible in Australian utility-scale portfolios where asset owners prioritize availability over capital expenditure minimization.
Solar Tracker Installation Market Segmentation
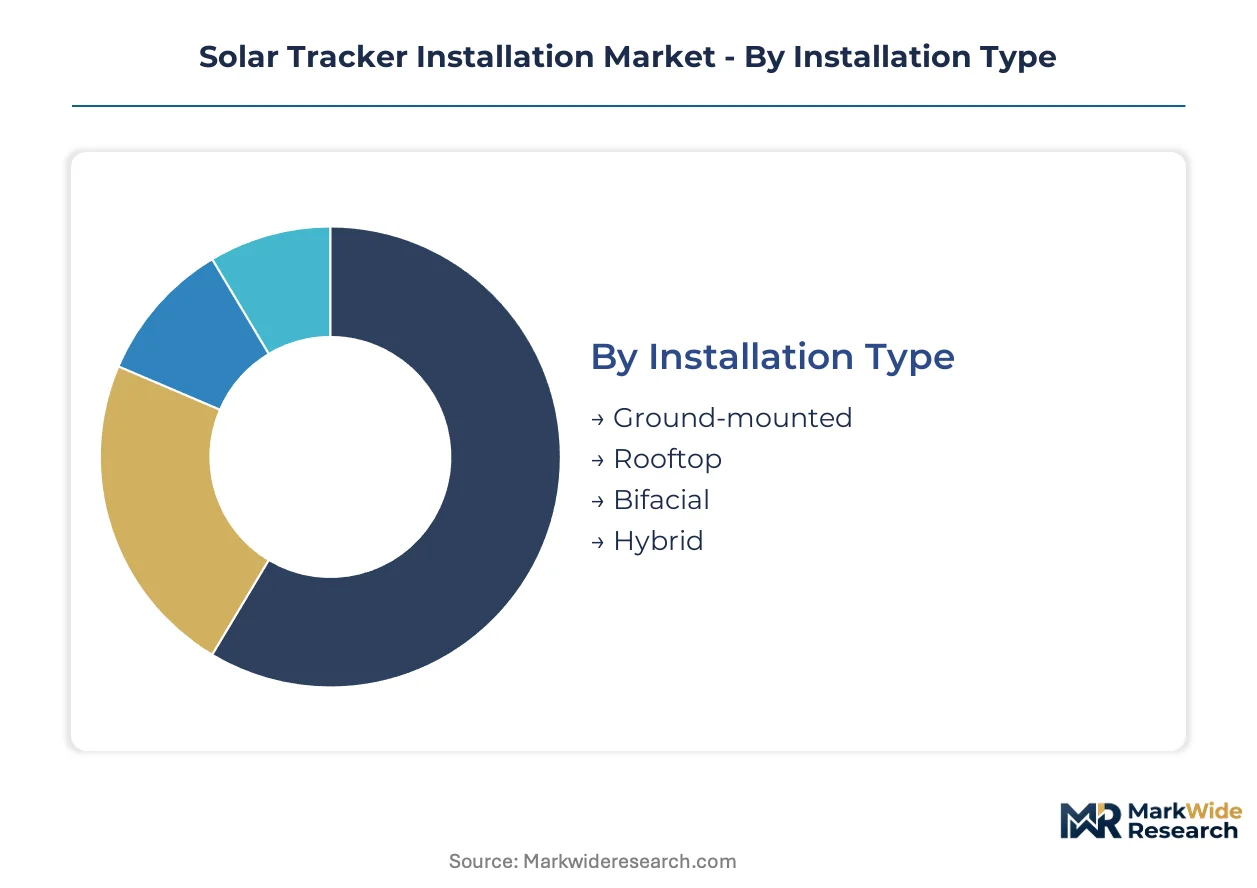
Tracker deployment patterns diverge sharply across installation contexts, system architectures, and energy conversion technologies. Each segmentation axis reveals distinct procurement priorities, engineering constraints, and margin structures that shape vendor positioning.
Installation Type:
Mature configurations dominate utility procurement, while emerging formats capture specialized terrain and dual-use applications.
- Ground-mounted:Open-terrain steel structures anchored by driven piles or concrete ballast constitute the baseline for utility-scale solar parks. Southwestern United States project pipelines concentrate here, with EPC contractors optimizing for acreage density and geotechnical uniformity. FERC interconnection timelines and IRA production incentives compress procurement cycles for these installations.
- Bifacial:Elevated torque tube spacing and algorithmic rear-side irradiance tracking extract incremental yield from dual-glass modules in high-albedo desert environments. Saudi developers at Neom gigaprojects specify these configurations to maximize energy density per hectare, though civil engineering costs rise with foundation height requirements.
- Rooftop:Low-profile tracking mechanisms adapt to commercial building structural load limits and wind uplift codes. METI technical standards in Japan constrain maximum tilt angles for urban installations.
- Hybrid:Dual-purpose structures combining photovoltaic generation with agricultural cultivation or reservoir coverage address land-use restrictions in Italy and Thailand.
Ground-mounted configurations handle the majority of throughput; bifacial installations are expanding most quickly on share.
System Type:
Cost tier differentiation separates mass-market electromechanical systems from precision-engineered alternatives serving concentrated thermal applications.
- Single-axis:East-west rotation driven by linear actuators or motor-driven slew gears delivers 20-35% yield improvement over fixed-tilt at moderate hardware cost. Ningbo industrial corridors concentrate motor drive and sensor assembly capacity for these systems, exposing project timelines to shipping congestion.
- Dual-axis:Azimuth and elevation tracking maintains precise solar alignment for concentrated solar power applications where focal accuracy drives thermal efficiency. These systems command premium positioning in CSP towers and parabolic trough installations despite higher mechanical complexity and maintenance burden.
- Active:Real-time sensor feedback and predictive algorithms adjust positioning based on weather conditions and soiling forecasts. Control software talent scarcity constrains R&D velocity for mid-tier hardware suppliers developing these capabilities.
- Passive:Thermal expansion and gravitational mechanisms eliminate motor and controller dependencies, reducing capital cost and failure modes for remote deployments.
Single-axis systems anchor volume procurement; dual-axis designs claim the steepest expansion trajectory in thermal power segments.
End User:
Customer type determines contract structure, financing mechanisms, and service intensity across the ownership spectrum.
- Utility:Independent power producers and regulated utilities deploy single-axis trackers across multi-hundred-megawatt portfolios, prioritizing availability guarantees and long-term service contracting over upfront capital minimization. Australian asset owners exemplify this shift toward outcome-based O&M partnerships.
- Commercial:C&I developers balance rooftop structural constraints with behind-the-meter savings optimization, often selecting low-profile active tracking for retail and logistics facilities.
- Industrial:Heavy manufacturing and data center operators procure on-site generation with uptime requirements that favor predictive maintenance platforms and spare parts stocking agreements.
- Residential:Distributed rooftop applications rarely justify tracker complexity given smaller scale and shading variability, though niche dual-axis kits penetrate high-insolation rural markets.
Utility procurement drives aggregate capacity additions; commercial installations are climbing the fastest as distributed generation economics improve.
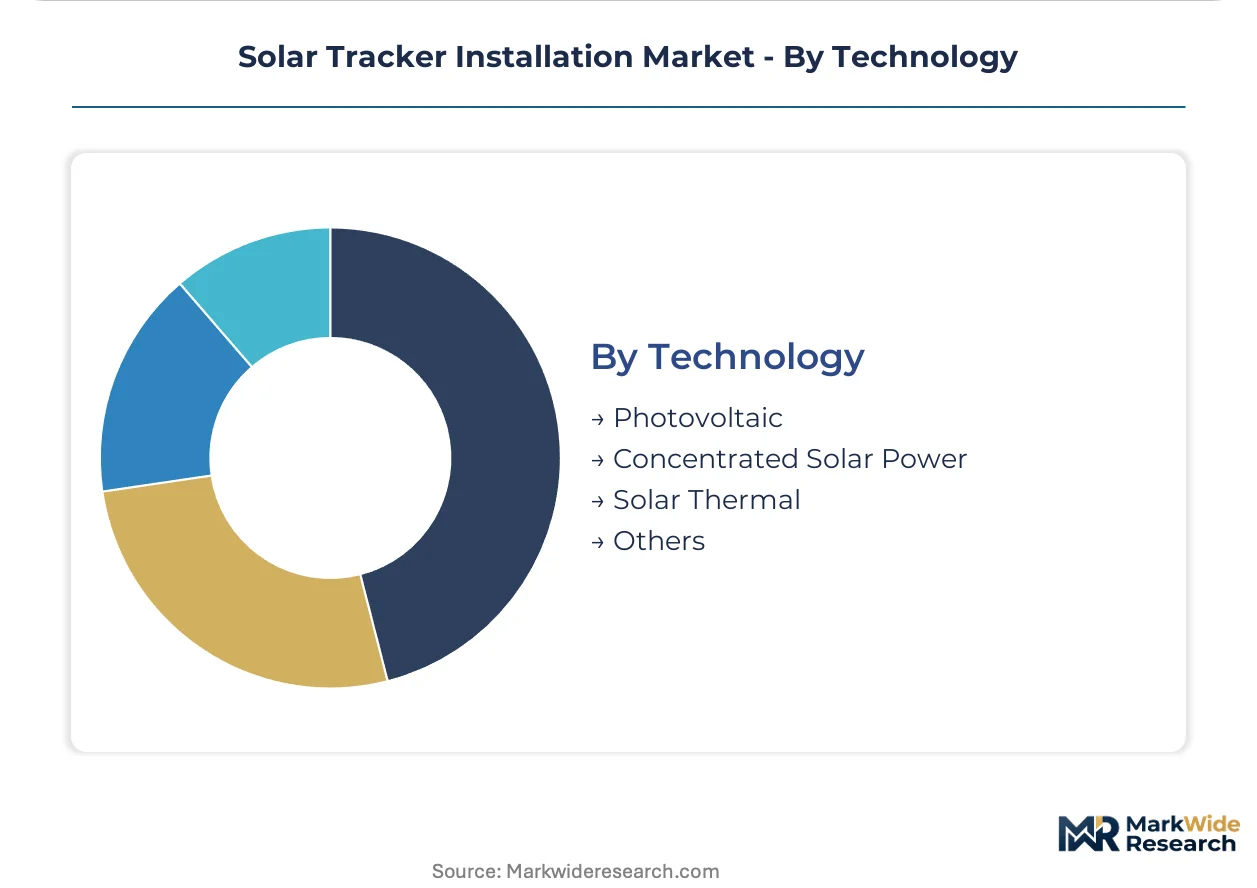
Technology:
Energy conversion mechanism dictates tracker precision requirements, thermal tolerance, and integration architecture.
- Photovoltaic:Silicon and thin-film module orientation dominates installed base, with bifacial compatibility now standard in new tracker designs. EU Green Deal carbon border adjustments reshape steel sourcing protocols for these systems, favoring electric-arc-furnace producers with renewable power purchase agreements.
- Concentrated Solar Power:Heliostat fields and parabolic troughs demand sub-degree tracking accuracy to maintain focal alignment on thermal receivers. Dual-axis systems retain essential positioning in this segment despite cost premiums.
- Solar Thermal:Flat-plate and evacuated tube collectors for water heating deploy simpler seasonal tilt adjustment rather than continuous tracking.
- Others:Emerging concentrator photovoltaics and solar fuel synthesis pilot projects test precision tracking at laboratory scale.
Photovoltaic applications absorb the dominant share of tracker deployment; concentrated solar power represents the fastest-growing trajectory in thermal generation markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Vietnam exhibit acute price sensitivity to steel input costs, while Australian and Saudi Arabian utilities prioritize availability guarantees over capital minimization. This demand-elasticity contrast shapes procurement patterns across tracker markets.
United States
Southwestern utility-scale solar farms in Arizona and Texas drive concentrated demand for single-axis systems. The IRA's Investment Tax Credit extension compresses project payback periods, accelerating procurement timelines. Ningbo industrial corridors supply motor drive assemblies, though domestic steel fabrication in Indiana and Texas insulates some projects from import volatility.
China
Torque tube and control system manufacturing clusters dominate global supply capacity around Ningbo and Tianjin industrial zones. The country's national renewable energy administration enforces grid-connection standards that prioritize tracker-backed projects in western desert provinces. Dual carbon goals pressure domestic producers toward electric-arc-furnace steel with renewable power purchase agreements.
Australia
Utility-scale asset owners in New South Wales and Queensland prioritize long-term service contracting over upfront hardware costs. The national electricity regulator mandates grid stability studies that extend interconnection timelines for tracker-backed projects. Predictive maintenance platforms from domestic integrators capture recurring revenue across installed fleets.
Saudi Arabia
Neom gigaprojects specify bifacial tracker configurations with self-cleaning coatings to maximize yield density per hectare. The national renewable energy program awards capacity through competitive auctions that reward technology differentiation. Eastern Province industrial zones host assembly operations serving Gulf Cooperation Council markets.
India
Rajasthan and Gujarat solar parks expand procurement of terrain-adaptive designs for uneven desert topography. The national solar mission production-linked incentive scheme supports domestic torque tube fabrication capacity expansion. Domestic steel producers in Jharkhand and Odisha supply galvanized coil to regional EPC contractors.
Solar Tracker Installation Market Vendor Landscape
Integrated platform providers and specialized hardware fabricators split the market along service-intensity and cost-efficiency vectors. The vendor base concentrates around three strategic archetypes: predictive analytics platforms capturing recurring revenue, domestic steel fabricators insulating timelines from import volatility, and terrain-adaptive specialists reducing civil engineering costs on complex sites. M&A activity targets control software capabilities, while capacity expansion concentrates in India and Vietnam to serve Southeast Asian solar parks.
Among North American platform providers, Nextracker and Array Technologies exemplify the integrated service model, with the former leveraging proprietary monitoring systems and the latter anchoring competitive position through domestic fabrication. Soltec occupies a position within the terrain-adaptive specialist tier. Chinese manufacturers including Trina Tracker and Arctech Solar represent scale-driven fabrication archetypes serving global export markets.
| Leading Market Players |
|---|
| GameChange Solar |
| PV Hardware |
| Nextracker |
| Trina Tracker |
| Versolsolar |
| Arctech Solar |
| Soltec |
| FTC Solar |
| Array Technologies |
| Others |
Supply Flow & Price Mechanics
Ningbo industrial corridors concentrate motor drive and sensor assembly capacity, anchoring margin pools in aftermarket service tiers rather than pure hardware shipment. Galvanized steel coil volatility and control system import exposure compress fabrication margins for domestic assemblers lacking long-term offtake contracts.
Pricing Analysis
Aftermarket service contracts and predictive maintenance subscriptions now drive lifetime value capture across installed tracker fleets. Three-tier pricing structure across premium, standard, and economy levels separates vendors bundling uptime guarantees from transactional parts suppliers. Price differentiation rests on steel sourcing certification and software platform integration depth. Cost compression in standard-tier hardware is intensifying because Indian and Vietnamese fabrication capacity expansion erodes legacy premium positioning. Utility-scale asset owners in Australia and Saudi Arabia exhibit lowest price sensitivity, prioritizing availability commitments over capital expenditure minimization.
Supply Chain Analysis
Contract manufacturing for torque tubes and drive assemblies concentrates in Ningbo, Tianjin, and Ho Chi Minh City industrial zones. Raw material dependencies span galvanized steel coil, zinc ingot, and rare-earth motor magnets. Supply chain risk centers on FERC interconnection queue saturation stranding pre-revenue capital in Texas and California project pipelines. Distribution runs through regional EPC contractor networks with direct procurement relationships to utility-scale developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
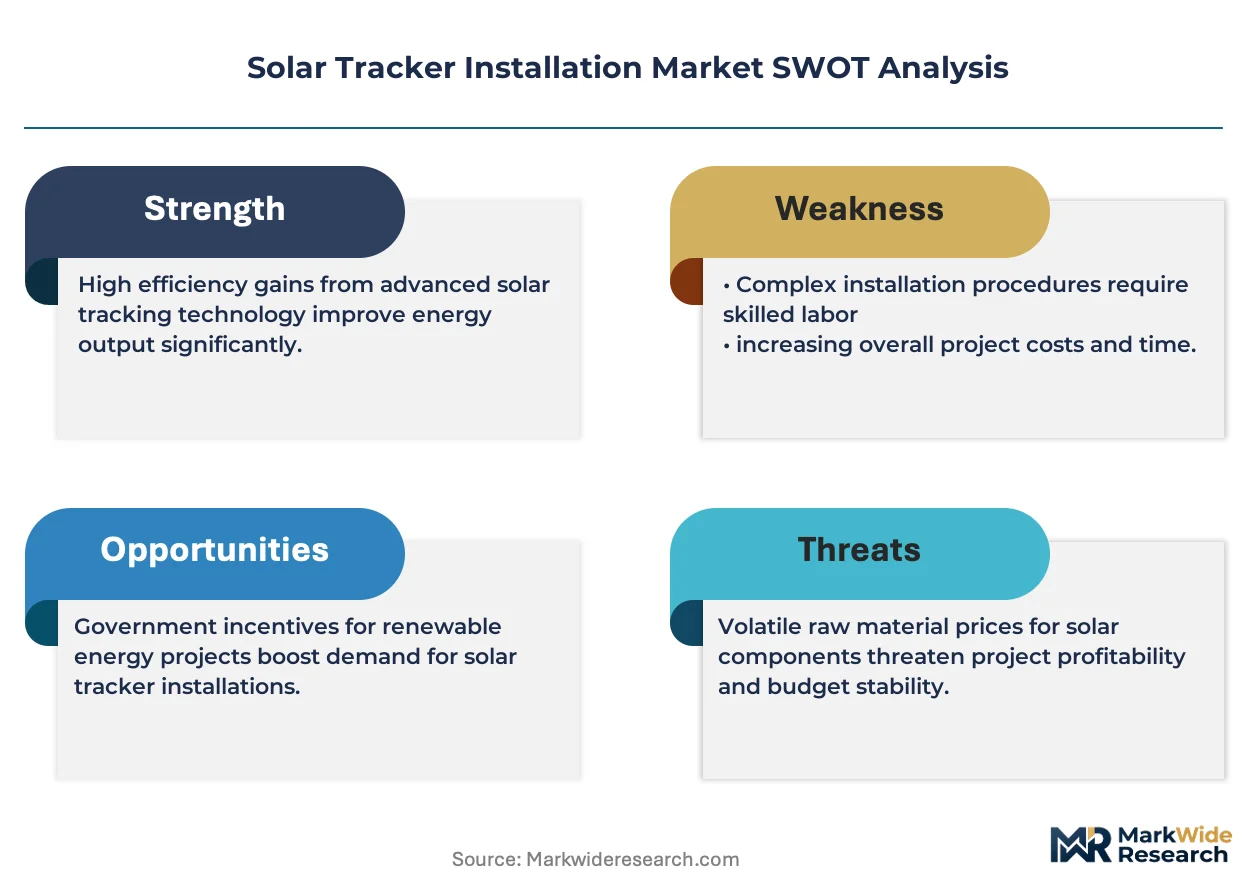
Fixed-tilt racking systems and agrivoltaic fixed-mount alternatives threaten substitution as steel price volatility compresses tracker payback advantages. Incumbents must defend through service bundling and domestic fabrication insulation.
For Market Incumbents: Entrench predictive maintenance platform adoption to lock recurring revenue streams and raise switching costs for utility-scale asset owners. Secure captive steel fabrication capacity in Indiana or Texas to insulate project timelines from Ningbo shipping congestion and customs processing exposure. Counter emerging terrain-adaptive specialists by acquiring control software capabilities that reduce civil engineering customization costs.
For New Entrants and Emerging Players: Mid-market commercial rooftop installations in Japan and Italy represent the most penetrable entry point given METI technical standards and land-use restrictions constraining incumbent tracker designs. Floating solar reservoir applications in Brazil and Thailand offer uncaptured demand where corrosion-resistant mechanisms command premium positioning. Lead with outcome-based O&M partnerships rather than hardware-only sales to differentiate from established volume suppliers.
For Investors and Strategic Acquirers: Capital is best deployed toward control software specialists with embedded systems expertise in photovoltaic tracking algorithms, given talent scarcity constraining R&D velocity for mid-tier hardware vendors. Long-term viability hinges on predictive analytics platform penetration decoupling vendor economics from shipment cycles. Monitor FERC interconnection queue clearance rates as the signal to watch for demand inflection in the southwestern United States.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | IoT-enabled failure prediction for drive motors creates recurring revenue streams across Australian utility fleets. |
| Domestic Steel Fabrication Expansion | Captive torque tube production in Indiana insulates Array Technologies from import volatility and IRA domestic content thresholds. |
| Terrain-Adaptive Design Acquisition | Control software capabilities reduce civil engineering costs on Rajasthan desert sites with geotechnical variability. |
| Agrivoltaic Tracker Configuration Launch | Elevated structures enable simultaneous crop cultivation in Italian agricultural zones with restrictive land-use codes. |
| Floating Solar Mechanism Development | Corrosion-resistant designs address unmet reservoir-mounted demand in Thailand where land availability constrains conventional deployment. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with tracker manufacturers, EPC contractors, utility planning officers, and IPP project developers; and secondary validation through FERC interconnection filings, EIA generation capacity data, IEA renewable technology reports, and customs trade records for galvanized steel coil imports. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates across the analysis window.
Forecast inputs span installation type segmentation, system architecture tiers, end-user contract structures, and technology conversion mechanisms. CAGRs were derived from modeled deployment trajectories against steel price volatility scenarios and IRA incentive duration assumptions. Regional splits incorporated country-specific renewable portfolio obligations, interconnection queue backlogs, and domestic content threshold compliance pathways.
Macroeconomic conditions sit as an overlay; deviation in galvanized steel coil pricing, zinc input costs, or shipping lane congestion would shift the trajectory. Forecasts reflect documented assumptions on bifacial module penetration rates and control system import exposure. Quarterly review of FERC queue clearance rates, Ningbo port congestion indices, and IRA domestic content rule adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Thin Film Photovoltaic Modules Market
Solar Power Systems
Asia-Pacific Rooftop Solar Market
Solar Power Systems
Solar Polysilicon Ingot Wafer Cell Module Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Polycrystalline Solar Cell Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Solar Phone Chargers Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Flat Plate Solar Collector Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Global Solar PV Balance of System Market