
 China Transformer Market | 2026-2036
China Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
China Transformer Market Outlook
GB standards on transformer energy efficiency is hardening the cost-of-entry calculus for new manufacturers. TBEA Co., Ltd. leverages its integrated silicon steel and winding operations to absorb compliance costs without margin erosion. CHINT Electric Co., Ltd. anchors its position through deep distribution into county-level power bureaus. XJ Electric Co., Ltd. specializes in extra-high-voltage converter transformers for long-distance DC transmission projects.
A transformer is a static electromagnetic device that transfers electrical energy between circuits through mutual induction, typically operating at frequencies of 50 Hz in China with core laminations of grain-oriented silicon steel to minimize eddy-current losses. Its primary purpose is to step voltage up for efficient long-distance transmission or step it down for safe end-use distribution. Power transformers dominate capital deployment as ultra-high-voltage backbone expansion continues, while distribution transformers face replacement pressure from GB-tier efficiency mandates. Instrument transformers represent a concentrated margin pool for firms with metering-calibration certifications.
SAMR enforces compulsory certification for transformer safety and electromagnetic compatibility, while MEE tracks embodied carbon in steel and insulating oil through product lifecycle assessments. MIIT's industrial policy directs capacity consolidation toward enterprises meeting tier-one energy efficiency benchmarks. Stakeholders must monitor whether dual carbon enforcement tightens material sourcing requirements faster than domestic silicon steel capacity expands.
Market Dynamics
State Grid Corporation and China Southern Power Grid are accelerating ultra-high voltage corridor buildouts, compressing procurement cycles for 1000kV+ converter transformers while GB 20052-2020 efficiency tiers force simultaneous fleet replacement.
Growth Catalysts
- Ultra-high voltage transmission expansion:State Grid's 14th Five-Year Plan mandates new ±1100kV DC lines linking western generation bases to eastern load centers, pulling demand for converter transformers and shunt reactors.
- Dual carbon policy enforcement:MEE's embodied carbon tracking for steel and insulating oil is retrofitting lifecycle accounting into utility procurement scoring, advantaging suppliers with captive silicon steel.
- County-level distribution modernization:Rural grid upgrades in Henan and Shandong are replacing millions of S9-era distribution transformers with GB-tier amorphous-core units.
Market Restraints
- Grain-oriented silicon steel concentration:Baowu Steel and Shougang control over 80% of domestic high-permeability lamination supply, creating input bottlenecks during UHV procurement surges.
- Amorphous alloy import dependency:Metglas and Hitachi Metals dominate ribbon supply for distribution transformer cores, exposing tier-2 manufacturers to yen-denominated volatility and MOFCOM anti-dumping duties.
- SF6 insulation phase-out friction:MEE's fluorinated gas restrictions are colliding with the 12-18 month qualification timelines for dry-type and natural ester alternatives in 220kV+ applications.
Strategic Opportunities
- Digital twin integration:MIIT's smart grid demonstration zones in Jiangsu and Zhejiang are piloting sensor-embedded transformers with edge analytics, opening software-attach revenue streams for hardware OEMs.
- Offshore wind platform demand:Guangdong and Fujian coastal arrays require 66kV collector transformers with salt-fog corrosion ratings, a specification gap versus onshore product lines.
- Second-life battery storage coupling:Retired electric vehicle cells from CATL and BYD supply chains are being repurposed into transformer substation buffer systems under provincial peak-shaving incentives.
Industry Challenges
- UHV test bay scarcity:Only Xian and Suzhou facilities can perform full-load heat-run verification for 1000kV units, creating 8-10 month queue bottlenecks for new entrants.
- GB standard revision cadence:SAMR's three-year efficiency tier updates are forcing R&D retooling faster than typical 5-year product amortization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Transformer Market |
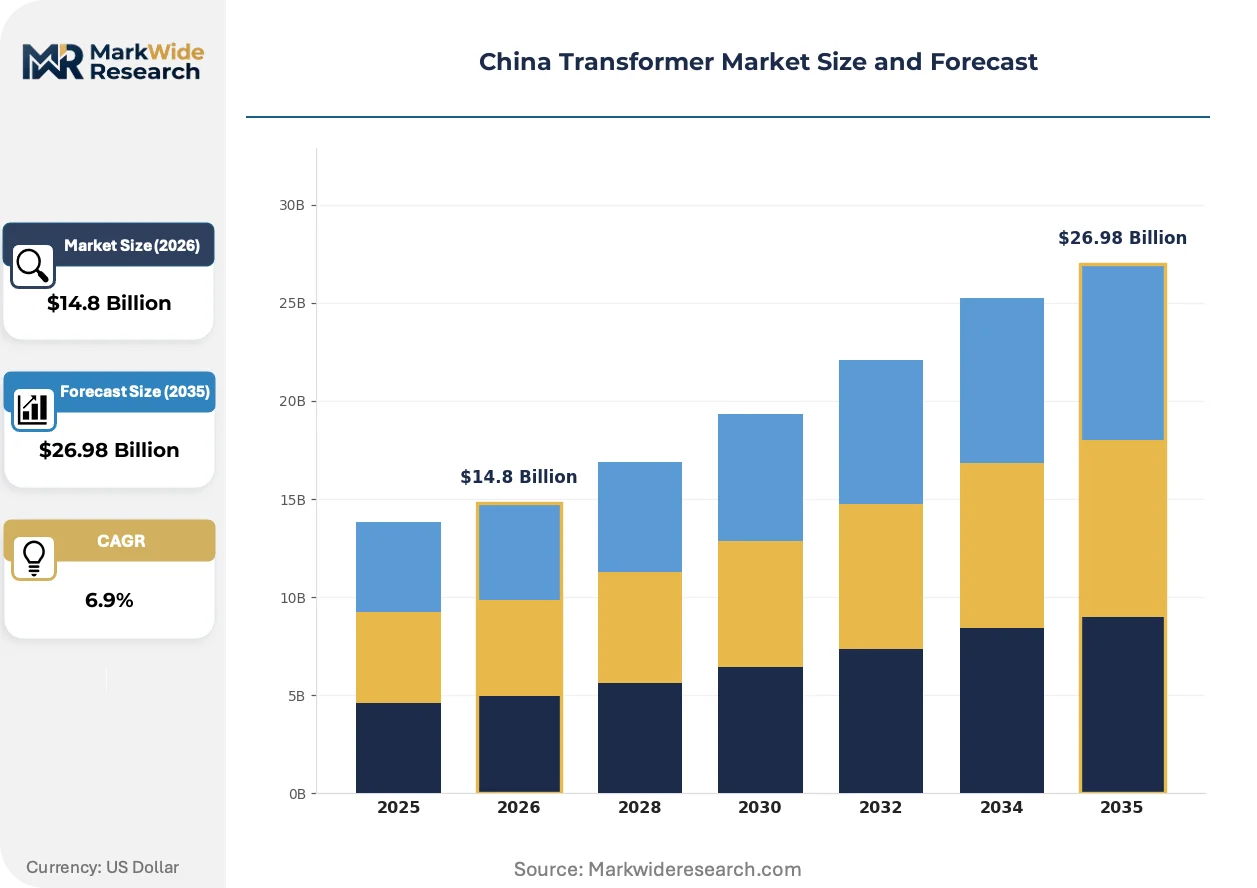
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Transformer, Distribution Transformer, Instrument Transformer, Auto Transformer End User: Utilities, Industrial, Commercial, Residential Installation Type: Indoor, Outdoor, Substation, Pole-mounted Voltage Level: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | CHINT Electric Co., Ltd., AISITE Transformer Co., Ltd., TBEA Co., Ltd., XJ Electric Co., Ltd., Shandong Electrical Engineering Group Co., Ltd., China XD Group, CEEG, Jinpan Technology Co., Ltd., Taikai Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Transformer Market Strategic Shifts
Transformer architecture is bifurcating between maximized efficiency for distribution replacement and extreme reliability for UHV backbone expansion, with material science and digitalization bridging both paths.
Amorphous metal core technology is electrifying distribution transformer efficiency curves. Non-crystalline alloy ribbons from Hitachi Metals and Qingdao Yunlu enable no-load losses 70% below conventional grain-oriented steel. State Grid's Jiangsu subsidiary has standardized amorphous units for all new 10kV urban deployments since 2023. This material transition is electrifying competitive positioning, as OEMs without ribbon sourcing agreements face 15-20 point margin compression against integrated suppliers.
MIIT's tier-one energy efficiency benchmarks are hardening procurement gatekeeping. Utilities now require third-party verification of core losses under GB 20052-2020 Appendix C test protocols before contract award. The policy is concentrating orders toward manufacturers with in-house silicon steel slitting and annealing capabilities. Eastern coastal provinces are responding fastest, with Shanghai and Zhejiang power bureaus rejecting non-compliant bids regardless of price.
County-level power bureaus are consolidating transformer procurement through provincial e-commerce platforms. State Grid's ECP 2.0 system now handles 90% of distribution unit tendering, replacing decentralized municipal purchasing. This channel compression is squeezing regional distributors and forcing manufacturers to maintain direct platform compliance teams. The shift is most visible in Shandong and Henan, where 2024 transaction volumes through centralized portals exceeded legacy channels.
China Transformer Market Segmentation
Transformer procurement in China diverges sharply between backbone infrastructure and edge distribution, with voltage class and installation environment dictating entirely different supplier qualifications. Understanding these segment boundaries clarifies why integrated steel producers dominate UHV contracts while regional assemblers retain county-level distribution share.
Product Type:
Capital intensity and certification requirements separate winners from casualties across product tiers.
- Power Transformer:Units rated 110kV and above handle bulk transmission between generation bases and load centers. State Grid's ±1100kV DC corridor buildouts concentrate demand in western provinces where converter transformers face 8-10 month test bay queues at Xian and Suzhou facilities.
- Distribution Transformer:10kV-35kV units step voltage down for final delivery. County-level power bureaus in Henan and Shandong are replacing millions of S9-era units with GB-tier amorphous-core models under rural grid modernization mandates.
- Instrument Transformer:Current and voltage sensors for metering and protection systems. SAMR calibration certifications create margin concentration for specialized manufacturers serving utility substation automation projects.
- Auto Transformer:Single-winding designs for voltage ratios below 3:1 in interconnected grid applications. Limited deployment in China's radial transmission architecture restricts this segment to specific intertie configurations.
Power transformers lead on scale; distribution transformers lead on replacement velocity.
End User:
Procurement authority concentration varies dramatically across customer types, from centralized state utility tenders to fragmented industrial specifications.
- Utilities:State Grid Corporation and China Southern Power Grid account for the majority of high-voltage procurement through centralized ECP 2.0 platforms. Their 14th Five-Year Plan ultra-high voltage mandates compress supplier qualification timelines while GB 20052-2020 efficiency tiers harden technical gatekeeping.
- Industrial:Steel, cement, and chemical plants operate captive substations requiring 35kV-220kV step-down capacity. MEE's embodied carbon tracking is retrofitting lifecycle accounting into procurement scoring, advantaging suppliers with verified low-carbon steel sourcing.
- Commercial:Data centers and high-rise developments in Shanghai and Shenzhen drive dry-type transformer demand. MIIT's smart grid demonstration zones are piloting sensor-embedded units with edge analytics for load forecasting.
- Residential:Urban renewal projects and new district construction in eastern coastal provinces specify compact pad-mounted units. Provincial peak-shaving incentives are coupling retired EV battery storage with distribution substations.
Utilities dominate absolute volume; commercial applications are climbing fastest on digitalization premiums.
Installation Type:
Environmental exposure and space constraints determine insulation technology and enclosure standards.
- Indoor:Dry-type cast resin units for commercial buildings and underground substations. MEE's fluorinated gas restrictions are accelerating SF6 phase-outs in 220kV+ applications, though 12-18 month qualification timelines for natural ester alternatives create near-term friction.
- Outdoor:Oil-immersed tanks with weatherproof housings for utility substations and industrial yards. Salt-fog corrosion ratings separate suppliers serving Guangdong and Fujian offshore wind platforms from standard onshore product lines.
- Substation:Integrated transformer-switchgear assemblies in dedicated utility facilities. UHV test bay scarcity at Xian and Suzhou creates 8-10 month bottlenecks for 1000kV unit verification.
- Pole-mounted:Compact single-phase units for rural distribution in Henan and Shandong. County-level procurement consolidation through State Grid's ECP 2.0 platform has displaced decentralized municipal purchasing.
Outdoor installations anchor current deployment; indoor specifications are gaining share on urban density and SF6 restrictions.
Voltage Level:
Technical complexity and supplier qualification barriers escalate nonlinearly with voltage class.
- Low Voltage:Below 1kV units for final distribution and small commercial applications. Amorphous metal core technology from Hitachi Metals and Qingdao Yunlu enables no-load losses 70% below conventional grain-oriented steel in this tier.
- Medium Voltage:1kV-35kV range covering industrial substations and urban distribution. State Grid's Jiangsu subsidiary has standardized amorphous units for all new 10kV urban deployments since efficiency tier tightening.
- High Voltage:35kV-230kV transmission and large industrial interconnections. Baowu Steel and Shougang control over 80% of domestic high-permeability grain-oriented silicon steel supply, creating input bottlenecks during procurement surges.
- Extra High Voltage:230kV and above for ultra-high voltage backbone corridors. Only Xian and Suzhou facilities can perform full-load heat-run verification for 1000kV units, concentrating supplier capability.
Extra high voltage commands the steepest margin premiums; medium voltage offers the broadest supplier base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled electrical engineering talent clusters along the eastern seaboard where ultra-high voltage corridors terminate and GB standards enforcement is strictest.
Guangdong Province
Offshore wind platform deployments in the Pearl River Delta drive demand for 66kV collector transformers with salt-fog corrosion ratings. Provincial energy bureaus enforce MEE's embodied carbon tracking on steel sourcing for substation projects. Shenzhen and Guangzhou host the densest concentration of smart grid demonstration zones testing sensor-embedded units.
Jiangsu Province
State Grid's Jiangsu subsidiary standardized amorphous-core distribution transformers for all new 10kV urban deployments since efficiency tier tightening took effect. MIIT's tier-one benchmarks require third-party verification of core losses under GB 20052-2020 protocols before contract award. Nanjing and Suzhou anchor the Yangtze River Delta manufacturing corridor where UHV test bay capacity concentrates.
Shandong Province
Rural grid modernization mandates replacement of millions of S9-era distribution units with GB-tier amorphous-core models across county-level power bureaus. Procurement consolidation through State Grid's ECP 2.0 platform displaced decentralized municipal purchasing in 2024. Jinan and Qingdao host ribbon sourcing agreements with domestic amorphous alloy suppliers.
Sichuan-Chongqing Region
Western generation bases feed ultra-high voltage DC lines linking to eastern load centers, pulling demand for converter transformers and shunt reactors. SAMR enforces compulsory certification for electromagnetic compatibility on all units entering utility substations. Chengdu and Chongqing serve as logistics hubs for equipment staging toward Tibetan and Yunnan hydro projects.
Zhejiang Province
Hangzhou and Ningbo power bureaus reject non-compliant bids regardless of price under the strictest GB 20052-2020 enforcement outside Shanghai. Digital twin integration pilots in MIIT smart grid zones open software-attach revenue streams for hardware OEMs. Provincial peak-shaving incentives couple retired EV battery storage with distribution substations in urban renewal districts.
China Transformer Market Competitive Environment
The competitive structure tilts toward integrated steel producers with captive silicon steel capacity. State utility procurement through centralized platforms compresses supplier qualification timelines while hardening technical gatekeeping around GB efficiency tiers. Three archetypes dominate: integrated steel-electrical conglomerates with lamination control, regional assemblers with county-level distribution relationships, and specialized UHV test bay operators. Capacity expansion and backward integration into core material production represent the dominant competitive moves.
Within the integrated conglomerate tier, TBEA Co., Ltd. and XJ Electric Co., Ltd. exemplify players with in-house silicon steel slitting and annealing capabilities that absorb compliance costs without margin erosion. CHINT Electric Co., Ltd. occupies a position representing deep distribution into county-level power bureaus. These three entities anchor the competitive landscape as procurement consolidation through State Grid's ECP 2.0 platform squeezes regional distributors and forces direct platform compliance investments.
| Leading Market Players |
|---|
| CHINT Electric Co., Ltd. |
| AISITE Transformer Co., Ltd. |
| TBEA Co., Ltd. |
| XJ Electric Co., Ltd. |
| Shandong Electrical Engineering Group Co., Ltd. |
| China XD Group |
| CEEG |
| Jinpan Technology Co., Ltd. |
| Taikai Group |
| Others |
Value Chain & Pricing Dynamics
Grain-oriented silicon steel spot indices cascade through transformer manufacturing into three distinct pricing tiers. Baowu Steel and Shougang's 80% domestic supply control concentrates input cost leverage among integrated producers, while tier-2 assemblers absorb margin compression from yen-denominated amorphous alloy ribbon volatility.
Pricing Analysis
Product-plus-service bundling separates transformer pricing into equipment-only, installation-inclusive, and lifecycle-maintenance contract structures. Premium tiers command spreads through GB 20052-2020 tier-one certification and captive silicon steel production, while economy positioning faces cost compression from centralized ECP 2.0 platform procurement. County-level power bureaus exhibit acute price sensitivity on distribution units; UHV converter transformer buyers prioritize qualification speed over procurement cost.
Supply Chain Analysis
GB standard certification and SAMR electromagnetic compatibility approval gate entry into State Grid's supplier roster. China sources high-permeability grain-oriented silicon steel from Baowu and Shougang mills, while amorphous alloy ribbon draws from Hitachi Metals and Qingdao Yunlu. Single-source vulnerability concentrates in UHV test bay capacity at Xian and Suzhou facilities. Distribution runs through State Grid's ECP 2.0 centralized platform, displacing legacy municipal purchasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's transformer market offers margin expansion pathways through backward integration into silicon steel and premium-tier GB certification positioning. Amorphous-core technology transitions and digital twin attach rates concentrate value capture among integrated manufacturers.
For Market Incumbents: Lock in amorphous alloy ribbon supply agreements with Qingdao Yunlu or Hitachi Metals before county-level modernization waves accelerate. Expand captive silicon steel slitting capacity to absorb GB 20052-2020 compliance costs without margin erosion, while maintaining direct ECP 2.0 platform compliance teams as channel consolidation squeezes regional distributors. For New Entrants and Emerging Players: Enter via offshore wind platform specifications in Guangdong and Fujian, where salt-fog corrosion ratings create qualification gaps versus established onshore product lines. Target 66kV collector transformer deployments with localized corrosion testing partnerships, leveraging provincial energy bureau procurement autonomy outside State Grid's centralized high-voltage tenders. For Investors and Strategic Acquirers: Consolidation pressure builds where GB tier-one certification investments exceed typical amortization cycles and UHV test bay queues stretch beyond contract award windows. Mid-cap manufacturers with in-house silicon steel annealing but limited ultra-high voltage track records represent acquisition targets. Watch for MEE embodied carbon enforcement tightening material sourcing requirements faster than domestic steel capacity expands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Steel | Captive lamination supply absorbs GB 20052-2020 efficiency tier compliance costs without margin compression. |
| Amorphous Core Technology Licensing | Ribbon sourcing agreements with Hitachi Metals or Qingdao Yunlu electrify competitive positioning against grain-oriented steel incumbents. |
| Digital Twin Platform Development | Sensor-embedded units with edge analytics open software-attach revenue streams in MIIT smart grid demonstration zones. |
| UHV Test Bay Capacity Expansion | Xian or Suzhou facility investment breaks 8-10 month qualification bottlenecks for 1000kV converter transformer contracts. |
| Offshore Wind Certification Investment | Salt-fog corrosion rating capabilities capture Guangdong and Fujian coastal array demand outside standardized onshore product lines. |
Study Parameters
Multiple input streams — utility procurement officer interviews, silicon steel mill technical consultations, and county-level power bureau planning documents — were reconciled against SAMR certification databases and State Grid ECP 2.0 tender records. Secondary validation drew from MIIT industrial policy filings, MEE embodied carbon tracking protocols, and GB standard revision notices. Bottom-up unit deployment estimates across voltage classes were triangulated with top-down infrastructure investment flows from provincial energy bureaus.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include voltage level, installation environment, core material technology, and end-user procurement authority concentration. CAGRs were derived from infrastructure deployment schedules and replacement cycle dynamics. Forecast inputs incorporated dual carbon policy enforcement intensity and amorphous alloy supply elasticity.
Inputs from State Grid planning subsidiaries and provincial power bureaus were available through the study window; gaps in county-level S9-era unit inventory data introduce uncertainty bands around replacement velocity assumptions. Forecasts reflect documented infrastructure commitment schedules and regulatory enforcement trajectories. A model refresh is warranted upon material change in MEE embodied carbon tracking implementation pace or GB standard revision cadence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Smart Transformer Market
Transformers
Transformer Oil Market
Transformers
Distribution Transformer Market
Transformers
Transformer Core Market
Transformers
United Arab Emirates Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Current Transformer Market
Transformers
Global Transformer Market
Transformers
United States Power Transformer Market
Transformers
Transformer Steel Market
Transformers
Green Transformer Market
Transformers
Rail Traction Transformers Market
Transformers
Rectifier Transformers Market
Transformers
Air Cooled Transformer Market
Transformers
Phase-Shifting Transformer Market
Transformers
Transformer Bobbin Market