
 Industrial Control Transformers Market | 2026-2036
Industrial Control Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Control Transformers Market Intelligence
The emergence of specialized machine builders and system integrators for niche automation tasks is restructuring the traditional customer base for industrial control transformers. Siemens leverages its extensive portfolio in industrial automation to offer integrated solutions, bundling transformers with its PLCs and drives. Rockwell Automation specializes in control systems for complex manufacturing environments, embedding its components within its Allen-Bradley ecosystem. Schneider Electric competes on energy management and efficiency within control panel designs.
An industrial control transformer is an isolation transformer engineered to supply consistent, low-voltage power to control circuits within machinery. These devices are specifically designed to step down higher supply voltages and manage the high inrush currents associated with energizing electromagnetic components like relays and solenoids. Dry-type transformers lead the market due to their inherent safety features and minimal maintenance requirements in industrial settings. While process automation represents a large, established application, demand from renewable power plants is expanding rapidly for grid interface and control functions.
Product design and market access are governed by stringent safety and performance standards, including UL 5085 in the United States and the CE marking requirements under the Low Voltage Directive in Europe. These regulations dictate construction, insulation integrity, and testing protocols to ensure operator safety and equipment reliability. Consequently, manufacturers must prioritize designs that meet both regional electrical codes and global ISO standards. Stakeholder decisions will increasingly balance transformer performance with compliance to evolving energy efficiency regulations.
Market Dynamics
The industrial control transformer market is shaped by the dual pressures of advancing automation and tightening safety regulations. Accelerating investment in robotics and complex machinery creates baseline demand, while mandates like ISO 13849 force electrical system upgrades, embedding new transformers into modern control panels.
Growth Catalysts
- Industrial Modernization:Government-backed factory upgrade initiatives, particularly in Germany's manufacturing sector, drive consistent demand for control components to support new automation and robotics systems.
- Renewable Energy Infrastructure:The rapid build-out of solar and wind power generation facilities creates new applications for control transformers in grid interface panels, switchgear, and plant control systems.
- Machine Safety Mandates:The enforcement of stringent standards, including UL 5085 in the United States and the CE Low Voltage Directive in Europe, compels OEMs to integrate compliant transformers into their equipment designs.
Market Restraints
- Input Cost Volatility:Price fluctuations for core raw materials, specifically high-grade copper for windings and electrical steel for cores, directly impact manufacturer margins and create pricing instability.
- Threat of Functional Integration:Advanced variable frequency drives (VFDs) and programmable logic controllers (PLCs) increasingly incorporate built-in, low-voltage power supplies, eliminating the need for a separate control transformer in certain applications.
- Regulatory Compliance Overhead:The cost and complexity of designing and certifying products to meet divergent regional standards, such as UL and CE, present a significant barrier for smaller manufacturers.
Strategic Opportunities
- Smart Transformer Development:Embedding IIoT sensors for voltage monitoring, temperature tracking, and predictive maintenance analysis creates a new tier of premium, high-value products for critical applications.
- Expansion in Emerging Economies:Industrialization in markets like India and Mexico, which are upgrading their manufacturing infrastructure, offers significant greenfield opportunities outside of traditionally dominant regions.
- Energy Efficiency Standards:The introduction of new energy efficiency regulations for electrical components provides an opportunity to market premium transformers that offer lower operational costs and improved performance.
Industry Challenges
- Legacy System Compatibility:Integrating modern control transformers with aging industrial machinery often requires extensive and costly rewiring and panel modifications, slowing down the replacement cycle.
- Certification Delays:The lengthy and rigorous testing protocols required to obtain UL and CE certifications for new or modified transformer designs can create significant bottlenecks in product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Control Transformers Market |
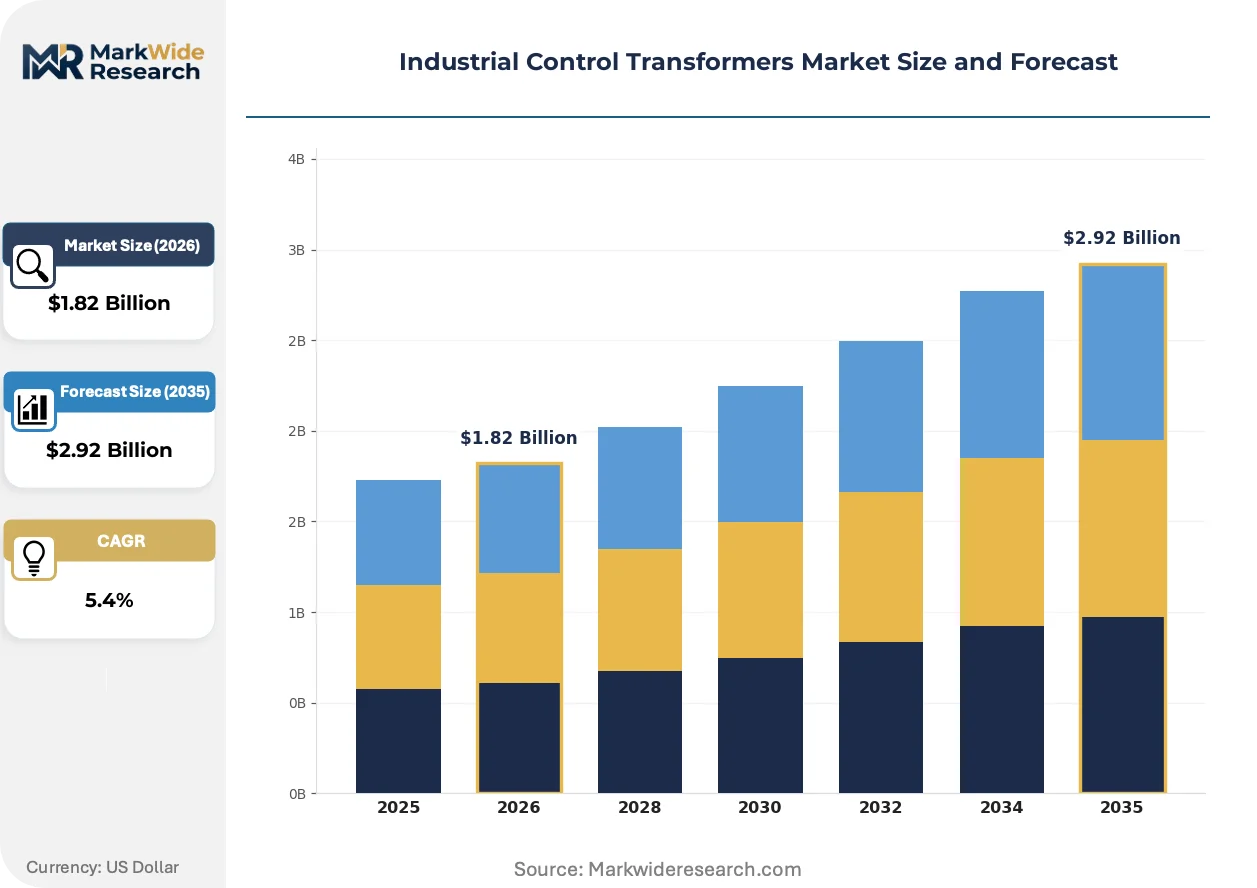
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry-Type, Oil-Immersed, Cast Resin, High-Frequency, Toroidal Technology: Magnetic Core, Electrostatic, Laminated Core, Ferrite Core, Air Core Application: Process Automation, Power Distribution, Renewable Power Plants, Manufacturing Equipment, Robotics Systems End User Industry: Utility Providers, Chemical Processing, Transportation Infrastructure, Aerospace Manufacturers, Food Processing |
| Companies Covered | Eaton, Rockwell Automation, ABB, Hubbell, Emerson Electric, Siemens, GE Vernova, MCI Transformer Corporation, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Control Transformers Market Strategic Shifts & Innovations
Product design is evolving toward greater environmental resilience and embedded intelligence. This shift is reshaping how transformers are specified and integrated into larger control systems, moving away from standalone components toward system-level performance criteria driven by new regulations and customer expectations.
Fully encapsulated transformers, which use an epoxy potting compound to seal the core and windings, offer superior protection against moisture, shock, and vibration. End-users in harsh industrial settings like food processing and chemical manufacturing are rapidly adopting these designs for enhanced reliability. This robust, sealed construction is overtaking traditional open-frame designs in applications where operational uptime is critical.
In Europe, the Low Voltage Directive (LVD) and its associated CE marking requirements dictate fundamental design principles for electrical safety. This regulation forces manufacturers to validate insulation integrity, thermal management, and short-circuit protection through rigorous testing protocols defined by harmonized standards. The entire supply chain, from material suppliers to original equipment manufacturers, must adapt product specifications to ensure compliance for market access.
A notable behavioral change involves the move from purchasing individual components to specifying fully engineered and integrated control panels. This disrupts the business model for traditional component distributors, who now compete with system integrators and specialized machine builders that offer complete, pre-wired solutions. This trend is most advanced in the German machine tool industry, where end-users prioritize turnkey systems.
Industrial Control Transformers Market Segmentation
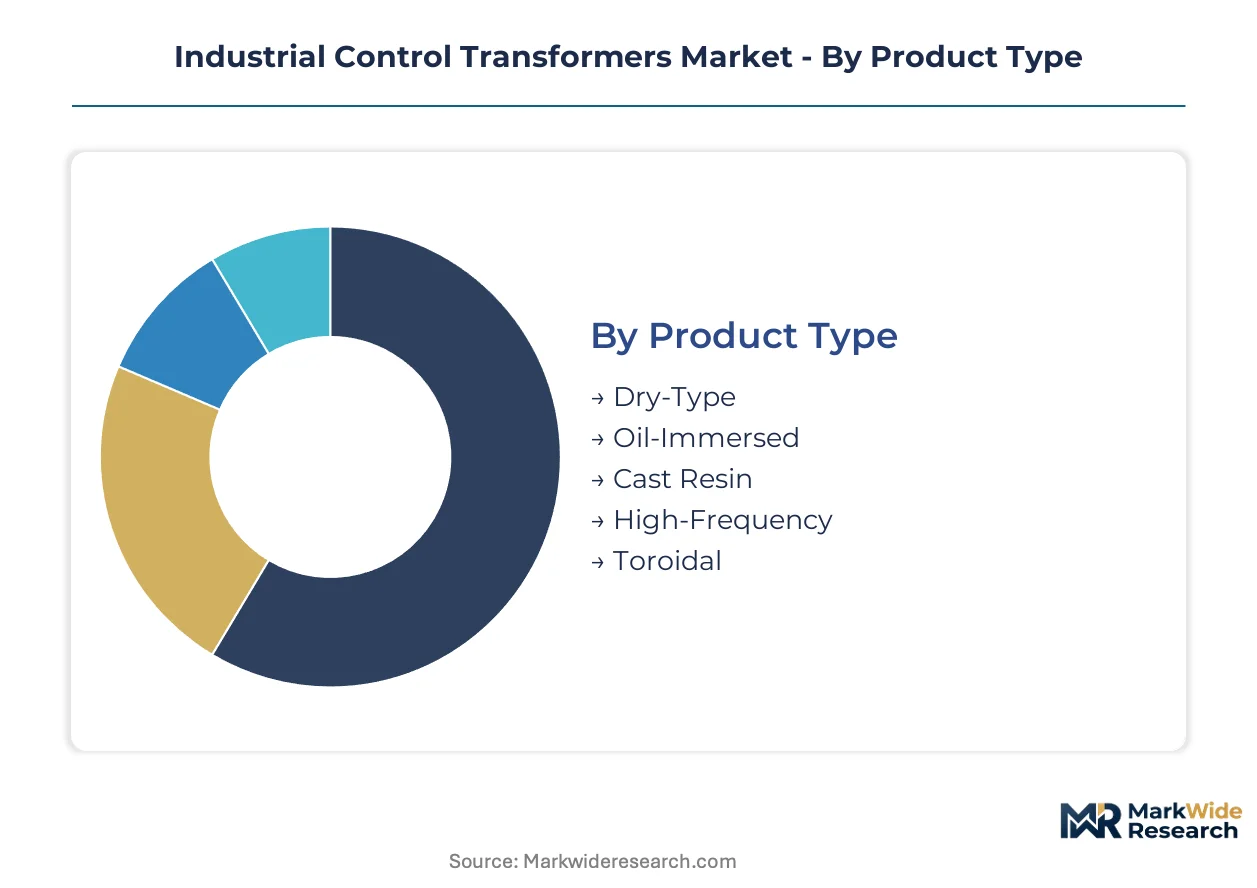
Segmentation provides a granular view of the industrial control transformers market, dissecting demand and supply dynamics across distinct product types, technologies, applications, and end-user industries. Understanding these categories is essential for identifying specific growth pockets and evolving customer needs within the broader industrial automation landscape.
Product Type:
Supply concentration in industrial control transformers is evident across various product types, each optimized for specific operational demands and environmental conditions.
- Dry-Type:Dry-type transformers utilize air or solid insulation instead of liquid, preventing fire hazards and simplifying installation in enclosed spaces. Demand concentrates in manufacturing facilities across Germany, where strict safety regulations and high operational uptime are paramount.
- Cast Resin:Cast resin transformers encapsulate windings in epoxy resin, providing superior protection against moisture, dust, and mechanical stress in harsh environments. Applications in chemical processing plants in the United States increasingly adopt these for enhanced reliability and reduced maintenance in corrosive atmospheres.
- Oil-Immersed:These transformers use mineral oil for cooling and insulation, suitable for high-power applications requiring efficient heat dissipation.
- High-Frequency:Designed for higher operational frequencies, these compact units are critical in advanced power electronics and specialized industrial machinery.
- Toroidal:Toroidal transformers feature a ring-shaped core, offering high efficiency, low leakage flux, and a compact footprint for sensitive electronic controls.
Today's leader: Dry-Type. Tomorrow's challenger: Cast Resin.
Technology:
The underlying technology determines not only performance characteristics but also the manufacturing complexity and overall cost tier of industrial control transformers.
- Magnetic Core:Magnetic core transformers rely on ferromagnetic materials to efficiently couple magnetic flux between primary and secondary windings. This foundational technology underpins most industrial control applications in established manufacturing hubs like Japan, ensuring stable power delivery to PLCs.
- Laminated Core:Laminated core technology uses thin, insulated steel laminations to form the core, minimizing eddy current losses and improving efficiency. Widespread adoption in European industrial automation systems, especially within Germany's machine tool industry, prioritizes energy efficiency and reliability.
- Electrostatic:These transformers utilize capacitance to transfer energy, finding niche applications where galvanic isolation is not strictly required.
- Ferrite Core:Ferrite core transformers are preferred for high-frequency operations due to their low losses and compact size in switch-mode power supplies.
- Air Core:Air core transformers, lacking a ferromagnetic core, offer excellent linearity and are used in specialized high-frequency or high-current sensing applications.
Ferrite Core technology represents the fastest-growing trajectory, driven by the expanding integration of high-frequency power electronics in industrial controls.
Application:
Specific application requirements dictate the design and performance parameters for industrial control transformers, influencing demand patterns across diverse industrial sectors.
- Process Automation:Control transformers supply stable low-voltage power to PLCs, sensors, and actuators that manage continuous industrial processes. This application remains a cornerstone in chemical and pharmaceutical manufacturing across the United States, supporting complex and automated production lines.
- Renewable Power Plants:These transformers provide control power for grid interface equipment, switchgear, and monitoring systems within solar and wind energy facilities. Investment in new renewable infrastructure across India and China is driving significant demand for these specialized control applications.
- Power Distribution:Control transformers enable safe and reliable operation of switchgear and circuit breakers within industrial power distribution networks.
- Manufacturing Equipment:They ensure consistent voltage for machine tools, assembly lines, and various production machinery, supporting operational stability.
- Robotics Systems:Robotics systems rely on dedicated control transformers to power their intricate motion control and sensing components, ensuring precision and safety.
While Process Automation maintains its dominance, Renewable Power Plants applications are gaining share fastest, reflecting global energy transition efforts.
End User Industry:
The diverse needs of various end-user industries shape the specific requirements for industrial control transformers, from ruggedness to precision.
- Utility Providers:Utility providers integrate control transformers into substations, grid infrastructure, and power generation facilities for reliable control circuit operation. Modernization efforts in Europe's energy grids, driven by renewable integration, create consistent demand for robust and compliant transformers.
- Food Processing:These industries require control transformers with high ingress protection and corrosion resistance to withstand frequent washdowns and chemical exposure. Strict hygiene standards and automation investments in food and beverage facilities across the United Kingdom drive demand for specialized, encapsulated units.
- Chemical Processing:Chemical processing plants require highly durable and often explosion-proof control transformers for hazardous environments.
- Transportation Infrastructure:Control transformers support signaling systems, traffic management, and operational controls within rail, road, and port infrastructure.
- Aerospace Manufacturers:Aerospace manufacturing uses precision control transformers for automated assembly, testing equipment, and critical environmental controls.
Food Processing is currently on the steepest expansion trajectory, driven by automation and stringent safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's highly skilled engineering workforce and advanced manufacturing capabilities anchor significant demand for industrial control transformers across Europe. Industrial modernization initiatives and stringent safety mandates consistently drive market expansion. This region, along with other key industrial powerhouses, demonstrates varied growth trajectories influenced by local regulatory frameworks and industrial development.
Germany
Accelerating investments in process automation and robotics systems create strong demand for industrial control transformers in Germany. The enforcement of ISO 13849 for machine safety compels manufacturers to upgrade electrical control panels. The machine tool industry in Bavaria and Baden-Württemberg continually integrates new compliant transformers into advanced production lines.
United States
Process automation remains a cornerstone application for industrial control transformers in the United States. UL 5085 certification is a mandatory requirement for electrical control equipment, ensuring product safety and performance. Manufacturing facilities across the Midwest, particularly in states like Michigan and Ohio, are modernizing infrastructure, increasing demand for reliable power solutions.
China
The rapid build-out of renewable energy infrastructure fuels demand for control transformers in China. The country's dual carbon goals promote investment in solar and wind power generation facilities. Industrial clusters in the Yangtze River Delta region are adopting advanced control systems for grid interface and plant operations.
India
Industrialization and factory upgrade initiatives drive consistent demand for control components in India's manufacturing sector. The Production Linked Incentive (PLI) scheme encourages domestic manufacturing, stimulating the need for automation equipment. Major industrial hubs like Pune and Chennai are expanding their manufacturing capabilities, requiring robust control power solutions.
Industrial Control Transformers Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the industrial control transformers market, creating a tiered competitive structure. Major players leverage extensive portfolios to offer integrated solutions, bundling transformers with broader automation components. Strategic partnerships and portfolio diversification are common competitive moves, as companies seek to address evolving customer needs and regulatory requirements across various industrial applications.
Within the integrated solutions tier, Siemens AG, a German multinational conglomerate, exemplifies a broad approach, bundling transformers with its PLCs and drives. Rockwell Automation, a US-based company, anchors its offerings within the Allen-Bradley ecosystem, specializing in control systems for complex manufacturing environments. Schneider Electric, a French multinational, occupies a strong position by focusing on energy management and efficiency within control panel designs, serving a wide array of industrial and commercial clients.
| Leading Market Players |
|---|
| Eaton |
| Rockwell Automation |
| ABB |
| Hubbell |
| Emerson Electric |
| Siemens |
| GE Vernova |
| MCI Transformer Corporation |
| Schneider Electric |
| Others |
Cost & Logistics Intelligence
Germany's highly skilled engineering workforce, particularly in Bavaria, influences pricing tiers across industrial control transformers, reflecting labor-cost differentials in high-precision manufacturing. This expertise contributes to the premium commanded by specialized, compliant units.
Pricing Analysis
The bundled-vs-unbundled service split significantly impacts pricing for industrial control transformers. While per-unit transactional pricing remains common, integrated solutions often command value-based pricing due to their comprehensive nature. UL 5085 certification level and customization for specific machinery serve as key price differentiation drivers. Pricing pressure stems from input cost volatility for high-grade copper and electrical steel. System integrators are less price-sensitive due to turnkey project needs, while smaller original equipment manufacturers are highly sensitive to unit costs.
Supply Chain Analysis
Regional distribution centers, particularly those in Europe and North America, form critical nodes in the industrial control transformer supply chain. Geographic supply concentration includes Germany, China, and the United States as key manufacturing hubs. High-grade copper for windings and electrical steel for cores are critical raw material dependencies. Commodity price volatility for these raw materials poses a structural supply chain risk. Distribution runs through specialized industrial distributors and direct sales channels to large original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, driven by the shift towards fully encapsulated transformers for enhanced reliability in harsh industrial settings. End-users prioritize robust, compliant solutions over basic functionality.
For Market Incumbents: Extend existing portfolios by integrating smart transformer functionalities for predictive maintenance and remote monitoring. Deepen partnerships with system integrators to offer bundled solutions, countering the threat of functional integration from advanced drives. Invest in R&D for advanced materials to mitigate raw material price volatility. Leverage established channel control through robust distribution networks.
For New Entrants and Emerging Players: CE marking requirements under the Low Voltage Directive in Europe open a window for specialized manufacturers focused on compliance. Target niche applications in renewable power plants and food processing, which require specialized designs. Emerging economies like India, upgrading their manufacturing infrastructure, represent a penetrable segment. Focus on energy-efficient designs that meet evolving regulations as a primary go-to-market angle.
For Investors and Strategic Acquirers: Diversified industrial conglomerates are the most active acquirers in this space, seeking to broaden their automation portfolios. The market demonstrates long-term viability, supported by ongoing industrial modernization and safety mandates across key regions. Mid-sized specialists with strong intellectual property in fully encapsulated or high-frequency designs represent attractive acquisition archetypes. Increased merger and acquisition activity among system integrators signals consolidation pressure and is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Smart Transformer R&D | Siemens can gain market share by offering IIoT-enabled products for critical industrial applications. |
| Pursue Strategic Partnerships | Rockwell Automation can integrate specialized transformer technology into its Allen-Bradley ecosystem offerings. |
| Certify Products for UL 5085 | Smaller manufacturers can access the United States market by meeting stringent electrical safety standards. |
| Target Renewable Energy Projects | Schneider Electric can leverage its energy management expertise in solar and wind power facilities. |
| Invest in New Manufacturing Capacity | Companies can reduce lead times and improve cost efficiency in key regions like Germany. |
Research Approach
Direct dialogue with plant engineers, procurement leads at original equipment manufacturers, system integrators, and regulatory compliance specialists informed primary data collection. This was triangulated with secondary sources including national manufacturing statistics, electrical safety standards (UL 5085, CE Low Voltage Directive), and company financial reports. The analysis employed both bottom-up and top-down data validation methodologies.
The quantitative model generated market size and growth projections across the analysis window, segmented by product type, technology, application, and end-user industry. Compound Annual Growth Rates were derived from historical trends and projected demand for automation components. Key inputs included investment forecasts for industrial robotics and renewable energy infrastructure build-out.
Revisions become necessary when significant shifts in global trade policies or raw material supply occur. Forecasts reflect assumptions documented at the time of publication. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Europe Smart Transformers Market
Transformers
Europe Oil Filled Distribution Transformer Market
Transformers
Middle-East Smart Transformer Market
Transformers
United States Power Transformer Market
Transformers
United States Transformer Market
Transformers
Step Up/Down Transformers Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
High Frequency Transformer Market
Transformers
HVDC Converter Transformers Market
Transformers
India Power Transformer Market
Transformers
Air Cooled Transformer Market
Transformers
Green Transformer Market
Transformers
North America Dry Type Transformer Market
Transformers
North America Smart Transformers Market
Transformers
Liquid-Immersed Transformers Market
Transformers
High Voltage (35-550 KV) Power Transformer Market