
 Transformer Oil Market | 2026-2036
Transformer Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Transformer Oil Market Analysis
IEC 60296 certification for mineral insulating oils is reorganizing supplier eligibility across the transformer oil value chain. Nynas AB leverages its naphthenic base oil integration to sustain European supply continuity for utilities requiring high-grade dielectric fluids. Exxon Mobil Corporation anchors North American availability through controlled refining capacity and established utility procurement channels. APAR Industries dominates South Asian distribution with localized blending operations and technical service networks.
Transformer oil is a refined hydrocarbon or synthetic dielectric fluid formulated to insulate windings, suppress corona discharge, and dissipate thermal energy in oil-immersed electrical apparatus, with typical viscosity grades ranging from 8 cSt to 12 cSt at 40°C and minimum interfacial tension thresholds above 40 mN/m to ensure oxidation stability. Mineral oil occupies the largest volume share due to entrenched utility specifications and cost structures, though ester-based oils are gaining fastest as fire-safety regulations tighten around indoor and offshore substation deployments. Power transformers command the deepest margin pools because of long fill volumes and technical support requirements, while renewable energy end users represent an emerging demand vector for biodegradable and synthetic formulations.
The US EPA governs mineral oil spill containment and disposal protocols under the Clean Water Act and SPCC regulations, while the EU F-Gas Regulation and REACH framework constrain certain synthetic fluid chemistries and mandate environmental compatibility disclosures. India's BIS enforces IS 335 standards for new and reclaimed insulating oils, shaping product acceptance criteria for domestic manufacturers and importers. Stakeholders must track evolving fire-safety codes and carbon-accounting rules that will determine which fluid chemistries retain access to utility procurement programs.
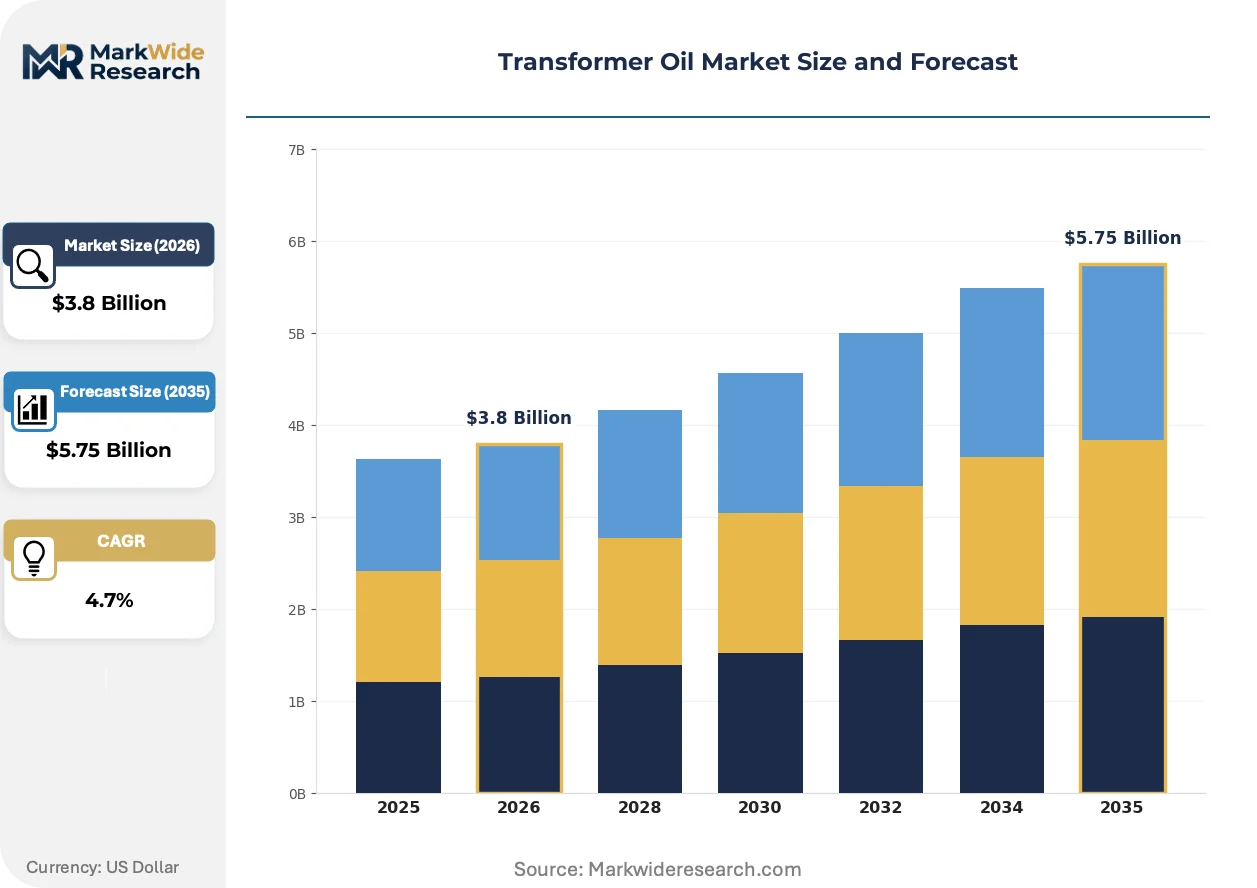
Market Dynamics
Grid modernization programs across Asia-Pacific utilities are accelerating transformer replacement cycles, forcing suppliers to align product portfolios with IEC 60296 and ASTM D3487 certification requirements while managing naphthenic base oil supply constraints.
Growth Catalysts
- Transmission infrastructure expansion:India and China are deploying ultra-high voltage corridors that require high-grade mineral insulating oils for power transformers above 400 kV.
- REACH environmental mandates:The EU F-Gas Regulation is phasing down certain synthetic chemistries, creating pull-through demand for biodegradable ester alternatives in indoor substations.
- Fire-safety code tightening:Offshore wind installations in the North Sea are specifying synthetic ester fluids to meet IEC 61000 thermal runaway containment protocols.
Market Restraints
- Naphthenic crude concentration:Refining capacity for transformer-grade base oils concentrates in a limited number of European and North American facilities, exposing buyers to geographic supply risk.
- Mineral oil substitution ceiling:Ester-based fluids face viscosity-performance tradeoffs at sub-zero temperatures that limit adoption in Nordic and Siberian transmission networks.
- Reclaiming infrastructure gaps:India's BIS IS 335 reclaimed oil standards lack enforcement mechanisms, suppressing circular economy participation among smaller utilities.
Strategic Opportunities
- Renewable integration white space:Solar and wind farm developers in the United States are procuring biodegradable dielectric fluids to satisfy EPA spill prevention countermeasure requirements.
- Distribution transformer channel:Technical service networks that bundle fluid testing with scheduled maintenance are capturing recurring revenue from municipal utilities.
- Dual-carbon policy alignment:China's MIIT industrial efficiency mandates are creating procurement preferences for low-carbon intensity refining processes in state-grid tenders.
Industry Challenges
- Certification timeline compression:IEC 60296 fourth-edition testing protocols for oxidation stability and corrosive sulfur are extending product qualification cycles by 12-18 months for reformulated blends.
- Dielectric fluid analysis talent scarcity:Utilities face shortages of laboratory technicians trained in dissolved gas analysis and furanic compound interpretation for predictive maintenance programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transformer Oil Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Silicones, Ester-Based Oils, Biodegradable Oils Application: Power Transformers, Distribution Transformers, Voltage Regulators, Reactors End User: Utilities, Industrial, Commercial, Renewable Energy Packaging Type: Cylinders, Drums, Bulk Containers, Bottles |
| Companies Covered | Ergon, Calumet Specialty Products Partners, Shell, Sinopec Lubricant Company, Exxon Mobil Corporation, Nynas AB, APAR Industries, Cargill, PetroChina Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transformer Oil Market Emerging Trajectories
Synthetic ester chemistry and digital monitoring integration are bifurcating product architectures, while regulatory jurisdictions compete to set the dominant environmental standard for dielectric fluid disposal and carbon accounting.
Natural and synthetic ester formulations are bifurcating the product landscape between legacy mineral oil systems and next-generation fire-safe alternatives. Offshore wind developers in the North Sea are specifying synthetic esters for platform substations to satisfy insurance underwriter requirements. This technology is bifurcating supplier R&D budgets toward biodegradable chemistries that command 40-60% price premiums over conventional grades.
The EU F-Gas Regulation and REACH Article 33 disclosure requirements are constraining certain synthetic aromatic chemistries used in high-temperature transformer applications. Manufacturers are reformulating blends to eliminate restricted substances ahead of 2027 phase-down deadlines. Power transformers above 100 MVA rating face the steepest compliance burden, with several European utilities now requiring full material composition certificates in procurement specifications.
Integrated fluid monitoring subscriptions are displacing discrete laboratory testing contracts among North American municipal utilities. Sensor-embedded transformers transmit dissolved gas data to cloud analytics platforms, enabling condition-based maintenance scheduling. This shift is most advanced in California and Texas, where wildfire liability exposure has accelerated investment in predictive failure detection for distribution infrastructure.
Transformer Oil Market Segmentation
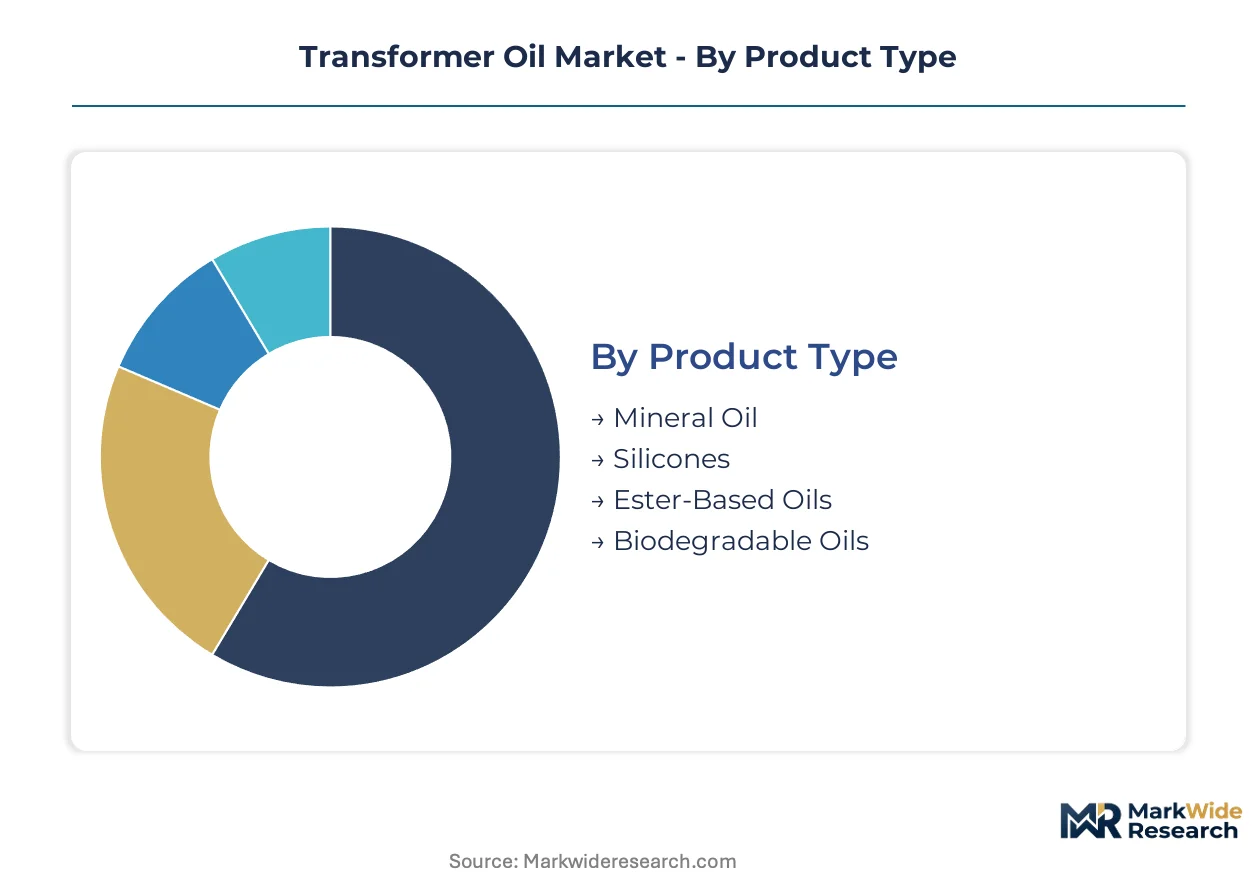
Segmentation in transformer oils reveals divergent substitution economics across chemistries and application scales. Procurement specifications from IEC 60296 and ASTM D3487 create tiered entry barriers that reshape supplier positioning by product grade and end-use sophistication.
Product Type:
Substitution pressure from fire-safety regulations and carbon-accounting rules is fragmenting demand across dielectric fluid chemistries, with mineral oil facing the steepest regulatory headwinds.
- Mineral Oil:Refined naphthenic or paraffinic hydrocarbon base stocks dominate installed capacity due to entrenched utility specifications and cost structures. Demand concentrates in India's transmission expansion and China's ultra-high voltage corridors where IS 335 and GB standards maintain mineral oil preference for outdoor installations above 400 kV.
- Ester-Based Oils:Synthetic and natural ester formulations deliver fire-safety performance meeting IEC 61000 thermal containment protocols. Offshore wind developers in the North Sea and indoor substation operators across Germany and the Netherlands are specifying ester fluids to satisfy insurance underwriter requirements and REACH environmental mandates.
- Silicones:Polydimethylsiloxane chemistry provides thermal stability in high-temperature applications where mineral oil oxidation limits service life. Niche adoption persists in specialized industrial transformers requiring extended maintenance intervals.
- Biodegradable Oils:Vegetable-derived base stocks with synthetic performance additives address EPA spill prevention requirements for solar and wind farm installations in California and Texas.
Mineral oil anchors the volume base while ester-based oils gain share at the steepest rate.
Application:
Fill volume and technical service intensity create distinct margin architectures across transformer scale classes.
- Power Transformers:Oil-immersed units above 100 MVA rating require 10,000-100,000 liter fills with dissolved gas analysis monitoring protocols. Procurement concentrates in state-grid tenders across India, China, and the United States where long-term technical support contracts accompany fluid supply.
- Distribution Transformers:Smaller fill volumes below 1,000 liters dominate unit shipments but compress per-unit margins. Municipal utilities in Germany and Japan are bundling fluid testing subscriptions with scheduled maintenance to capture recurring revenue streams.
- Voltage Regulators:Tap-changing equipment in transmission networks requires dielectric fluids with precise viscosity control across temperature cycling. Demand tracks grid modernization timelines in South Korea and Australia.
- Reactors:Shunt and series reactor applications specify high oxidation stability for continuous duty cycles. Procurement aligns with HVDC corridor deployments in Brazil and Saudi Arabia.
Power transformers command the deepest margin pools while distribution transformers drive shipment volume.
End User:
Procurement sophistication and regulatory exposure segment customers by compliance burden and technical specification authority.
- Utilities:State-owned and investor-owned grid operators specify certified dielectric fluids through multi-year framework agreements. India's CEA and China's State Grid enforce BIS IS 335 and GB standards that lock in supplier qualification timelines.
- Industrial:Manufacturing facilities and data centers operate captive transformer fleets with shorter replacement cycles. Fire-safety codes in EU member states are accelerating ester adoption for indoor installations.
- Commercial:Building infrastructure and retail distribution networks prioritize first-cost minimization over lifecycle fluid performance. Procurement channels through electrical contractors with limited technical specification involvement.
- Renewable Energy:Solar and wind farm developers face EPA spill prevention countermeasure requirements in the United States and EU environmental compatibility disclosures. Biodegradable fluid specifications are emerging as a procurement preference in California and Germany.
Utilities anchor demand stability while renewable energy developers are expanding most quickly.
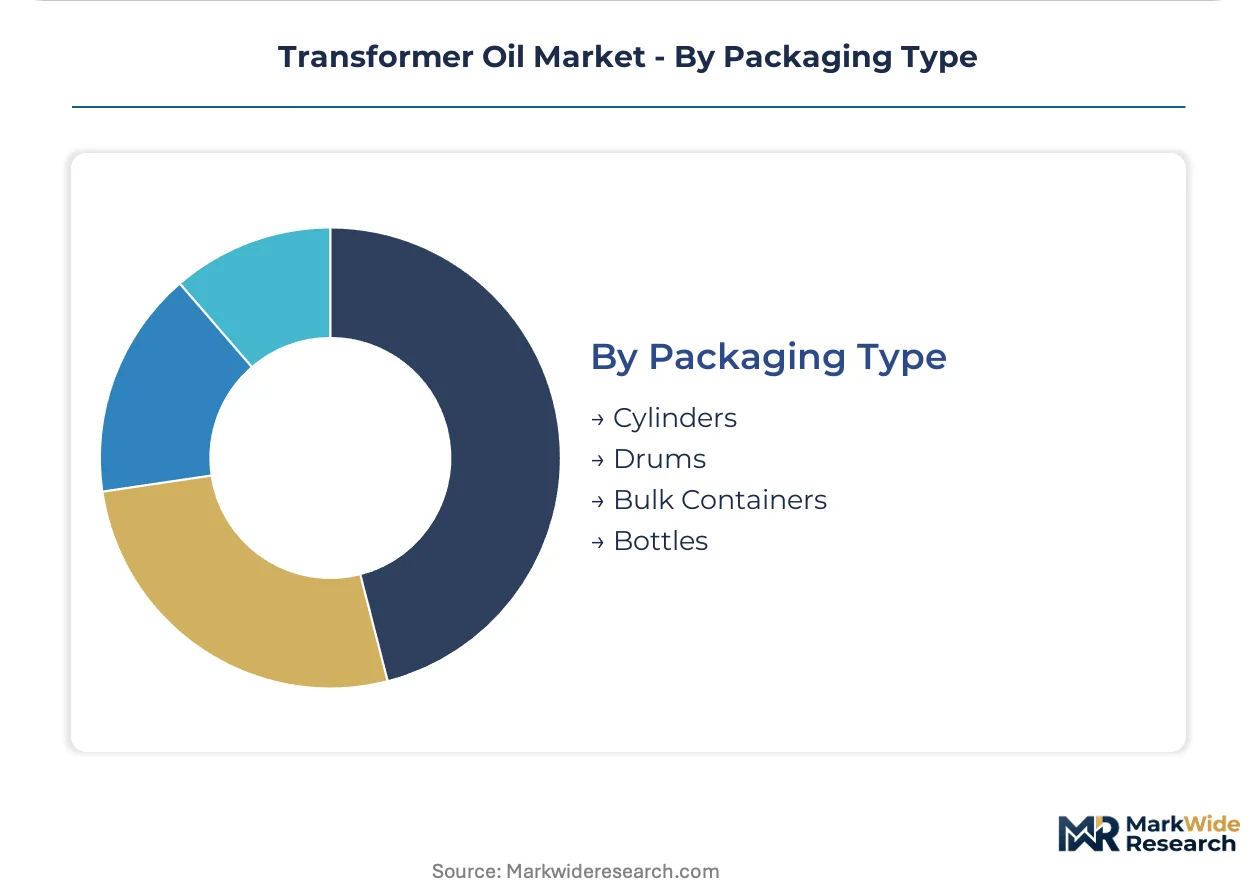
Packaging Type:
Logistics economics and contamination risk shape packaging selection by customer scale and geographic access.
- Bulk Containers:Tank truck and ISO tank deliveries serve power transformer OEMs and large utility filling operations with dedicated storage infrastructure. Concentrated demand in China, India, and the United States reflects transmission manufacturing scale.
- Drums:200-liter steel drums remain the standard for distribution transformer servicing and industrial maintenance operations. Procurement channels through electrical distributors with regional stocking points.
- Cylinders:Pressurized containers address specialized applications requiring moisture exclusion during transport. Limited adoption in laboratory testing and small-batch reclamation operations.
- Bottles:Small-format packaging supports field sampling, quality control testing, and emergency top-off scenarios. Demand fragments across service contractor networks.
Bulk containers dominate value concentration while drums capture the widest customer reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grid modernization incentives and transmission infrastructure programs are concentrating transformer oil procurement across five national markets where regulatory frameworks and utility investment cycles intersect most directly.
United States
EPA spill prevention countermeasure requirements are accelerating biodegradable fluid adoption for solar and wind farm installations across California and Texas. FERC transmission reliability mandates drive dissolved gas analysis monitoring subscriptions among municipal utilities. Houston and Los Angeles anchor the largest utility procurement clusters for power transformer maintenance programs.
China
MIIT industrial efficiency mandates and State Grid ultra-high voltage corridor deployments sustain mineral oil preference for outdoor installations above 400 kV. GB standards maintain entrenched specifications that lock in supplier qualification timelines. Yangtze River Delta manufacturing zones concentrate domestic blending capacity for transmission infrastructure expansion.
India
CEA transmission expansion programs and BIS IS 335 certification requirements are reorganizing supplier eligibility for naphthenic base oil formulations. Maharashtra and Gujarat host localized blending operations that dominate South Asian distribution networks. Technical service bundling with scheduled maintenance is capturing recurring revenue from state-grid tenders.
Germany
EU F-Gas Regulation phase-down deadlines and REACH Article 33 disclosure requirements are constraining synthetic aromatic chemistries for high-temperature applications. ECHA environmental mandates accelerate ester adoption for indoor substations across the Netherlands border region. North Rhine-Westphalia utilities now require full material composition certificates in procurement specifications above 100 MVA ratings.
Brazil
National grid operator transmission reliability programs and HVDC corridor deployments are shaping reactor fluid specifications for continuous duty cycles. ANVISA-equivalent environmental protocols for spill containment are emerging in parallel with renewable integration targets. São Paulo industrial clusters anchor the largest captive transformer fleet maintenance operations in Latin America.
Transformer Oil Market Vendor Landscape
Player mix skews toward integrated petroleum refiners with captive naphthenic base oil supply, creating tiered competition between global majors and regional blenders. Three strategic archetypes dominate: European naphthenic specialists with backward integration into crude sourcing, North American integrated refiners with controlled pipeline logistics, and South Asian formulators with localized technical service networks. Competitive moves concentrate on certification timeline acceleration and predictive maintenance service bundling rather than capacity expansion.
Within the integrated refiner tier, Exxon Mobil Corporation anchors North American availability through established utility procurement channels, while Nynas AB exemplifies European naphthenic base oil integration for high-grade dielectric fluid continuity. APAR Industries occupies a position as the dominant South Asian distributor with localized blending operations. Ergon and Calumet Specialty Products Partners represent independent specialty refiners competing on technical specification flexibility rather than scale.
| Leading Market Players |
|---|
| Ergon |
| Calumet Specialty Products Partners |
| Shell |
| Sinopec Lubricant Company |
| Exxon Mobil Corporation |
| Nynas AB |
| APAR Industries |
| Cargill |
| PetroChina Company Limited |
| Others |
Supply Flow & Price Mechanics
Ester-based fluid substitution for mineral oil in offshore wind and indoor substations is simultaneously redrawing supply geography toward European biorefineries and compressing pricing power among naphthenic base oil refiners locked into legacy utility contracts. This chemistry shift forces buyers to absorb 40-60% price premiums while suppliers struggle to reconcile ester feedstock volatility with long-term procurement frameworks.
Pricing Analysis
Certification level under IEC 60296 and ASTM D3487 creates the primary spread between qualified and unqualified dielectric fluid suppliers. Three-tier pricing structure across premium ester formulations, certified mineral grades, and reclaimed oils reflects oxidation stability testing costs and corrosive sulfur compliance burdens. Pricing pressure stems from naphthenic crude concentration in limited European and North American refining facilities. Municipal utilities in distribution transformer channels exhibit highest price sensitivity, while offshore wind developers accept premium positioning for fire-safety performance.
Supply Chain Analysis
Naphthenic crude availability from Venezuela, Russia, and select North Sea fields anchors transformer-grade base oil production. Refining capacity concentrates in Sweden, the United States, and Belgium, with downstream distribution running through tank truck and ISO tank networks serving power transformer OEMs. Single-source vulnerability persists where European utilities depend on Baltic Sea transit routes for specialty naphthenic shipments. Regional blending operations in India and China complete the downstream structure for localized technical service delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across fire-safety codes and carbon-accounting rules is spawning addressable niches for specialized formulators who can navigate certification complexity faster than integrated refiners.
For Market Incumbents: Shield core utility relationships by accelerating IEC 60296 fourth-edition qualification timelines for reformulated blends before smaller competitors secure state-grid tender eligibility. Backward integration into captive naphthenic sourcing in the Baltic region mitigates geographic supply risk from crude concentration. Channel control through bundled fluid testing subscriptions locks in recurring revenue against independent service contractors. For New Entrants and Emerging Players: Lead with biodegradable ester formulations targeting solar and wind farm developers in California and Texas facing EPA spill prevention countermeasure requirements. Renewable energy end users represent the most penetrable segment given limited incumbent technical service presence outside utility channels. A go-to-market angle combining fluid supply with dissolved gas analysis training programs addresses talent scarcity among smaller developers. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down deadlines reshape the acquisition landscape toward formulators with REACH-compliant synthetic ester portfolios and material composition disclosure capabilities. Long-term viability favors mid-cap specialists with laboratory infrastructure for oxidation stability testing rather than pure blending operations. The signal to watch is BIS enforcement intensity for India's IS 335 reclaimed oil standards, which would validate circular economy business models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphthenic Crude Sourcing | Secures supply continuity for European utilities facing Baltic transit bottlenecks. |
| Certification Acceleration for IEC 60296 Fourth Edition | Compresses 12-18 month qualification cycles before competitors reformulate. |
| Biodegradable Ester Formulation Development | Captures EPA-driven procurement from solar and wind farm developers. |
| Technical Service Network Expansion | Bundles fluid testing subscriptions to lock in municipal utility recurring revenue. |
| Reclaimed Oil Infrastructure Investment | Positions for BIS IS 335 enforcement in India's circular economy transition. |
Methodological Framework
Desk research of IEC and ASTM standard documentation, utility procurement specifications, and EPA regulatory filings preceded structured interviews with utility planning officers, transformer OEM procurement leads, dielectric fluid technical directors, and reclamation facility operators. Secondary validation drew from customs trade data, state-grid tender announcements, and SEC filings from listed petroleum refiners. Bottom-up volume estimates from transformer installation databases were triangulated against top-down market sizing from refining capacity disclosures.
Variance decomposition across product chemistry, application scale, and end-user regulatory exposure shaped the analytical framework throughout the forecast period. Segmentation dimensions modeled include dielectric fluid type, transformer capacity tier, packaging format, and regional certification requirements. CAGRs were derived from utility capital expenditure trajectories and renewable energy interconnection queues. Industry-specific inputs incorporated naphthenic base oil supply forecasts and REACH substance restriction timelines.
The analysis sits within stated boundaries; outcomes outside sustained transmission infrastructure investment in India and China or accelerated EU F-Gas phase-down schedules would require recalibration. Forecasts reflect assumptions regarding BIS enforcement mechanisms and MIIT industrial efficiency mandate continuity. Practitioners should keep alternative scenarios live as fire-safety code adoption rates and carbon-accounting rule finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Latin America Transformer Market
Transformers
North America Smart Transformers Market
Transformers
Green Transformer Market
Transformers
Cast Resin Transformers Market
Transformers
Renewable Energy Transformer Market
Transformers
United States Power Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Traction Transformer Market
Transformers
HVDC Converter Transformers Market
Transformers
Distribution Transformer Market
Transformers
North America Dry Type Transformer Market
Transformers
Current Transformer Market
Transformers
United States Large Power Transformer Market
Transformers
Asia-Pacific Transformer Market
Transformers
Transformer Core Market
Transformers
Transformer Steel Market