
 Asia-Pacific Transformer Market | 2026-2036
Asia-Pacific Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Transformer Market Outlook
Utility procurement dominance is collapsing as industrial captive power and data center operators expand transformer orders. ABB Ltd. leverages its regional manufacturing footprint to serve utility tenders across Southeast Asia. Mitsubishi Electric Corporation anchors premium gas-insulated transformer supply for urban substations in Japan and South Korea. Siemens AG competes on digital transformer portfolios that integrate grid monitoring software.
A transformer is a static electromagnetic device that transfers electrical energy between circuits through mutual induction, typically operating at frequencies of 50 or 60 Hz with voltage ratings spanning 11 kV to 765 kV or higher for grid applications. Its primary industrial purpose is to step up voltage for efficient long-distance transmission and step down voltage for safe distribution to end users. Power transformers capture the largest value pool given their role in inter-regional transmission corridors, while distribution transformers face margin compression from standardization despite volume leadership. Smart transformer technology is expanding fastest as grid operators deploy sensors and tap changers for real-time load management.
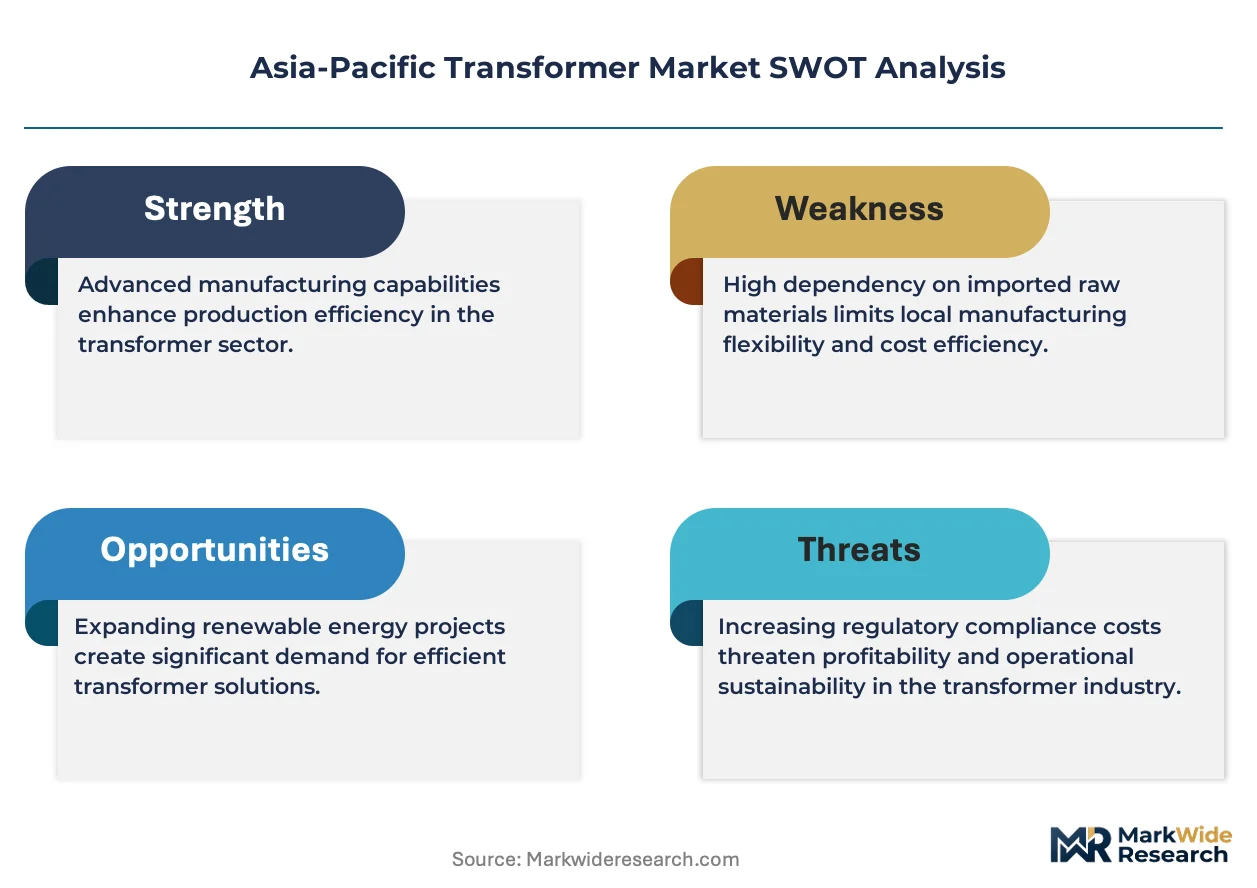
India's CEA mandates efficiency standards for distribution transformers under national electricity regulations, while China's GB standards and MIIT directives enforce loss-reduction targets and smart-grid compatibility. Japan's METI promotes amorphous metal core adoption through efficiency benchmarking programs. Stakeholders must monitor how divergent national efficiency regimes affect cross-border product certification costs and localization requirements.
Market Dynamics
China's dual carbon goals and India's PLI scheme for power equipment are restructuring domestic manufacturing requirements across the Asia-Pacific transformer landscape. These policy frameworks are forcing localization of supply chains and accelerating the phase-out of high-loss transformer designs.
Growth Catalysts
- India's transmission expansion programs:State-owned Power Grid Corporation and state utilities are tendering for high-capacity inter-regional transformers to integrate renewable zones with load centers.
- CEA efficiency mandates:India's Central Electricity Authority enforces loss-reduction standards for distribution transformers, compelling fleet replacement and smart-meter compatibility upgrades.
- Southeast Asian rural electrification:Indonesia's Perusahaan Listrik Negara and Vietnam's EVN are extending grid infrastructure to remote provinces, driving procurement of compact distribution units.
Market Restraints
- Grain-oriented electrical steel concentration:China and Japan control over 80% of global GOES supply, exposing transformer manufacturers to input cost volatility and export quota risks.
- MIIT localization requirements:China's Ministry of Industry and Information Technology mandates domestic content ratios for grid-connected equipment, complicating foreign vendor participation in state tenders.
- Amorphous metal core substitution limits:Despite METI efficiency benchmarking in Japan, amorphous alloy transformers face cost premiums and core fragility that constrain deployment beyond urban substations.
Strategic Opportunities
- Data center power infrastructure:Hyperscale operators in Singapore and Sydney are procuring gas-insulated transformers with integrated monitoring for mission-critical uptime requirements.
- Australian grid-scale solar integration:The Australian Energy Market Operator's renewable connection standards create demand for high-voltage step-up transformers with dynamic thermal rating capabilities.
- Smart tap changer convergence:Integration of power electronics with conventional magnetic cores enables real-time voltage regulation for distributed solar penetration in Thailand and the Philippines.
Industry Challenges
- Transformer design engineering scarcity:Specialized electromagnetic simulation expertise for EHV units above 400 kV concentrates at a handful of regional engineering centers in Japan and South Korea.
- GB standard certification timelines:China's national standards body requires extended type-testing protocols for imported equipment, delaying market entry by 12-18 months for non-domestic manufacturers.
- Legacy SCADA integration complexity:Digital transformer deployments must interface with decades-old control systems at Indian and Indonesian substations, requiring custom protocol adapters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Transformer Market |
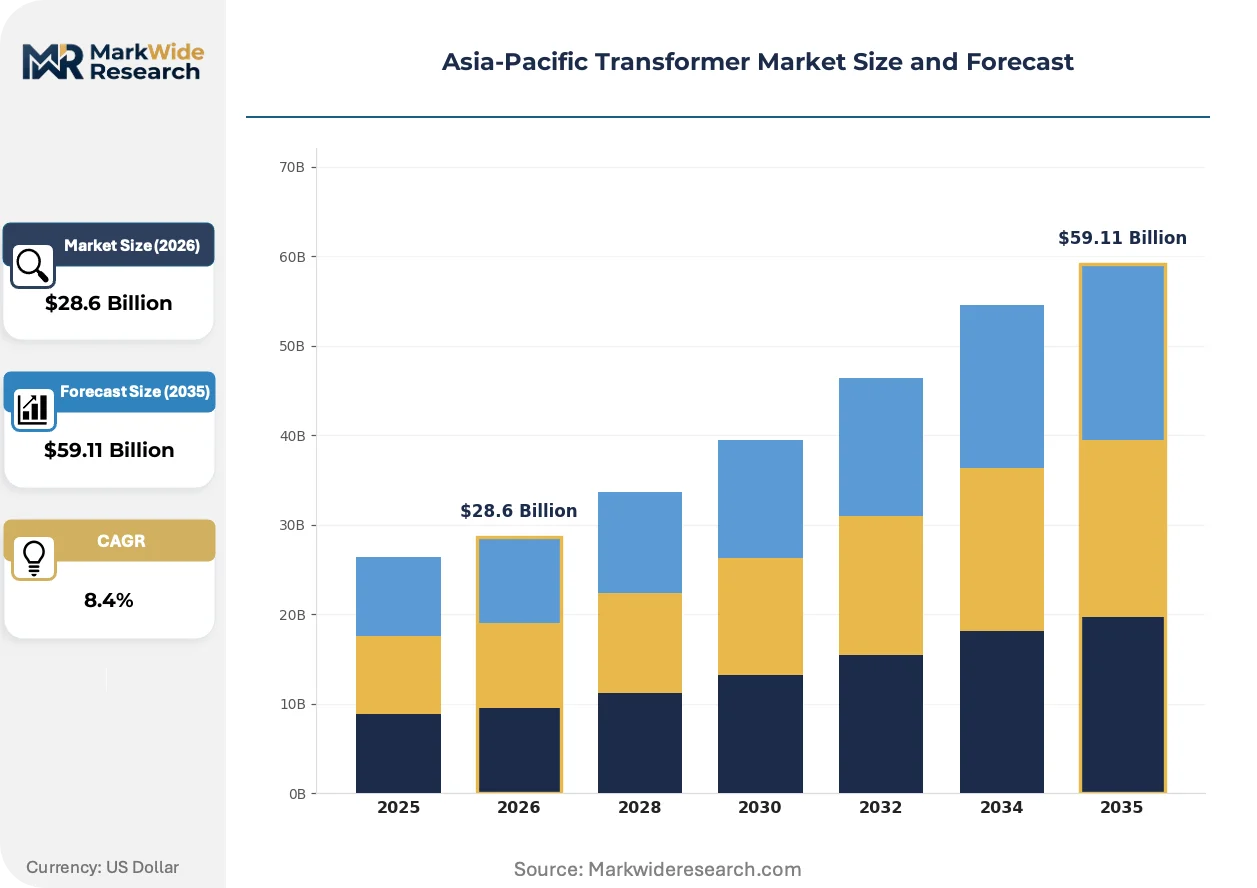
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Transformer, Distribution Transformer, Specialty Transformer, Instrument Transformer End User: Utilities, Industrial, Commercial, Residential Technology: Conventional, Smart, Renewable-Compatible, Oil-Insulated Application: Energy Distribution, Power Generation, Industrial Processing, Renewable Energy |
| Companies Covered | Siemens AG, ABB Ltd., General Electric Company, Mitsubishi Electric Corporation, Schneider Electric SE, Hitachi Energy Ltd., Toshiba Corporation, CG Power and Industrial Solutions Ltd., Hyosung Heavy Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Transformer Market Strategic Shifts
Electrification of transport and heavy industry is expanding transformer duty cycles beyond traditional utility baseload patterns. This demand stress is accelerating materials innovation and control system intelligence across the Asia-Pacific supply base.
Natural ester insulating fluids derived from seed oils are fragmenting the mineral oil dominance in distribution transformers. Japanese utilities led early adoption for fire-safety-critical indoor installations. Australian network operators now specify biodegradable fluids for coastal and agricultural zones where spill containment is costly. The technology is fragmenting procurement specifications as national regulators diverge on fluid compatibility with legacy gaskets and bushings.
China's GB/T standards for smart-grid equipment interoperability are mandating embedded sensors and digital twins for transformers above 110 kV. The MIIT directive forces domestic manufacturers to integrate temperature, dissolved gas, and partial discharge monitoring. State Grid Corporation of China is consolidating supplier lists to vendors with certified digital platforms, compressing margins for purely mechanical producers.
Industrial captive power operators in India and Vietnam are unbundling transformer procurement from EPC contracts. Reliance Industries, Tata Steel, and Formosa Plastics Group now issue standalone tenders for high-specification units with 25-year service guarantees. This disintermediation of integrated project vendors is visible most acutely in western India's chemical corridor and Vietnam's northern industrial zones near Haiphong.
Asia-Pacific Transformer Market Segmentation
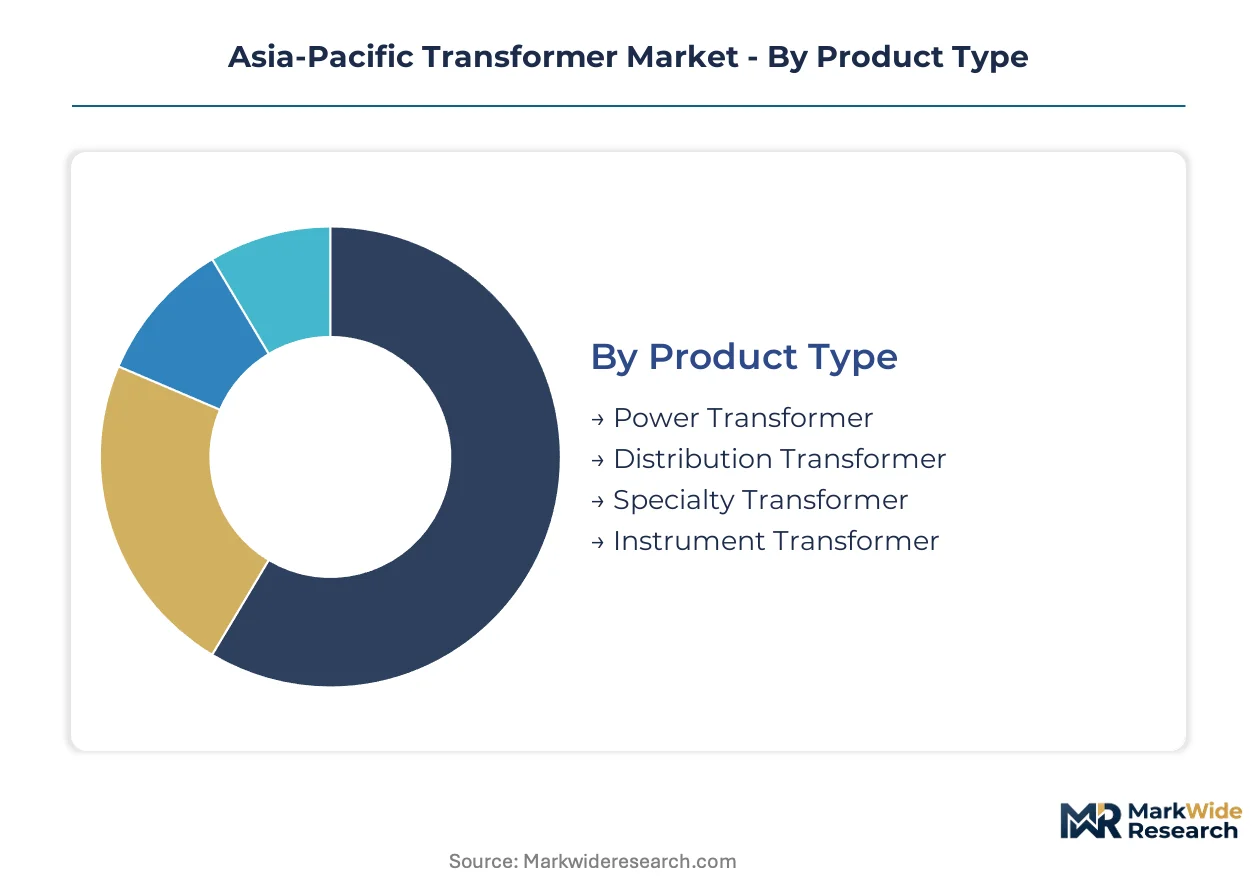
Transformer procurement patterns diverge sharply across voltage classes and end-use applications. Understanding these fault lines reveals where technology substitution pressures concentrate and where incumbent designs retain structural advantages.
Product Type:
Power transformers face intensifying substitution risk from modular solid-state alternatives in data center and industrial captive applications, while distribution units confront margin erosion from standardization.
- Power Transformer:High-capacity electromagnetic units rated above 33 kV for inter-regional transmission corridors. Demand concentrates in India's transmission expansion programs and China's ultra-high-voltage backbone projects, where State Grid Corporation tenders specify 765 kV and above for renewable zone integration.
- Distribution Transformer:Step-down units operating at 11-33 kV for last-mile grid connectivity. Procurement volumes dominate Southeast Asian rural electrification drives led by Indonesia's Perusahaan Listrik Negara and Vietnam's EVN, though CEA efficiency mandates in India compress supplier margins.
- Specialty Transformer:Custom-designed units for furnace, rectifier, and traction applications with non-standard impedance profiles.
- Instrument Transformer:Voltage and current sensing devices for metering and protection systems in substation automation.
Distribution transformers retain volume leadership across the Asia-Pacific footprint; smart-enabled power transformers hold the steepest expansion curve.
End User:
Customer-type segmentation exposes divergent procurement sophistication, with industrial operators unbundling transformer supply from EPC contracts faster than utility incumbents.
- Utilities:State-owned transmission and distribution companies operating under regulated return frameworks. India's Power Grid Corporation and Australia's network operators dominate tender volumes, though MIIT localization requirements in China constrain foreign vendor participation.
- Industrial:Captive power operators in chemical, steel, and semiconductor manufacturing. Reliance Industries and Tata Steel in western India's chemical corridor now issue standalone specifications with 25-year service guarantees, bypassing integrated project vendors.
- Commercial:Office complexes, retail centers, and healthcare facilities requiring compact indoor installations.
- Residential:Single-unit deployments for apartment blocks and gated communities with standardized kVA ratings.
Utilities anchor absolute procurement tonnage; industrial end users are climbing the fastest as captive power expansion accelerates.
Technology:
Technology tiers stratify by digital maturity, with conventional magnetic cores facing displacement from sensor-embedded alternatives in premium grid applications.
- Smart:Sensor-integrated units with embedded temperature, dissolved gas, and partial discharge monitoring. China's GB/T standards mandate digital twins for transformers above 110 kV, compressing margins for mechanical-only producers.
- Conventional:Electromechanical designs without embedded monitoring, still dominant in cost-sensitive rural electrification.
- Renewable-Compatible:Dynamic thermal rating units for solar and wind farm step-up applications with fluctuating load profiles.
- Oil-Insulated:Mineral oil or natural ester fluid designs for fire-safety-critical indoor installations, with Japanese utilities leading amorphous metal core adoption.
Conventional technology retains installed-base dominance; smart transformer platforms are expanding most quickly as grid digitization mandates proliferate.
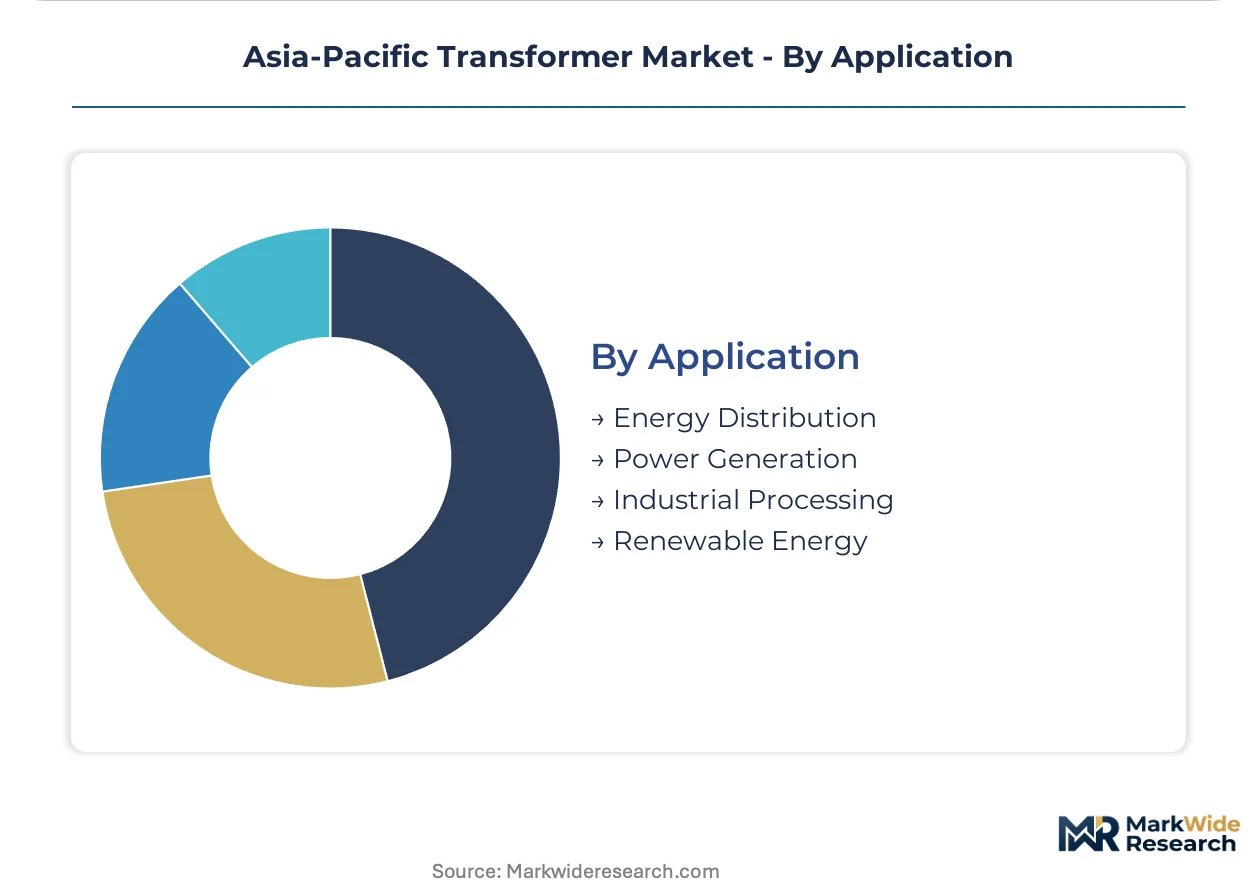
Application:
Application segmentation tracks voltage transformation stages, with renewable energy integration creating specification divergence from legacy baseload patterns.
- Energy Distribution:Grid infrastructure for voltage step-down to commercial and residential endpoints. Australia's network operators specify biodegradable insulating fluids for coastal agricultural zones.
- Renewable Energy:Solar farm and wind park interconnection requiring dynamic thermal rating capabilities. The Australian Energy Market Operator's connection standards drive procurement of high-voltage step-up units.
- Power Generation:Generator step-up transformers for thermal, hydro, and nuclear plant output.
- Industrial Processing:Heavy manufacturing loads with non-linear power quality requirements.
Energy distribution captures the largest installed base; renewable energy applications hold the steepest growth trajectory as grid-scale solar penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The State Grid Corporation of China's ultra-high-voltage backbone interconnects the world's largest transformer procurement market. This grid infrastructure underwrites regional demand concentration.
China
State Grid Corporation tenders specify 765 kV and above for renewable zone integration across western provinces. MIIT mandates domestic content ratios for grid-connected equipment, complicating foreign vendor participation. The Yangtze River Delta manufacturing cluster supplies digital transformer platforms with embedded sensor arrays.
India
Power Grid Corporation and state utilities tender high-capacity inter-regional units to connect solar parks in Rajasthan with load centers. CEA enforces loss-reduction standards for distribution transformers, compelling fleet replacement. Western India's chemical corridor sees Reliance Industries and Tata Steel issuing standalone specifications with 25-year service guarantees.
Japan
Tokyo Electric Power and regional utilities deploy gas-insulated transformers for premium urban substations. METI promotes amorphous metal core adoption through efficiency benchmarking programs. The Kanto industrial basin concentrates engineering expertise for EHV units above 400 kV.
Australia
The Australian Energy Market Operator's renewable connection standards drive procurement of high-voltage step-up transformers with dynamic thermal rating capabilities. Network operators specify biodegradable insulating fluids for coastal agricultural zones. Grid-scale solar projects in Queensland and New South Wales accelerate step-up transformer orders.
Vietnam
EVN extends grid infrastructure to remote northern provinces near Haiphong, driving compact distribution unit procurement. Industrial captive power expansion at Formosa Plastics Group facilities creates demand for high-specification units. The northern industrial zones unbundle transformer procurement from EPC contracts faster than utility incumbents.
Asia-Pacific Transformer Market Competitive Environment
Concentration sits with diversified electrical equipment conglomerates holding integrated manufacturing and digital platform capabilities. The vendor base stratifies across three tiers: premium gas-insulated specialists, scale-driven power transformer fabricators, and regional distribution unit assemblers. Two strategic archetypes dominate — Japanese-Korean engineering-centric players and European digital-integrated platforms. Competitive moves center on localization partnerships to satisfy MIIT content requirements and smart technology licensing to meet China's GB/T interoperability mandates.
Among diversified electrical equipment conglomerates, Siemens AG and ABB Ltd. occupy positions exemplifying the digital-integrated platform archetype, while Mitsubishi Electric Corporation anchors the premium gas-insulated specialist tier. Hitachi Energy Ltd. represents the engineering-centric engineering heritage common to Japanese-Korean competitors. These three companies illustrate how vendor positioning stratifies across technology tiers rather than geographic origin alone.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| General Electric Company |
| Mitsubishi Electric Corporation |
| Schneider Electric SE |
| Hitachi Energy Ltd. |
| Toshiba Corporation |
| CG Power and Industrial Solutions Ltd. |
| Hyosung Heavy Industries |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between State Grid Corporation and domestic manufacturers lock in grain-oriented electrical steel access while capping price volatility for ultra-high-voltage transformer tiers. These arrangements bind input security to procurement visibility across China's dual carbon deployment timeline.
Pricing Analysis
Volume-discount tiering separates 765 kV ultra-high-voltage units from standard 110-220 kV power transformers and mass-market distribution units. Price differentiation rests on amorphous metal core certification and smart-sensor integration under GB/T standards. Cost compression in distribution tiers intensifies as CEA efficiency mandates standardize loss-reduction specifications. Industrial captive operators show lowest price sensitivity due to 25-year service guarantee requirements.
Supply Chain Analysis
Strategic stockpiling of grain-oriented electrical steel dominates over just-in-time approaches given China's export quota volatility and Japan's Nippon Steel concentration. Manufacturing draws from China, Japan, and South Korea for core lamination and winding operations. Single-source vulnerability concentrates in GOES supply where two producers control regional output. Distribution runs through state utility tender channels and industrial EPC unbundling in India's chemical corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital service layers including predictive maintenance platforms and dissolved gas monitoring subscriptions expand faster than hardware unit sales across Asia-Pacific grid modernization programs. This service-attach dynamic restructures vendor economics toward recurring revenue streams.
For Market Incumbents: Secure backward integration into grain-oriented electrical steel through joint ventures with Nippon Steel or Baowu Steel to defend against input cost volatility. Anchor smart transformer certification under evolving GB/T and CEA standards to lock out mechanical-only competitors from state tender lists.
For New Entrants and Emerging Players: Differentiate on natural ester fluid compatibility and coastal corrosion resistance for Australian agricultural zone specifications. Target Vietnam's northern industrial zones near Haiphong where Formosa Plastics Group and emerging semiconductor fabs unbundle procurement from integrated EPC vendors.
For Investors and Strategic Acquirers: Engineering-centric specialists with EHV simulation capabilities above 400 kV represent consolidation targets as design talent concentrates in Japan's Kanto basin. Watch for MIIT localization requirement tightening as the inflection signal triggering foreign-domestic partnership premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Integration | GB/T mandates embed temperature and partial discharge monitoring above 110 kV, compressing mechanical-only margins. |
| Natural Ester Fluid Transition | Australian network operators specify biodegradable insulation for coastal agricultural spill-containment zones. |
| Amorphous Metal Core Scale-Up | METI efficiency benchmarking accelerates urban substation deployment despite cost premiums. |
| Digital Twin Platform Licensing | State Grid Corporation consolidates supplier lists to vendors with certified interoperability platforms. |
| GOES Supply Joint Venture | Domestic content ratios under MIIT directives force foreign manufacturers into steel partnership structures. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with utility planning officers, transformer procurement leads at state grid corporations, EPC project managers, and aftermarket service heads. Secondary validation drew from CEA regulatory filings, MIIT directive releases, State Grid Corporation tender databases, and customs trade records for grain-oriented electrical steel. Bottom-up unit shipment estimates triangulated against top-down grid investment forecasts.
Across the analysis window, projections model voltage class segmentation, end-user archetype behavior, and technology tier adoption curves. CAGRs derive from weighted average of historical investment trajectories and policy-mandated replacement schedules. Forecast inputs incorporate renewable interconnection standards from the Australian Energy Market Operator and PLI scheme disbursement timelines.
Forecasts assume regulatory continuity in CEA efficiency mandates and MIIT localization requirements; material policy shifts would require re-modeling. Revision becomes warranted when grain-oriented electrical steel export quotas or amorphous metal core cost curves cross thresholds disrupting current supply economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Europe Distribution Transformer Market
Transformers
Middle-East Smart Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Smart Transformer Market
Transformers
North America Transformer Market
Transformers
Green Transformer Market
Transformers
Liquid Filled Transformer Market
Transformers
Transformer Core Market
Transformers
Canada Transformer Market
Transformers
Current Transformer Market
Transformers
Europe Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
US Oil Filled Distribution Transformer Market
Transformers
Phase-Shifting Transformer Market
Transformers
United Arab Emirates Transformer Market
Transformers
Middle East Distribution Transformer Market