
 Smart Transformer Market | 2026-2036
Smart Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Transformer Market Analysis
REACH is decoupling legacy transformer chemistries from the European supply base, forcing manufacturers to reformulate insulating fluids and core materials. ABB leverages its digital twin platform to sustain design leadership across medium-voltage installations. Siemens anchors its position through in-house production of power electronics modules that control bidirectional power flows. Mitsubishi Electric competes on manufacturing scale in Asia-Pacific utility tenders.
A smart transformer integrates semiconductor-based power converters, real-time sensor arrays, and embedded control algorithms to regulate voltage, current, and power factor dynamically across distribution networks. These units operate at switching frequencies above 10 kHz, enabling precise load matching and harmonic compensation that conventional electromagnetic transformers cannot achieve. Among technology segments, IoT Integration leads in new order volume as utilities demand predictive maintenance and remote diagnostics, while Power Electronics captures the deepest margin pools due to silicon carbide component scarcity. Control Systems represents the fastest-growing component segment, driven by embedded software requirements for grid-edge autonomy.
The EU Green Deal and F-Gas Regulation shape European product standards by mandating lower-loss designs and restricting fluorinated greenhouse gases in cooling systems. EMA and ECHA coordinate chemical safety assessments for novel dielectric fluids entering the market. China's MIIT enforces GB standards on smart grid interoperability, creating a separate certification pathway for foreign suppliers. Stakeholders must monitor whether NMPA-style equipment registration expands to power electronics imports, as this would reshape market access timelines and localization requirements.
Market Dynamics
Silicon carbide semiconductor shortages are compressing power electronics lead times and redrawing supplier hierarchies across medium-voltage distribution networks. This supply concentration is forcing utilities to pre-book converter modules eighteen months ahead of installation schedules.
Growth Catalysts
- EU F-Gas Regulation:Mandates phasing down fluorinated greenhouse gases in transformer cooling systems, accelerating demand for natural ester and synthetic paraffin dielectric fluids across German and French utility fleets.
- State Grid Corporation procurement:China's centralized tendering for digitally controlled substations is absorbing excess manufacturing capacity and validating silicon carbide inverter designs at scale.
- IoT sensor miniaturization:Embedded fiber-optic temperature and partial-discharge monitoring is enabling predictive maintenance contracts that extend asset life cycles beyond traditional electromagnetic units.
Market Restraints
- Silicon carbide substrate concentration:Wolfspeed and Coherent control over eighty percent of high-quality SiC wafer supply creates single-source vulnerability for converter manufacturers.
- GB standard certification timelines:China's MIIT interoperability testing adds six to nine months to foreign equipment market entry, freezing out smaller European suppliers without localized testing facilities.
- Copper and grain-oriented electrical steel volatility:Core material price swings above fifteen percent annually are eroding fixed-price contract margins for transformer OEMs.
Strategic Opportunities
- India urban distribution:CEA mandates for smart metering integration create first-mover advantage for vendors offering combined transformer-meter-communication platforms in Mumbai and Delhi distribution zones.
- Renewable interconnect hybridization:Converging photovoltaic inverter and transformer functions into single power-conversion units opens substation footprint reduction contracts with European offshore wind developers.
- US IRA manufacturing credits:Domestic content bonuses for grid infrastructure are attracting module assembly investment to Texas and Arizona, shortening supply lines for North American utilities.
Industry Challenges
- Power electronics firmware integration:Embedded control algorithms for bidirectional power flow require rare combinations of electrical engineering and real-time software expertise that utilities lack in-house.
- Legacy asset interoperability:IEC 61850 protocol implementation across decades-old substation automation systems demands costly gateway hardware and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Transformer Market |
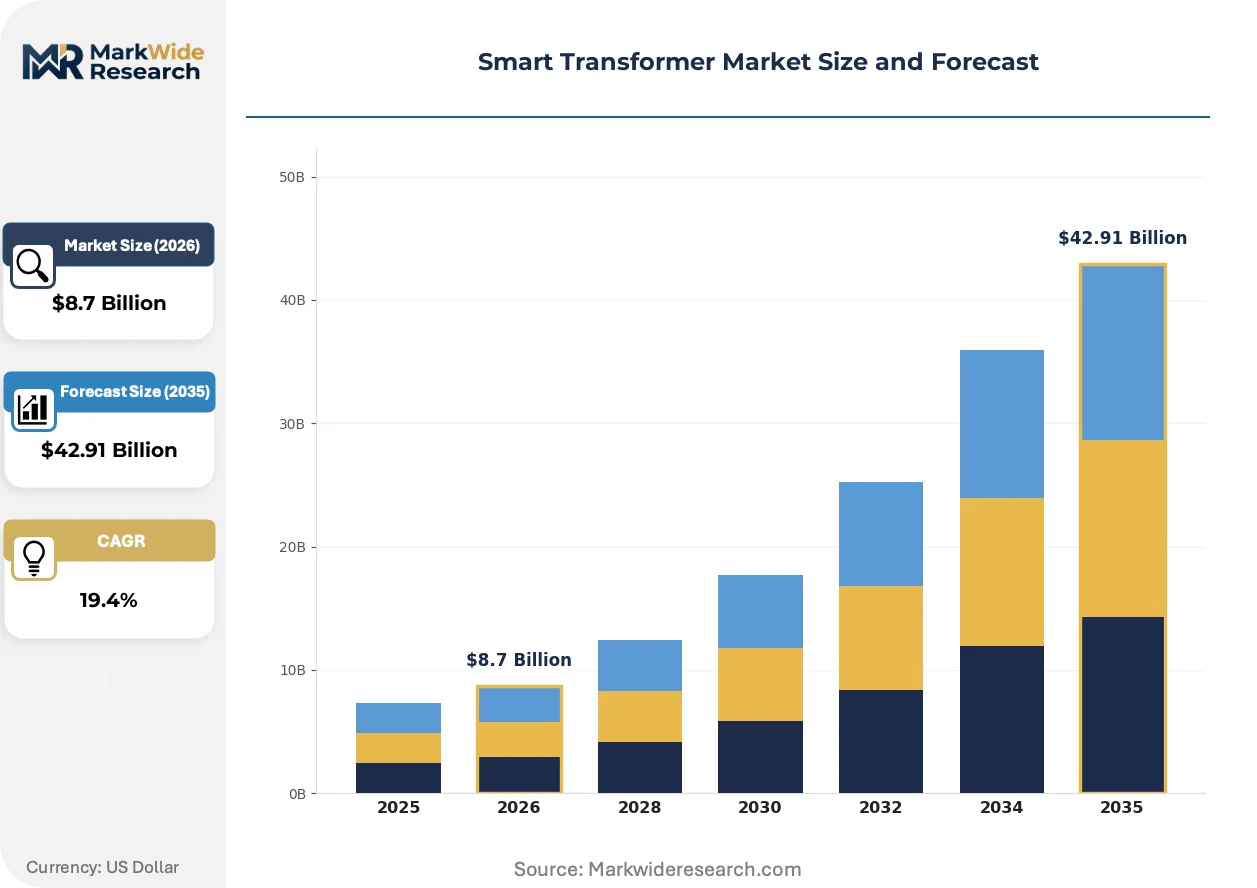
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Switchgear, Sensors, Control Systems, Monitoring Devices Technology: Digital, Analog, Power Electronics, IoT Integration End User: Utilities, Industrial, Commercial, Renewable Energy Installation: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | General Electric, Mitsubishi Electric, ABB, Hitachi, Eaton, Siemens, Toshiba, Hyundai Electric, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Transformer Market Emerging Trajectories
Digital twin simulation is compressing design-validation cycles and enabling performance guarantees that shift project risk from utilities to equipment vendors. This capability gap is separating integrated platform providers from component suppliers.
Silicon carbide metal-oxide-semiconductor field-effect transistors are replacing insulated-gate bipolar transistors in medium-voltage converters, cutting switching losses by two-thirds. German utilities adopting these modules in Hamburg and Munich substations are demanding ten-year performance warranties. This semiconductor transition is converging with cloud-based fleet analytics to create subscription-based asset management offerings.
The EU Green Deal's efficiency mandates are tightening permissible no-load loss thresholds for distribution transformers rated above 1 MVA. Manufacturers serving the Netherlands and Belgium markets are redesigning core laminations and magnetic circuits to meet 2027 Tier 2 requirements. Medium-voltage product lines face forced obsolescence if certification is not secured by the December 2026 deadline.
Utility procurement departments are consolidating vendor panels and demanding outcome-based availability contracts rather than equipment-only purchases. This shift transfers operational risk to OEMs and compresses margins for pure hardware manufacturers. The transformation is most advanced in Scandinavian markets where Statnett and Energinet have eliminated traditional capital expenditure tenders for distribution infrastructure.
Smart Transformer Market Segmentation
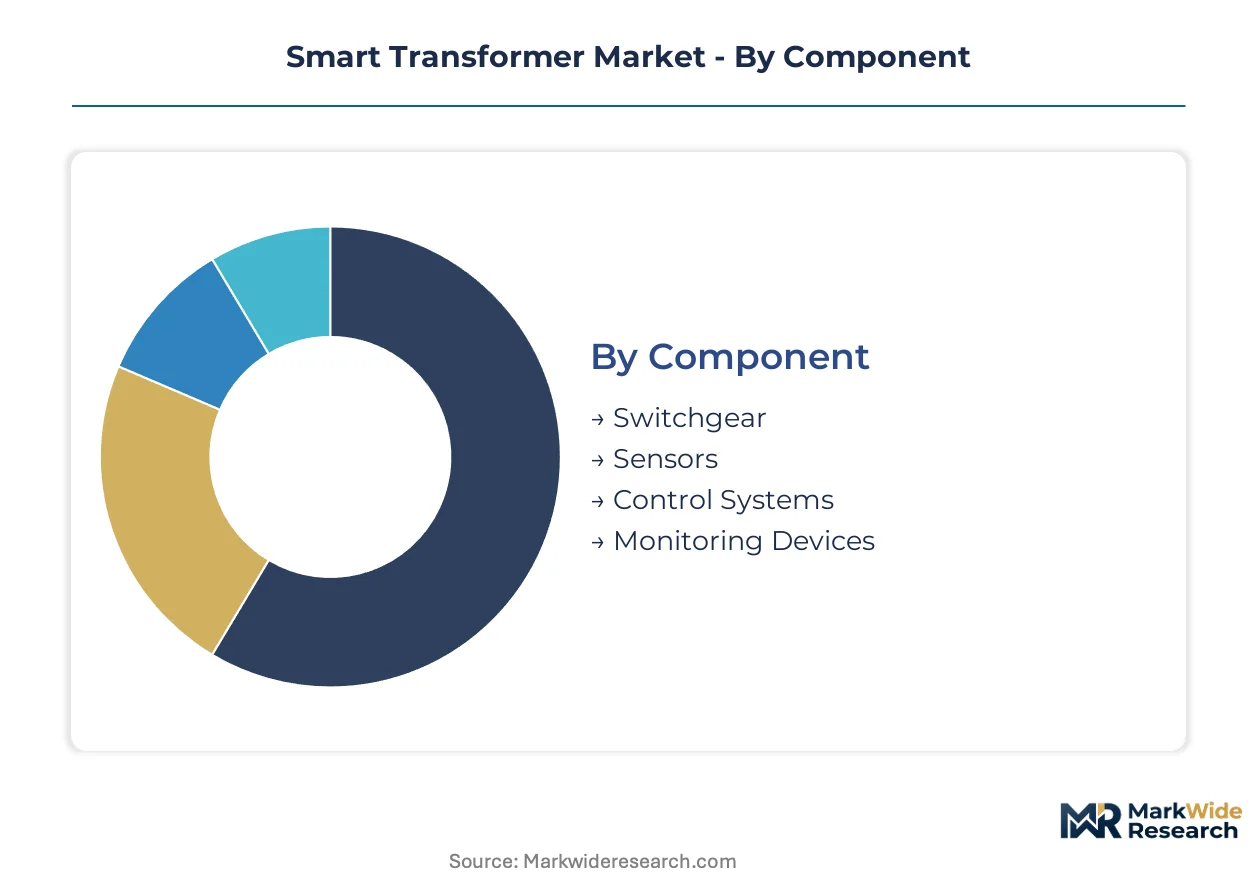
Smart transformer procurement splits sharply between volume-driven utility standardization and premium-priced technology integration. Component selection determines warranty terms and lifecycle cost models that reshape vendor selection criteria across tender processes.
Component:
Volume concentrates in hardware-intensive subsystems while premium margins accrue to software-embedded intelligence layers.
- Control Systems:Embedded algorithms govern bidirectional power flow and voltage regulation in real time. German utilities in Hamburg and Munich specify these for grid-edge autonomy projects under F-Gas Regulation compliance timelines.
- Sensors:Fiber-optic temperature and partial-discharge arrays enable predictive maintenance contracts. State Grid Corporation tenders for Shanghai and Beijing substations require embedded monitoring as baseline specification.
- Switchgear:Medium-voltage circuit protection hardware integrates with digital control buses for remote operation.
- Monitoring Devices:Standalone diagnostic units aggregate sensor data for cloud-based fleet analytics platforms.
Mature deployment sits with Switchgear. Newer deployment is concentrated in Control Systems.
Technology:
Cost tier separation runs from legacy electromagnetic designs through silicon carbide-enabled digital platforms.
- IoT Integration:Predictive maintenance platforms combine edge computing with cloud analytics for asset lifecycle extension. Scandinavian utilities including Statnett and Energinet mandate remote diagnostics in outcome-based availability contracts.
- Power Electronics:Silicon carbide converters operate above 10 kHz switching frequency with switching losses one-third of IGBT equivalents. Wolfspeed wafer scarcity compresses lead times to eighteen months for converter module procurement.
- Digital:Software-defined voltage regulation replaces tap-changer mechanics with semiconductor-based control.
- Analog:Conventional electromagnetic transformers with electromechanical voltage adjustment retain cost advantage in price-sensitive tenders.
Legacy procurement favors Analog. Steepest expansion trajectory belongs to IoT Integration.
End User:
Customer type dictates performance specification stringency and contract structure complexity.
- Utilities:Centralized procurement departments demand ten-year performance warranties and outcome-based availability contracts. EU Green Deal efficiency mandates force Tier 2 loss threshold compliance for units above 1 MVA.
- Renewable Energy:Offshore wind developers in the Netherlands and Belgium converge photovoltaic inverter and transformer functions for substation footprint reduction.
- Industrial:Manufacturing facilities prioritize harmonic compensation and power quality for sensitive production equipment.
- Commercial:Data centers and large facilities specify compact indoor installations with integrated metering.
Established demand centers on Utilities. Fastest share gain occurs in Renewable Energy.
Installation:
Application environment determines enclosure specifications and thermal management architecture.
- Outdoor:Weather-hardened enclosures with natural ester cooling meet EU F-Gas Regulation phase-down requirements for German and French distribution fleets.
- Indoor:Compact designs with synthetic paraffin dielectric fluids serve urban substation space constraints in Mumbai and Delhi distribution zones under CEA smart metering mandates.
- Onshore:Standardized foundation-mounted units dominate utility-scale renewable interconnect projects.
- Offshore:Platform-integrated designs withstand salt corrosion and vibration for North Sea wind installations.
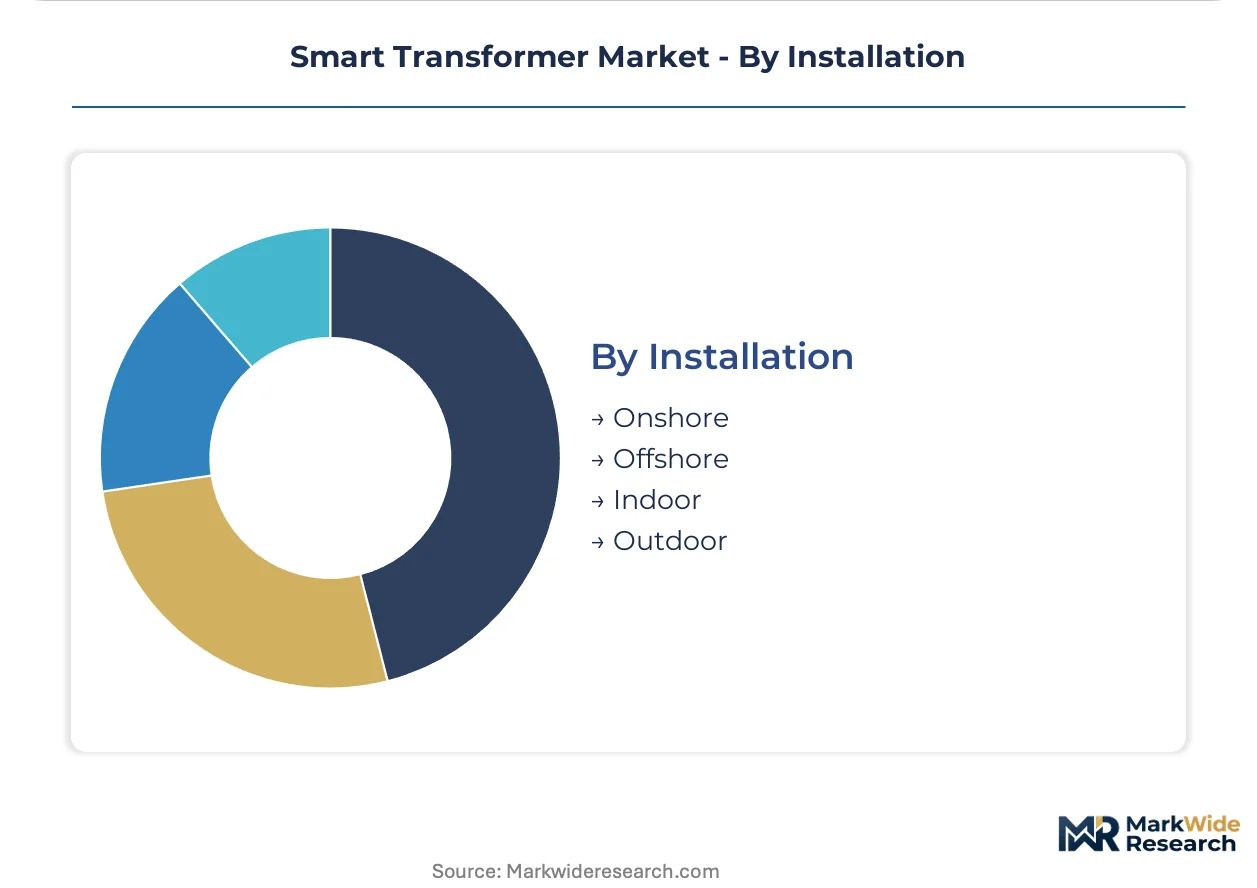
Volume deployment remains with Onshore. Emerging specification intensity clusters in Offshore.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta concentrate smart transformer manufacturing capacity, while Germany's Ruhr industrial corridor anchors European demand for digitally controlled substations. Tax incentives under India's Production Linked Incentive scheme are drawing module assembly investment to Gujarat and Maharashtra.
China
State Grid Corporation's centralized tendering for urban substation modernization absorbs excess silicon carbide manufacturing capacity. MIIT enforces GB standards on smart grid interoperability, creating separate certification pathways for foreign suppliers. Shanghai and Beijing substation clusters validate digitally controlled voltage regulation systems at scale.
Germany
Utilities in Hamburg and Munich specify embedded control algorithms for grid-edge autonomy projects. EU F-Gas Regulation mandates phasing down fluorinated greenhouse gases in transformer cooling systems, accelerating natural ester fluid adoption. The Ruhr industrial corridor hosts concentrated medium-voltage distribution fleet upgrades.
United States
Domestic content bonuses under IRA grid infrastructure provisions attract module assembly investment to Texas and Arizona. FERC interconnection standards shape bidirectional power flow requirements for renewable interconnect projects. California and New York utilities consolidate vendor panels around outcome-based availability contracts.
India
CEA mandates for smart metering integration create first-mover advantage for combined transformer-meter-communication platforms. PLI scheme incentives localize power electronics module production in Gujarat and Maharashtra. Mumbai and Delhi distribution zones specify compact indoor installations with integrated metering.
Netherlands
Offshore wind developers in Rotterdam and Amsterdam converge photovoltaic inverter and transformer functions for substation footprint reduction. EU Green Deal Tier 2 loss thresholds force core lamination redesigns for units above 1 MVA. North Sea platform-integrated designs withstand salt corrosion for offshore installations.
Smart Transformer Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology integration tiers. Market structure concentrates around three strategic archetypes: integrated platform providers leveraging digital twin capabilities, power electronics specialists controlling silicon carbide converter supply, and regional scale manufacturers serving utility tender markets. Dominant competitive moves include backward integration into semiconductor wafer sourcing and geographic expansion through localized testing facility investment.
Among diversified industrial conglomerates, General Electric and Siemens exemplify platform-integrated positioning spanning control systems and power electronics. Mitsubishi Electric occupies a scale-driven position within Asia-Pacific utility procurement. These three represent distinct competitive vectors: digital twin-enabled lifecycle services, in-house power electronics module production, and manufacturing scale in centralized tender markets.
| Leading Market Players |
|---|
| General Electric |
| Mitsubishi Electric |
| ABB |
| Hitachi |
| Eaton |
| Siemens |
| Toshiba |
| Hyundai Electric |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Power electronics firmware engineers concentrated in Germany's Ruhr corridor and China's Yangtze River Delta create labor-cost differentials that widen pricing spreads between premium digitally controlled units and commodity electromagnetic designs. Tier 1 utilities absorb these premiums for grid-edge autonomy projects, while price-sensitive industrial buyers in India and Southeast Asia default to analog alternatives.
Pricing Analysis
Premium pricing for eighteen-month silicon carbide converter lead times compresses margins for spot-inventory procurement, while discounted legacy IGBT-based systems clear through secondary channels. Three-tier pricing structure across premium SiC-enabled, standard IGBT-based, and economy analog electromagnetic levels separates warranty-backed availability contracts from equipment-only transactions. Cost compression in the standard tier intensifies because Wolfspeed wafer scarcity forces converter OEMs to prioritize long-term utility offtakes. Industrial manufacturing facilities exhibit highest price sensitivity, whereas Scandinavian utilities accepting outcome-based contracts show lowest.
Supply Chain Analysis
Freight cost volatility for liquid dielectric fluids shipped from European chemical producers to Asian assembly plants amplifies total landed cost spreads across regional manufacturing footprints. Supply concentrates in China for power electronics module assembly, Germany for control system engineering, and Japan for precision sensor manufacturing. Raw material dependencies include silicon carbide wafers, grain-oriented electrical steel, and copper windings. Single-source vulnerability at Wolfspeed and Coherent for high-quality SiC substrates threatens converter production schedules. Distribution runs through direct utility procurement departments for large tenders, with regional distributors serving smaller industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide substrate scarcity props pricing power across medium-voltage converter tiers, creating supply-constrained conditions that favor incumbents with pre-booked wafer allocations.
For Market Incumbents: Acquire captive silicon carbide wafer supply through long-term offtake agreements or minority positions in substrate manufacturers. Expand in-house power electronics module production in Texas and Arizona to capture IRA domestic content bonuses. Defend against emerging Chinese scale manufacturers by accelerating GB standard certification timelines through localized testing facility investment. For New Entrants and Emerging Players: Cloud-native fleet analytics platforms offer technology-first entry points into subscription-based asset management contracts underserved by hardware-centric incumbents. Target India's CEA-mandated smart metering integration in Mumbai and Delhi distribution zones, where combined transformer-meter-communication platforms face limited established competition. Pursue joint development agreements with European offshore wind developers seeking converged photovoltaic inverter-transformer functions. For Investors and Strategic Acquirers: Re-rating potential sits with power electronics specialists controlling silicon carbide converter supply given State Grid Corporation procurement validation at scale. Long-term viability across the projection horizon favors vertically integrated platform providers over pure hardware manufacturers facing margin compression from outcome-based contracting. Monitor whether NMPA-style equipment registration expands to power electronics imports as inflection signal for market access timeline restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Wafer Supply | Secures converter module production capacity against Wolfspeed and Coherent concentration. |
| Localized GB Standard Certification Investment | Shortens China market entry timelines for foreign equipment suppliers under MIIT enforcement. |
| Cloud-Based Fleet Analytics Platform Launch | Enables subscription revenue streams from Statnett and Energinet outcome-based contracts. |
| Natural Ester Cooling System Transition | Aligns product portfolios with EU F-Gas Regulation phase-down mandates in Germany and France. |
| Combined Transformer-Meter-Communication Development | Captures CEA-mandated opportunities in Mumbai and Delhi urban distribution zones. |
Methodological Framework
Multi-period observation of silicon carbide converter lead times, utility procurement contract structures, and regulatory certification timelines anchored the trend analysis, supplemented by interviews with utility planning officers, power electronics procurement managers, grid operators, EPC contractors, and substation automation engineers. Secondary validation drew from FERC interconnection filings, EIA grid infrastructure data, IEA power system reports, and customs records for transformer component trade flows. Bottom-up unit economics triangulated against top-down market sizing across component, technology, end user, and installation dimensions.
Segment-weighting approaches distributed value estimates across IoT Integration, Power Electronics, Digital, and Analog technology tiers, with additional stratification by utility, renewable energy, industrial, and commercial end-user categories. CAGRs derived from installed base turnover rates, replacement demand curves, and new-build infrastructure pipelines throughout the forecast period. Industry-specific inputs included silicon carbide wafer supply forecasts, EU Green Deal efficiency mandate compliance deadlines, and State Grid Corporation tender volume trajectories.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting semiconductor equipment exports, unanticipated breakthroughs in gallium nitride converter economics, and force majeure disruptions to grain-oriented electrical steel production. Forecasts reflect documented assumptions about supply chain normalization trajectories and regulatory implementation schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Global Large Power Transformers Market
Transformers
Gas Insulated Transformer Market
Transformers
High Frequency Transformer Market
Transformers
United States Dry-Type Transformer Market
Transformers
Liquid-Immersed Transformers Market
Transformers
North America Power Transformer Market
Transformers
Global Transformer Market
Transformers
Distribution Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
China Transformer Market
Transformers
North America Transformer Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
North America Oil Filled Transformer Market
Transformers
HVDC Converter Transformers Market
Transformers
Rectifier Transformers Market