
 Locomotive Traction Transformer Market | 2026-2036
Locomotive Traction Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Locomotive Traction Transformer Market Foresight
The EU Green Deal's rail decarbonization mandate is shifting procurement criteria toward lighter, more efficient traction transformer designs. ABB leverages its European manufacturing footprint to dominate retrofit contracts for existing locomotive fleets. Siemens anchors its position through R&D intensity in solid-state transformer architectures. Alstom competes on geographic breadth, sustaining project wins across multiple electrified corridors.
A locomotive traction transformer converts high-voltage catenary power to levels suitable for traction motors, typically operating at 15-25 kV and 50-60 Hz with oil-immersed or dry-type insulation systems rated for severe vibration and thermal cycling. Single-phase transformers occupy the largest installed base due to legacy compatibility with 15 kV and 25 kV overhead lines across Europe and Asia. Static transformers represent the fastest-expanding technology segment, as silicon carbide power electronics displace conventional tap-changer designs. Three-phase configurations command premium positioning in high-speed train applications where harmonic distortion tolerances are tightest.
IEC 60310 and EN 50328 standards govern thermal performance and electromagnetic compatibility for traction transformers sold into European networks, while the EU F-Gas Regulation restricts insulating medium choices in sealed systems. Japan's METI efficiency benchmarks and China's GB/T rail standards create divergent compliance pathways that fragment supplier certification requirements. Stakeholders must monitor solid-state technology maturation and regional certification reciprocity to anticipate where manufacturing scale advantages will consolidate.
Market Dynamics
Silicon carbide power electronics are compressing transformer footprints while EU Green Deal mandates force fleet operators toward lighter, more efficient designs. This dual pressure is restructuring procurement criteria across electrified rail corridors.
Growth Catalysts
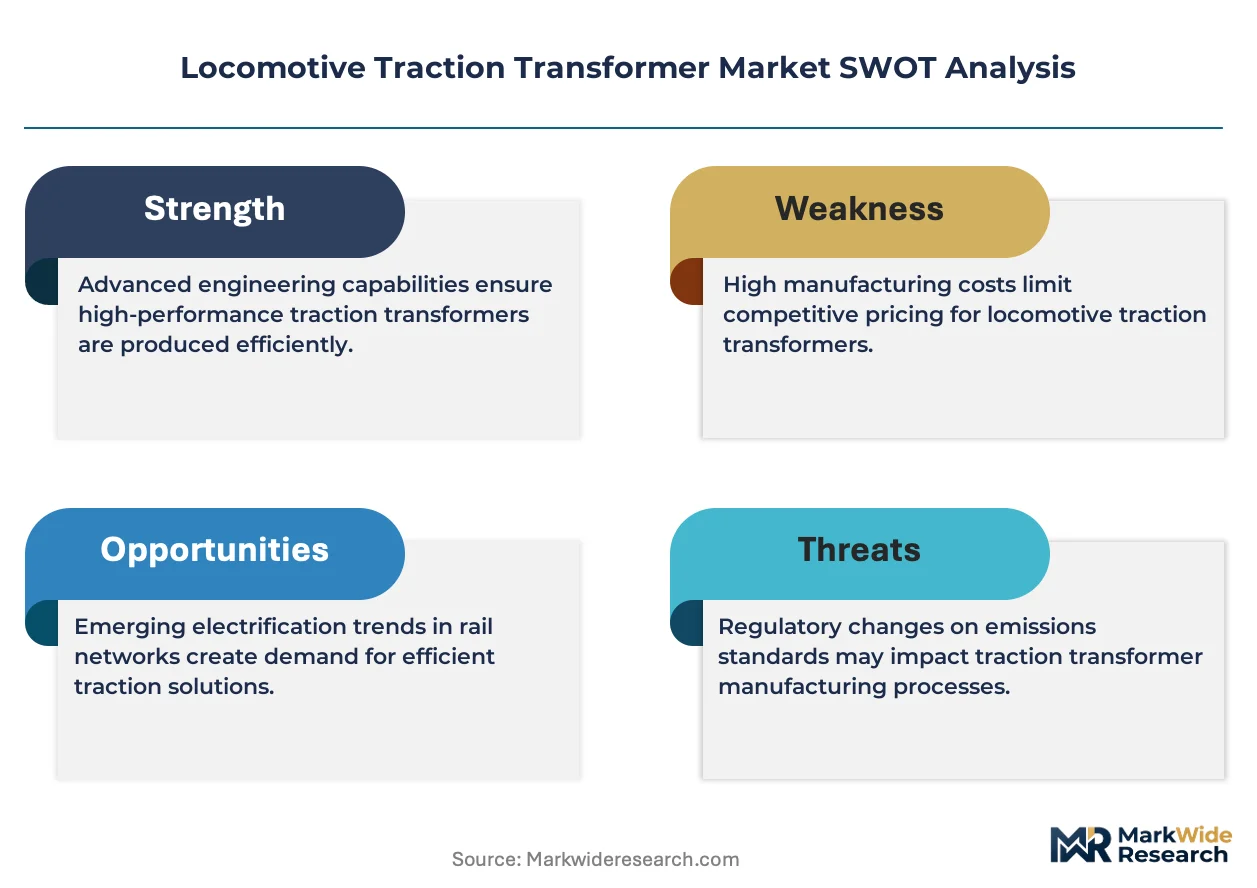
- EU Green Deal rail decarbonization mandate:Freight operators must electrify corridors to meet emission targets, creating sustained demand for high-efficiency traction transformers.
- Silicon carbide semiconductor integration:These wide-bandgap devices reduce cooling system mass and enable compact transformer architectures.
- German fleet modernization programs:Deutsche Bahn's procurement volumes anchor regional demand for replacement and new-build locomotive systems.
Market Restraints
- Copper and grain-oriented electrical steel price volatility:Core winding materials face supply pressure from energy-intensive smelting operations concentrated in China.
- EU F-Gas Regulation restrictions:Sealed transformer designs face constrained insulating medium choices, complicating thermal management in compact units.
- Tap-changer mechanical complexity:Conventional voltage regulation systems require intensive maintenance, limiting operational availability in high-mileage freight service.
Strategic Opportunities
- Polish and Romanian electrification corridors:These markets show underpenetrated high-speed and freight line development with EU cohesion fund backing.
- Solid-state transformer architecture convergence:Power electronics and magnetic component integration enables modular, scalable traction power systems.
- Retrofit aftermarket channel development:Aging locomotive fleets across Central Europe create demand for drop-in replacement units with improved efficiency profiles.
Industry Challenges
- IEC 60310 and EN 50328 certification timelines:Electromagnetic compatibility and thermal performance testing extends product qualification cycles.
- Power electronics-magnetic component integration complexity:Solid-state designs require rare interdisciplinary expertise spanning semiconductor physics and high-voltage insulation engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Locomotive Traction Transformer Market |
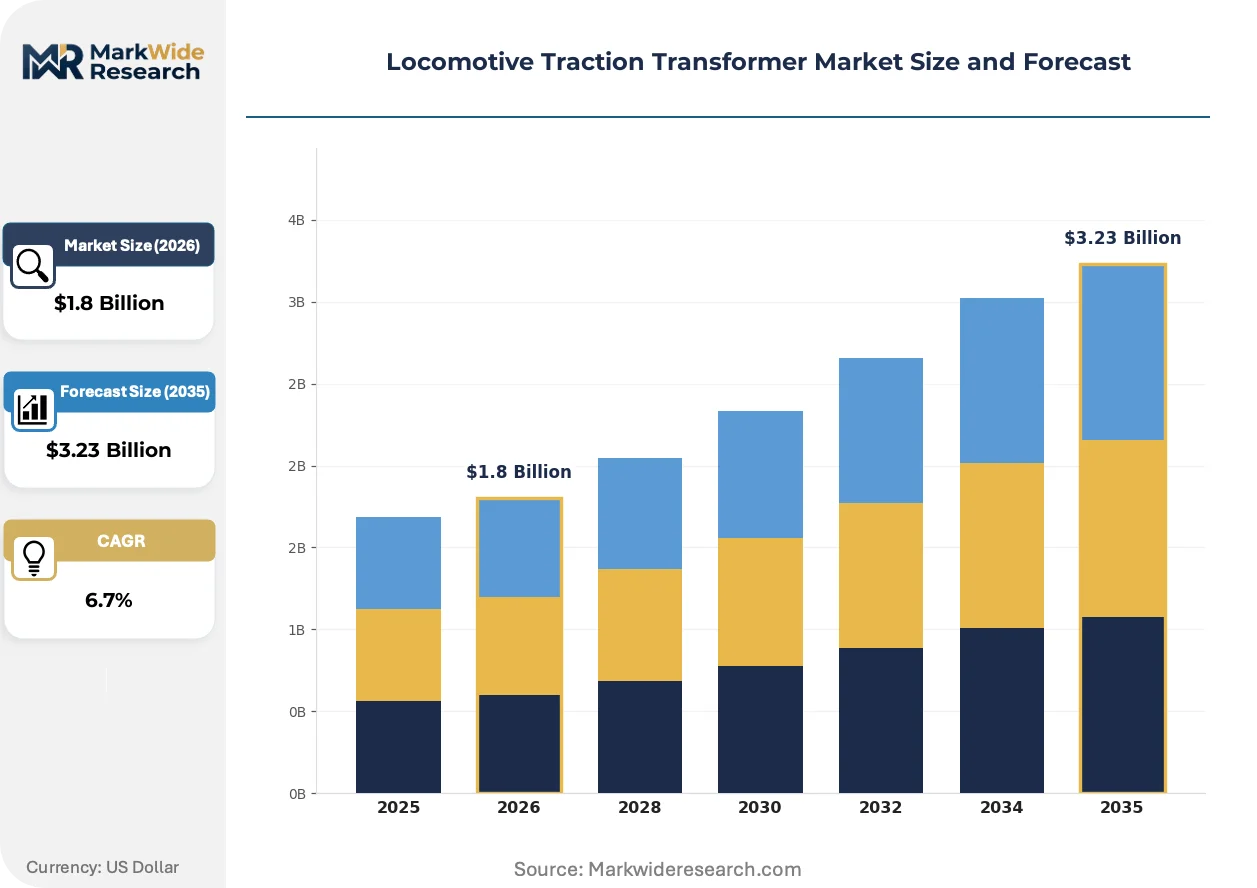
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase Transformers, Three-Phase Transformers, Static Transformers, Load Commutated Inverters End User: Railways, Metro Systems, Freight Operators, High-Speed Trains Technology: High Voltage Direct Current, Alternating Current, Solid-State Technology, Modular Technology Installation Type: Onboard Installation, Trackside Installation, Ground Level Installation, Elevated Installation |
| Companies Covered | ABB, Siemens, Alstom, Mitsubishi Electric, Hitachi, Schneider Electric, Toshiba, JST Transformateurs, Setrans Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Locomotive Traction Transformer Market Shifts & Advancements
Power semiconductor evolution and regulatory tightening are converging to redefine traction transformer design priorities. Equipment buyers now weight lifecycle efficiency metrics above initial capital cost in procurement decisions.
Silicon carbide MOSFETs and Schottky diodes are expanding into traction power conversion stages, replacing silicon IGBTs in front-end rectifier and inverter modules. Freight operators in Germany and Austria are specifying SiC-based auxiliary power systems for new locomotive orders. This semiconductor transition is expanding into main transformer interfaces, enabling dry-type insulation systems that eliminate oil cooling infrastructure.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in sealed electrical equipment, forcing manufacturers toward natural ester or synthetic hydrocarbon insulating fluids. Transformer OEMs must reformulate dielectric systems while maintaining fire safety ratings under EN 45545 railway standards. High-speed train applications face the tightest compliance windows, with 2027 deadlines accelerating fluid qualification programs.
Lifecycle cost contracting is displacing unit-price procurement in Deutsche Bahn and SNCF tender processes. Operators now contract energy consumption guarantees and availability targets rather than accepting capital expenditure bids alone. This performance-based model concentrates supplier selection among firms with predictive maintenance platforms and European service networks.
Locomotive Traction Transformer Market Segmentation
Transformer architecture choices directly determine weight budgets, cooling infrastructure, and compatibility with legacy catenary systems across electrified rail networks. Procurement decisions cascade through fleet availability, maintenance intervals, and energy consumption guarantees that now dominate European tender processes.
Product Type:
Buyers differentiate primarily by legacy infrastructure compatibility versus efficiency gains from emerging semiconductor integration.
- Single-Phase Transformers:These conventional units operate at 15-25 kV with oil-immersed insulation rated for severe vibration cycles. Deutsche Bahn's fleet modernization in Germany sustains procurement volumes for replacement drop-in units compatible with existing overhead line infrastructure.
- Static Transformers:Silicon carbide power electronics displace mechanical tap-changers, compressing footprints and eliminating oil cooling systems. Austrian freight corridors specify these for new locomotive orders where weight reduction translates directly to payload capacity.
- Three-Phase Transformers:Premium positioning in high-speed applications where harmonic distortion tolerances are tightest.
- Load Commutated Inverters:Specialized traction power conversion for heavy-haul freight segments.
Single-phase transformers lead volumes today; static transformers are gaining share fastest.
End User:
Operational intensity and mileage profiles create divergent specifications for thermal cycling durability.
- Freight Operators:High-mileage duty cycles demand robust tap-changer alternatives and predictive maintenance integration. EU Green Deal corridor electrification mandates in Poland and Romania drive replacement demand for aging Central European locomotive fleets.
- High-Speed Trains:Tight harmonic distortion requirements and fire safety ratings under EN 45545 dominate procurement criteria. SNCF tender processes now contract energy consumption guarantees rather than capital expenditure alone.
- Railways:National infrastructure operators balance legacy compatibility with modernization pathways.
- Metro Systems:Urban electrification projects with frequent stop-start thermal profiles.
Freight operators anchor replacement demand; high-speed rail commands the steepest expansion trajectory.
Technology:
Power conversion architecture determines semiconductor content, cooling mass, and electromagnetic compatibility certification complexity.
- Alternating Current:Dominant installed base with mature IEC 60310 certification pathways and established service networks across European corridors.
- Solid-State Technology:Power electronics and magnetic component integration enables modular traction power systems with dry-type insulation eliminating oil infrastructure.
- High Voltage Direct Current:Specialized applications requiring distinct electromagnetic compatibility testing protocols.
- Modular Technology:Scalable architectures for fleet operators seeking standardized spare part strategies.
Alternating Current retains installed base dominance; solid-state designs are climbing the fastest.
Installation Type:
Physical mounting constraints dictate thermal management architecture and accessibility for maintenance intervals.
- Onboard Installation:Space-constrained locomotive compartments require compact designs with severe vibration tolerance. German and Austrian specifications increasingly mandate silicon carbide auxiliary power systems to reduce cooling system mass.
- Trackside Installation:Fixed infrastructure applications with easier thermal management but higher exposure to environmental cycling.
- Ground Level Installation:Maintenance-accessible configurations for depot-based fleet operations.
- Elevated Installation:Specialized mounting for terrain-constrained corridor electrification.
Onboard installation commands procurement volumes; trackside configurations show expanding deployment in new electrification corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Traction transformer manufacturing originated in Germany and Switzerland during the early electrification of European rail networks. These engineering traditions established the technical foundations that now diffuse across electrified corridors worldwide.
Germany
Deutsche Bahn's fleet modernization sustains the largest procurement volumes for replacement and new-build locomotive systems. The EU Green Deal mandates corridor electrification through 2030, accelerating tender processes for high-efficiency units. Manufacturing clusters concentrate in Bavaria and Baden-Württemberg, where ABB and Siemens anchor transformer production for domestic and export markets.
China
CRRC's locomotive production scale drives demand for traction power systems compatible with 25 kV and 50 Hz infrastructure. GB/T rail standards create distinct certification pathways that domestic suppliers navigate more efficiently than foreign competitors. Industrial concentration in the Yangtze River Delta and Shandong Peninsula supports vertically integrated supply chains for core winding materials.
Japan
METI efficiency benchmarks push rail operators toward lighter transformer designs that reduce energy consumption per passenger-kilometer. Shinkansen network expansion into Hokkaido and Kyushu requires compact units for high-speed trainsets with severe thermal cycling profiles. Manufacturing capabilities cluster in the Chubu region around Nagoya, where Hitachi and Toshiba maintain traction power engineering centers.
United States
Freight rail electrification remains limited, but Amtrak's Northeast Corridor modernization generates niche demand for dual-voltage systems. Federal Railroad Administration safety regulations govern thermal performance testing protocols that extend product qualification timelines. Industrial activity concentrates in the Midwest, where transformer specialists service the small installed base of electric locomotives.
India
Indian Railways' dedicated freight corridor electrification creates sustained procurement for heavy-haul traction transformers rated for tropical thermal conditions. CEA efficiency mandates and BIS certification requirements shape supplier selection for domestic manufacturing partnerships. Production capabilities concentrate in Maharashtra and Gujarat, where joint ventures with European OEMs transfer technology for local assembly.
Locomotive Traction Transformer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the traction transformer value chain. The market structure consolidates around integrated electrical equipment conglomerates with captive railway divisions and specialized transformer OEMs serving niche retrofit channels. Two strategic archetypes dominate: diversified industrial groups leveraging cross-divisional R&D, and focused transformer specialists competing on regional service density. Competitive moves center on solid-state technology licensing partnerships and aftermarket service network expansion.
Among European-based integrated suppliers, ABB, Siemens, and Alstom occupy positions that exemplify divergent strategic orientations. ABB represents the diversified industrial archetype with manufacturing footprints spanning multiple electrified corridors. Siemens exemplifies R&D-intensive positioning in emerging solid-state architectures. Alstom sits within the mobility-focused tier, leveraging geographic breadth across project wins. These three anchors illustrate how procurement concentration in German and Austrian markets rewards suppliers with predictive maintenance platforms and European service networks.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Alstom |
| Mitsubishi Electric |
| Hitachi |
| Schneider Electric |
| Toshiba |
| JST Transformateurs |
| Setrans Holding |
| Others |
Supply & Pricing Matrix
Backward integration into silicon carbide semiconductor fabrication anchors pricing power for European traction transformer OEMs while insulating them from raw material volatility in Asian supply markets. This captive production of wide-bandgap power electronics compresses transformer footprints and commands premium positioning in Deutsche Bahn's lifecycle cost contracting frameworks.
Pricing Analysis
Lifecycle cost contracting with energy consumption guarantees now dominates procurement in German and Austrian freight corridors. Price differentiation rests on solid-state technology maturity and predictive maintenance platform integration, with static transformer configurations commanding substantial premiums over conventional tap-changer designs. Cost compression in single-phase replacement units is intensifying because copper and grain-oriented electrical steel face supply pressure from energy-intensive Chinese smelting operations. Freight operators in Poland and Romania exhibit the highest price sensitivity, while high-speed rail tenders in France and Germany prioritize availability metrics over capital expenditure.
Supply Chain Analysis
Dual-sourcing requirements mandated by IEC 60310 certification protocols force OEMs to qualify alternate suppliers for core winding materials across Germany, China, and Japan. Manufacturing draws from concentrated deposits of copper cathode and grain-oriented electrical steel in China, with silicon carbide substrates sourced from Japanese and American wafer foundries. Single-source vulnerability in rare earth magnetic materials creates exposure to export restriction risks from Chinese regulatory authorities. Distribution runs through captive service networks maintained by ABB, Siemens, and Alstom for aftermarket replacement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal rail decarbonization mandates create a geographic-arbitrage opportunity between established German manufacturing clusters and emerging Polish electrification corridors where labor and regulatory compliance costs diverge meaningfully.
For Market Incumbents: Anchor defensive positioning through predictive maintenance platform expansion and solid-state transformer R&D lock-in. Threat from silicon carbide semiconductor specialists entering power conversion stages demands backward integration into wide-bandgap device supply. Certification investment in EN 50328 electromagnetic compatibility testing extends competitive moats against emerging Asian competitors. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for natural ester insulating fluid specialists to capture retrofit demand from sealed transformer designs facing 2027 compliance deadlines. Polish and Romanian freight corridor electrification presents the most penetrable white-space, with EU cohesion fund backing de-risking capital deployment. Go-to-market through predictive maintenance service contracts rather than unit-sales positioning aligns with Deutsche Bahn's procurement evolution. For Investors and Strategic Acquirers: Roll-up economics work for regional transformer service specialists because fragmented aftermarket channels in Central Europe lack predictive maintenance platform integration. Long-term viability hinges on solid-state technology maturation and certification reciprocity consolidation across European corridors. Acquisition targets should exhibit dense regional service networks and EN 45545 fire safety qualification pipelines. The signal to watch is silicon carbide device cost curves crossing threshold levels that enable mass-market static transformer adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Transformer Architecture Development | Silicon carbide integration eliminates oil cooling infrastructure and reduces locomotive weight budgets. |
| Predictive Maintenance Platform Deployment | Deutsche Bahn's lifecycle contracting favors suppliers with sensor-enabled fleet monitoring capabilities. |
| Natural Ester Insulating Fluid Qualification | EU F-Gas Regulation compliance requires reformulated dielectric systems for sealed transformer designs. |
| Polish Electrification Corridor Partnership | EU cohesion fund backing de-risks capital deployment in underpenetrated freight infrastructure. |
| Backward Integration into SiC Semiconductor Supply | Captive wide-bandgap device production insulates margins from Asian raw material volatility. |
Research Methodology
Bottom-up locomotive fleet modeling reconciled against top-down transformer production tracking forms the analytical core of this study. Primary interviews with Deutsche Bahn procurement officers, SNCF tender evaluation leads, ABB traction power engineers, and Polish freight operator maintenance directors combined with secondary validation from IEC certification databases, EU F-Gas Regulation implementation reports, and customs trade data for copper and electrical steel flows. Triangulation across these sources ensures segmentation integrity for static versus conventional transformer architectures.
Input-output matrices map silicon carbide device adoption curves against fleet modernization timelines across the projection horizon. Segmentation dimensions include transformer architecture type, end-use application, technology platform, and installation configuration, with regional regulatory cluster as an additional modeled variable. CAGRs derive from fitted growth curves applied to base-year procurement volumes, incorporating Deutsche Bahn's published electrification targets and METI efficiency benchmark trajectories as structural anchors.
Revisions become necessary when silicon carbide substrate supply disruptions, EU F-Gas Regulation enforcement delays, or copper price volatility spikes materialize beyond modeled ranges. Deviation in German fleet modernization commitment levels would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
China Transformer Market
Transformers
Transformer Oil Market
Transformers
Global Large Power Transformers Market
Transformers
Middle-East Smart Transformer Market
Transformers
United States Transformer Market
Transformers
Green Power Transformers Market
Transformers
Uninhibited Transformer Oil Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
United States Power Transformer Market
Transformers
Neon Transformer Market
Transformers
Transformer Core Market
Transformers
Power Transformer Market
Transformers
Step Up/Down Transformers Market
Transformers
Transformer Bobbin Market