
 Cast Resin Transformers Market | 2026-2036
Cast Resin Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Cast Resin Transformers Market Insights
Multi-source procurement for epoxy resin and copper windings is broadening as OEMs reduce dependency on single foundries. Siemens Energy leverages its European manufacturing footprint to sustain delivery reliability for utility-scale orders. ABB competes through technology leadership in vacuum pressure impregnated systems. Hitachi Energy anchors its position in the Asia-Pacific region with localized dry-type transformer production.
Cast resin transformers employ epoxy or polyurethane resin to encapsulate windings, delivering Class F or Class H insulation with IP ratings up to IP56 for harsh environments. These units eliminate fire and leakage risks, making them essential for indoor substations, underground facilities, and densely populated commercial districts. Three phase configurations dominate volume shipments due to industrial and utility-scale deployment, while single phase units occupy niche residential and rural electrification roles. Epoxy resin technology leads margin pools because of its superior thermal endurance and established certification pathways, whereas polyurethane is gaining traction in cost-sensitive commercial segments.
CE marking under the EU's Low Voltage Directive and IEC 60076-11 standards govern product compliance for cast resin transformers sold across Europe, with ECHA's REACH framework restricting certain flame-retardant additives in resin formulations. In the United States, OSHA electrical safety standards and NEMA ST-20 influence installation practices and product specifications. India's BIS certification mandates thermal performance testing for domestic supply. Stakeholders must monitor evolving fire-safety codes and resin material restrictions as building electrification intensifies in urban cores.
Market Dynamics
EU F-Gas Regulation is systematically phasing out oil-immersed transformer alternatives, forcing utilities and data center operators toward cast resin designs for indoor installations.
Growth Catalysts
- EU Green Deal decarbonization mandates:Member states must electrify industrial infrastructure, directing procurement toward fire-safe cast resin units for urban substations and underground facilities.
- Data center indoor installation requirements:Hyperscale operators prioritize encapsulated windings to eliminate leakage risks in densely populated server halls.
- Epoxy resin thermal performance:Class H insulation ratings enable higher loading capacities, supporting renewable grid integration projects across Germany and the Netherlands.
Market Restraints
- Copper and epoxy resin cost volatility:Raw material price swings compress OEM margins and complicate long-term utility contract pricing.
- Foundry concentration in East Asia:Limited domestic winding fabrication capacity in Europe creates supply vulnerability for rush orders.
- Polyurethane substitution ceiling:Inferior thermal endurance restricts polyurethane systems to commercial segments below 1 MVA ratings.
Strategic Opportunities
- India BIS certification expansion:Domestic thermal testing mandates create localized production incentives for dry-type transformer assembly.
- Building electrification codes:Fire-safety regulations in urban cores accelerate replacement of aging oil-filled units with IP56-rated cast resin alternatives.
- Digital twin integration:IoT sensor convergence with resin-encapsulated windings enables predictive maintenance contracts for utility fleets.
Industry Challenges
- Vacuum pressure impregnation technician scarcity:Specialized resin casting expertise concentrates at a handful of European OEM facilities.
- REACH compliance timeline complexity:ECHA flame-retardant additive restrictions force reformulation cycles that delay product recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cast Resin Transformers Market |
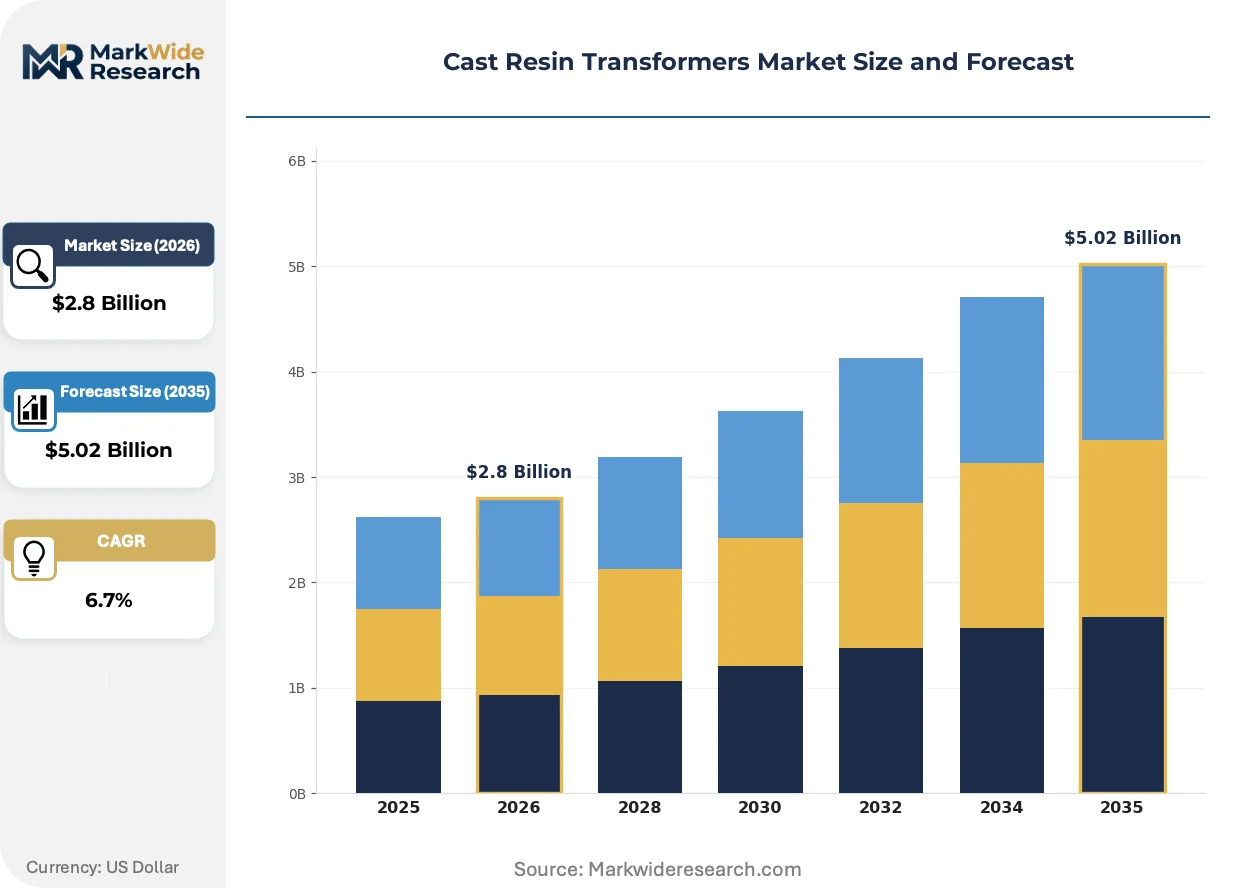
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Phase, Three Phase, Dry Type, Oil Immersed End User: Utilities, Industrial, Commercial, Residential Technology: Vacuum Pressure Impregnated, Epoxy Resin, Polyurethane, Composite Application: Renewable Energy, Grid Connection, Power Generation, Motor Control |
| Companies Covered | Schneider Electric, Siemens Energy, Eaton, Fuji Electric Co. Ltd., Hitachi Energy, ABB, General Electric, Bharat Heavy Electricals Limited, CG Power & Industrial Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cast Resin Transformers Market Trends and Innovations
Technology trajectories in cast resin transformers center on thermal performance enhancement, regulatory material compliance, and procurement model restructuring across utility and commercial segments.
Epoxy resin vacuum pressure impregnation is consolidating as the dominant winding encapsulation method for utility-scale installations. Grid operators in Germany and Denmark specify VPI-processed units for offshore wind connection substations. The technology is consolidating margin pools around OEMs with captive impregnation facilities, squeezing smaller assemblers dependent on outsourced resin casting.
EU REACH restrictions on halogenated flame retardants are forcing resin formulation changes across European supply chains. Compound suppliers must certify alternative thermal additives under IEC 60076-11 standards before volume deployment. German utilities are most exposed, facing compressed procurement timelines as existing inventory depletes ahead of reformulation approvals.
Long-term service agreements are displacing transactional equipment sales among data center operators. Colocation providers in Frankfurt and Amsterdam now bundle transformer maintenance with cooling infrastructure contracts. Facility managers in these markets prioritize OEMs with localized technical service teams over lowest-bid procurement.
Cast Resin Transformers Market Segmentation
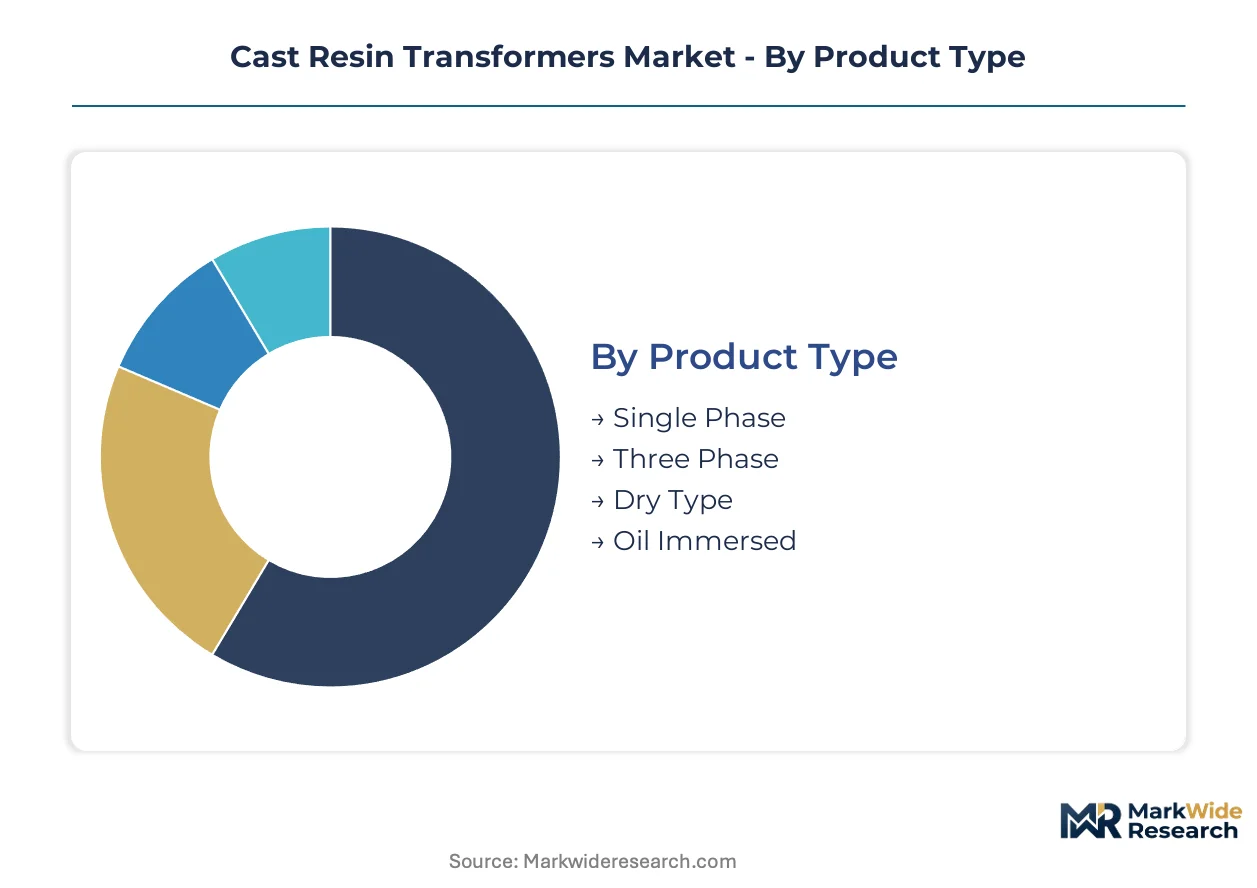
Segmentation in cast resin transformers determines procurement pathways, certification requirements, and margin structures. Product type dictates IEC 60076-11 testing protocols. Technology choice shapes thermal performance ceilings and REACH compliance timelines. Application segments align with distinct customer risk tolerances and service contract models.
Product Type:
Certification burdens vary sharply across product configurations, with IEC 60076-11 thermal testing and IP rating validation applying differentially based on phase count and cooling architecture.
- Three Phase:These units employ epoxy-encapsulated windings in delta or wye configurations, delivering Class H insulation for utility-scale substations and industrial feeders. Demand concentrates in Germany's renewable grid integration projects, where offshore wind connection substations require 1-10 MVA ratings with IP56 environmental sealing. REACH-compliant flame-retardant formulations extend procurement timelines for European utilities.
- Single Phase:Compact resin-cast designs serve rural electrification and residential distribution networks with ratings below 500 kVA. Deployment clusters in India's BIS-certified domestic supply chains, where thermal testing mandates favor localized assembly over import dependency.
- Dry Type:Air-cooled construction eliminates liquid dielectrics entirely, satisfying indoor installation codes for data centers and underground commercial facilities. OSHA electrical safety standards and NEMA ST-20 govern US deployment specifications.
- Oil Immersed:Mineral oil cooling persists in legacy outdoor installations despite EU F-Gas Regulation phase-out pressures, creating stranded asset risk for utilities delaying cast resin conversion.
Leading the category by volume: Three Phase. Growing fastest: Dry Type.
End User:
Customer type determines contract structure, with utilities favoring long-term service agreements and commercial buyers prioritizing capital expenditure minimization.
- Utilities:Grid operators procure VPI-processed units through multi-year framework agreements bundling predictive maintenance and digital twin integration. Frankfurt and Amsterdam colocation markets now require OEM-localized technical service teams as contract prerequisites.
- Industrial:Manufacturing facilities specify Class F or Class H insulation for motor control centers and process power distribution. German industrial electrification mandates under the EU Green Deal accelerate replacement of aging oil-filled assets.
- Commercial:Office complexes and retail centers favor polyurethane-based systems below 1 MVA where thermal endurance requirements permit cost-sensitive procurement. Fire-safety codes in urban cores mandate IP-rated encapsulated windings for basement and rooftop installations.
- Residential:Single-phase cast resin units serve apartment substations and district heating integration points. BIS certification requirements in India channel demand toward domestic assemblers with captive thermal testing capabilities.
Highest margin concentration: Utilities. Steepest volume expansion: Industrial.
Technology:
Encapsulation method governs thermal performance, REACH compliance complexity, and technician skill requirements across manufacturing footprints.
- Epoxy Resin:Vacuum pressure impregnation with bisphenol-A or cycloaliphatic formulations delivers Class H thermal endurance and established IEC 60076-11 certification pathways. German and Danish offshore wind specifications consolidate procurement around OEMs with captive impregnation facilities.
- Vacuum Pressure Impregnated:VPI processing penetrates winding insulation with resin under vacuum, eliminating voids that degrade dielectric strength. Grid operators specify this technology for renewable connection substations requiring 30-year service life guarantees.
- Polyurethane:Lower-cost encapsulation suits commercial segments below 1 MVA where Class F insulation suffices. Inferior thermal endurance restricts penetration into utility-scale procurement despite favorable material cost structures.
- Composite:Hybrid resin systems blending epoxy and polyurethane characteristics target mid-market industrial applications seeking cost-performance balance. ECHA reformulation cycles for alternative flame-retardant additives delay product recertification timelines.
Dominant revenue share: Epoxy Resin. Gaining share fastest: Vacuum Pressure Impregnated.
Application:
Use case determines loading profiles, environmental exposure, and integration with adjacent power electronics.
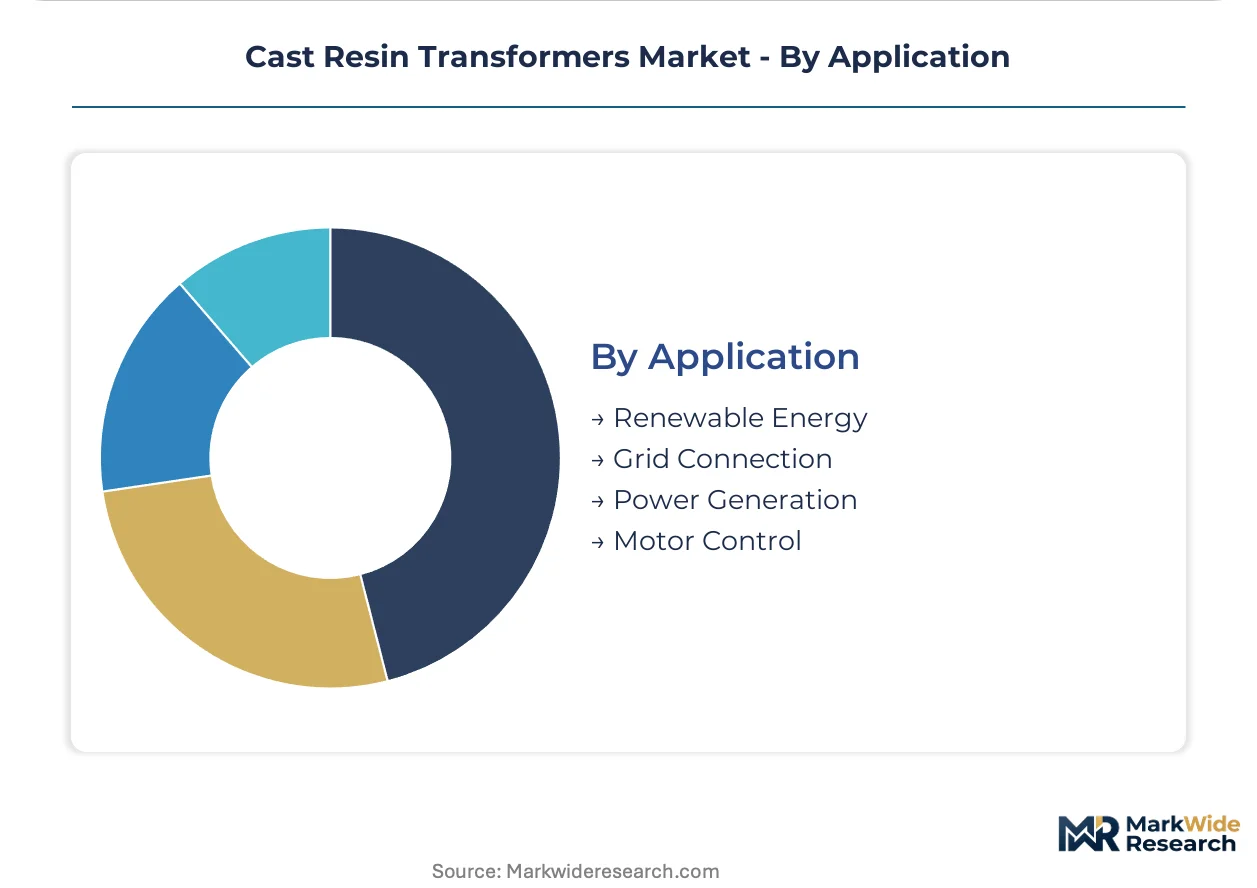
- Renewable Energy:Wind and solar farm substations require cast resin units with wide ambient temperature operating ranges and low partial discharge characteristics. Offshore wind projects in the North Sea specify VPI-processed transformers with marine-grade IP ratings.
- Grid Connection:Transmission interface points demand high short-circuit withstand capability and harmonic tolerance from inverter-based generation. German TSO procurement frameworks prioritize OEMs with European manufacturing footprints for delivery reliability.
- Power Generation:Cogeneration and backup power installations utilize dry-type units for indoor turbine hall placement. Fire-safety codes in densely populated generation sites prohibit oil-immersed alternatives.
- Motor Control:Variable frequency drive isolation and soft-start applications require transformers with high dv/dt tolerance and common-mode noise rejection. Industrial motor centers specify Class H insulation for frequent starting duty cycles.
Primary volume driver: Grid Connection. Expanding most quickly: Renewable Energy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Epoxy resin foundries in East Asia supply winding materials to transformer assemblers across Germany, India, and the United States. Copper procurement networks concentrate in Chilean mining districts and Chinese smelting corridors. Regional demand patterns diverge sharply between EU decarbonization mandates, Asian industrial electrification, and North American data center construction cycles.
Germany
Industrial electrification under the EU Green Deal drives procurement of Class H insulated units for motor control centers and renewable grid integration. The F-Gas Regulation accelerates phase-out schedules for oil-immersed alternatives in urban substations. Bavarian manufacturing clusters around Nuremberg and Munich host OEM impregnation facilities serving North Sea offshore wind connection points.
United States
Hyperscale data center operators in Northern Virginia and Phoenix metro areas specify dry-type encapsulated windings for indoor server hall installations. OSHA electrical safety standards and NEMA ST-20 govern product specifications and installation practices. Texas ERCOT grid interconnection projects absorb utility-scale three-phase units for renewable energy transmission.
India
BIS certification mandates thermal performance testing for domestic cast resin transformer supply, channeling procurement toward localized assemblers. The PLI scheme incentivizes captive winding fabrication capacity in Maharashtra and Gujarat industrial corridors. Tamil Nadu's renewable energy parks drive demand for dry-type units in solar farm substations.
China
Dual carbon goals under MIIT directives accelerate replacement of aging oil-filled distribution assets in Yangtze River Delta manufacturing zones. GB standards for dry-type transformer efficiency reshape procurement specifications for state grid tenders. Shandong Peninsula wind farms specify marine-grade IP ratings for offshore substation connections.
Netherlands
Amsterdam and Frankfurt colocation markets require OEM-localized technical service teams as prerequisites for maintenance bundling contracts. REACH flame-retardant additive restrictions force reformulation cycles that compress procurement timelines for Dutch utilities. Rotterdam port electrification projects specify VPI-processed units for shore power infrastructure.
Cast Resin Transformers Market Competitive Landscape
Capacity expansion dominates the current landscape as OEMs respond to EU F-Gas Regulation phase-out deadlines and data center procurement surges. The vendor base stratifies across three tiers: integrated electrical conglomerates with captive resin casting facilities, regional assemblers dependent on outsourced winding supply, and specialized dry-type transformer pure-plays. Strategic archetypes include technology leaders differentiating through vacuum pressure impregnation expertise, scale-driven manufacturers optimizing procurement across copper and epoxy resin markets, and service bundlers capturing long-term maintenance contracts. Geographic expansion and strategic partnerships represent the dominant competitive vectors as players establish localized technical teams in priority markets.
Among integrated European electrical conglomerates, Siemens Energy and ABB exemplify the technology-leader archetype through their established VPI processing capabilities and utility-scale order execution. Hitachi Energy occupies a position bridging Asia-Pacific manufacturing scale with European certification pathways. Schneider Electric represents the service-bundling vector through its integrated power distribution portfolio. These three anchors demonstrate how competitive positioning crystallizes around resin casting expertise, regional manufacturing footprints, and long-term service contract capture rather than transactional equipment pricing alone.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens Energy |
| Eaton |
| Fuji Electric Co. Ltd. |
| Hitachi Energy |
| ABB |
| General Electric |
| Bharat Heavy Electricals Limited |
| CG Power & Industrial Solutions |
| Others |
Pricing and Supply Chain Analysis
Utility-scale procurement officers in Germany and the Netherlands concentrate buying power around OEMs bundling long-term service agreements with equipment sales, anchoring pricing models to predictive maintenance contracts rather than transactional unit costs. This buyer archetype dominance forces price differentiation through warranty scope and localized technical team availability rather than base equipment discounts.
Pricing Analysis
Warranty and service-bundling terms separate premium-tier OEMs from standard assemblers in cast resin transformer procurement. Three-tier pricing structure across premium, standard, and economy levels reflects VPI processing certification, REACH-compliant flame-retardant formulations, and IP rating validation tiers. Cost compression in polyurethane-based commercial segments below 1 MVA intensifies because raw material volatility squeezes foundry margins. Commercial buyers in retail and office complexes exhibit highest price sensitivity, while data center operators in Frankfurt and Amsterdam prioritize localized service teams over lowest-bid procurement.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Northern Virginia and Phoenix data center operators, bypassing distributor markups for utility-scale three-phase units. Epoxy resin foundries in China and South Korea feed winding materials to European assemblers, while copper sourcing rests on Chilean mining districts and Chinese smelting corridors. Single-source vulnerability concentrates in East Asian foundry capacity for vacuum pressure impregnation materials. Distribution runs through regional transformer assemblers in India and Germany serving localized BIS and CE certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation and REACH flame-retardant restrictions erect compliance moats that favor incumbent OEMs with captive resin casting facilities and established IEC 60076-11 certification pathways, marginalizing smaller assemblers dependent on outsourced supply.
For Market Incumbents: Anticipate REACH reformulation cycles compressing procurement timelines for German utilities by securing alternative flame-retardant additive certifications ahead of ECHA deadlines. Prioritize backward integration into epoxy resin compounding to insulate margins from raw material volatility threatening outsourced winding supply. Defend against emerging regional assemblers in India by embedding digital twin capabilities into long-term service agreements for utility fleets. For New Entrants and Emerging Players: Begin with BIS-certified domestic assembly in Maharashtra and Gujarat industrial corridors, where thermal testing mandates channel procurement away from import-dependent supply. Target commercial segments below 1 MVA ratings where polyurethane cost structures offset inferior thermal endurance specifications. Pursue shore power infrastructure projects in Rotterdam and other port electrification programs requiring marine-grade IP ratings with shorter qualification cycles than utility-scale renewable connections. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European assemblers with stranded VPI technician expertise and pending REACH recertification timelines in Germany and the Netherlands. Long-term viability over the next decade hinges on captive impregnation facilities and localized service team density in priority colocation markets. Monitor ECHA additive approval announcements as inflection indicators for procurement timeline normalization and margin recovery in reformulation-exposed supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Captive VPI Facility Investment | Consolidates margin pools around OEMs processing windings in-house rather than outsourcing to East Asian foundries. |
| REACH-Compliant Resin Reformulation | ECHA flame-retardant additive restrictions force certification cycles that delay product launches for non-compliant assemblers. |
| Localized Technical Service Teams | Frankfurt and Amsterdam colocation providers now require OEM-localized maintenance capacity as contract prerequisites. |
| Digital Twin Integration | IoT sensor convergence with resin-encapsulated windings enables predictive maintenance contracts displacing transactional equipment sales. |
| India BIS Certification Expansion | Domestic thermal testing mandates create localized production incentives favoring assemblers with captive testing capabilities. |
Research Methodology
Independent corroboration across utility procurement officers, resin compound technical directors, and vacuum pressure impregnation facility managers underwrites the qualitative findings in this study. Primary interviews with OEM strategic planning leads, data center facility managers in Northern Virginia and Frankfurt, and ECHA regulatory affairs specialists combined with secondary validation from IEC 60076-11 certification databases, EU F-Gas Regulation implementation reports, and BIS thermal testing protocol documentation. Bottom-up aggregation of segment-level demand and top-down reconciliation with macroeconomic electrification trends established analytical coherence.
Comparable-period anchoring to historical utility procurement cycles and data center construction timelines structured the forecast window across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, encapsulation technology, and application use case alongside regional regulatory cluster differentiation. CAGRs derived from trend-line extrapolation of procurement volumes adjusted for F-Gas Regulation phase-out schedules and building electrification code adoption curves. Forecast inputs incorporated raw material price elasticity assumptions for copper and epoxy resin markets.
Underlying measurement precision varies by segment; utility-scale three-phase and VPI-processed categories carry tighter precision than emerging polyurethane commercial applications. Forecasts reflect documented assumptions regarding REACH compliance timelines and offshore wind connection substation deployment rates. Periodic stress-testing of base assumptions is recommended against ECHA additive approval announcements and data center capex cycle inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
United States Power Transformer Market
Transformers
Traction Transformer Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
Air Cooled Transformer Market
Transformers
Power Transformer Market
Transformers
Middle-East Smart Transformer Market
Transformers
North America Transformer Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
Europe Oil Filled Distribution Transformer Market
Transformers
Uninhibited Transformer Oil Market
Transformers
Three Phase Transformer Market
Transformers
Box Transformer Substation Market
Transformers
Asia-Pacific Transformer Market
Transformers
Smart Transformer Market
Transformers
South America Transformer Market
Transformers
Rectifier Transformers Market