
 Current Transformer Market | 2026-2036
Current Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Current Transformer Market Intelligence
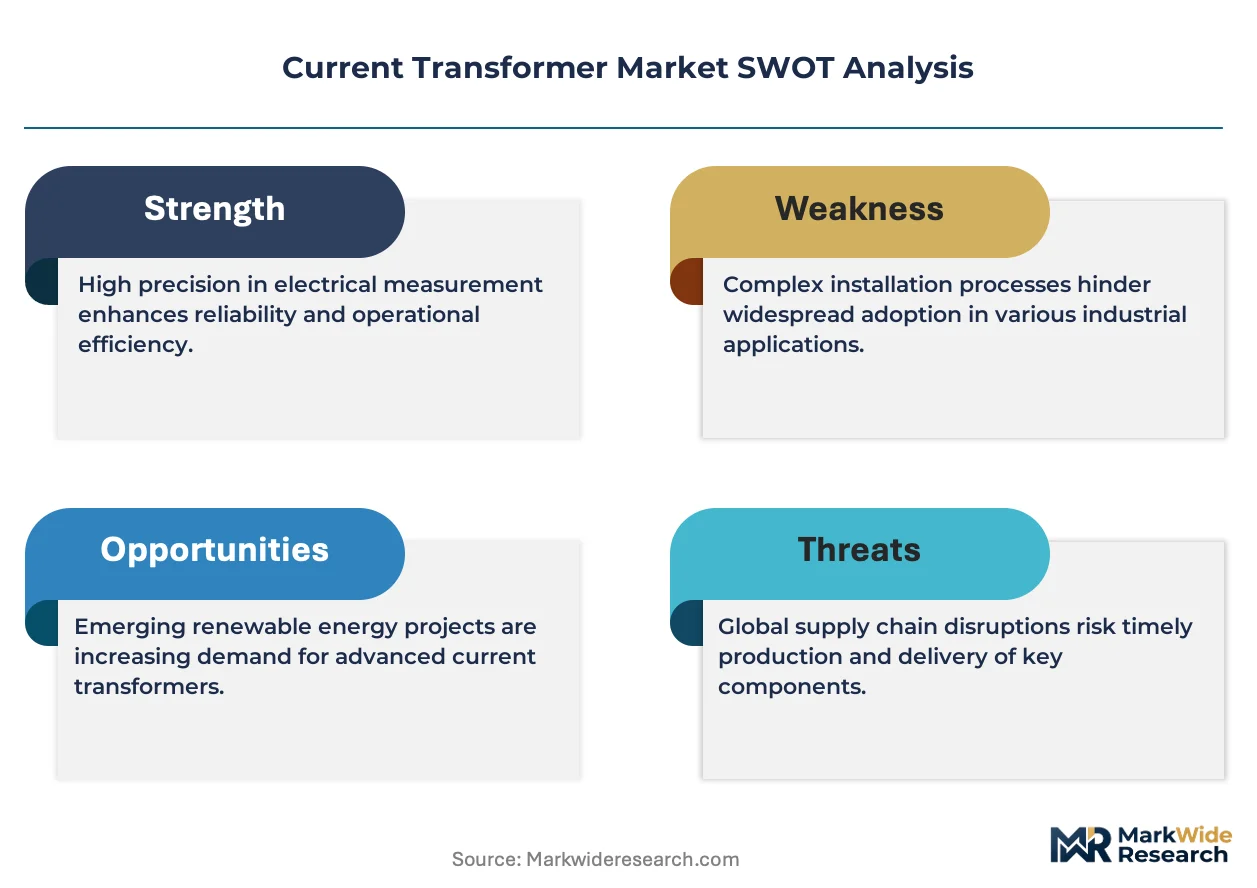
The divergence in performance requirements for grid protection versus basic metering is repositioning the competitive landscape for current transformers. High-specification, digital-ready units for complex protection systems command a premium, a segment where Siemens Energy leverages its extensive grid technology portfolio. Conversely, the commodity segment for standard metering applications is highly competitive, where Schneider Electric competes on scale and distribution channel access. Hitachi Energy specializes in high-voltage applications, differentiating through reliability for transmission networks.
A current transformer is an instrument transformer designed to produce an alternating current in its secondary winding which is proportional to the AC in its primary. These devices, defined by their accuracy class and burden rating, enable the safe measurement and monitoring of high currents. Within applications, protection systems represent the highest-value segment due to stringent performance needs. The utilities end-user segment continues to dominate purchasing volume, driven by grid upgrades and replacement cycles.
Compliance with International Electrotechnical Commission (IEC) 61869 standards is fundamental for market access, defining performance and testing protocols. In parallel, regional requirements such as ANSI/IEEE C57.13 in the United States and specific GB standards in China dictate design and safety specifications for local markets. Vendor success will depend on navigating this fragmented standards environment while investing in digital and smart transformer capabilities.
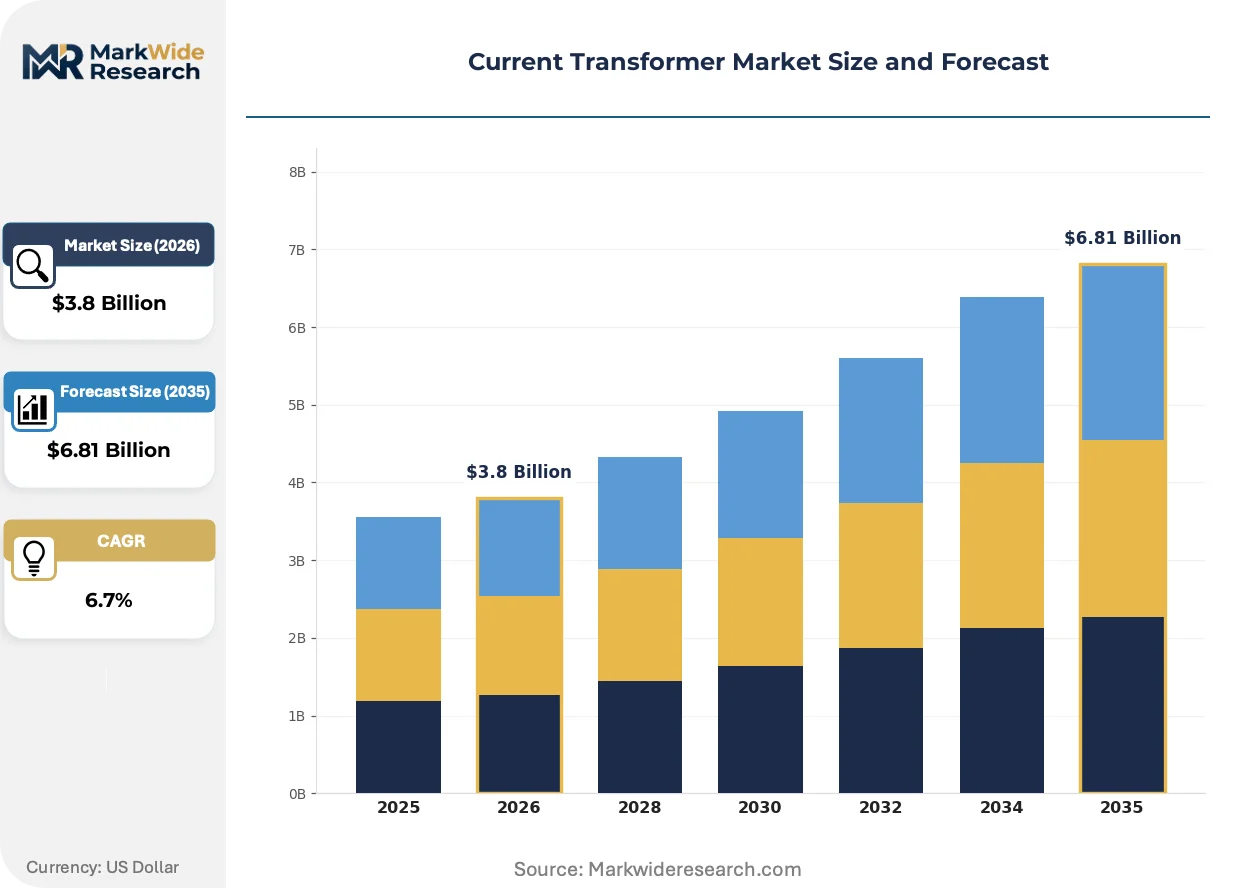
Market Dynamics
The bifurcation of performance requirements for protection versus metering applications is the central force shaping the current transformer market. Grid modernization mandates high-accuracy, digital-ready units for complex protection systems, while the standard metering segment remains a volume-driven commodity market defined by price and scale.
Growth Catalysts
- Smart Grid Mandates:Government policies in countries like India and across the European Union promoting smart meter rollouts directly stimulate demand for metering-class current transformers.
- Renewable Energy Integration:The construction of new substations to connect utility-scale solar and wind farms to the grid requires a significant volume of both protection and metering transformers for monitoring and safety.
- Infrastructure Development in China:Massive state-led investment in China's power transmission and distribution network, guided by its dual carbon goals, provides a continuous stream of large-scale projects.
Market Restraints
- Raw Material Volatility:Fluctuations in the price of high-grade electrical steel and copper directly impact manufacturing costs, creating margin pressure, particularly in the competitive metering segment.
- Alternative Sensing Technologies:The emergence of Rogowski coils and optical current sensors presents a substitution threat in specific applications, such as retrofits and high-frequency monitoring, where they offer installation advantages.
- Fragmented Standards Compliance:The need to meet divergent standards, such as IEC 61869 globally, ANSI/IEEE C57.13 in the US, and specific GB standards in China, increases design and testing complexity.
Strategic Opportunities
- Digital Output Transformers:Developing current transformers with native IEC 61850 digital outputs offers a path to higher margins by serving the growing demand for fully digital substations and advanced protection schemes.
- Data Center Power Monitoring:The rapid expansion of hyperscale data centers creates a high-value opportunity for compact, high-accuracy current transformers used in power distribution units and busway monitoring systems.
- Grid Expansion in Southeast Asia:Electrification projects and industrialization in countries like Vietnam and Indonesia present significant greenfield opportunities for vendors able to navigate local procurement and partnership requirements.
Industry Challenges
- Legacy System Integration:Utilities face significant technical hurdles and costs when integrating modern digital current transformers into existing substations that rely on analog wiring and protocols.
- Power Engineering Skills Gap:A shortage of engineers skilled in both traditional high-voltage power systems and modern digital communication protocols complicates the deployment of advanced protection schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Current Transformer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wound, Bar, Laminate, Core Applications: Power Measurement, Protection Systems, Metering, Circuit Monitoring End User: Utilities, Industrial, Commercial, Residential Technology: Analog, Digital, Smart, Passive |
| Companies Covered | Siemens Energy, ABB, Schneider Electric, Eaton Corporation, Hitachi Energy, General Electric, ARTECHE, CG Power & Industrial Solutions, NISSIN ELECTRIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Current Transformer Market Strategic Shifts & Innovations
The evolution of current transformers is defined by the dual pressures of digitalization and performance standardization. These forces are fundamentally changing product design, compliance requirements, and how end-users specify and deploy these critical grid components, separating value-added and commodity segments more distinctly.
Low-Power Instrument Transformers (LPITs) represent a significant product evolution, providing a low-voltage or digital signal instead of a traditional secondary current. Utilities and industrial facility operators are adopting LPITs for new digital substations due to improved safety and smaller footprints. This technology is converging with fiber optic communication networks to enable fully digital measurement chains, eliminating analog signal paths and associated errors.
Adoption of the IEC 61869 series of standards is creating a unified global framework for instrument transformer performance, testing, and digital interfaces. This standardization simplifies product development for manufacturers but also raises the bar for compliance and testing capabilities. The protection and control segment is most affected, as vendors must validate performance against stringent transient response and accuracy requirements defined by the standard.
A notable shift in purchasing behavior involves utilities specifying complete, type-tested protection and control panels rather than individual components. This disrupts the traditional channel of selling standalone current transformers directly to panel builders or end-users. The trend is most visible in critical infrastructure projects in Europe and North America, where reducing on-site integration risk is a primary objective for asset owners.
Current Transformer Market Segmentation
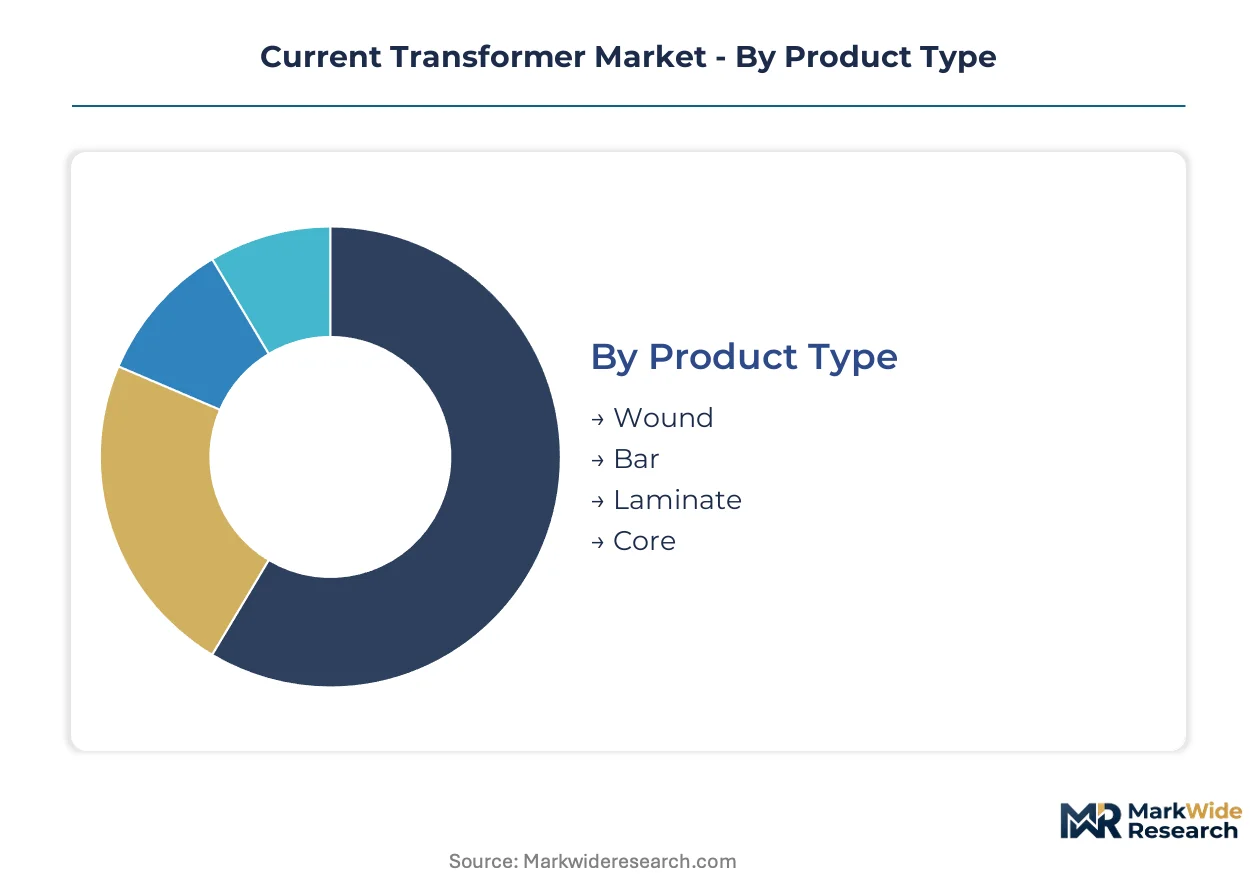
A detailed segmentation of the current transformer market illuminates the diverse performance needs and technological shifts influencing product development and procurement. Understanding these distinct segments helps manufacturers align their offerings with specific end-user requirements and regulatory mandates. This breakdown reveals where value creation and volume demand are most concentrated.
Product Type:
The current transformer market's product types are experiencing varied replacement and upgrade cycles, influencing manufacturing priorities and investment in new designs.
- Wound:These current transformers feature a primary winding with multiple turns, providing high accuracy for measuring low primary currents. Demand is concentrated in older grid infrastructure upgrades in Europe, where precise measurement for legacy protection systems is critical.
- Bar:Bar-type current transformers integrate the primary conductor directly through a central opening, simplifying installation in high-current busbar applications.
- Laminate:Laminate core current transformers offer compact designs and are often used in switchgear and motor control centers for space-constrained environments.
- Core:Core-type current transformers are foundational, with the primary conductor passing through the core opening, suitable for a wide range of current ratings. Expansion is driven by new substation construction in China, which requires robust and reliable core designs for its expanding transmission networks.
Volume placements concentrate in Core type current transformers; the faster expansion belongs to Wound type units for specialized retrofits.
Applications:
Application segments exhibit distinct margin profiles, reflecting the varying performance demands and regulatory compliance costs associated with each use case.
- Power Measurement:These applications focus on monitoring energy consumption and generation within industrial and utility settings for billing and operational analysis.
- Protection Systems:This segment demands high-accuracy, transient-response current transformers critical for safeguarding grid infrastructure against faults and overloads. Demand is particularly strong in North America for utility grid modernization projects, driven by stringent reliability standards from FERC.
- Metering:Metering applications require reliable, cost-effective current transformers for revenue billing and energy management in commercial and residential contexts. Growth is stimulated by smart meter rollouts in India, where government mandates promote widespread deployment.
- Circuit Monitoring:Circuit monitoring applications utilize current transformers for real-time fault detection and operational diagnostics within electrical distribution panels.
The integration of advanced digital outputs is driving demand within Protection Systems, while Metering maintains a steady base through smart grid initiatives.
End User:
End-user segmentation reveals distinct purchasing behaviors and technical specifications, influenced by operational scale and regulatory environments across different customer types.
- Utilities:This segment represents the largest purchasing volume, driven by extensive grid modernization, renewable energy integration, and replacement of aging infrastructure. Demand is concentrated in the United States and Europe, where significant investment targets grid stability and efficiency.
- Industrial:Industrial end-users require current transformers for process control, motor protection, and energy management within manufacturing plants and heavy industries. This segment sees demand from new factory construction in Southeast Asia, supporting rapid industrialization.
- Commercial:Commercial applications include power distribution monitoring and energy management in office buildings, data centers, and retail complexes.
- Residential:Residential current transformers are primarily used in smart home energy monitoring systems and localized solar power installations.
Demand from Utilities is characterized by stringent regulatory compliance and long asset lifecycles, whereas Industrial end-users focus on operational reliability and safety.
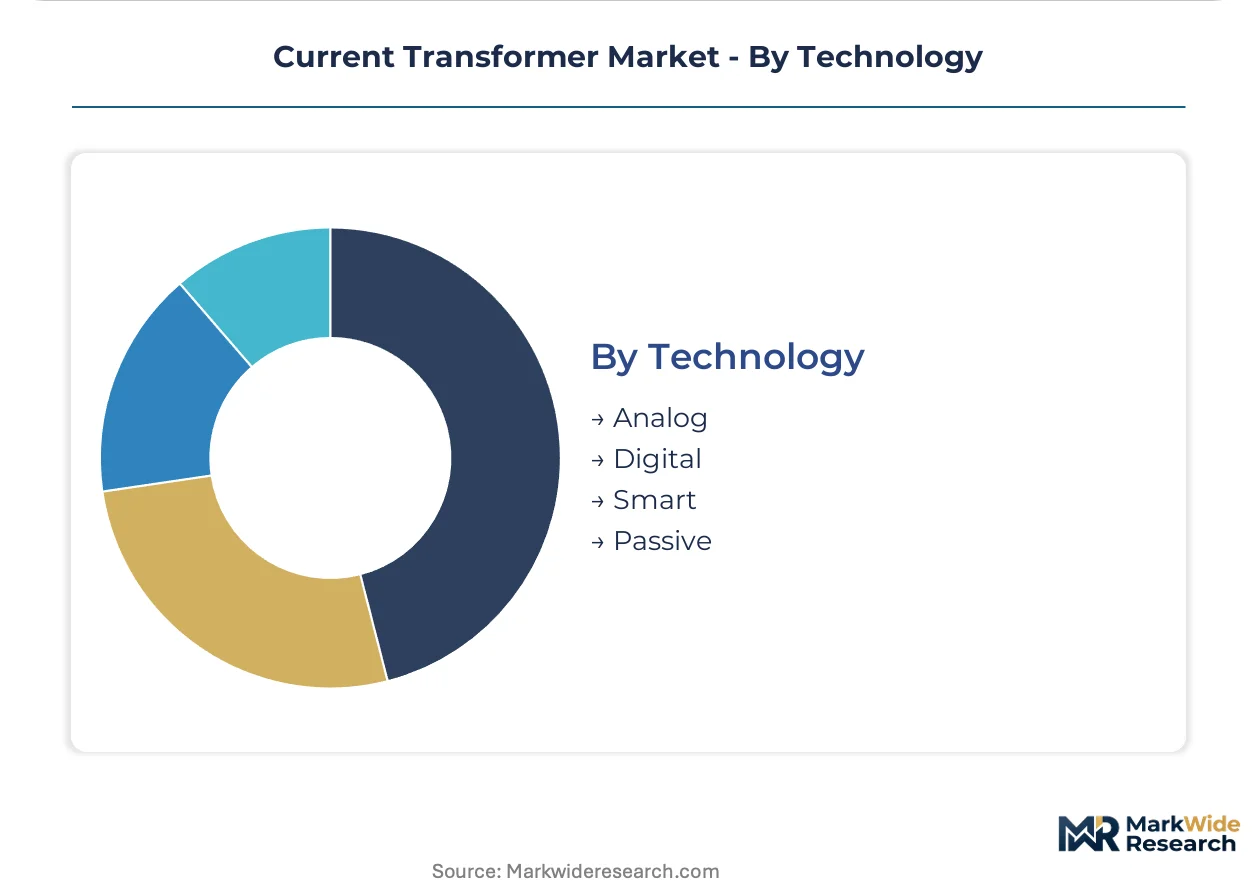
Technology:
Technology segmentation reflects varying stages of market maturity, with established analog solutions coexisting alongside rapidly developing digital and smart alternatives.
- Analog:Analog current transformers provide traditional current signals, widely used in legacy protection and metering systems due to their proven reliability.
- Digital:Digital current transformers integrate electronic components to provide a digital output signal, supporting advanced grid automation and IEC 61850 protocol compliance. This technology is gaining traction in new substation builds in Germany, driven by European Union mandates for smart grid interoperability.
- Smart:Smart current transformers incorporate advanced sensing, communication, and processing capabilities for real-time data and predictive analytics. Their adoption is accelerating in data center power monitoring applications globally, where precise load balancing and efficiency optimization are paramount.
- Passive:Passive current transformers operate without external power, relying solely on the primary current to induce a proportional secondary current.
The shift towards Digital and Smart technologies reflects a push for higher data integration and enhanced grid intelligence, moving beyond traditional Analog solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's robust industrial base and extensive power grid infrastructure drive significant demand for current transformers, reflecting China's broader commitment to grid modernization. The country's dual carbon goals accelerate investment in renewable energy integration, necessitating advanced monitoring and protection solutions across its vast transmission networks. This focus creates a continuous stream of large-scale projects.
China
Massive state-led investment in power transmission and distribution fuels demand for current transformers, particularly for core-type units. China's GB standards dictate specific design and safety specifications for local markets, ensuring compliance for manufacturers. New substation construction in the Yangtze River Delta region requires robust and reliable core designs for its expanding transmission networks.
United States
Utility grid modernization projects drive demand for high-accuracy protection systems, particularly in North America. FERC reliability standards mandate stringent performance requirements for grid infrastructure against faults and overloads. Investments in Texas and California target grid stability and efficiency, integrating advanced current transformer technologies for enhanced monitoring.
Germany
New substation builds in Germany gain traction, propelled by European Union mandates for smart grid interoperability. Compliance with IEC 61869 standards is fundamental for market access, defining performance and testing protocols. The energy transition in Bavaria requires advanced digital current transformers to support renewable energy integration and grid automation.
India
Smart meter rollouts directly stimulate demand for metering-class current transformers across India. Government policies promote widespread deployment, creating a steady base for reliable, cost-effective units. Electrification projects in Maharashtra and Gujarat require significant volumes of current transformers for revenue billing and energy management.
Vietnam
Electrification projects and rapid industrialization in countries like Vietnam present significant greenfield opportunities for current transformer vendors. The country's growing manufacturing sector requires reliable power infrastructure for process control and energy management. New factory construction near Ho Chi Minh City supports increased demand for industrial-grade current transformers.
Current Transformer Market Key Industry Players
Premium-margin players sit above commodity-margin players across the performance and technology spectrum within the current transformer market. The competitive landscape bifurcates into segments requiring high-specification, digital-ready units and those focused on cost-effective, standard metering applications. Strategic archetypes include specialized high-voltage providers, integrated grid technology firms, and volume-driven component suppliers. Geographic expansion into emerging markets and portfolio diversification into smart grid solutions represent dominant competitive moves.
Specialists in grid technology, such as Siemens Energy, leverage extensive portfolios to serve complex protection systems. Schneider Electric occupies a position focused on scale and distribution channel access, competing effectively in the commodity segment for standard metering applications. Hitachi Energy represents a high-voltage archetype, differentiating through reliability for critical transmission networks.
| Leading Market Players |
|---|
| Siemens Energy |
| ABB |
| Schneider Electric |
| Eaton Corporation |
| Hitachi Energy |
| General Electric |
| ARTECHE |
| CG Power & Industrial Solutions |
| NISSIN ELECTRIC |
| Others |
Cost & Logistics Intelligence
Vertical integration into core material production anchors both manufacturing supply positions and pricing power for certain current transformer specialists. This strategic control mitigates raw material volatility and ensures consistent quality for high-specification units.
Pricing Analysis
Value-based pricing anchors the premium segment, where current transformers for protection systems command higher prices due to stringent performance and reliability requirements. Price differentiation stems from accuracy class certifications like IEC 61869 compliance and specialized digital output capabilities. Pricing pressure stems from raw material volatility, particularly in the commodity metering segment. The metering segment exhibits high price sensitivity, while protection system buyers prioritize performance over cost.
Supply Chain Analysis
High-grade electrical steel and copper supply rests on a concentrated base of producers, notably in China and Europe. Raw material volatility presents a structural risk across the current transformer supply chain, impacting manufacturing costs. The fragmented standards environment, including IEC 61869 and ANSI/IEEE C57.13, adds complexity to component sourcing and design. Downstream distribution is shifting, with utilities increasingly specifying complete, type-tested protection and control panels rather than individual current transformers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a supply-constrained story, with specialized manufacturing capacity for high-accuracy digital current transformers propping pricing in the premium segments.
For Market Incumbents: Deepen investment in digital output transformer capabilities to serve the growing demand for fully digital substations. Focus on securing long-term supply agreements for critical raw materials like high-grade electrical steel to counter price volatility. Leverage extensive grid technology portfolios to offer integrated protection and control solutions, mitigating the threat from alternative sensing technologies. Invest in training programs to address the power engineering skills gap.
For New Entrants and Emerging Players: Capture white-space opportunities in data center power monitoring, where compact, high-accuracy current transformers are in demand. Target greenfield grid expansion projects in Southeast Asia, such as Vietnam, by offering cost-effective, standards-compliant metering and protection units. A specialized go-to-market angle could involve developing modular, easy-to-integrate digital current transformers for retrofit applications in legacy substations.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquiring digital technology specialists or niche providers with strong intellectual property in smart transformer capabilities. The long-term viability for current transformer investments spans a 5-10 year window, driven by ongoing grid modernization and renewable energy integration. A key signal to watch is the accelerated adoption rate of IEC 61850 digital substations in major utility markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Digital Output CT R&D | Enhances product portfolio for advanced grid automation and IEC 61850 compliance. |
| Secure Raw Material Supply Contracts | Mitigates margin pressure from high-grade electrical steel and copper price volatility. |
| Expand into Southeast Asian Markets | Accesses significant greenfield opportunities driven by electrification and industrialization. |
| Develop Compact CTs for Data Centers | Addresses a high-value, rapidly expanding application segment requiring precise power monitoring. |
| Strengthen Standards Compliance Expertise | Ensures market access and competitive advantage across diverse regional regulatory environments like China's GB standards. |
Research Approach
Independent corroboration across primary interviews, secondary research, and industry reports underwrites the qualitative findings and quantitative projections within this analysis. The study combined insights from utility planning officers, substation engineers, smart grid architects, and component manufacturers. Secondary data sources included IEC 61869 standards documents, national grid development plans, and power utility investment reports, ensuring a robust bottom-up and top-down triangulation.
The analytical framework anchored the forecast window to historical reference periods, establishing a baseline for market evolution over the projection horizon. Segmentation dimensions modeled included product type, application, end-user, technology, and accuracy class. Compound annual growth rates were derived from a detailed assessment of market drivers and restraints, with smart meter rollout targets and renewable energy capacity additions serving as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw material price volatility and geopolitical shifts impacting infrastructure development. All projections reflect assumptions about technological adoption rates and regulatory stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Oil Filled Transformer Market
Transformers
Phase-Shifting Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
North America Smart Transformers Market
Transformers
India Distribution Transformer Market
Transformers
South America Transformer Market
Transformers
Europe Transformer Market
Transformers
Power Transformer Market
Transformers
Amorphous Core Transformers Market
Transformers
Rectifier Transformers Market
Transformers
Global Large Power Transformers Market
Transformers
Transformer Steel Market
Transformers
Europe Smart Transformers Market
Transformers
Liquid-Immersed Transformers Market
Transformers
Transformer Core Market
Transformers
Cast Resin Transformers Market