
 India Gas Insulated Switchgear Market | 2026-2036
India Gas Insulated Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
India Gas Insulated Switchgear Market Foresight
The India gas insulated switchgear market is restructuring around a widening gap between premium digital-hybrid systems and conventional commodity units. ABB Ltd leverages its digital substation portfolio to command positions in smart grid corridors, while Bharat Heavy Electricals Limited anchors large-scale public sector procurement through its manufacturing scale across multiple plant locations. Siemens Energy competes on technology leadership in high-voltage GIS with integrated monitoring capabilities.
Gas insulated switchgear encloses electrical conductors and circuit breakers within sealed chambers pressurized with sulfur hexafluoride or alternative insulating gases, achieving dielectric strength far exceeding air-insulated alternatives in footprints less than one-tenth the size. The equipment serves critical functions in high-power density environments where land scarcity, contamination exposure, or altitude constraints prohibit conventional open-air substations. High voltage GIS commands the dominant value share given its role in interstate transmission backbones and ultra-mega power project integration, while digital technology segments are expanding fastest as utilities deploy sensor-enabled predictive maintenance architectures. Modular product configurations are gaining traction among industrial end users seeking phased capital deployment and reduced commissioning downtime.
BIS certification requirements and CEA technical standards for substation equipment govern product approval pathways and operational safety benchmarks across Indian utilities. The Electricity Act framework and state-level regulatory commissions shape procurement timelines and tariff-linked investment cycles for transmission infrastructure. Stakeholders must weigh sulfur hexafluoride phase-down commitments against alternative gas readiness when committing to long-dated manufacturing partnerships and fleet standardization strategies.
Market Dynamics
The India gas insulated switchgear market is bifurcating around sulfur hexafluoride phase-down mandates, forcing utilities to choose between proven SF6 infrastructure and unproven alternative gas platforms before CEA reliability standards harden.
Growth Catalysts
- CEA substation reliability norms:Central Electricity Authority mandates on fault tolerance and space optimization are compelling transmission utilities to replace aging air-insulated infrastructure with compact GIS configurations in metropolitan corridors.
- Renewable integration clusters:Western and southern state grids in Maharashtra, Gujarat, Tamil Nadu, and Karnataka require higher switching capacity to manage intermittent solar and wind power flows through interstate transmission backbones.
- Urban load density compression:Municipal land scarcity in Delhi NCR, Mumbai, and Bangalore is eliminating conventional substation footprints, directing capital toward sealed-chamber systems occupying less than one-tenth the physical area.
Market Restraints
- SF6 gas supply concentration:Domestic sulfur hexafluoride production remains limited, exposing utilities to import dependency and price volatility from Chinese and European chemical suppliers.
- Alternative gas technical immaturity:Fluoronitrile and fluoroketone mixtures lack long-term performance data at Indian ambient temperature ranges, creating fleet standardization risk for multi-decade asset commitments.
- BIS certification timelines:Bureau of Indian Standards type-testing protocols for new gas formulations extend product approval cycles, delaying commercial deployment of next-generation switchgear platforms.
Strategic Opportunities
- PLI scheme manufacturing incentives:Production-Linked Incentive allocations for power sector equipment are enabling domestic GIS assembly scale-up, reducing landed cost premiums against imported European and Japanese systems.
- Digital predictive maintenance convergence:Sensor-enabled condition monitoring integrated with SCADA architectures is opening service revenue streams for utilities seeking to unbundle maintenance from capital procurement.
- Eastern and northeastern grid expansion:Underpenetrated state transmission networks in Odisha, West Bengal, and Assam present first-mover positioning for modular GIS configurations supporting phased rural electrification.
Industry Challenges
- SF6 handling technician scarcity:Certified gas recovery and recycling specialists remain concentrated in western Indian industrial corridors, constraining maintenance response times for geographically dispersed installations.
- Legacy AIS-GIS integration complexity:Hybrid substation architectures combining existing air-insulated buswork with sealed-chamber breaker modules demand custom engineering that compresses contractor margins and extends commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Gas Insulated Switchgear Market |
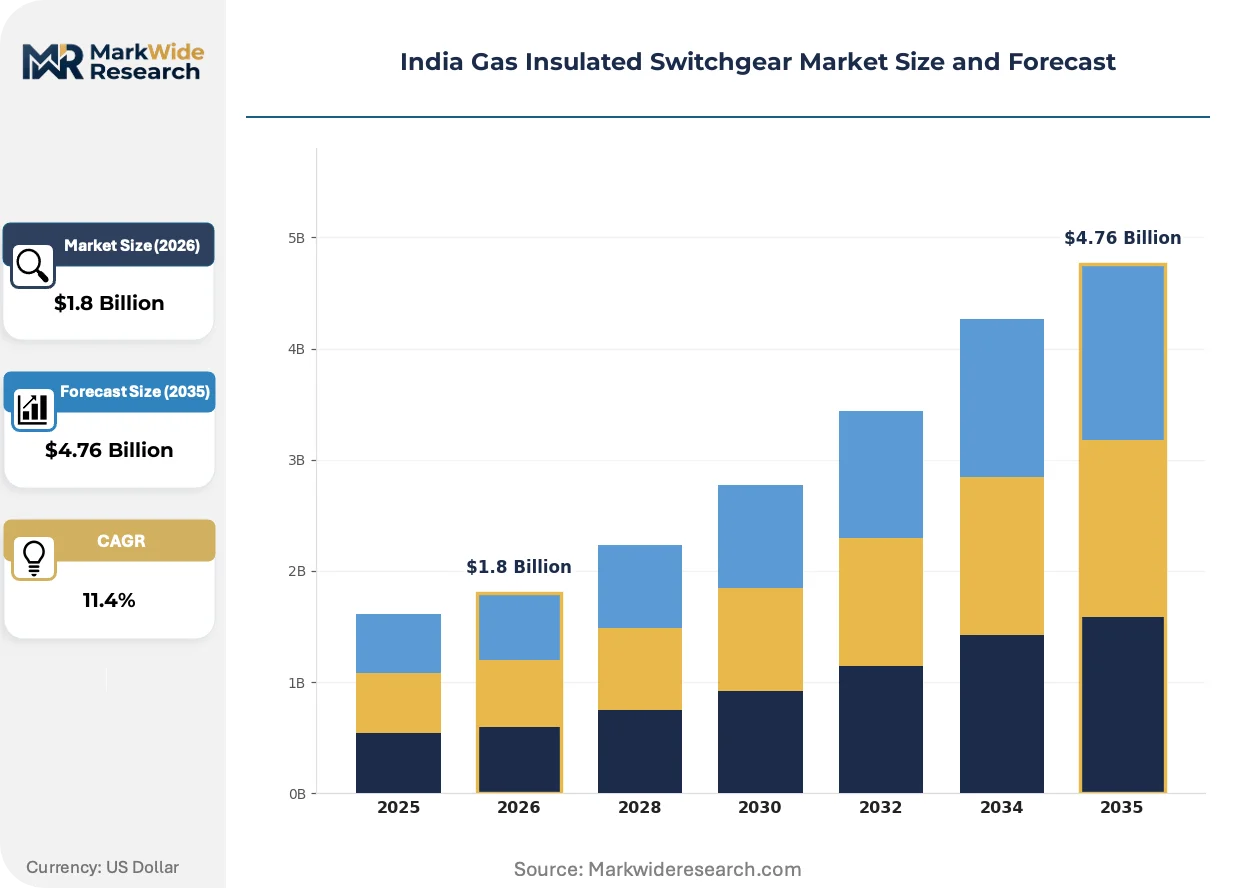
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage, High Voltage, Ultra High Voltage, Modular End User: Power Generation, Transmission Utilities, Renewable Energy, Industrial Installation: Indoor, Outdoor, Substation, Brownfield Technology: Hybrid, Digital, Conventional, Smart |
| Companies Covered | ABB Ltd, Bharat Heavy Electricals Limited, Hitachi Energy Ltd, Mitsubishi Electric Corporation, Eaton Corporation PLC, Schneider Electric SE, Siemens Energy, Larsen & Toubro, General Electric Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Gas Insulated Switchgear Market Shifts & Advancements
Digital substation architectures are reconfiguring how Indian utilities procure, operate, and maintain high-voltage infrastructure, compressing the traditional separation between primary equipment and control systems into unified intelligent platforms.
Hybrid gas technology is decentralizing switchgear deployment patterns across Indian transmission networks. Fluoronitrile-insulated modules achieve comparable dielectric performance to SF6 at moderate pressure differentials, enabling utilities to standardize on single platforms across voltage classes. State transmission utilities in Maharashtra and Gujarat are piloting these systems at 145 kV and 245 kV ratings ahead of anticipated CEA environmental guidelines. This technology is decentralizing capital planning by allowing phased substation expansion without full footprint reconfiguration.
BIS is aligning with IEC 62271-200 standards for sealed pressure systems, tightening type-test requirements for internal arc classification and gas tightness over equipment lifetime. The regulatory consequence is elevating engineering documentation burdens for domestic manufacturers seeking multi-voltage certifications. High-voltage GIS producers serving central public sector undertakings are responding with captive testing facilities to compress approval cycles and reduce third-party laboratory dependency.
Utility procurement patterns are fragmenting between turnkey EPC bundling and unbundled equipment-only purchasing. Industrial captive power consumers in steel, cement, and petrochemical sectors are bypassing traditional distribution utility channels to source GIS directly from manufacturers, demanding modular delivery with self-managed installation. This disintermediation is most visible in Gujarat's Mundra and Hazira industrial corridors, where large consumers negotiate frame agreements independent of state transmission company procurement calendars.
India Gas Insulated Switchgear Market Segmentation
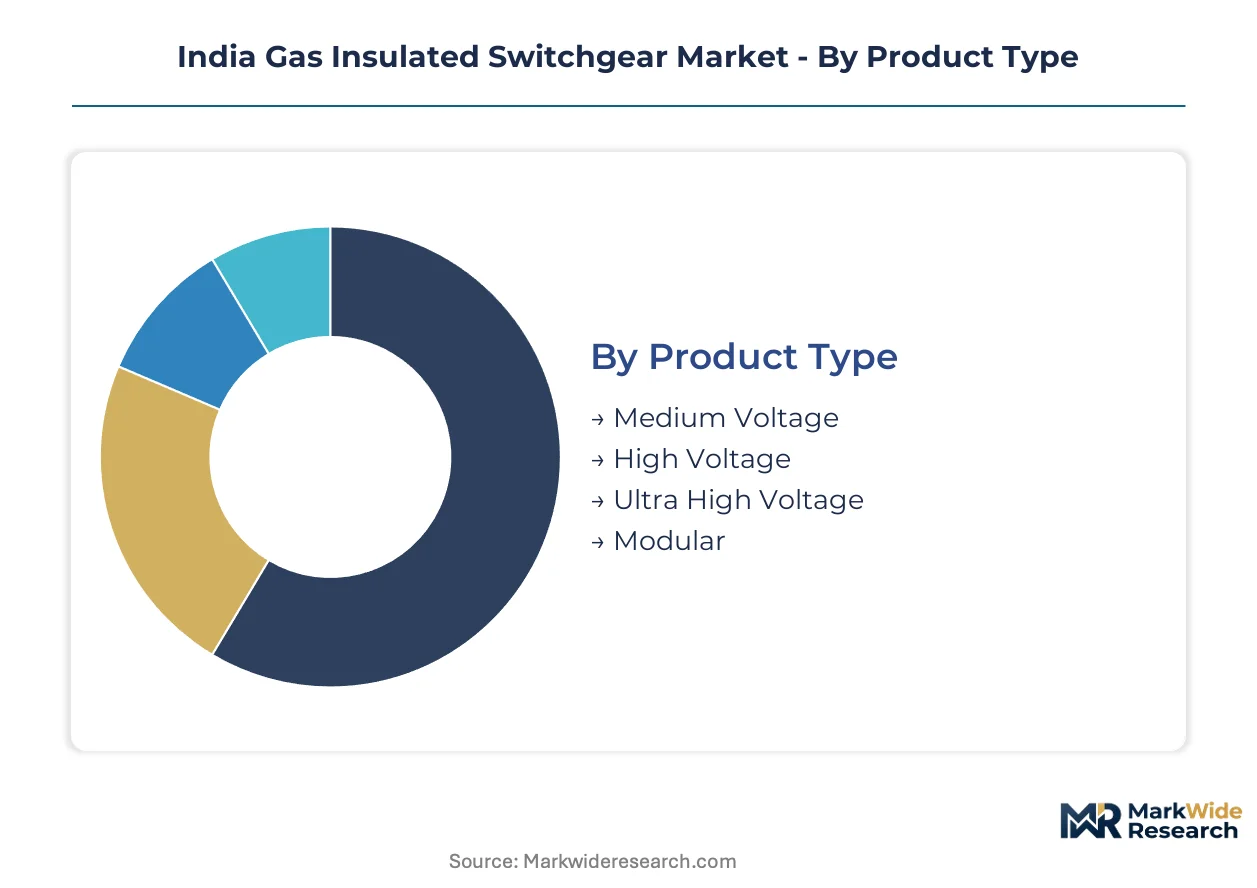
Capital allocation across voltage classes, end-use applications, and installation environments determines procurement patterns in India's GIS market. Utilities prioritize segments offering the optimal trade-off between dielectric performance, spatial compression, and lifecycle reliability under CEA substation norms.
Product Type:
Capital intensity escalates sharply with voltage rating, with ultra high voltage installations demanding specialized manufacturing infrastructure and extended testing protocols.
- High Voltage:Sealed chambers rated 72.5 kV to 245 kV enclose circuit breakers and disconnectors pressurized with sulfur hexafluoride or alternative insulating gases. Interstate transmission backbones across Maharashtra and Gujarat anchor demand as these states integrate renewable clusters requiring higher switching capacity.
- Medium Voltage:Compact 12 kV to 36 kV configurations serve urban distribution networks where municipal land scarcity eliminates conventional air-insulated footprints. Metropolitan corridors in Delhi NCR and Bangalore drive procurement as distribution utilities replace aging outdoor substations with indoor sealed systems.
- Ultra High Voltage:420 kV and above ratings command specialized engineering for ultra-mega power project integration and national grid interconnections.
- Modular:Phased-deployment configurations enable industrial consumers to scale capacity incrementally without full substation reconstruction.
Most installed capacity flows through High Voltage. Expansion is steepest in Modular configurations as industrial users seek capital flexibility.
End User:
Procurement authority concentrates in state transmission companies, though industrial captives are disintermediating traditional utility channels through direct manufacturer relationships.
- Transmission Utilities:State transmission companies in western and southern grids execute the bulk of public sector procurement under CEA reliability mandates. Maharashtra State Electricity Transmission Company and Gujarat Energy Transmission Corporation anchor volume as they densify metropolitan substation networks.
- Industrial:Steel, cement, and petrochemical consumers in Gujarat's Mundra and Hazira corridors negotiate frame agreements independent of state utility procurement calendars. These consumers demand modular delivery with self-managed installation, compressing traditional EPC margins.
- Power Generation:Thermal and hydroelectric plant operators specify GIS for generator switchyard integration where space constraints and contamination exposure prohibit open-air alternatives.
- Renewable Energy:Solar and wind project developers require compact switching infrastructure for pooling substations managing intermittent generation flows.
Transmission Utilities hold the dominant order book. Industrial procurement is climbing fastest as captive power consumers bypass distribution channels.
Installation:
Site constraints and existing infrastructure determine whether utilities deploy greenfield sealed systems or hybrid architectures integrating legacy buswork.
- Indoor:Fully enclosed installations occupy commercial and residential building basements or dedicated substation structures in dense urban cores. Mumbai and Bangalore distribution networks prioritize these configurations to eliminate outdoor footprint entirely.
- Substation:Purpose-built GIS bays within larger substation complexes balance spatial efficiency with maintenance accessibility. State transmission utilities in Tamil Nadu and Karnataka favor this approach for renewable integration clusters requiring staged expansion.
- Outdoor:Weatherproof enclosures extend GIS deployment to industrial zones and peripheral urban areas where indoor construction costs prove prohibitive.
- Brownfield:Retrofit installations demand custom engineering to interface sealed-chamber breaker modules with existing air-insulated buswork, extending commissioning schedules.
Substation deployments carry the largest committed capital. Indoor installations are gaining share fastest as municipal authorities tighten land-use regulations.
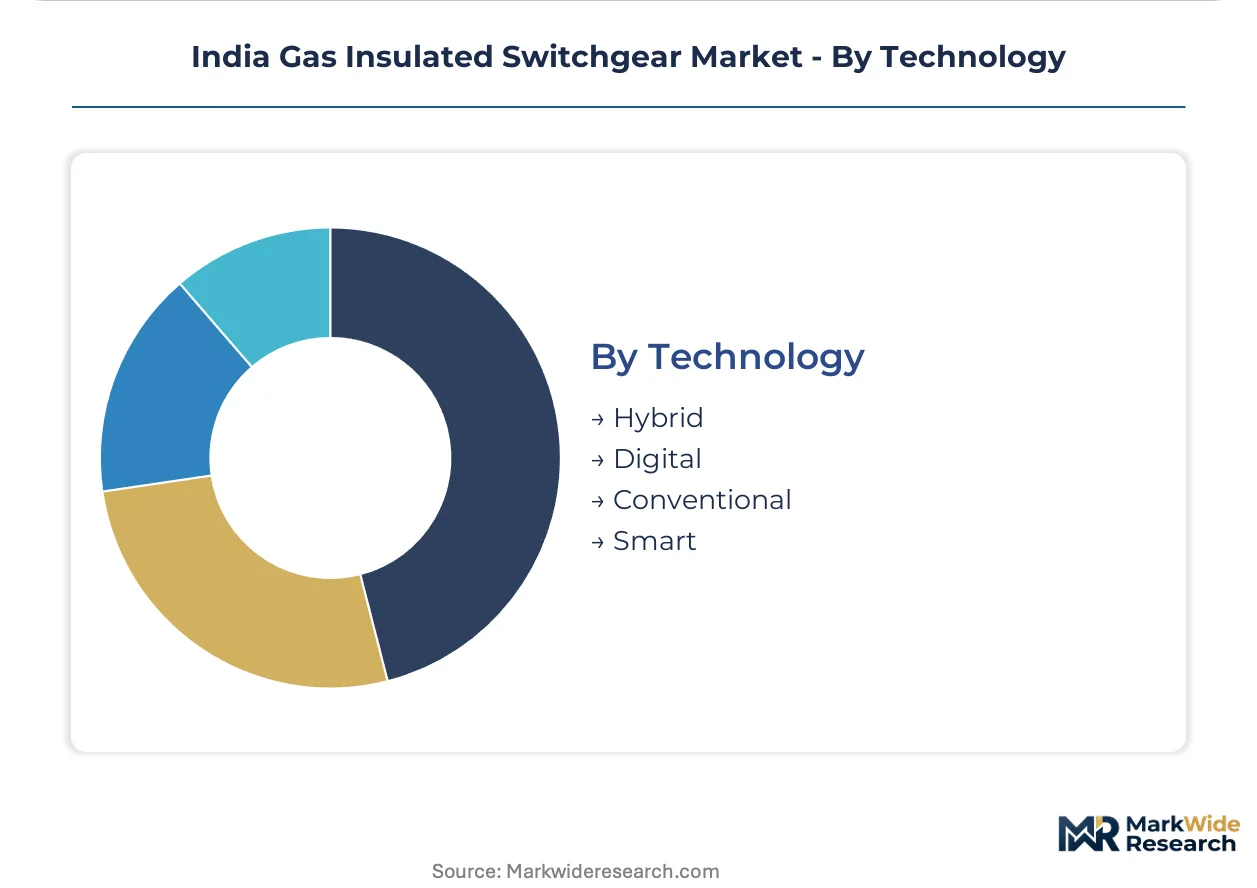
Technology:
Technology selection bifurcates between proven conventional platforms and sensor-enabled architectures requiring integrated SCADA investment.
- Digital:Sensor-integrated platforms enable predictive maintenance through continuous gas pressure, temperature, and partial discharge monitoring. ABB and Siemens Energy compete aggressively in this segment as utilities unbundle maintenance from capital procurement.
- Hybrid:Fluoronitrile-insulated modules achieve SF6-comparable dielectric performance at moderate pressure differentials, allowing single-platform standardization across voltage classes. Maharashtra and Gujarat state utilities pilot these systems at 145 kV and 245 kV ahead of anticipated environmental guidelines.
- Conventional:Proven sulfur hexafluoride-based designs dominate current procurement where utilities prioritize reliability data over emission reduction.
- Smart:Fully integrated intelligent platforms combine primary equipment, control systems, and analytics into unified architectures for smart grid corridors.
Conventional technology retains the installed base majority. Hybrid gas platforms are expanding most quickly as CEA environmental standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's western transmission corridors outpace eastern grids in GIS deployment density, while southern states accelerate renewable integration projects requiring compact switching infrastructure.
Maharashtra
Maharashtra State Electricity Transmission Company densifies metropolitan substation networks across Mumbai and Pune to manage urban load compression. CEA substation reliability norms mandate fault-tolerant configurations that eliminate conventional air-insulated footprints. The Mundra industrial corridor hosts captive power consumers in steel and petrochemical sectors negotiating direct manufacturer frame agreements.
Gujarat
Gujarat Energy Transmission Corporation anchors volume procurement for interstate renewable integration clusters managing intermittent solar and wind flows. State regulators prioritize space-optimized substation designs under municipal land-use tightening in Ahmedabad and Surat. The Hazira industrial belt sees direct GIS sourcing from manufacturers by large consumers bypassing traditional utility channels.
Karnataka
Bangalore distribution utilities replace aging outdoor substations with indoor sealed systems as municipal authorities eliminate conventional footprints in dense urban cores. Karnataka Renewable Energy Development Ltd requires compact switching infrastructure for solar park pooling substations. The state's transmission utility favors staged expansion approaches at renewable clusters in the northern districts.
Tamil Nadu
Tamil Nadu Transmission Corporation deploys purpose-built GIS bays within larger substation complexes balancing spatial efficiency with maintenance accessibility. State procurement cycles align with CEA technical standards for equipment approval pathways. Wind-rich regions in the western districts drive demand for higher switching capacity managing intermittent generation flows.
Delhi-NCR
Distribution utilities in Delhi NCR prioritize fully enclosed indoor installations occupying commercial building basements to eliminate outdoor footprint entirely. Central Electricity Authority norms on substation reliability accelerate replacement of aging infrastructure. The National Capital Region's transmission planners face severe land scarcity directing capital toward sealed-chamber systems.
India Gas Insulated Switchgear Market Competitive Landscape
Top-tier vendors anchor premium digital-hybrid systems, while domestic fabricators compete on public sector procurement scale and manufacturing footprint. The market structures around three tiers: multinational technology leaders with integrated monitoring portfolios, state-backed heavy electrical equipment producers with captive manufacturing scale, and specialized EPC contractors with installation capabilities. Consolidation pressures intensify as CEA certification requirements elevate engineering documentation burdens and compress margins for undifferentiated commodity suppliers. Dominant competitive moves include backward integration into gas handling and recycling services, plus strategic partnerships between technology licensors and domestic assemblers under PLI scheme incentives.
Among multinational technology providers, ABB Ltd and Siemens Energy occupy positions exemplifying the premium digital tier with sensor-enabled predictive maintenance architectures. Bharat Heavy Electricals Limited represents the state-backed manufacturing archetype with multi-plant domestic production scale serving central public sector undertakings. These three anchors illustrate the competitive bifurcation between technology-led service unbundling and capital-efficient equipment supply.
| Leading Market Players |
|---|
| ABB Ltd |
| Bharat Heavy Electricals Limited |
| Hitachi Energy Ltd |
| Mitsubishi Electric Corporation |
| Eaton Corporation PLC |
| Schneider Electric SE |
| Siemens Energy |
| Larsen & Toubro |
| General Electric Company |
| Others |
Supply & Pricing Matrix
State transmission utility consolidation around CEA-mandated digital-hybrid specifications is compressing procurement timelines and forcing manufacturers to absorb certification costs upfront, elevating price floors for unqualified suppliers while rewarding integrated players with service-revenue bundling power.
Pricing Analysis
Capacity additions in domestic assembly under PLI scheme incentives are reshaping price floors for medium-voltage configurations. Three-tier pricing structure across premium digital-hybrid, standard SF6-based, and economy modular tiers separates sensor-integrated platforms with predictive maintenance contracts from conventional sealed-chamber units. Cost compression in the standard tier is intensifying because BIS certification timelines extend engineering documentation burdens. Industrial captive consumers in Gujarat's Mundra corridor exhibit the highest price sensitivity, while central public sector undertakings prioritize reliability data over unit economics.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale transmission procurement, while industrial captives increasingly source through manufacturer-direct frame agreements bypassing EPC intermediaries. Manufacturing concentration rests on India, Germany, and Japan for high-voltage GIS engineering, with sulfur hexafluoride gas supply drawing from Chinese and European chemical producers. Raw material dependencies include specialized aluminum castings, epoxy resin insulators, and precision-machined breaker contacts. Single-source vulnerability in SF6 gas recovery equipment creates maintenance response bottlenecks for geographically dispersed installations. Distribution runs through state transmission company tender processes, OEM-direct industrial agreements, and EPC turnkey bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic manufacturing scale-up under PLI incentives is compressing landed cost premiums against imports, creating margin expansion headroom for players with captive testing facilities and gas-handling service networks.
For Market Incumbents: Acquire certified gas recovery and recycling service networks to anchor maintenance revenue streams and defend against unbundled procurement trends. Deepen backward integration into alternative gas formulation testing to preempt CEA environmental guideline shifts. Lock in frame agreements with Maharashtra and Gujarat state transmission companies before PLI scheme benefits diffuse to second-tier assemblers. For New Entrants and Emerging Players: Capture eastern and northeastern grid expansion in Odisha, West Bengal, and Assam where incumbent service density remains lowest. Target modular GIS configurations for industrial captive consumers seeking phased capital deployment without EPC bundling margins. Enter through technology licensing partnerships with established European or Japanese engineering licensors to compress BIS certification cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic fabricators possessing captive testing infrastructure and multi-voltage BIS certifications. Five-to-ten-year viability hinges on positioning ahead of SF6 phase-down mandates. Target acquisition archetypes include regional EPC contractors with installation capabilities in underpenetrated state grids. Monitor CEA draft environmental guidelines as the critical inflection signal for alternative gas platform readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gas Handling Services | Captive SF6 recovery infrastructure locks in maintenance revenue and accelerates response times for dispersed installations. |
| Alternative Gas Platform Certification | Fluoronitrile-insulated module approval under BIS-IEC alignment secures positioning ahead of CEA environmental mandates. |
| Digital Predictive Maintenance Convergence | Sensor-SCADA integration enables service unbundling from capital procurement for Maharashtra and Gujarat utilities. |
| Modular Product Configuration Scale-Up | Phased-deployment architectures attract industrial captive consumers in Gujarat's Hazira belt seeking capital flexibility. |
| Eastern Grid Expansion Partnership | First-mover positioning in Odisha and Assam transmission networks captures underpenetrated demand before incumbent density builds. |
Research Methodology
Multiple input streams — structured interviews with state transmission utility planning officers, EPC contractor project directors, and GIS manufacturer product heads; secondary validation through CEA technical standards documentation, BIS certification registries, and PLI scheme allocation records; plus customs and trade flow analysis — were reconciled through bottom-up and top-down triangulation to construct segment-level estimates.
Data-stream reconciliation anchored volume projections to modeled deployment across voltage class, end-user archetype, and installation environment dimensions over the projection horizon. CAGRs were derived from utility capital expenditure cycles, renewable integration cluster development timelines, and industrial captive power expansion patterns. Forecast inputs incorporated CEA substation reliability norm implementation schedules and state-level regulatory commission procurement calendar alignment.
SF6 phase-down mandate acceleration, alternative gas platform technical validation delays, and PLI scheme beneficiary concentration are the dominant revision risks to modeled outcomes. Periodic stress-testing of base assumptions against draft CEA environmental guideline releases and BIS type-test protocol updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
Bio-Based Transformer Oil Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
Europe Gas Insulated Switchgear Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Protective Relay Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Electric Vehicle Charging Cables Market
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Industrial Power Supply Market