
 Software Defined Radio Market | 2026-2036
Software Defined Radio Market Size, Share, and Industry Trends Forecast 2026-2036
Software Defined Radio Market Analysis
Defense procurement agencies is reorganizing demand away from legacy hardware contracts toward firmware-upgradeable platforms. BAE Systems plc anchors European supply through its UK-based manufacturing and deep sovereign relationships. L3Harris Technologies, Inc. dominates North American military channels with specialized tactical waveform portfolios. Thales Group extends its position across NATO interoperability frameworks through multiband product specialization.
Software defined radio replaces fixed-function hardware with reprogrammable digital signal processors, field-programmable gate arrays, and software-configurable RF front ends operating across 2 MHz to 6 GHz basebands. The architecture enables dynamic waveform loading, spectrum sensing, and protocol adaptation for military, public safety, and commercial networks. Base station deployments lead in revenue contribution due to infrastructure replacement cycles in telecommunications and defense. Handheld units represent the fastest-expanding product category as dismounted soldier programs prioritize reduced size, weight, and power constraints. Multiband technology captures widening margin pools where single platforms must operate across HF through SHF spectra without hardware swaps.
FCC Part 90 rules govern public safety spectrum allocation and mandate interoperability standards that shape procurement specifications for domestic first responders. EU defense fund mechanisms and NATO STANAG 4204 waveform standards collectively determine product certification requirements and market access across European member states. The Department of Defense's Modular Open Systems Approach directives further constrain supplier architectures toward vendor-neutral interfaces. Stakeholders must monitor evolving encryption mandates and spectrum reallocation proceedings to anticipate platform refresh timelines and compliance-driven replacement cycles.
Market Dynamics
The transition from hardware-defined to firmware-upgradeable radio architectures is compressing replacement cycles and reordering supplier relationships across defense and public safety procurement channels. This structural shift privileges vendors with software-centric engineering capabilities over traditional RF hardware specialists.
Growth Catalysts
- NATO STANAG 4204 waveform standards:Mandated interoperability protocols across member states are forcing platform consolidation toward multiband SDR architectures that eliminate single-purpose radio inventories.
- Cognitive radio capabilities:Dynamic spectrum sensing and protocol adaptation technologies are penetrating military modernization programs in the United States, Germany, and South Korea as force-multiplier investments.
- FCC Part 90 public safety mandates:Interoperability requirements for first responder communications are accelerating municipal and state-level SDR procurement timelines.
Market Restraints
- FPGA and RF component supply concentration:Advanced field-programmable gate arrays and wideband RF front-ends depend on a concentrated supplier base concentrated in East Asian foundries, creating vulnerability to trade policy disruptions.
- Encryption export control regimes:International Traffic in Arms Regulations and comparable EU dual-use controls impose licensing friction on cross-border technology transfers, elongating sales cycles.
- Legacy analog system installed base:Existing hardware-defined radio fleets in defense and public safety represent substantial sunk capital, slowing wholesale architecture transitions despite superior SDR performance.
Strategic Opportunities
- EU defense fund mechanisms:Collective procurement frameworks and joint capability development programs are creating consolidated tender opportunities for interoperable multiband platforms across European member states.
- Commercial 5G-private network convergence:SDR architectures capable of hosting both military waveforms and 3GPP protocols are opening dual-use applications in industrial automation and critical infrastructure.
- Disaggregated procurement models:Open RAN-inspired vendor-neutral interface specifications are enabling modular subsystem suppliers to penetrate historically integrated prime contractor relationships.
Industry Challenges
- RF-digital co-design expertise scarcity:The intersection of microwave engineering, signal processing algorithm development, and embedded software optimization requires rare interdisciplinary talent that defense contractors and commercial vendors compete to secure.
- Security certification timelines:National cryptographic module validation programs impose multi-year approval processes that delay product launches and compress revenue recognition windows.
- Backward compatibility requirements:New platforms must maintain interoperability with decades-old legacy waveforms, constraining architectural optimization and expanding firmware complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Defined Radio Market |
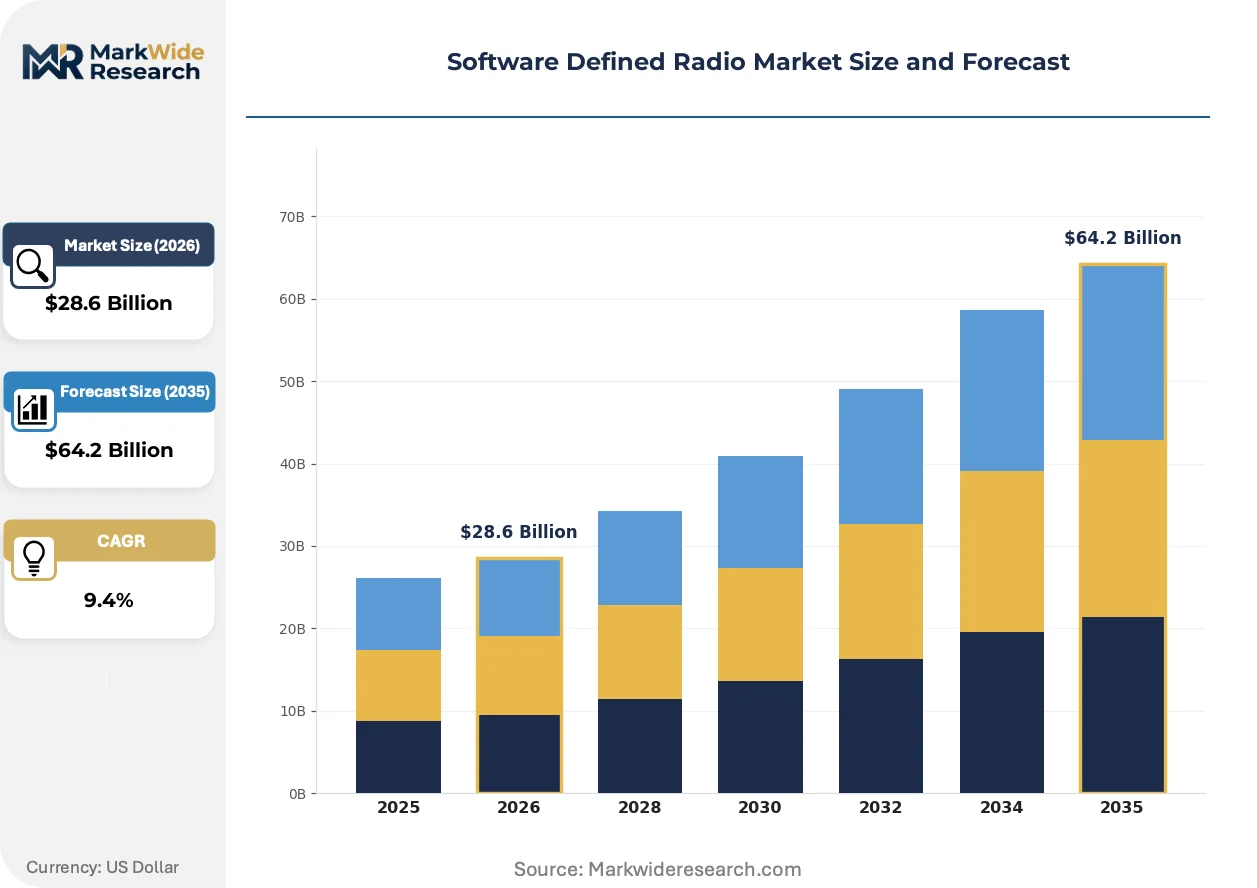
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Base Station, Software Tools, Transceiver Technology: Analog, Digital, Hybrid, Multiband End User: Aerospace, Defense, Telecommunications, Research Institutions Application: Public Safety, Commercial Communication, Military Operations, Remote Sensing |
| Companies Covered | Northrop Grumman Corporation, BAE Systems plc, L3Harris Technologies, Inc., Rafael Advanced Defense Systems Ltd., Elbit Systems Ltd., RTX Corporation, General Dynamics Corporation, National Instruments, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Defined Radio Market Emerging Trajectories
Three distinct vectors are restructuring how software-defined radio capabilities are developed, procured, and deployed across military and commercial applications. These shifts favor adaptable architectures over optimized point solutions.
Wideband RF front-end integration is bifurcating the component supply landscape. Gallium nitride power amplifiers and silicon-germanium transceiver chips now enable single hardware platforms to span HF through SHF spectra without mechanical switching. Defense primes are accelerating adoption of these consolidated front-ends to reduce size, weight, and power burdens on dismounted soldier programs. The technology is compressing demand for discrete band-specific modules and concentrating purchasing power with semiconductor suppliers capable of multi-octave performance.
EU defense fund directives and NATO interoperability frameworks are mandating vendor-neutral interface standards across member state procurement. These requirements constrain proprietary subsystem integration and force modular open systems approaches that enable competitive substitution of encryption, waveform, and antenna components. European military channels are responding by restructuring acquisition specifications around functional performance rather than platform-specific compliance.
Defense procurement agencies are consolidating radio requirements into enterprise-wide indefinite delivery contracts that span multiple vehicle and soldier programs. This concentration displaces program-specific hardware procurements and privileges suppliers capable of sustained firmware evolution under long-term performance-based agreements. The United States Department of Defense exemplifies this behavioral shift through its Modular Open Systems Approach directives applied to ground and airborne radio modernization.
Software Defined Radio Market Segmentation
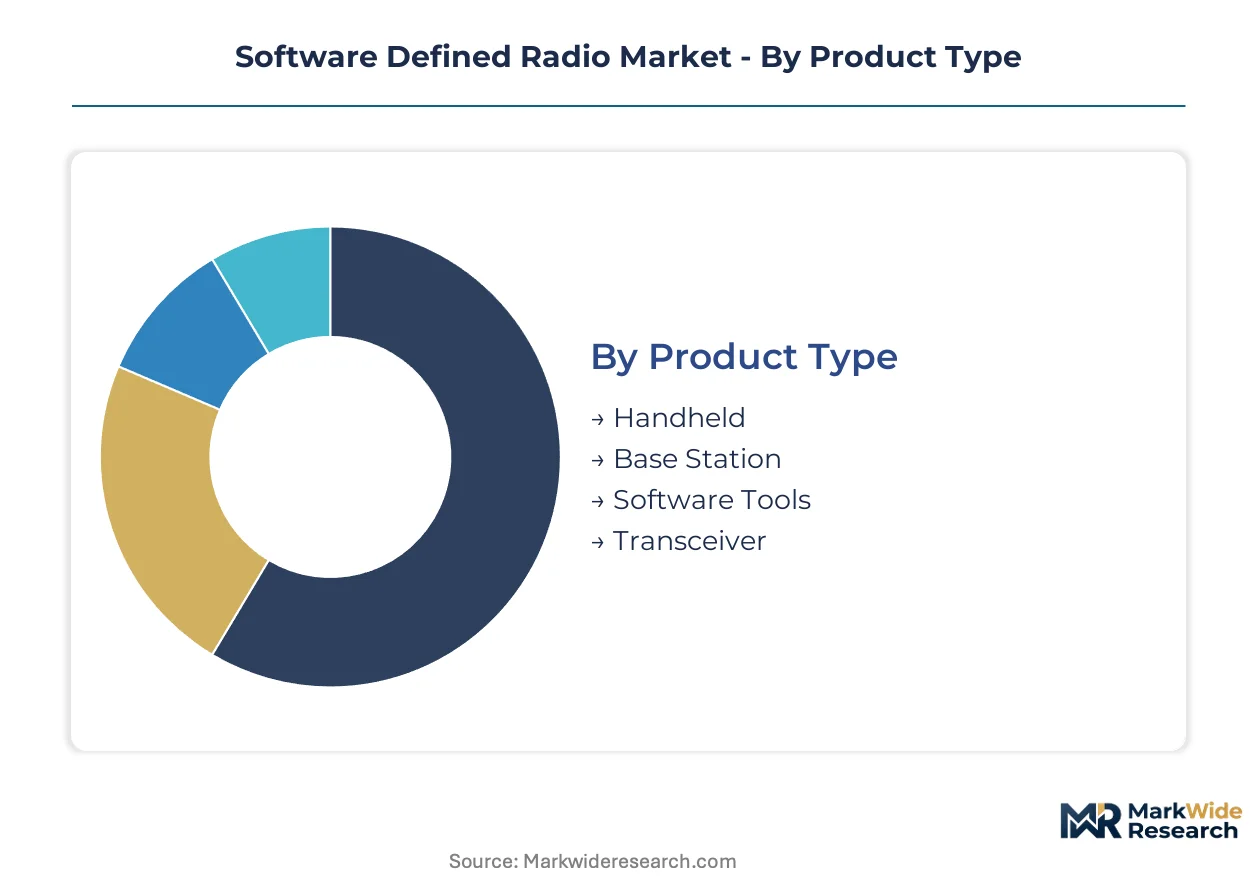
Segmentation in the software-defined radio market reveals how procurement priorities diverge between infrastructure-heavy telecommunications deployments and mobility-constrained defense applications. Technology choices and end-user requirements create distinct margin profiles that reshape competitive positioning across supplier tiers.
Product Type:
Substitution pressure intensifies where software-configurable platforms displace fixed-function hardware, compressing demand for single-purpose legacy equipment.
- Handheld:Compact units integrate reprogrammable digital signal processors with software-configurable RF front ends operating across 2 MHz to 6 GHz basebands. United States and South Korean dismounted soldier programs prioritize reduced size, weight, and power constraints, accelerating procurement timelines for cognitive radio capabilities.
- Base Station:Infrastructure platforms anchor revenue contribution through telecommunications replacement cycles and defense enterprise networks. Germany and NATO member states concentrate demand where multiband architectures eliminate single-purpose radio inventories under interoperability mandates.
- Software Tools:Firmware development environments enable dynamic waveform loading and protocol adaptation across heterogeneous hardware platforms.
- Transceiver:Modular RF-digital subsystems serve integrators requiring vendor-neutral interface compliance under open systems directives.
Base Station anchors the volume base while Handheld gains share at the steepest rate.
Technology:
Cost tier stratification separates premium multiband platforms from legacy analog substitutions in price-sensitive municipal procurement channels.
- Multiband:Single hardware platforms span HF through SHF spectra using gallium nitride power amplifiers and silicon-germanium transceiver chips without mechanical switching. Defense primes in the United States and European Union member states accelerate adoption to reduce size, weight, and power burdens, capturing widening margin pools.
- Digital:Fully reprogrammable architectures replace hardware-defined functions with firmware-upgradeable signal processing, compressing replacement cycles across public safety and military channels.
- Hybrid:Mixed-signal designs bridge legacy analog interoperability requirements with digital flexibility, constraining architectural optimization.
- Analog:Fixed-function hardware faces accelerating displacement despite substantial installed base sunk capital.
Digital platforms anchor the volume base while Multiband climbs the fastest as procurement specifications consolidate around consolidated front-end performance.
End User:
Application maturity varies sharply between regulated defense procurement with multi-year certification timelines and commercial telecommunications with compressed infrastructure refresh cycles.
- Defense:NATO STANAG 4204 waveform standards and Department of Defense Modular Open Systems Approach directives mandate interoperable multiband architectures. Procurement agencies across the United States, Germany, and United Kingdom reorganize demand toward firmware-upgradeable platforms under long-term performance-based agreements.
- Telecommunications:Base station infrastructure replacement cycles concentrate investment where SDR architectures host both military waveforms and 3GPP protocols for dual-use applications.
- Aerospace:Airborne radio modernization programs impose stringent size, weight, and power constraints favoring wideband RF front-end integration.
- Research Institutions:Experimental spectrum sensing and cognitive radio development drives demand for configurable software tools and transceiver modules.
Defense anchors the volume base while Telecommunications shows the steepest expansion trajectory as 5G-private network convergence opens dual-use applications.
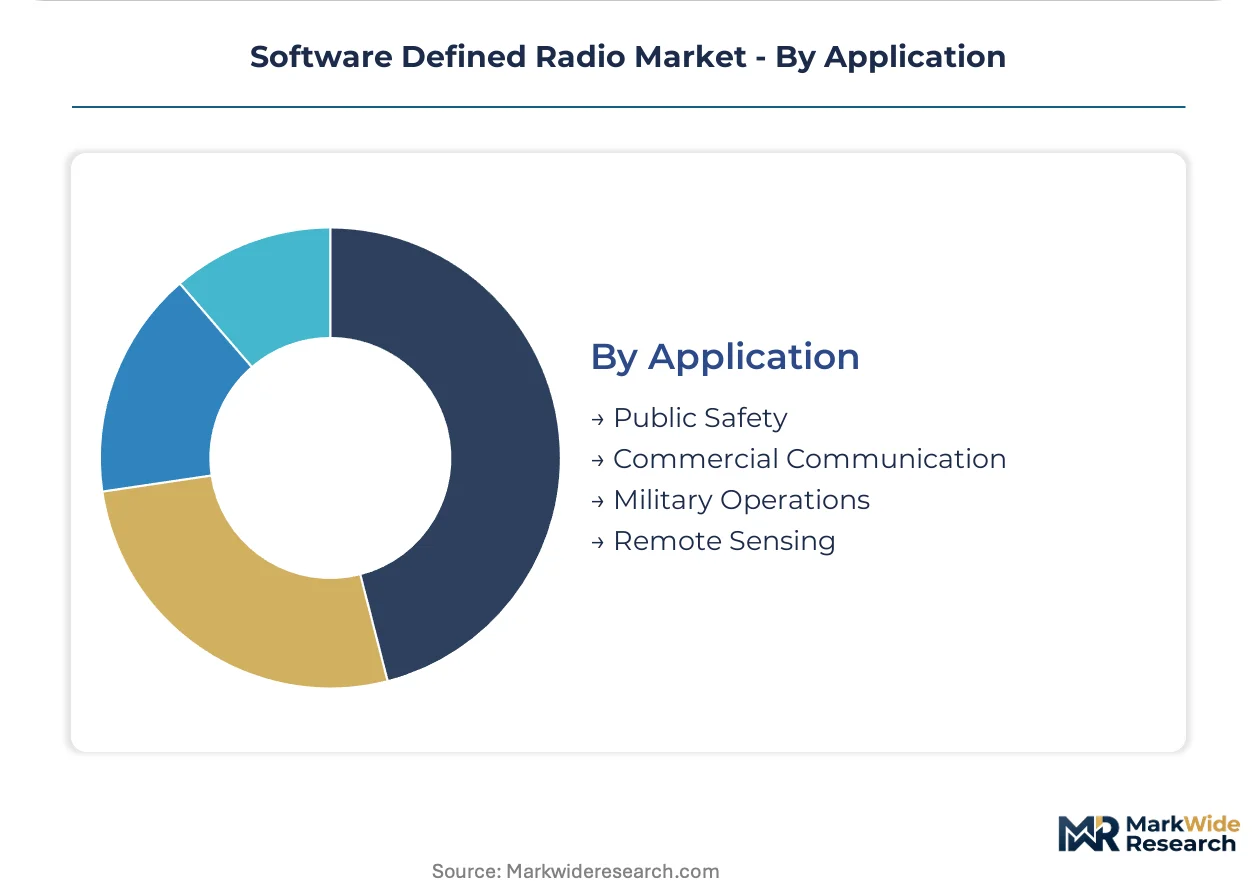
Application:
Customer type concentration separates enterprise-scale military operations from fragmented municipal public safety procurement with diverging compliance requirements.
- Military Operations:Dynamic spectrum sensing and protocol adaptation technologies penetrate force-multiplier investments in the United States, Germany, and South Korea. Encryption export control regimes under International Traffic in Arms Regulations impose licensing friction, elongating sales cycles.
- Public Safety:FCC Part 90 rules govern spectrum allocation and mandate interoperability standards that shape procurement specifications for domestic first responders, accelerating municipal and state-level SDR adoption.
- Commercial Communication:Industrial automation and critical infrastructure deployments leverage SDR flexibility for private network convergence.
- Remote Sensing:Spectrum monitoring and signal intelligence applications demand wideband sensing capabilities with embedded software optimization.
Military Operations anchors the volume base while Public Safety gains share fastest as interoperability mandates compress procurement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Defense's Joint Tactical Networking Center anchors procurement coordination across NATO interoperability frameworks. Germany's Federal Network Agency and South Korea's Defense Acquisition Program Administration shape certification requirements that cascade through allied supply chains.
United States
The Pentagon's Modular Open Systems Approach directives compress procurement timelines for firmware-upgradeable platforms. FCC Part 90 rules mandate interoperability standards for first responder communications across municipal agencies. Greater Boston and Northern Virginia clusters concentrate waveform algorithm development and RF-digital co-design expertise.
Germany
Bundeswehr modernization programs prioritize multiband architectures eliminating single-purpose radio inventories. EU defense fund mechanisms and NATO STANAG 4204 standards determine product certification requirements. Bavaria's aerospace and defense corridor hosts subsystem integration facilities serving European interoperability frameworks.
South Korea
Dismounted soldier programs drive demand for reduced size, weight, and power constraints in handheld cognitive radio platforms. Defense Acquisition Program Administration specifications align with US-Japan alliance coordination on spectrum management. Seoul Capital Area concentrates semiconductor packaging for wideband RF front-end components.
United Kingdom
Strategic Command reorganizes demand toward enterprise-wide indefinite delivery contracts spanning multiple vehicle programs. Ministry of Defence encryption mandates impose multi-year validation processes on platform launches. South West England's defense electronics cluster sustains sovereign manufacturing for NATO waveform integration.
France
Direction Générale de l'Armement consolidates radio requirements under long-term performance-based agreements replacing program-specific hardware buys. EU defense fund joint capability development programs create consolidated tender opportunities. Île-de-France hosts prime contractor headquarters coordinating multiband platform specialization across European member states.
Software Defined Radio Market Vendor Landscape
Concentration sits with defense primes possessing sustained firmware evolution capabilities under multi-year government contracts. The vendor base organizes around three strategic archetypes: integrated platform primes, modular subsystem specialists, and semiconductor component suppliers. M&A activity targets RF-digital co-design talent pools while strategic partnerships address encryption export control licensing friction.
Within the integrated platform tier, Northrop Grumman Corporation and L3Harris Technologies, Inc. exemplify vendors with specialized tactical waveform portfolios. BAE Systems plc represents European-based manufacturing anchored in UK sovereign relationships. Thales Group occupies a position across NATO interoperability frameworks through multiband product specialization. These three primes demonstrate how deep government contracting relationships and firmware-centric engineering capabilities reorder competitive positioning away from traditional RF hardware specialists.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| BAE Systems plc |
| L3Harris Technologies, Inc. |
| Rafael Advanced Defense Systems Ltd. |
| Elbit Systems Ltd. |
| RTX Corporation |
| General Dynamics Corporation |
| National Instruments |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
NATO STANAG 4204 certification requirements gate both supplier qualification and price stratification simultaneously, forcing vendors to absorb multi-year validation costs that separate defense-grade premiums from commercial alternatives. Defense primes pass encryption compliance burdens through to procurement agencies while municipal public safety buyers face compressed budgets under FCC Part 90 mandates.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with enterprise indefinite delivery contracts commanding 30-40% unit cost reductions against program-specific hardware buys. Price differentiation hinges on cryptographic module validation tier and waveform portfolio breadth, with NATO-interoperable platforms capturing premiums over single-band alternatives. Pricing pressure stems from open systems directives enabling competitive substitution of subsystems. Municipal first responders exhibit highest price sensitivity, while Pentagon enterprise buyers prioritize firmware evolution over unit economics.
Supply Chain Analysis
East Asian foundry concentration in Taiwan and South Korea underwrites gallium nitride power amplifier and silicon-germanium transceiver chip availability for wideband RF front-ends. Advanced FPGA and RF component production draws from a concentrated supplier base, creating single-source vulnerability to trade policy disruptions. Distribution runs through defense prime integrators holding long-term government contracts, with modular subsystem specialists penetrating via vendor-neutral interface specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against commercial 5G-private network convergence threatening to absorb dual-use spectrum applications. Firmware-upgradeable architectures must prove irreplaceable against hardened commercial alternatives.
For Market Incumbents: Secure sustained firmware evolution capabilities under multi-year performance-based agreements to lock out modular subsystem competitors. Deepen cryptographic module validation expertise to extend certification timelines that disadvantage new entrants. NATO interoperability mandates and open systems directives threaten proprietary integration margins—anchor relationships through waveform algorithm co-development with Joint Tactical Networking Center specifications. For New Entrants and Emerging Players: Differentiate on RF-digital co-design talent scarcity, targeting disaggregated procurement models where prime contractor relationships have fragmented. White-space sits in EU defense fund joint capability development programs and municipal public safety channels below Pentagon enterprise scale. Go-to-market through subsystem specialization for vendor-neutral encryption or antenna modules under Modular Open Systems Approach directives. For Investors and Strategic Acquirers: Carve-out targets emerge from defense primes divesting non-core RF hardware units under shareholder pressure for software-centric multiples. Long-term viability favors vendors with captive firmware development environments and sovereign manufacturing footprints. Watch for EU defense fund allocation acceleration as inflection indicator for consolidated tender volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Waveform Algorithm Co-Development | Locks prime contractor status under Pentagon Joint Tactical Networking Center roadmaps. |
| Backward Integration into GaN Foundry Relationships | Secures wideband RF front-end supply against Taiwan Strait logistics chokepoints. |
| EU Defense Fund Consortium Formation | Positions for consolidated multiband tenders across Bundeswehr and NATO member states. |
| Cognitive Radio Capability Acquisition | Addresses South Korean and German dismounted soldier program priorities for dynamic spectrum sensing. |
| Commercial 5G Protocol Licensing | Enables dual-use positioning in industrial automation private networks outside defense procurement cycles. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with defense procurement officers, RF systems engineers, and waveform algorithm developers; and secondary validation through NATO STANAG documentation, FCC Part 90 rulemaking dockets, and EU defense fund allocation disclosures. Bottom-up triangulation cross-checked unit economics against prime contractor indefinite delivery contract values, while top-down assessment anchored total addressable demand against national military modernization program budgets.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, technology tier, end-user vertical, and geographic procurement cluster. CAGRs derived from replacement cycle compression rates and interoperability mandate adoption curves, with specific inputs including encryption certification timeline distributions and gallium nitride component cost decline trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained NATO interoperability commitment and stable East Asian semiconductor supply; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU defense fund execution pace and US-Japan-South Korea alliance coordination on spectrum management evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
LTE Advanced Pro Market
Telecommunications
Russia Telecom Market
Telecommunications
Global LTE Market
Telecommunications
Iran Telecom Market
Telecommunications
Esim Subscription Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
5G Monetization Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Promotional Sms Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
Satcom Terminal Market
Telecommunications
5G Core Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
Transport Stream Switching Market