
 Global Heat Stress Monitor (HSM) Market | 2026-2036
Global Heat Stress Monitor (HSM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Heat Stress Monitor (HSM) Market Analysis
Silicon-based temperature sensors are shifting toward MEMS thermopile arrays in next-generation wearable heat stress monitors, reducing unit cost while improving wet-bulb globe temperature accuracy. TSI Incorporated leverages its aerosol instrumentation heritage to anchor premium positioning in occupational safety channels. Nielsen-Kellerman competes through specialized meteorological integration that extends product utility beyond industrial compliance into athletic performance monitoring.
A heat stress monitor measures environmental thermal load through wet-bulb globe temperature index calculation, combining dry-bulb, natural wet-bulb, and black-globe temperature sensors into a single composite reading for physiological strain assessment. Wearable devices dominate unit volume due to worker mobility requirements, while IoT-enabled wall-mounted monitors capture the fastest growth trajectory as facilities pursue centralized environmental data architecture. Bluetooth connectivity remains the mature baseline technology, though GPS-integrated units command margin premiums in remote mining and military logistics applications.
OSHA indoor heat injury prevention initiatives in the United States, EU-OSHA guidance frameworks under the European Agency for Safety and Health at Work, and Saudi Arabia's Ministry of Human Resources and Social Development occupational safety mandates collectively elevate compliance-driven procurement across construction, smelting, and agricultural sectors. ISO 7243 hot environments standard adoption accelerates product certification requirements in export markets. Stakeholders must monitor regulatory harmonization between regional heat exposure limits and emerging real-time biometric correlation protocols to anticipate next-generation product specifications.
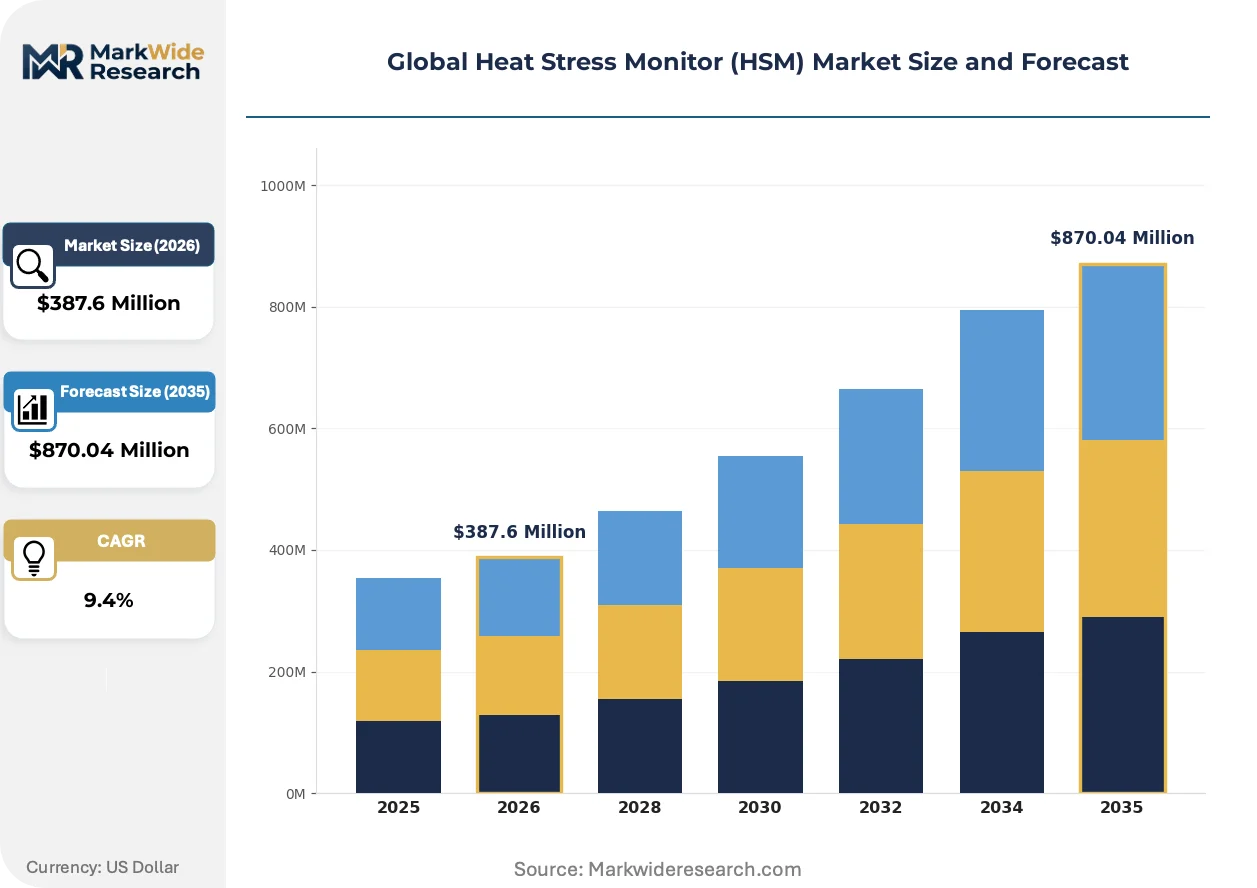
Market Dynamics
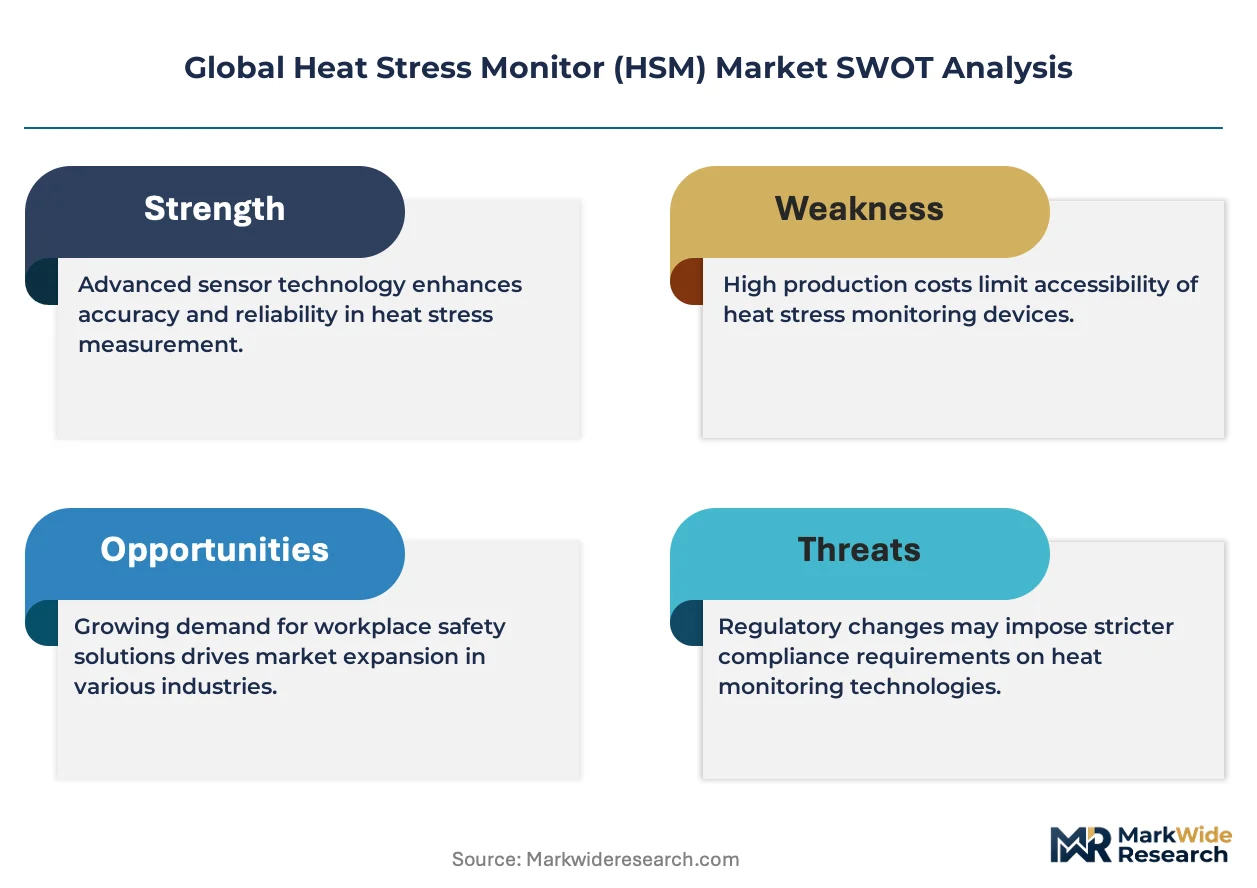
The transition from discrete sensor assemblies to MEMS thermopile arrays is compressing unit economics while elevating wet-bulb globe temperature precision, forcing incumbent manufacturers to retool fabrication lines or surrender premium positioning to semiconductor specialists.
Growth Catalysts
- OSHA Indoor Heat Injury Prevention Initiative:Enhanced enforcement across warehousing and manufacturing facilities is compelling employers to deploy continuous monitoring infrastructure. Compliance deadlines are accelerating replacement cycles for legacy spot-check devices.
- Underground Mining Expansion:Australian and Chilean operators are mandating wearable heat stress devices for all underground personnel. Fatality liability is shifting procurement from voluntary safety programs to capital budget line items.
- IoT Architecture Consolidation:Facilities management platforms are integrating wall-mounted heat monitors into centralized environmental data lakes. Bluetooth-enabled sensors feed predictive analytics for HVAC optimization and workforce scheduling.
Market Restraints
- MEMS Foundry Concentration:Taiwan Semiconductor Manufacturing and Samsung Foundry control advanced thermopile wafer supply. Geographic concentration creates vulnerability to trade policy disruptions and capacity allocation decisions.
- Calibration Drift in Harsh Environments:Natural wet-bulb wick degradation and black-globe coating deterioration in high-particulate settings require frequent recertification. Field maintenance costs erode total cost of ownership advantages.
- Spot-Check Thermometer Substitution:Low-cost infrared forehead thermometers satisfy minimum compliance in jurisdictions with weak enforcement. Price-sensitive agricultural employers delay upgrade to continuous monitoring systems.
Strategic Opportunities
- Saudi Arabia Gigaproject Construction:NEOM, Red Sea Global, and Qiddiya developments mandate heat stress protocols for outdoor workforces. Procurement volumes for wall-mounted and wearable systems are scaling with project milestones.
- Biometric Correlation Protocols:Integration of core body temperature sensors with environmental monitors enables individualized heat strain alerts. Military logistics and elite athletic training programs are piloting dual-sensor architectures.
- EU-OSHA Guidance Harmonization:Anticipated alignment of national heat exposure limits across Germany, France, and Italy will standardize product certification requirements. First-movers with pan-European approval capture specification advantages.
Industry Challenges
- ISO 7243 Interpretation Variance:National accreditation bodies apply divergent testing protocols for wet-bulb globe temperature accuracy certification. Multi-market entrants face redundant validation cycles and documentation burdens.
- Legacy Building Management System Integration:BACnet and Modbus protocol fragmentation across installed HVAC infrastructure complicates seamless data aggregation. Custom middleware development extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Heat Stress Monitor (HSM) Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $870.04 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Wall-mounted Monitors, Smartphone Applications, Remote Sensors End User: Agriculture, Sports Teams, Emergency Services, Manufacturing Technology: Bluetooth, Wi-Fi, IoT-enabled, GPS Application: Occupational Safety, Environmental Monitoring, Public Health, Research |
| Companies Covered | TSI Incorporated, Nielsen-Kellerman, LSI LASTEM, Casella, Delta OHM, REED Instruments, PCE Instruments, Sper Scientific, Romteck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Heat Stress Monitor (HSM) Market Emerging Trajectories
Sensor miniaturization and wireless connectivity standards are converging to enable continuous physiological monitoring at scale, transforming heat stress management from periodic compliance checks to real-time risk mitigation systems.
Solid-state MEMS thermopile arrays are electrifying temperature sensing architecture in next-generation wearable devices. Mining operators in Western Australia and Antofagasta are specifying these units for twelve-hour continuous duty cycles. The technology is compressing bill-of-materials costs while extending battery life beyond legacy thermistor designs.
EU-OSHA's anticipated binding heat exposure limit value under the European Agency for Safety and Health at Work strategic framework 2023-2025 is mandating systematic risk assessment protocols. German automotive foundries and Spanish agricultural processors are pre-positioning monitoring infrastructure ahead of formal adoption. Wall-mounted IoT systems with automated logging capabilities are capturing specification preference for audit trail compliance.
Facility managers are unbundling after-sales calibration services from original equipment procurement, engaging third-party metrology laboratories for annual recertification. Industrial distributors in Texas and Alberta are building captive service capabilities to capture recurring revenue streams. This pattern is most pronounced in oilfield services and petrochemical refining verticals with established safety service procurement relationships.
Global Heat Stress Monitor (HSM) Market Segmentation
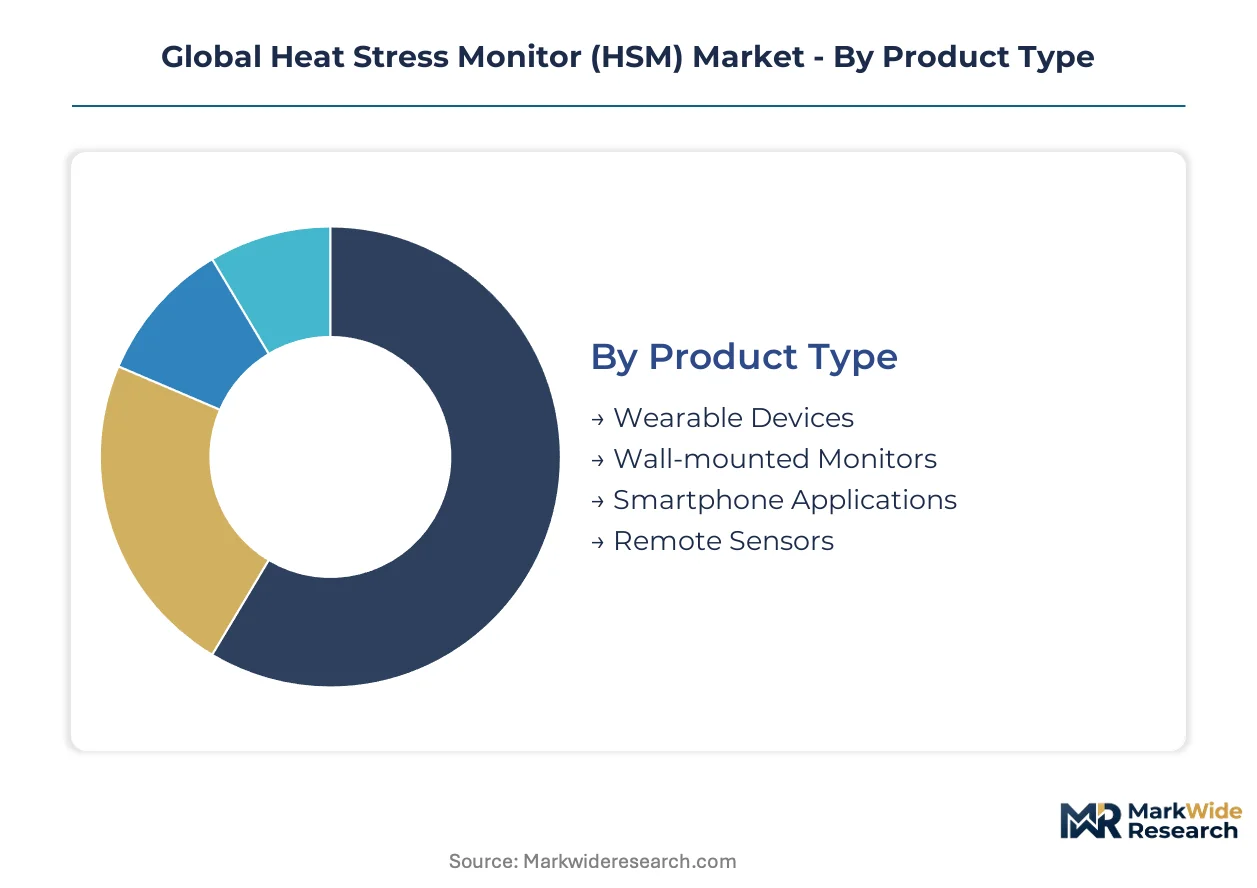
Heat stress monitor procurement patterns diverge sharply across deployment contexts, from personal protective equipment programs to facility-wide environmental control systems. Product specifications, connectivity requirements, and compliance documentation needs vary substantially by end-use vertical, creating distinct specification clusters that manufacturers must address separately.
Product Type:
Wearable and fixed-installation formats anchor opposite ends of the customization spectrum, with software-based solutions occupying an intermediate position on configurability and price.
- Wearable Devices:Wrist-mounted or clipped units integrate MEMS thermopile arrays for continuous wet-bulb globe temperature calculation during mobile work. Australian and Chilean underground mining operations mandate these for all personnel, with twelve-hour battery life now standard specification.
- Wall-mounted Monitors:Fixed-position units with IoT backhaul feed centralized building management platforms. Gulf Cooperation Council construction and oilfield sites deploy these for perimeter monitoring, with BACnet protocol compatibility increasingly required for HVAC integration.
- Smartphone Applications:Software leveraging device sensors or paired peripherals delivers spot-check functionality at minimal hardware cost. Agricultural employers in weak-enforcement jurisdictions use these for baseline compliance documentation.
- Remote Sensors:Distributed probe networks enable area-wide thermal mapping without worker-borne equipment. Military logistics and large-scale outdoor events pilot these for perimeter risk assessment.
Most installed capacity flows through wearable devices. Expansion is steepest in wall-mounted monitors as facilities consolidate environmental data architecture.
End User:
Risk liability profiles and regulatory exposure intensity shape procurement sophistication across verticals, with fatality-sensitive applications commanding premium specification tiers.
- Agriculture:Seasonal labor contractors face intermittent enforcement pressure. Price-sensitive operators in the United States delay continuous monitoring upgrades, relying on infrared spot-check thermometers where OSHA indoor heat standards remain uninspected.
- Sports Teams:Elite athletic programs specify GPS-integrated units with core body temperature correlation for personalized heat strain alerts. Collegiate and professional training facilities in Texas and Florida drive specification innovation.
- Emergency Services:Fire departments and hazmat units require intrinsically safe ratings and rapid-deployment form factors. Post-incident liability documentation needs elevate logging and audit-trail requirements.
- Manufacturing:Foundries, smelters, and warehousing operations face binding exposure limits under OSHA and EU-OSHA frameworks. German automotive foundries pre-position monitoring infrastructure ahead of anticipated binding heat exposure limit adoption.
Manufacturing absorbs the largest equipment volume. Sports applications are climbing the fastest as biometric correlation protocols mature.
Technology:
Connectivity architecture determines data latency, infrastructure requirements, and integration complexity across deployment scenarios.
- Bluetooth:Mature baseline standard for wearable-to-smartphone pairing dominates unit economics. Battery efficiency and universal handset compatibility sustain its position in cost-constrained procurement.
- Wi-Fi:Higher bandwidth enables wall-mounted systems to stream continuous logs to facility servers. Range limitations and IT security review requirements constrain adoption in distributed outdoor sites.
- IoT-enabled:Cellular or LPWAN backhaul eliminates local infrastructure dependency. Remote mining and military logistics applications command margin premiums for this capability.
- GPS:Location tagging enables geofenced alerts and post-incident spatial analysis. Integration with environmental sensors creates dual-sensor architectures for individualized risk assessment.
Bluetooth retains the largest installed base. IoT-enabled systems are expanding most quickly as facilities pursue centralized data lakes.
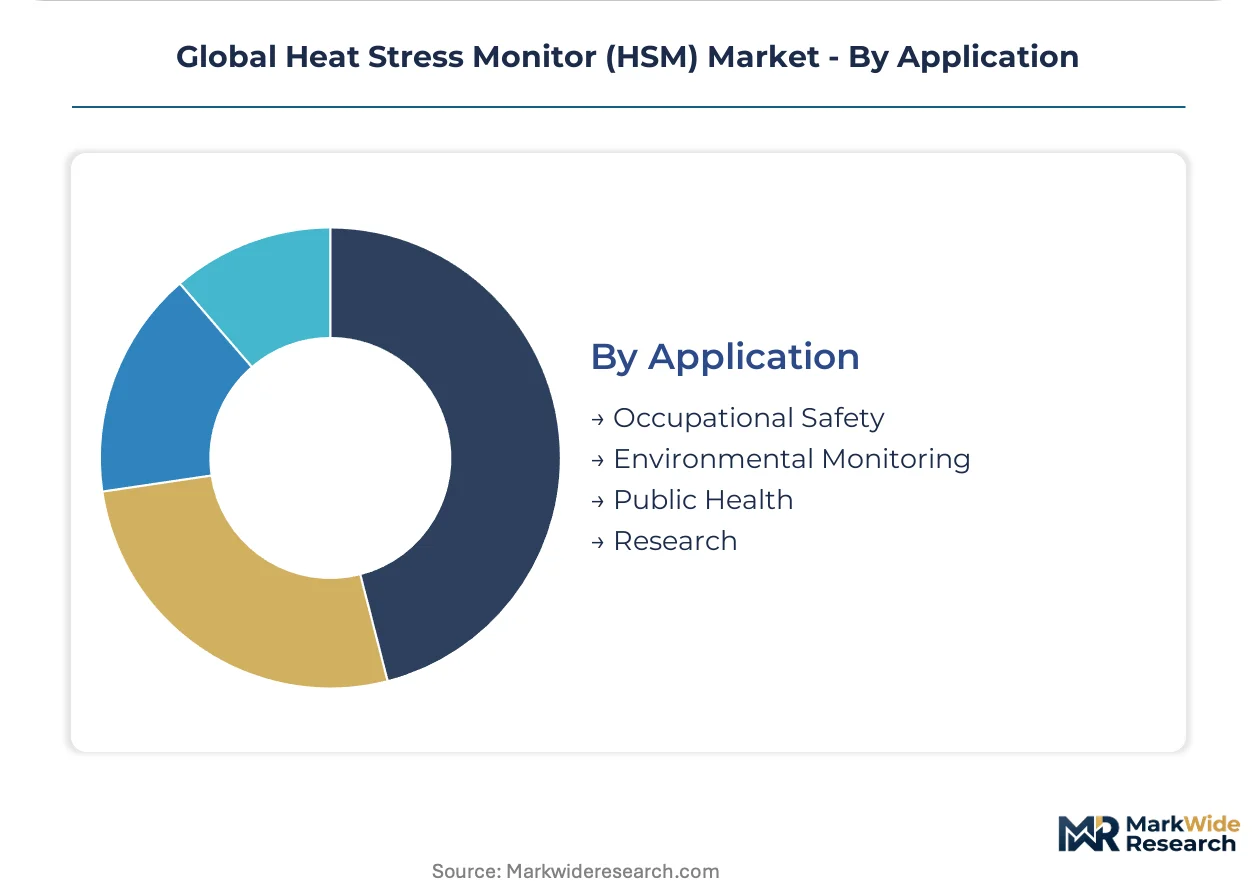
Application:
Regulatory mandate strength and litigation exposure differentiate procurement urgency across use cases, with compliance-driven segments leading specification advancement.
- Occupational Safety:Employer liability frameworks in the United States, European Union, and Saudi Arabia mandate systematic heat risk assessment. Procurement ties directly to capital budgeting for compliance infrastructure.
- Environmental Monitoring:Urban heat island research and climate adaptation planning drive academic and municipal procurement. Data continuity requirements favor fixed-installation networked systems.
- Public Health:Heat health warning systems and vulnerable population protection programs operate at municipal scale. Integration with emergency broadcast infrastructure elevates reliability specifications.
- Research:Physiological and environmental studies demand calibrated accuracy and customizable logging intervals. Smaller volume but highest per-unit specification requirements.
Occupational safety channels dominate revenue concentration. Public health applications are gaining share fastest as municipal climate adaptation budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian underground mining operations anchor procurement volume for wearable heat stress monitors, with Western Australia and Queensland driving specification requirements for twelve-hour continuous duty cycles.
United States
OSHA's enhanced indoor heat injury prevention enforcement compels warehousing and manufacturing employers to deploy continuous monitoring infrastructure. German automotive foundries pre-position wall-mounted IoT systems ahead of anticipated binding heat exposure limit adoption. Houston and Midland oilfield service clusters drive specification innovation for remote telemetry integration.
Australia
Underground mining fatalities in Western Australia and Queensland shift procurement from voluntary safety programs to mandatory capital budget line items. State occupational safety regulators mandate wearable devices for all personnel in confined thermal environments. Pilbara iron ore operations specify MEMS thermopile arrays for extreme ambient temperature durability.
Germany
Automotive foundries in Stuttgart and Wolfsburg face systematic heat risk assessment protocols under EU-OSHA strategic frameworks. The country's national occupational safety regulator accelerates certification requirements for wet-bulb globe temperature accuracy. Bavarian automotive suppliers integrate wall-mounted monitors into centralized environmental data lakes.
Saudi Arabia
NEOM, Red Sea Global, and Qiddiya gigaprojects mandate heat stress protocols for outdoor construction workforces. The Ministry of Human Resources and Social Development elevates procurement volumes through occupational safety mandates. Eastern Province oilfield sites deploy perimeter monitoring networks for contractor liability management.
Chile
Antofagasta copper mining operations expand wearable device deployment to underground extraction personnel. National mining regulator enforcement creates specification pull-through for GPS-integrated units in remote logistics applications. Atacama Desert extraction sites drive demand for black-globe coating durability in high-particulate conditions.
Global Heat Stress Monitor (HSM) Market Vendor Landscape
Global majors compete with regional champions across sensor technology and compliance documentation capabilities. Market structure fragments across three tiers: semiconductor specialists controlling MEMS thermopile supply, occupational safety incumbents with aerosol instrumentation heritage, and meteorological equipment providers extending into industrial channels. Strategic moves concentrate on foundry partnerships for wafer supply security and third-party metrology service integration for recurring calibration revenue.
Within the precision instrumentation tier, TSI Incorporated exemplifies aerosol-to-safety channel extension, while Nielsen-Kellerman occupies a position bridging meteorological and athletic performance applications. Among European specialists, LSI LASTEM and Casella represent compliance-focused archetypes with environmental monitoring heritage. Delta OHM anchors Italian positioning in wall-mounted IoT integration. These players illustrate divergent paths: semiconductor-adjacent capability acquisition versus service-layer revenue capture through calibration unbundling.
| Leading Market Players |
|---|
| TSI Incorporated |
| Nielsen-Kellerman |
| LSI LASTEM |
| Casella |
| Delta OHM |
| REED Instruments |
| PCE Instruments |
| Sper Scientific |
| Romteck |
| Others |
Supply Flow & Price Mechanics
Silicon wafer spot prices cascade through MEMS thermopile fabrication costs into three distinct pricing tiers for heat stress monitors, compressing margins for legacy thermistor-based units while elevating premium positioning for semiconductor-integrated designs.
Pricing Analysis
Input-cost pass-through from MEMS foundry pricing dominates unit economics, with Taiwan Semiconductor Manufacturing and Samsung Foundry capacity allocation decisions flowing directly into landed costs for wearable devices. Three-tier pricing structure across premium, standard, and economy levels separates GPS-integrated mining units from Bluetooth baseline models and smartphone-dependent spot-check applications. Cost compression in the economy tier is intensifying because agricultural employers in weak-enforcement jurisdictions delay continuous monitoring upgrades. Manufacturing and mining verticals show least price sensitivity due to fatality liability exposure, while seasonal agricultural contractors anchor the price-sensitive segment.
Supply Chain Analysis
ISO 7243 wet-bulb globe temperature accuracy certification gates market access, with national accreditation bodies in Germany, the United States, and Saudi Arabia applying divergent testing protocols that fragment supplier qualification requirements. Taiwan and South Korea anchor MEMS thermopile wafer supply, while China and Vietnam concentrate final assembly for wearable housings and battery integration. The supply chain draws from silicon substrates, precision-machined black-globe assemblies, and natural wet-bulb wick materials. Single-source vulnerability concentrates in advanced thermopile foundry capacity. Distribution runs through industrial safety distributors in Texas and Alberta, plus direct OEM relationships with mining operators in Western Australia and Antofagasta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS thermopile cost-down curves and biometric correlation premium tiers frame this market as a margin-expansion story for participants who capture semiconductor-adjacent capabilities or recurring calibration service streams.
For Market Incumbents: Deploy foundry partnership leverage to secure wafer allocation priority as Taiwan Semiconductor Manufacturing and Samsung Foundry ration capacity among automotive and industrial sensor customers. Deepen backward integration into MEMS design capabilities to reduce dependency on semiconductor specialists who are encroaching on premium positioning. Capture calibration service revenue through third-party metrology laboratory relationships or captive service capabilities in oilfield services clusters. For New Entrants and Emerging Players: EU-OSHA's anticipated binding heat exposure limit value in Germany opens a window for wall-mounted IoT systems with automated audit-trail logging ahead of formal adoption deadlines. Saudi Arabia's Ministry of Human Resources and Social Development mandates for NEOM and Qiddiya gigaprojects create immediate procurement volume for outdoor construction monitoring. Target agricultural processing in Spain and Portugal through smartphone-integrated spot-check solutions that satisfy baseline compliance at minimal hardware cost. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor specialists possessing MEMS thermopile design capabilities who can extend into occupational safety channels without legacy thermistor retooling burdens. Long-term viability hinges on regulatory harmonization across OSHA, EU-OSHA, and Gulf Cooperation Council frameworks that standardizes certification requirements and consolidates supplier landscapes. Watch for ISO 7243 interpretation convergence between German, French, and Italian accreditation bodies as the inflection signal for pan-European specification advantages.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Secures wafer supply priority from Taiwan Semiconductor Manufacturing for extreme-temperature mining specifications. |
| Calibration Service Integration | Captures recurring revenue through third-party metrology relationships with Alberta oilfield services clusters. |
| Biometric Correlation Development | Enables premium positioning in Texas and Florida elite athletic training facilities through core body temperature integration. |
| EU-OSHA Pre-Positioning | Captures German automotive foundry specifications ahead of binding heat exposure limit adoption. |
| Gulf Gigaproject Certification | Locks in NEOM and Red Sea Global procurement through Saudi Ministry of Human Resources and Social Development compliance. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mining safety directors, occupational health officers at German automotive foundries, Gulf Cooperation Council construction procurement managers, and MEMS sensor engineering leads with secondary validation against OSHA enforcement databases, EU-OSHA strategic framework documents, Saudi Ministry of Human Resources and Social Development mandates, and ISO 7243 accreditation body protocols. Bottom-up unit shipment estimates from Australian and Chilean mining operators triangulated against top-down market sizing from industrial safety distributor channel checks.
Segment-weighting across product type, end user, technology, and application dimensions drove the analytical framework, with wearable versus wall-mounted format splits, mining versus manufacturing versus agricultural vertical allocation, Bluetooth versus IoT connectivity architecture, and occupational safety versus environmental monitoring versus public health use case differentiation modeled throughout the projection horizon. CAGRs derived from regulatory mandate timing, gigaproject construction milestones, and MEMS cost-down curve penetration. Forecast inputs included OSHA indoor heat standard enforcement intensity and EU-OSHA binding limit adoption probability.
Revisions become necessary when MEMS foundry capacity allocation shifts, trade policy disrupts Taiwan or South Korea supply corridors, or ISO 7243 harmonization accelerates or stalls across European accreditation bodies. Forecasts reflect assumptions regarding regulatory enforcement continuity and gigaproject construction schedule adherence. A model refresh is warranted upon material change in OSHA indoor heat injury prevention initiative funding or Saudi gigaproject procurement pacing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
RFID Smart Cabinet Market
Sensors
Drain Camera Market
Sensors
Data Buoy Market
Sensors
Eye Tracking Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Low Power Geolocation Market
Sensors
Handheld GPS Units Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Automated Weather Observation System Market
Sensors
Asia Pacific RFID Market
Sensors
Mobile Lidar Scanner Market
Sensors
Micro Location Technology Market
Sensors
Vision Positioning System Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
2D Barcode Reader Market
Sensors
Europe RFID Market