
 Global Home Networking Device Market | 2026-2036
Global Home Networking Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Networking Device Market Foresight
Taiwanese ODM capacity is broadening as contract manufacturers scale Wi-Fi 6E and mesh system output for branded vendors. TP-Link Technologies Co., Ltd. leverages vertically integrated Shenzhen facilities to control router cost curves from chipset sourcing to finished goods. NETGEAR, Inc. anchors North American premium channel distribution through specialty retail and direct-to-consumer platforms. Huawei Technologies Co., Ltd. competes aggressively in emerging markets with integrated carrier-grade CPE bundled to broadband subscriptions.
Home networking devices comprise consumer-premises equipment that manages local area data traffic across wired and wireless interfaces, typically operating at 2.4 GHz, 5 GHz, or 6 GHz spectra with throughput specifications scaling from 1 Gbps to 10 Gbps aggregate. These products enable residential and small-office environments to distribute internet connectivity, interconnect smart appliances, and sustain latency-sensitive applications such as 4K streaming and cloud gaming. Mesh systems now capture disproportionate margin pools as consumers prioritize whole-home coverage over standalone router upgrades. Wi-Fi 6E technology leads product transition cycles, though Ethernet maintains structural relevance in desktop gaming and NAS setups where wired stability outweighs wireless convenience. Smart home automation application demand concentrates among mesh and Zigbee-enabled gateway products that consolidate protocol translation.
FCC spectrum allocations in the United States, CE marking requirements under EU radio equipment directives, and China's MIIT type-approval standards collectively shape product certification timelines and regional feature availability. Ecodesign regulations under the EU F-Gas Framework and REACH substance restrictions further constrain material choices for enclosure plastics and thermal interface compounds. Stakeholders must monitor 6 GHz spectrum harmonization progress across national regulators, as fragmented band plans threaten economies of scale for unified global SKUs and inventory pooling.
Market Dynamics
Wi-Fi 6E spectrum harmonization is fragmenting product roadmaps as OEMs confront divergent national band plans for 6 GHz deployment, forcing regional SKU proliferation that strains inventory pooling economics and compresses gross margins on unified global platforms.
Growth Catalysts
- FCC 6 GHz Authorization:The United States regulator opened 1200 MHz of contiguous spectrum for unlicensed use, enabling tri-band router architectures that deliver multi-gigabit throughput to residential environments. This regulatory unlock accelerates hardware refresh cycles among early adopters.
- Remote Work Permanence:Enterprise hybrid policies sustain residential bandwidth demand for video conferencing and cloud application access, driving mesh system penetration among suburban households with coverage dead zones.
- Fiber-to-the-Home Rollouts:Germany, China, and the United States are expanding gigabit-capable last-mile infrastructure, creating downstream demand for Wi-Fi 6E CPE capable of saturating subscribed speeds across multiple simultaneous clients.
Market Restraints
- 6 GHz Fragmentation:China's MIIT, the EU's CE marking authorities, and the FCC have adopted incompatible band plans for 6 GHz unlicensed access, preventing single-SKU global deployment and inflating certification costs.
- Semiconductor Supply Concentration:Wi-Fi 6E chipset fabrication concentrates among TSMC and Samsung Foundry capacity, exposing OEMs to allocation constraints during foundry node transitions.
- Copper and Rare Earth Input Volatility:Enclosure manufacturing and thermal interface materials face cost pressure from REACH substance restrictions and fluctuating rare earth magnet pricing for power supply components.
Strategic Opportunities
- Matter Protocol Convergence:The unified smart home standard collapses Zigbee, Z-Wave, and proprietary stacks into a single IP-based framework, enabling gateway vendors to capture protocol translation margins previously dispersed across hub manufacturers.
- India Broadband Expansion:The country's national digital infrastructure push under PLI scheme incentives creates greenfield demand for cost-optimized mesh systems in tier-2 and tier-3 cities with nascent fiber penetration.
- EU Ecodesign Mandates:The F-Gas Framework and emerging standby power regulations are forcing thermal design innovation, rewarding vendors with advanced passive cooling architectures that eliminate fan noise and improve reliability ratings.
Industry Challenges
- RF Engineering Talent Scarcity:mmWave and 6 GHz antenna design expertise concentrates among a narrow cohort of specialists, extending product development timelines and inflating compensation costs for qualified hardware architects.
- Multi-Regulatory Certification Parallelism:Simultaneous FCC, CE, and MIIT approval processes for tri-band products create timeline misalignment, delaying market entry in priority regions and compressing effective product lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Networking Device Market |
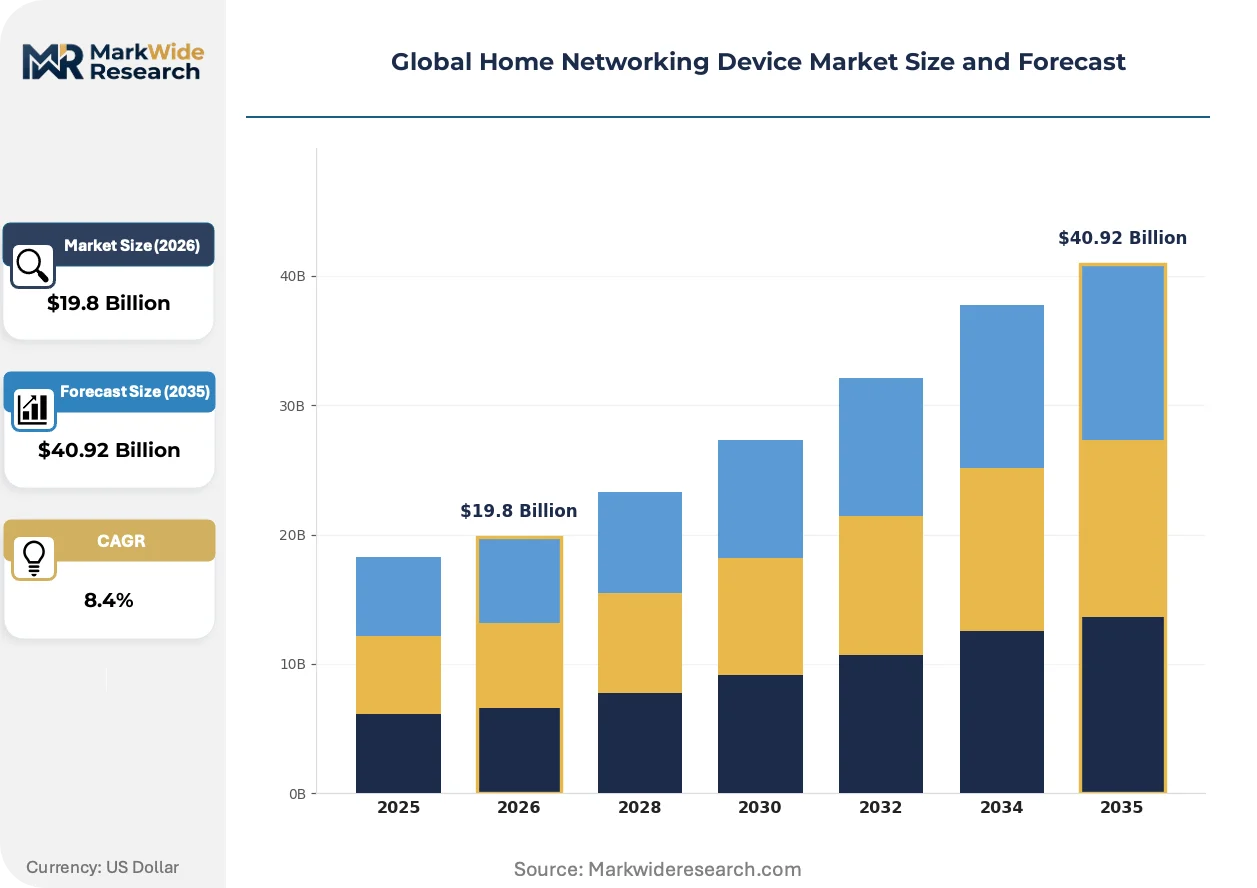
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $40.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Routers, Network Extenders, Mesh Systems, Powerline Adapters, Network Switches Technology: Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, Ethernet, Zigbee, Thread Application: Streaming, Online Gaming, Smart Home Automation, Remote Learning, Telecommuting End User: Residential Users, Small Office Setup, Co-Working Spaces, Vacation Rentals |
| Companies Covered | TP-Link Technologies Co., Ltd., NETGEAR, Inc., ASUSTeK Computer Inc., Cisco Systems, Inc., D-Link Corporation, Huawei Technologies Co., Ltd., Amazon.com, Inc., Google, Belkin International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Networking Device Market Shifts & Advancements
Mesh networking architectures are displacing standalone router form factors as the default residential infrastructure choice, while regulatory fragmentation around 6 GHz spectrum and converging smart home protocols reshape competitive differentiation vectors across hardware portfolios.
Wi-Fi 6E tri-band chipsets are consolidating premium product tiers by integrating 6 GHz backhaul channels with legacy 2.4 GHz and 5 GHz client serving bands into single-radio solutions. Enterprise IT departments migrating home office equipment are specifying these platforms for executive residential deployments. This silicon integration is consolidating vendor margins previously split between discrete radio modules and external backhaul extenders.
The EU F-Gas Regulation and emerging Ecodesign requirements for networked standby power are forcing thermal management redesigns across enclosure engineering. Vendors must eliminate forced-air cooling in favor of passive heat dissipation to meet acoustic and efficiency thresholds. German and French distribution channels are prioritizing silent-operation certifications as a procurement filter for premium residential segments.
Subscription-based firmware and security service bundling is displacing perpetual-license hardware sales in North American direct-to-consumer channels. NETGEAR and TP-Link have introduced annual protection plans with automatic threat signature updates. This recurring revenue pivot is most visible in United States urban markets where consumers demonstrate higher willingness-to-pay for managed network security.
Global Home Networking Device Market Segmentation
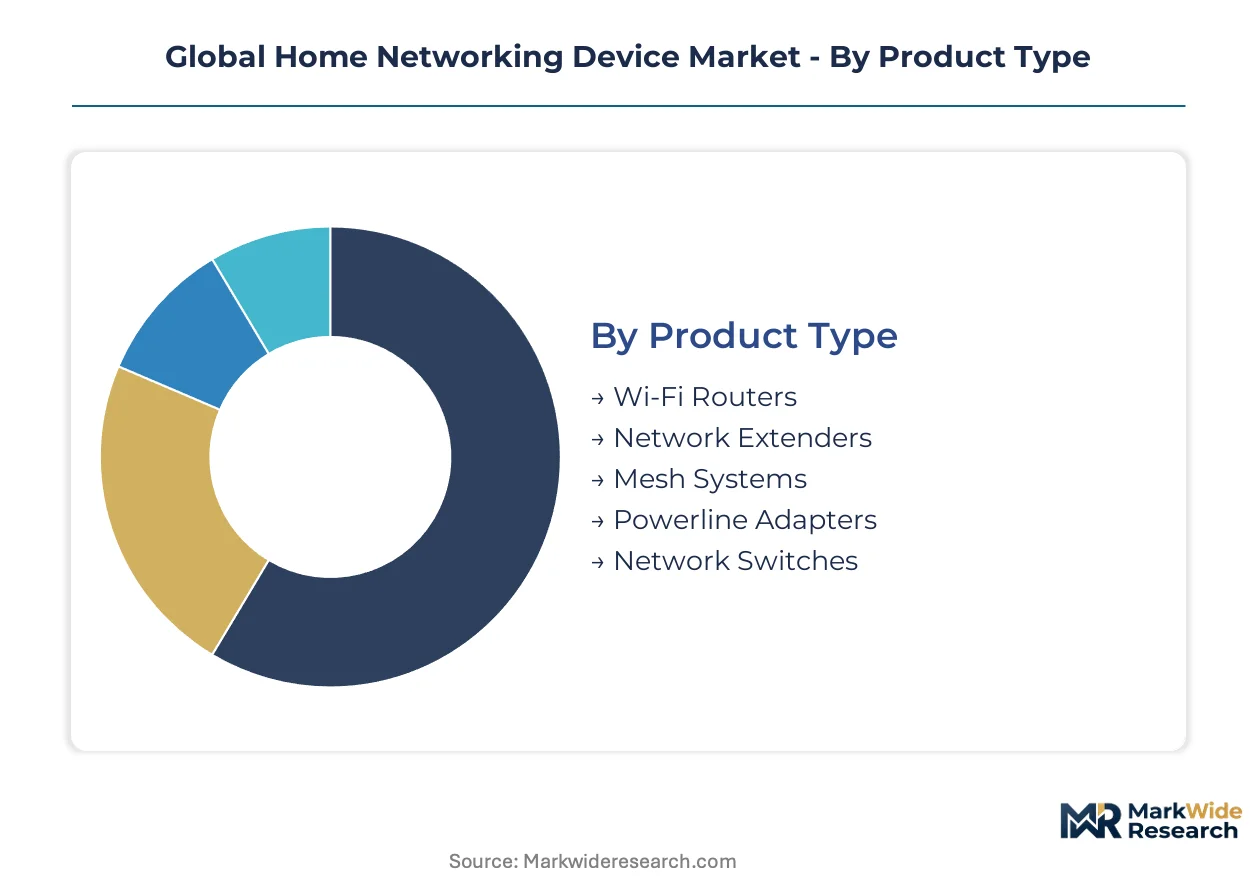
Segmentation reveals how hardware specifications, protocol standards, and deployment contexts fragment demand across distinct purchasing logics. Manufacturers must align R&D roadmaps and channel strategies to these divergent technical requirements and usage intensities.
Product Type:
Contract manufacturers concentrate tri-band chipset allocation toward form factors commanding premium ASPs and recurring firmware revenue streams.
- Wi-Fi Routers:Standalone units with integrated 2.4 GHz, 5 GHz, and 6 GHz radios serve as the default residential gateway. Demand clusters in suburban United States households refreshing hardware to match fiber-to-the-home gigabit subscriptions.
- Mesh Systems:Distributed node architectures eliminate coverage dead zones through self-healing backhaul protocols. German and French distribution channels prioritize these for multi-story residences where concrete construction degrades single-point signal propagation.
- Network Extenders:Single-band repeaters bridge coverage gaps in legacy deployments.
- Powerline Adapters:Electrical wiring transport for environments where wireless penetration fails.
- Network Switches:Wired Ethernet expansion for desktop gaming and NAS configurations.
Wi-Fi Routers absorb the bulk of installed capacity; Mesh Systems are expanding most quickly.
Technology:
Protocol transitions follow regulatory authorization timelines, with 6 GHz availability determining regional product tiering.
- Wi-Fi 6E:Tri-band operation incorporating 1200 MHz of 6 GHz spectrum enables multi-gigabit throughput with reduced interference. FCC authorization in the United States accelerates hardware refresh cycles among early adopters seeking latency reduction for cloud gaming.
- Wi-Fi 6:OFDMA and 1024-QAM modulation improve spectral efficiency in congested environments. China MIIT type-approval concentrates manufacturing volume here where 6 GHz band plans remain fragmented.
- Wi-Fi 5:Legacy 802.11ac dominates emerging market price-sensitive tiers.
- Ethernet:Copper and fiber physical layer standards persist for stationary high-bandwidth endpoints.
- Zigbee:Low-power mesh protocol for battery-operated sensor networks.
- Thread:IP-native low-power standard gaining traction through Matter protocol convergence.
Wi-Fi 6 commands current manufacturing volume; Wi-Fi 6E is climbing the fastest as spectrum harmonization progresses.
Application:
Latency sensitivity and bandwidth concurrency requirements determine hardware specification thresholds across use cases.
- Online Gaming:Sub-20 millisecond latency requirements drive demand for tri-band routers with dedicated 6 GHz backhaul. United States urban markets show willingness-to-pay premiums for quality-of-service prioritization features.
- Smart Home Automation:Gateway functions consolidating Zigbee, Thread, and proprietary protocols into unified control planes. German households lead Europe in Matter-compatible device penetration.
- Streaming:4K and 8K video distribution demands consistent throughput across multiple simultaneous clients.
- Remote Learning:Video conferencing reliability requirements accelerated mesh adoption during hybrid education transitions.
- Telecommuting:Enterprise VPN performance and security segmentation needs.
Streaming absorbs the bulk of installed capacity; Online Gaming is gaining share fastest among premium tier purchasers.
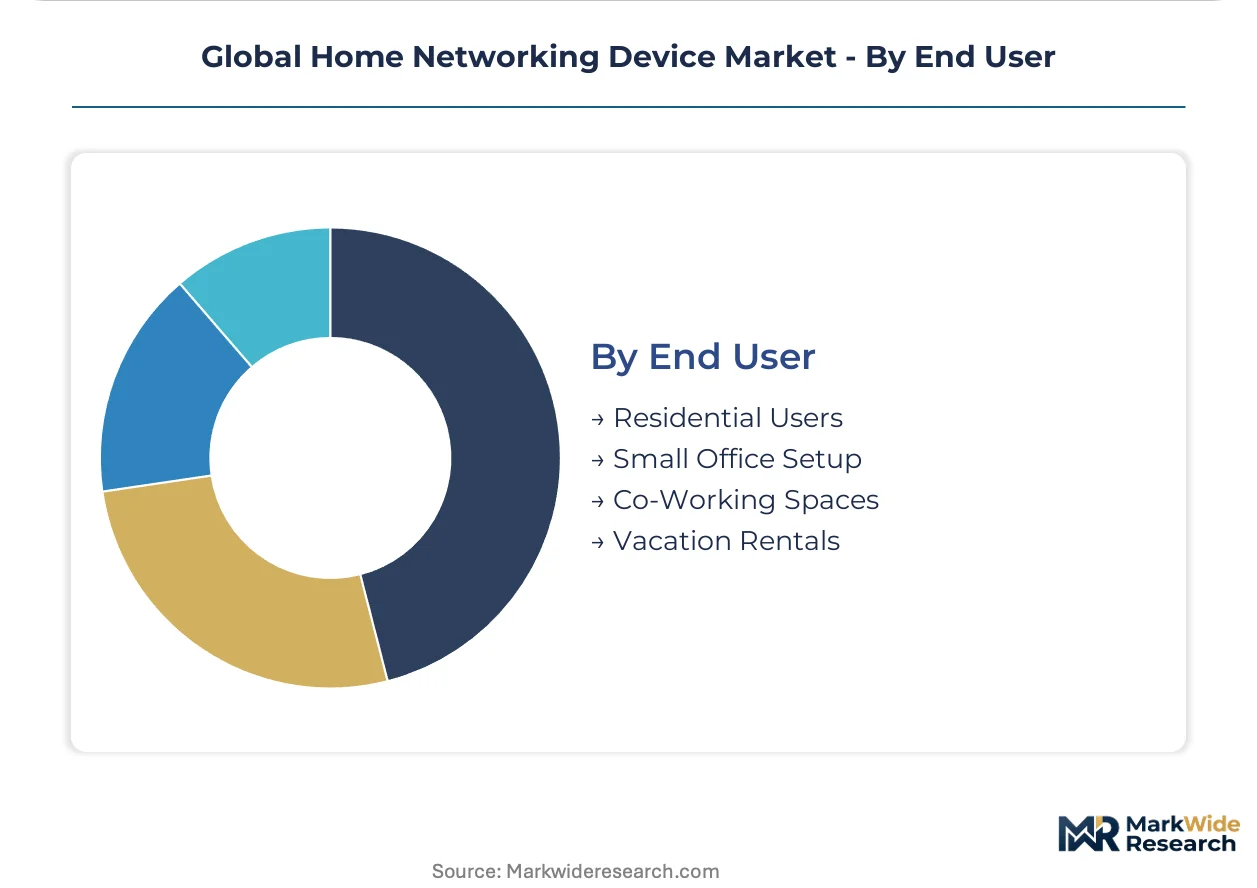
End User:
Purchasing authority and technical sophistication shape channel strategy and support service bundling.
- Residential Users:Individual consumers selecting hardware through retail or direct-to-consumer channels. Remote work permanence in the United States sustains above-replacement-cycle demand for coverage expansion.
- Small Office Setup:SOHO environments requiring enterprise-grade security features without IT staff. China and India show expanding demand as gigabit fiber penetrates commercial districts.
- Co-Working Spaces:Multi-tenant environments with client isolation and usage metering requirements.
- Vacation Rentals:Short-term hospitality operators prioritizing simple guest onboarding and remote management.
Residential Users absorb the bulk of installed capacity; Small Office Setup is expanding most quickly as hybrid work institutionalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon substrate fabrication in Taiwan anchors supply-side capacity for tri-band chipset production serving residential networking deployments worldwide.
United States
FCC authorization of 1200 MHz contiguous 6 GHz spectrum accelerates tri-band router refresh cycles among early adopters seeking cloud gaming latency reduction. The Infrastructure Investment and Jobs Act funds fiber-to-the-home expansion in underserved census tracts. Austin and Seattle metropolitan clusters concentrate smart home automation engineering talent developing Matter protocol gateway firmware.
Germany
Concrete construction in multi-story residences drives mesh system penetration where single-point wireless propagation fails. The EU F-Gas Regulation mandates passive thermal design eliminating forced-air cooling from premium residential segments. Munich and Stuttgart industrial corridors host ODM facilities scaling Wi-Fi 6E output for European distribution channels.
China
MIIT type-approval standards for 6 GHz band plans remain fragmented, concentrating manufacturing volume on Wi-Fi 6 platforms for domestic consumption. The national dual carbon goals accelerate energy efficiency requirements for networked standby power in CPE devices. Shenzhen and Dongguan electronics clusters control vertically integrated router production from chipset sourcing through finished goods assembly.
India
PLI scheme incentives for telecom equipment manufacturing create greenfield demand for cost-optimized mesh systems in tier-2 and tier-3 cities with nascent fiber penetration. TRAI broadband policy mandates drive gigabit infrastructure targets through 2025. Bengaluru and Hyderabad technology corridors concentrate firmware development operations serving domestic and export markets.
Japan
METI standards for radio equipment certification enforce stringent electromagnetic compatibility testing for residential gateway devices. Compact dwelling architectures prioritize space-efficient mesh node form factors over standalone router footprints. Tokyo-Osaka metropolitan demand concentrates premium-tier procurement for latency-sensitive telecommuting and online gaming applications.
Global Home Networking Device Market Competitive Landscape
Global majors compete with regional champions across certification and distribution capabilities, producing a tiered structure where scale-driven OEMs, vertically integrated contract manufacturers, and cloud-platform entrants each occupy distinct competitive vectors. Strategic archetypes include silicon-integrated platform vendors, ODM-scale fabricators with captive supply chains, and ecosystem players bundling hardware with subscription services. Dominant competitive moves encompass backward integration into chipset sourcing and geographic expansion through carrier-grade CPE bundling partnerships.
Among Asia-Pacific-based fabricators, TP-Link Technologies Co., Ltd. and Huawei Technologies Co., Ltd. exemplify scale-driven manufacturing archetypes with integrated production ecosystems. NETGEAR, Inc. represents the premium-channel distribution model anchoring North American specialty retail and direct-to-consumer platforms. These three entities collectively illustrate the competitive tension between cost-optimized volume production and margin-rich service bundling strategies reshaping residential networking procurement patterns.
| Leading Market Players |
|---|
| TP-Link Technologies Co., Ltd. |
| NETGEAR, Inc. |
| ASUSTeK Computer Inc. |
| Cisco Systems, Inc. |
| D-Link Corporation |
| Huawei Technologies Co., Ltd. |
| Amazon.com, Inc. |
| Belkin International, Inc. |
| Others |
Supply & Pricing Matrix
Copper futures volatility on the London Metal Exchange cascades through enclosure manufacturing costs into tiered pricing for residential networking hardware, compressing margins on economy-grade routers while premium mesh systems absorb input inflation through bundled security subscriptions. Contract manufacturers in Shenzhen and Dongguan translate raw material swings into quarterly price adjustments that OEMs pass to North American retail channels with 60-90 day lag structures.
Pricing Analysis
Warranty and firmware-update bundling separates premium router tiers from transactional hardware sales, with NETGEAR and TP-Link attaching annual protection plans to tri-band Wi-Fi 6E systems at 40-60% attach rates. Three-tier pricing structure across premium, standard, and economy levels reflects certification complexity—FCC-CE-MIIT triple-approved SKUs command 25-35% premiums over single-market variants. Cost compression in entry-level Wi-Fi 5 segments intensifies because ODMs divert tri-band chipset allocation toward higher-ASP mesh systems. Small office buyers in India and China demonstrate highest price sensitivity, while United States gaming enthusiasts accept premiums for sub-20ms latency specifications.
Supply Chain Analysis
India's PLI scheme domestic-content mandates for telecom equipment are reshaping sourcing patterns, pressuring multinational OEMs to qualify local SMT assembly partners in Bengaluru and Chennai. Tri-band chipset fabrication concentrates in Taiwan and South Korea, with Wi-Fi 6E silicon drawing from TSMC 7nm and Samsung Foundry 8nm capacity. Rare earth magnet pricing for power supply components introduces commodity volatility that enclosure vendors in Dongguan hedge through six-month forward contracts. Single-source vulnerability concentrates in baseband processor supply, where Qualcomm and MediaTek dominate premium tier allocation. Distribution runs through specialized electronics distributors in Germany, direct-to-consumer platforms in the United States, and carrier bundling partnerships in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
6 GHz spectrum fragmentation functions as a consolidation mechanism, elevating compliance costs that marginalize regional assemblers lacking parallel FCC-CE-MIIT certification capabilities.
For Market Incumbents: Anchor tri-band router portfolios in backward integration toward captive chipset sourcing through TSMC allocation commitments, insulating margin structures from foundry node transition bottlenecks. Defend against Amazon and Google ecosystem entrants by hardening carrier-grade CPE bundling relationships with Deutsche Telekom, China Telecom, and Verizon—channels where cloud-platform players lack installation service infrastructure.
For New Entrants and Emerging Players: Matter protocol gateway firmware expertise offers a technology-first wedge into German and French smart home automation segments, where concrete construction drives mesh penetration and protocol consolidation creates hub replacement cycles. Target tier-2 Indian cities under TRAI broadband mandates, where PLI incentives reduce landed cost disadvantages against established Chinese ODMs. Pursue co-development partnerships with fiber infrastructure deployers rather than retail channel builds.
For Investors and Strategic Acquirers: Distressed-cycle entries favor ODM-scale fabricators with MIIT type-approval libraries and Shenzhen-based vertical production in China's fragmented 6 GHz regulatory environment. Long-term viability hinges on Wi-Fi 7 silicon transition readiness and Matter certification pipelines rather than legacy Wi-Fi 6 volume positions. Monitor FCC spectrum harmonization negotiations with EU and MIIT authorities as the inflection signal—unified band plans would collapse regional SKU proliferation and reward global platform vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Chipset Supply Agreement | TSMC 7nm allocation commitments secure tri-band silicon for Wi-Fi 6E volume ramps. |
| Matter Protocol Certification | Unified smart home standard collapses Zigbee and Z-Wave hub fragmentation into gateway margins. |
| Passive Thermal Design Transition | EU F-Gas Regulation compliance eliminates fan noise for German premium residential channels. |
| Carrier CPE Bundling Partnership | Deutsche Telekom and China Telecom installations lock in subscription recurring revenue streams. |
| India PLI Manufacturing Qualification | Domestic assembly incentives reduce tariff exposure for cost-optimized mesh system exports. |
Research Methodology
Document review covered FCC equipment authorization databases, MIIT radio transmission type-approval registries, and EU CE marking notification files, complemented by interviews with router ODM procurement directors, carrier CPE product managers, and smart home platform engineering leads. Secondary validation drew from TSMC and Samsung Foundry capacity disclosure filings, customs trade data for networking equipment HS codes, and broadband infrastructure deployment reports from TRAI, the FCC, and Germany's Federal Network Agency. Bottom-up unit shipment estimates by product tier triangulated against top-down addressable household calculations across fiber-to-the-home footprints.
Segmented outputs across the projection horizon model Wi-Fi 6E adoption curves against regulatory authorization timelines, mesh system penetration rates in multi-story residential construction markets, and Matter protocol device attach rates. The analytical framework incorporates technology transition cycles, spectrum harmonization scenarios, and carrier bundling contract tenures as structural inputs. CAGRs derive from installed base replacement dynamics and gigabit broadband subscription growth rather than extrapolated historical trends.
Several conditions sit outside the modeled scope, including unforeseen 6 GHz band plan reversals by national regulators, foundry node yield disruptions affecting tri-band chipset supply, and geopolitical trade restrictions altering Taiwan-China electronics corridor flows. Forecasts reflect documented assumptions regarding fiber-to-the-home buildout paces and remote work policy permanence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Private LTE Market
Network Technology
CPE Router Market
Network Technology
Router and Switch Market
Network Technology
Managed Switches Market
Network Technology
US Private 5G Network Market
Network Technology
Network Telemetry Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
5G CPE Device Market
Network Technology
Passive Optical LAN (POL) Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Microduct Market
Network Technology
Converged Cable Access Platform (CCAP) Market
Network Technology
Cloud Managed Access Points Market
Network Technology
Protocol Analyzer Market
Network Technology
Data Center Switches Market