
 Session Border Controller (SBC) Market | 2026-2036
Session Border Controller (SBC) Market Size, Share, and Industry Trends Forecast 2026-2036
Session Border Controller (SBC) Market Outlook
The capital-intensity divergence between hardware-centric and software-native vendors is collapsing as cloud-native architectures commoditize proprietary silicon advantages. Ribbon Communications Operating Company, Inc. leverages its heritage voice infrastructure base to sustain carrier-grade deployment relationships. Cisco Systems, Inc. anchors enterprise SBC demand through unified communications platform bundling. Huawei Technologies Co., Ltd. competes aggressively in emerging market telecom infrastructure where cost optimization dominates procurement criteria.
A Session Border Controller is a network element that governs the initiation, conduct, and termination of VoIP and unified communications sessions, enforcing security policies through deep packet inspection, encryption, and topology hiding while mediating signaling protocols including SIP, H.323, and WebRTC. Its primary commercial purpose is to protect enterprise and service provider networks from malicious traffic, ensure interoperability between dissimilar communications platforms, and maintain quality of service across session handoffs. Software SBC and Cloud SBC segments are capturing disproportionate growth momentum as containerized deployments displace purpose-built appliances in greenfield installations. The Managed Service deployment model is expanding fastest among mid-market enterprises lacking internal VoIP security expertise, while On-Premises hardware retains durable demand in defense and regulated financial institutions where data sovereignty requirements preclude off-premises signaling control.
FCC STIR/SHAKEN mandates and the EU's NIS2 Directive are tightening compliance burdens on voice service providers, directly stimulating SBC refresh cycles to embed authenticated caller ID and enhanced threat detection capabilities. GDPR and sector-specific frameworks such as HIPAA impose encrypted session management requirements that elevate feature-rich SBC procurement specifications above basic connectivity functions. Stakeholders must evaluate whether their current session border infrastructure can absorb emerging quantum-resistant encryption standards without forklift replacement, as algorithm transitions will likely compress typical replacement timelines for installed security gateways.
Market Dynamics
The migration from monolithic hardware appliances to cloud-native, containerized software stacks is collapsing traditional vendor moats built on proprietary silicon and forcing wholesale restructuring of deployment economics across carrier and enterprise segments.
Growth Catalysts
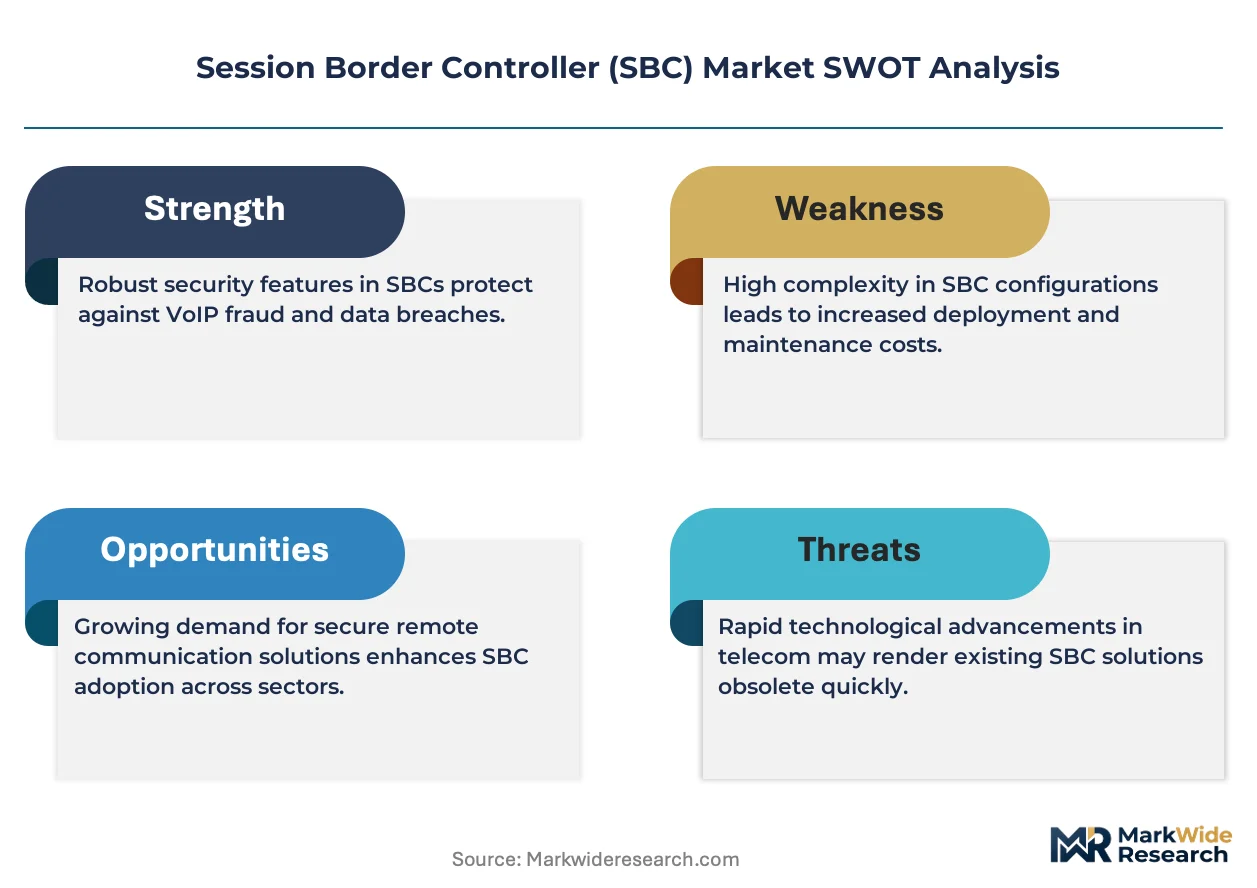
- FCC STIR/SHAKEN Framework:Mandated robocall mitigation in the United States compels voice service providers to refresh session border infrastructure for authenticated caller ID embedding, accelerating replacement cycles for legacy signaling gateways.
- Healthcare Encryption Requirements:HIPAA-mandated encrypted session management elevates procurement specifications for financial institutions and medical networks, disqualifying basic connectivity-focused SBC offerings.
- 5G Standalone Core Transition:Telecom operators deploying 5G SA architectures require security gateway reconfiguration, stimulating demand for signaling mediation capable of handling network slicing and edge orchestration.
Market Restraints
- Specialized Engineering Talent Scarcity:Deep expertise in SIP protocol stacks, WebRTC integration, and real-time packet inspection concentrates among a limited pool of engineers, inflating implementation costs and extending deployment timelines.
- Input Cost Volatility in Semiconductors:Purpose-built hardware SBCs remain dependent on FPGA and ASIC supply chains concentrated in Taiwan and South Korea, exposing margins to foundry capacity constraints.
- Regulatory Fragmentation:Divergent national encryption export controls and lawful intercept mandates create product variant proliferation, compressing economies of scale for standardized platform development.
Strategic Opportunities
- Mid-Market Managed Services Gap:Enterprises lacking internal VoIP security expertise present white space for managed SBC service models, particularly in Germany and France where GDPR complexity deters self-managed deployments.
- Quantum-Resistant Cryptography Migration:Early positioning for post-quantum encryption standards creates upgrade pathway capture opportunities as NIST algorithm finalization approaches.
- WebRTC-to-SIP Convergence:Browser-based communications integration with legacy enterprise telephony systems opens deployment scenarios in contact center modernization and remote workforce enablement.
Industry Challenges
- Multi-Vendor Interoperability Certification:Ensuring seamless signaling mediation across heterogeneous unified communications platforms from Microsoft, Cisco, and Avaya requires extensive testing matrices that delay revenue recognition.
- Container Orchestration Skill Gaps:Kubernetes-native SBC deployments demand DevOps competencies foreign to traditional telecom engineering organizations, creating implementation friction and customer churn risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Session Border Controller (SBC) Market |
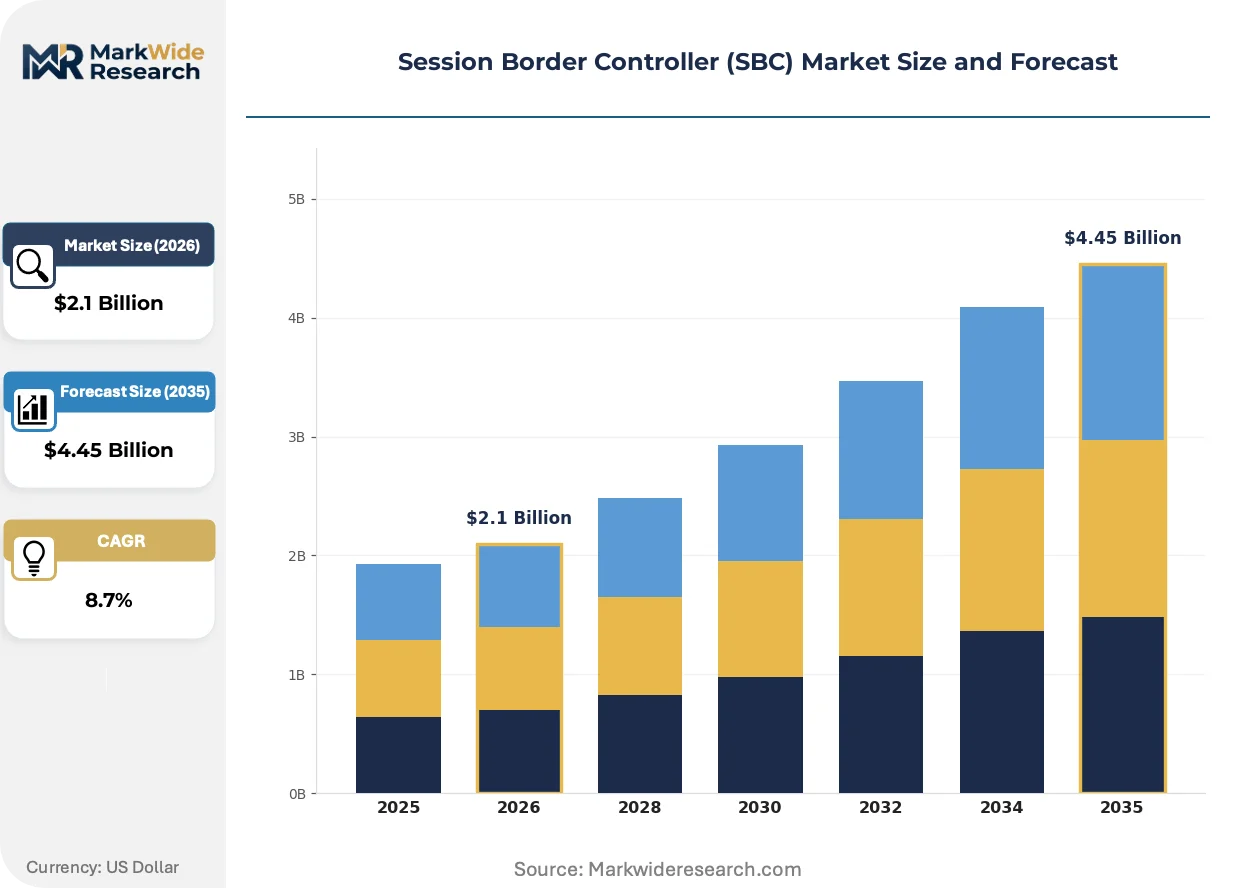
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware SBC, Software SBC, Virtual SBC, Cloud SBC Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Service End User: Telecom Operators, Enterprises, Service Providers, OEMs Feature: Security, Interoperability, Load Balancing, Call Routing |
| Companies Covered | Ribbon Communications Operating Company, Inc., AudioCodes Ltd., Cisco Systems, Inc., Oracle, Huawei Technologies Co., Ltd., Nokia, Avaya Inc., ADTRAN, TelcoBridges Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Session Border Controller (SBC) Market Strategic Shifts
Containerized software architectures are decomposing the monolithic appliance model that dominated session border control for two decades, redistributing value capture toward orchestration platforms and away from proprietary hardware vendors.
Cloud-native SBC software is decomposing the integrated appliance stack into microservices-based signaling, media, and policy functions. Tier-1 carriers in Japan and South Korea are deploying these disaggregated components at network edge locations, compressing capital requirements for distributed security gateway coverage while enabling elastic scaling during traffic spikes.
Europe's NIS2 Directive tightens cybersecurity governance obligations on voice service providers, mandating incident reporting thresholds and supply chain risk management that reshape procurement evaluation criteria. German and French operators are embedding these compliance requirements into RFP specifications ahead of enforcement deadlines, favoring vendors with pre-certified security frameworks over commodity connectivity providers.
Enterprise buyers are consolidating vendor relationships through unified communications platform bundling, displacing standalone SBC procurement. Microsoft Teams Phone System deployments in United States financial services and United Kingdom professional services verticals increasingly specify native or certified session border elements, compressing addressable market scope for independent gateway specialists.
Session Border Controller (SBC) Market Segmentation
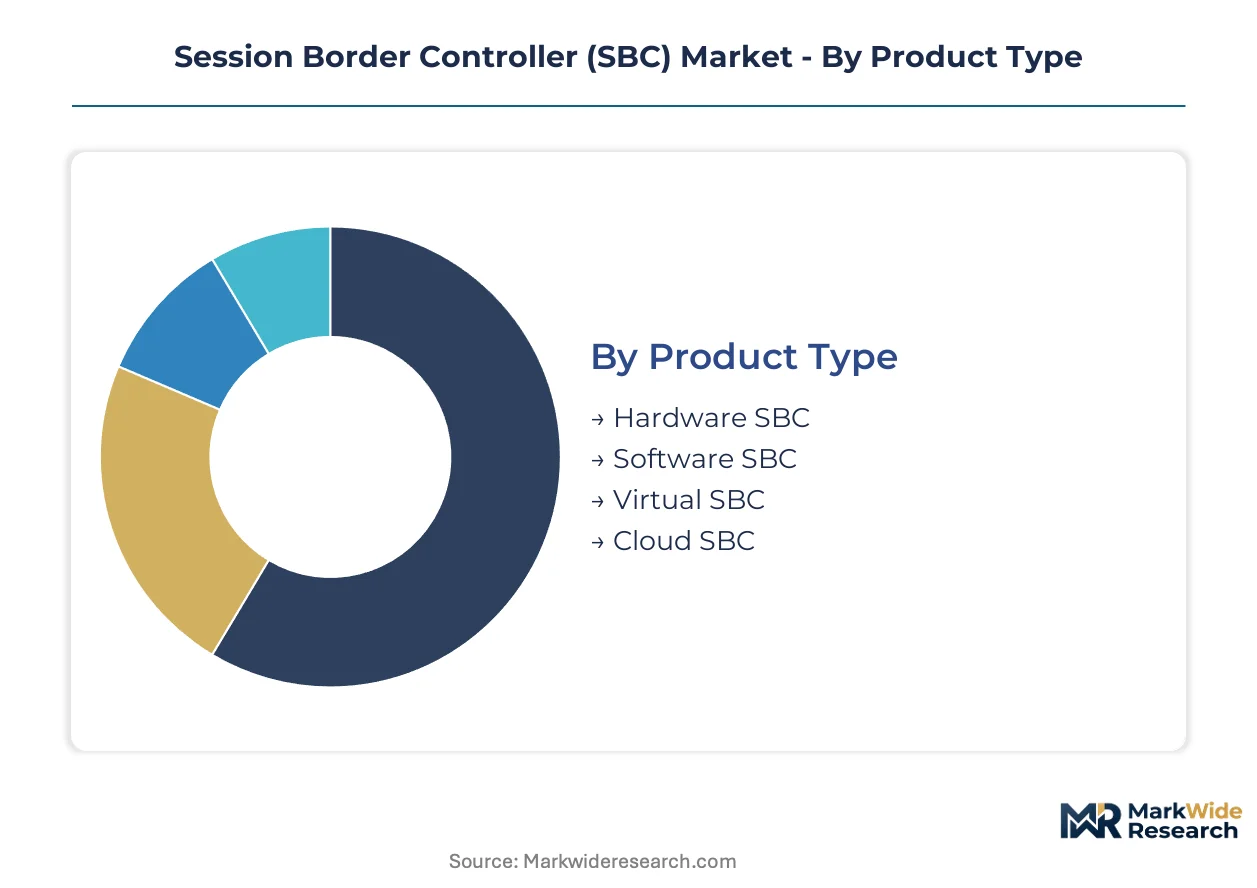
Session Border Controller procurement patterns diverge sharply across deployment architectures and buyer capabilities, with cloud-native alternatives displacing purpose-built appliances in greenfield installations while regulated verticals sustain durable hardware demand. Understanding these segment boundaries clarifies where vendor restructuring investments concentrate and where margin compression risks intensify.
Product Type:
Geographic demand concentration varies by product architecture, with cloud-native formats scaling fastest in North American and Western European enterprise markets while hardware-centric deployments retain dominance in Asia-Pacific telecom infrastructure buildouts.
- Hardware SBC:Purpose-built appliances integrating proprietary FPGA and ASIC silicon for carrier-grade signaling throughput. Defense agencies in the United States and regulated financial institutions in Switzerland and Germany specify hardware form factors to satisfy data sovereignty and tamper-resistance mandates that preclude virtualized alternatives.
- Software SBC:Disaggregated signaling and media processing functions deployable on commercial-off-the-shelf servers. Tier-1 operators in Japan and South Korea favor software SBC for 5G standalone core deployments where network slicing requires flexible policy orchestration.
- Virtual SBC:Hypervisor-based instances running on private cloud infrastructure within enterprise data centers. German automotive manufacturers deploy virtual SBC to bridge legacy PBX systems with Microsoft Teams while retaining on-premises control.
- Cloud SBC:Fully managed, multi-tenant services delivered via SaaS consumption models. Mid-market enterprises in the United Kingdom and France lacking internal SIP expertise drive adoption through managed service wrappers.
Hardware SBC commands the established base. The steepest expansion runs through Cloud SBC.
Deployment Model:
Buyer technical sophistication and regulatory exposure determine deployment model selection, with compliance-heavy verticals accepting higher capital burdens to retain direct infrastructure control.
- On-Premises:Customer-operated appliances within owned or colocated facilities. Swiss banking regulators and United States defense contractors mandate on-premises signaling control to satisfy audit trail and lawful intercept requirements that cloud architectures cannot accommodate.
- Cloud-Based:Third-party hosted infrastructure with customer-managed configuration. Professional services firms in London and Singapore adopt cloud-based SBC to accelerate unified communications rollouts without capital commitment.
- Hybrid:Split architectures combining on-premises session management with cloud bursting for traffic spikes. Australian healthcare networks deploy hybrid models to maintain HIPAA-equivalent patient data control while leveraging cloud elasticity for seasonal contact center volumes.
- Managed Service:Outsourced operation and maintenance by specialized service providers. French and German mid-market manufacturers lacking DevOps competencies favor managed service SBC to navigate GDPR complexity without internal security expertise.
On-Premises retains the revenue base. Managed Service climbs the fastest.
End User:
Procurement scale and technical specification authority concentrate differently across buyer categories, with telecom operators driving volume and enterprises diversifying feature requirements.
- Telecom Operators:National and multinational carriers requiring carrier-grade scalability and interconnection certification. Operators in South Korea and Japan specify SBC for 5G voice over new radio (VoNR) and network slicing security gateway functions.
- Enterprises:Corporate and government organizations securing internal unified communications. United States financial services firms embed SBC within zero-trust architectures to satisfy SEC cybersecurity disclosure rules.
- Service Providers:Voice over IP resellers and cloud communications platforms requiring multi-tenant session management. Unified-communications-as-a-service providers in the United Kingdom leverage SBC for STIR/SHAKEN compliance without infrastructure ownership.
- OEMs:Equipment manufacturers integrating SBC functions into broader networking or security platforms. Network equipment vendors in Taiwan incorporate SBC modules into converged security appliances for Southeast Asian telecom markets.
Telecom Operators anchor volume procurement. Enterprises diversify fastest.
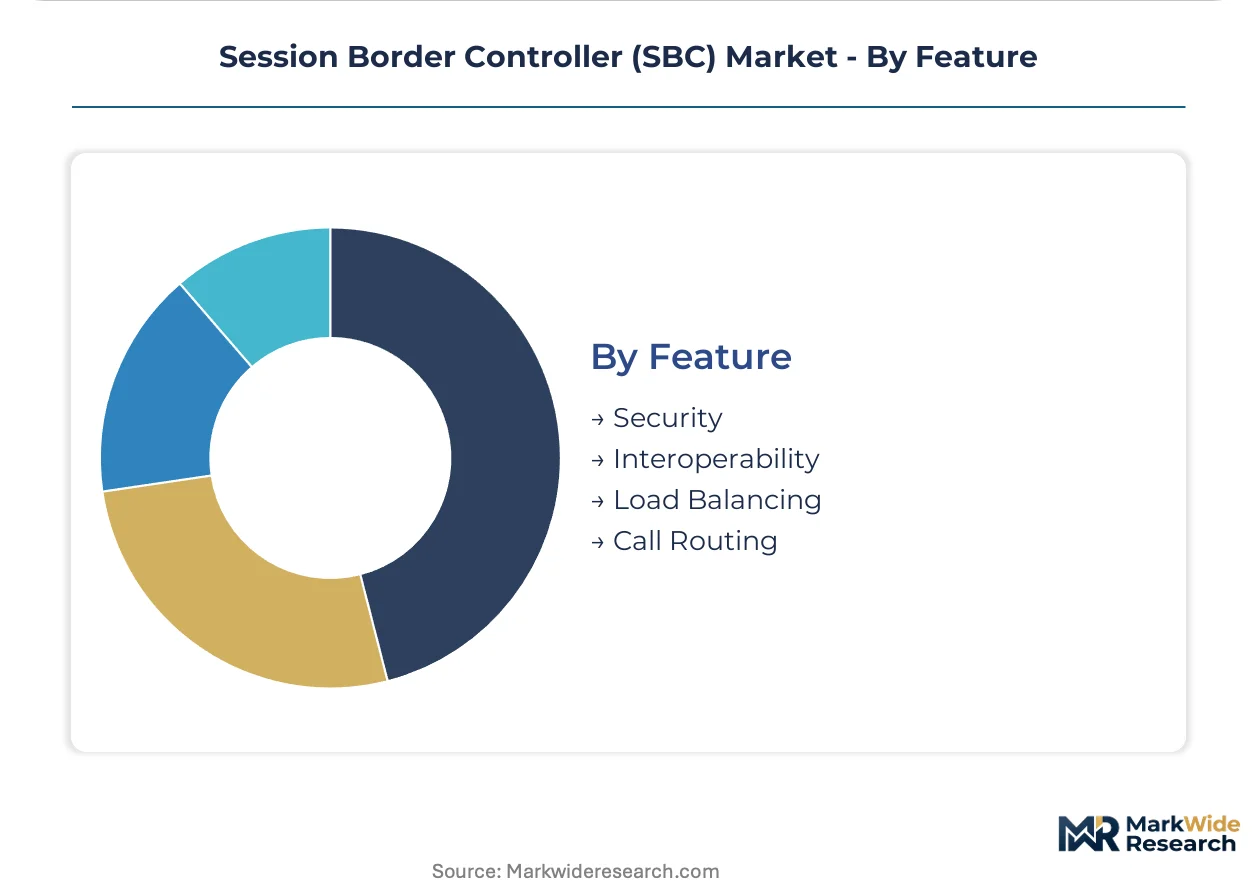
Feature:
Feature prioritization reflects buyer threat exposure and interoperability complexity, with security and interoperability functions commanding premium positioning over commodity connectivity.
- Security:Encryption, topology hiding, denial-of-service protection, and threat detection. Healthcare networks in the United States specify security-rich SBC to satisfy HIPAA encryption mandates for patient communications.
- Interoperability:Protocol mediation between SIP, H.323, WebRTC, and proprietary signaling variants. Contact center modernization in Germany requires interoperability functions to bridge browser-based WebRTC agents with legacy Avaya infrastructure.
- Load Balancing:Traffic distribution across multiple SBC instances for resilience and scale. Cloud communications providers in Singapore deploy load balancing to maintain service continuity during regional traffic spikes.
- Call Routing:Intelligent session direction based on policy, cost, or quality metrics. Wholesale carriers in the United Kingdom utilize call routing optimization to manage termination cost variance across international destinations.
Security functions command premium positioning. Interoperability expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in session border controller technology, exporting cloud-native software stacks and security gateway platforms while importing specialized FPGA components from Taiwan and South Korea. Germany and Japan balance modest exports of carrier-grade hardware against significant software licensing imports from American vendors. China's domestic production capabilities increasingly satisfy local telecom operator demand, reducing import dependency for 5G security infrastructure.
United States
FCC STIR/SHAKEN mandates compel voice service providers to refresh session border infrastructure for authenticated caller ID embedding. The SEC's cybersecurity disclosure rules drive financial institutions toward zero-trust SBC architectures. Silicon Valley vendors and Boston-area security specialists dominate cloud-native software development for enterprise unified communications.
Germany
GDPR complexity and NIS2 Directive compliance obligations deter self-managed SBC deployments among mid-market manufacturers. Germany's national cybersecurity regulator mandates incident reporting thresholds that reshape procurement evaluation criteria. Bavarian automotive manufacturers deploy virtual SBC to bridge legacy PBX systems with Microsoft Teams while retaining on-premises control.
Japan
METI's digital infrastructure investments accelerate 5G standalone core deployments requiring security gateway reconfiguration. Tier-1 carriers specify SBC for voice over new radio and network slicing functions. Tokyo and Osaka metropolitan clusters concentrate carrier-grade software development and systems integration expertise.
South Korea
Telecom operators deploying 5G SA architectures stimulate demand for signaling mediation capable of handling network slicing and edge orchestration. The country's national technology regulator emphasizes supply chain risk management for critical communications infrastructure. Seoul Capital Area vendors concentrate cloud-native SBC development for export markets.
United Kingdom
Professional services firms in London adopt cloud-based SBC to accelerate unified communications rollouts without capital commitment. Unified-communications-as-a-service providers leverage SBC for STIR/SHAKEN compliance without infrastructure ownership. The Southeast England technology corridor hosts managed service providers targeting GDPR-averse continental European clients.
Session Border Controller (SBC) Market Competitive Environment
Concentration sits with integrated networking vendors and specialized session management providers, with the vendor base stratifying across three capability tiers. Tier-1 positions are occupied by firms bundling SBC functions within broader unified communications or telecom infrastructure platforms. Tier-2 specialists concentrate on protocol interoperability and security gateway optimization. Tier-3 regional vendors compete on cost optimization for emerging market deployments. The dominant competitive moves involve portfolio diversification into adjacent security functions and strategic partnerships with cloud communications platforms.
Within the integrated platform tier, Ribbon Communications Operating Company, Inc. and Cisco Systems, Inc. exemplify contrasting heritage strategies—one leveraging carrier-grade voice infrastructure relationships, the other anchoring enterprise demand through unified communications bundling. Huawei Technologies Co., Ltd. occupies a distinct position competing aggressively in emerging market telecom infrastructure where procurement criteria emphasize cost optimization over proprietary feature depth.
| Leading Market Players |
|---|
| Ribbon Communications Operating Company, Inc. |
| AudioCodes Ltd. |
| Cisco Systems, Inc. |
| Oracle |
| Huawei Technologies Co., Ltd. |
| Nokia |
| Avaya Inc. |
| ADTRAN |
| TelcoBridges Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day FPGA procurement lead times from Taiwan foundries compress margin buffers for hardware-centric vendors while amplifying pricing power for software-native competitors with containerized delivery models. This inventory-to-pricing dynamic concentrates procurement leverage among Tier-1 carriers with volume commitments, forcing mid-market buyers toward SaaS consumption to bypass silicon dependency.
Pricing Analysis
Configured-to-order hardware appliances command 40-60% premiums over standard virtualized licenses, reflecting customization engineering for carrier-grade throughput specifications. Three-tier pricing structure across premium, standard, and economy levels segments by certification depth—FCC STIR/SHAKEN pre-certification attracts premium positioning, while basic connectivity functions face commoditization. Cost compression in economy-tier software licenses is intensifying because hyperscaler bundling absorbs standalone gateway value. Mid-market enterprises lacking DevOps competencies exhibit highest price sensitivity, whereas defense contractors mandate premium hardware regardless of cost.
Supply Chain Analysis
Strategic stockpiling of FPGA and ASIC components distinguishes carrier-grade hardware vendors from software-native competitors running lean inventory models. Taiwan, South Korea, and the United States anchor semiconductor supply for proprietary silicon, while India and Ireland concentrate software development talent. Taiwan Strait logistics chokepoints present single-source vulnerability for purpose-built appliances. Distribution runs through direct enterprise sales for on-premises deployments and hyperscaler marketplaces for cloud-native consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep expertise in SIP protocol stacks, WebRTC integration, and Kubernetes orchestration concentrates among a limited engineering pool, creating structural bottlenecks that favor incumbents with captive talent development programs over resource-constrained challengers.
For Market Incumbents: Fortify carrier-grade deployment relationships through backward integration into FPGA design capabilities, insulating against Taiwan foundry capacity constraints. Invest in STIR/SHAKEN pre-certification pipelines to capture FCC-mandated refresh cycles before commodity competitors close compliance gaps. For New Entrants and Emerging Players: Anchor in mid-market managed service white space across German and French manufacturing verticals, where GDPR complexity deters self-managed deployments. Target WebRTC-to-SIP convergence scenarios in contact center modernization, leveraging browser-native integration as a deployment velocity advantage over legacy gateway specialists. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because containerization collapses hardware moats and concentrates value capture among orchestration platform owners. Acquisition targets should demonstrate Kubernetes-native architectures and certified hyperscaler marketplace presence. The signal to watch is Microsoft Teams Phone System bundling penetration—acceleration compresses standalone SBC addressable markets and triggers distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Cryptography Migration | NIST algorithm finalization will force premature replacement cycles for encryption-dependent installed base. |
| Hyperscaler Marketplace Certification | AWS and Azure marketplace presence determines enterprise procurement funnel access for cloud-native vendors. |
| Managed Service Wrapper Development | GDPR complexity in Germany and France converts technical capability gaps into recurring revenue streams. |
| WebRTC-Native Architecture Investment | Browser-based communications integration opens contact center modernization and remote workforce scenarios. |
| 5G Standalone Core Partnership | Network slicing security gateway requirements in Japan and South Korea anchor carrier-grade volume procurement. |
Study Parameters
Cross-validation between primary interviews with carrier network architects, enterprise IT directors, and UCaaS platform engineers and secondary analysis of FCC STIR/SHAKEN implementation filings, hyperscaler capex disclosures, and carrier equipment procurement databases anchors the qualitative findings. Bottom-up triangulation across deployment model adoption rates and top-down validation against telecom infrastructure investment cycles ensure segmentation integrity.
Sensitivity analysis across deployment architecture migration scenarios, semiconductor supply disruption bands, and regulatory compliance deadline shifts shapes the analytical framework. Modeled dimensions span product type, deployment model, end-user category, and geographic adoption pattern throughout the forecast period. CAGRs derive from fitted growth curves against historical replacement cycle data and projected 5G standalone core rollout density.
Underlying assumptions cover carrier capital commitment continuity, hyperscaler bundling penetration trajectories, and NIST post-quantum algorithm standardization timelines, with deviation risk concentrated in Taiwan semiconductor supply stability and FCC enforcement intensity variation. Revision becomes warranted when enterprise Kubernetes adoption crosses 70% penetration or when quantum-resistant encryption mandates accelerate beyond baseline projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Global Wireless Router Market
Network Technology
Global Network Management Market
Network Technology
North America Structured Cabling Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Carrier Routing Equipment Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Europe SD-WAN Market
Network Technology
5G Enterprise Private Network Market
Network Technology
Global Industrial Ethernet Switch Market
Network Technology
Fiber to the Premises Market
Network Technology
Global Managed Wi-Fi Solutions Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Power Over Ethernet (Poe) Solutions Market
Network Technology
Optical Network Equipment Market
Network Technology
Low-Power WAN Market