
 Europe Self-Healing Networks Market | 2026-2036
Europe Self-Healing Networks Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Self-Healing Networks Market Analytics
The EU Green Deal is expanding the addressable base for energy-efficient network infrastructure across European telecom and utility sectors. Deutsche Telekom leverages its integrated fiber and mobile footprint to pilot autonomous remediation protocols in German metropolitan zones. Ericsson anchors its competitive stance through sustained R&D investment in intent-based networking software for European mobile operators. Nokia Corporation dominates the radio access segment by extending its Digital Operations Center portfolio with machine-learning-driven fault prediction modules.
Self-healing networks constitute autonomous communication infrastructure capable of detecting, diagnosing, and remediating service degradations without human intervention, typically employing closed-loop control architectures with sub-second response thresholds to preserve quality-of-service guarantees for critical applications. Artificial Intelligence and Network Automation command the largest current revenue share, while Machine Learning represents the fastest-expanding technology layer as European operators prioritize predictive over reactive operational models. Telecom Operators absorb the dominant share of end-user expenditure, though Utility Companies are emerging as a structurally higher-margin segment due to stricter uptime requirements and longer contract durations in smart grid modernization programs.
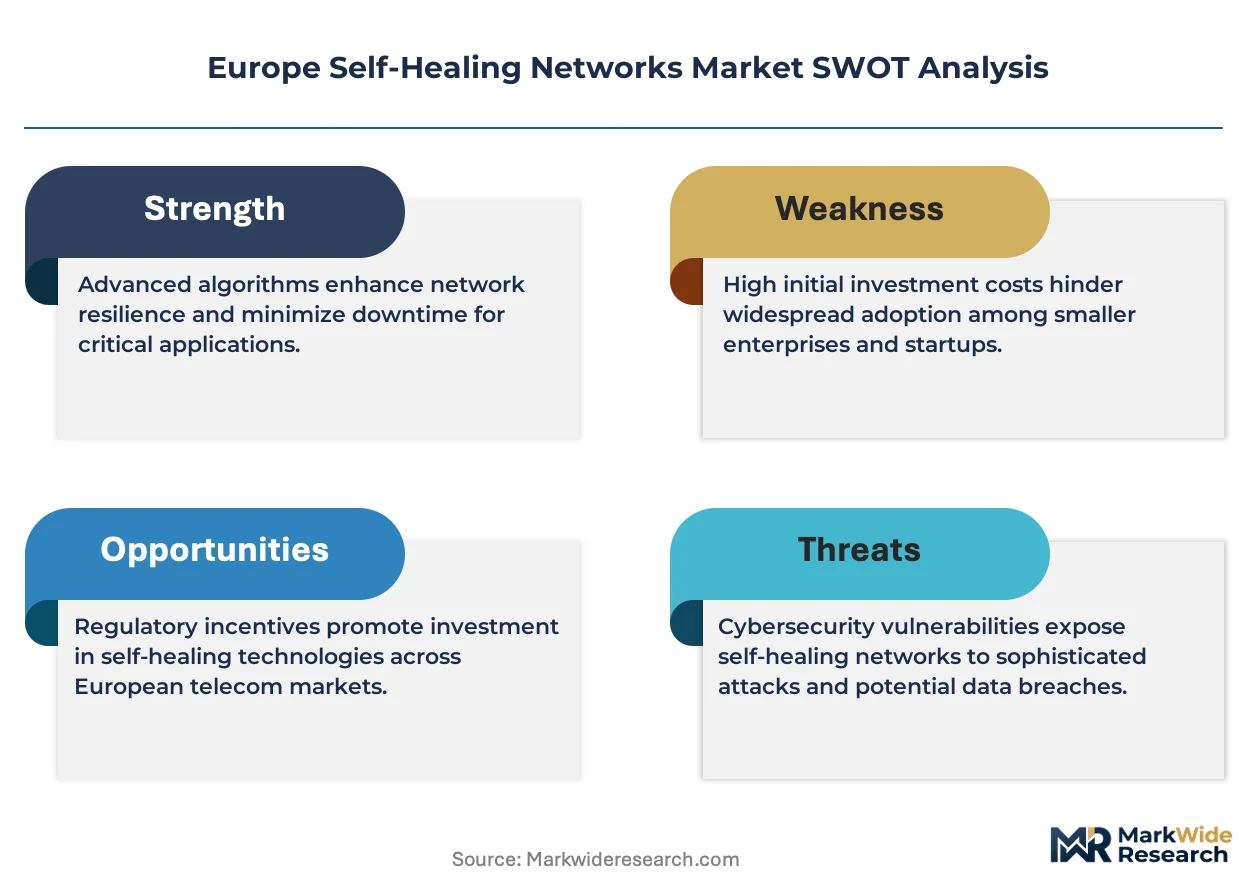
The European Telecommunications Standards Institute coordinates technical specifications for autonomous network management, while the EU AI Act imposes conformity assessment obligations on algorithmic decision systems controlling critical infrastructure. National regulators including Germany's Federal Network Agency and France's ANSSI enforce sector-specific resilience mandates that directly shape procurement criteria for self-healing platforms. Stakeholders must monitor the evolving intersection of product liability frameworks and algorithmic accountability rules as these determine which vendors can sustain market access across member states.
Market Dynamics
The EU AI Act's conformity assessment obligations for algorithmic systems controlling critical infrastructure are compressing procurement timelines and reshaping vendor qualification criteria across European telecom and utility sectors.
Growth Catalysts
- EU Green Deal energy efficiency mandates:Utility companies in Scandinavia and the Low Countries face binding decarbonization targets that accelerate smart grid modernization and autonomous network deployment.
- 5G standalone network rollouts:Telecom operators across Germany, France, and the United Kingdom require sub-second fault remediation to meet quality-of-service guarantees for industrial IoT and mission-critical applications.
- Machine learning adoption:Predictive operational models are displacing reactive maintenance frameworks, driving investment in intent-based networking software and closed-loop control architectures.
Market Restraints
- Semiconductor supply concentration:Specialized AI accelerators and network processing units depend on fabrication capacity concentrated in East Asian foundries, exposing European vendors to geopolitical supply disruptions.
- EU AI Act compliance costs:Conformity assessment procedures for high-risk algorithmic systems impose documentation and testing burdens that extend sales cycles by twelve to eighteen months for zero-touch automation platforms.
- Legacy infrastructure incompatibility:Brownfield telecom and utility environments running proprietary management protocols resist seamless integration with open-standard autonomous remediation systems.
Strategic Opportunities
- Polish and Romanian utility modernization:These markets exhibit underpenetrated smart grid infrastructure with accelerating EU cohesion fund allocations for network resilience investments.
- Convergence of digital twins with self-healing networks:Real-time simulation layers combined with autonomous remediation create predictive maintenance capabilities for transmission grid operators.
- CSRD sustainability reporting requirements:The Corporate Sustainability Reporting Directive mandates granular energy consumption disclosure, creating procurement preference for infrastructure vendors with verified efficiency metrics.
Industry Challenges
- Intent-based networking expertise scarcity:European operators report acute shortages of engineers capable of translating business policies into machine-executable network configurations.
- Multi-vendor interoperability certification:Fragmented testing regimes across Germany's Federal Network Agency, France's ANSSI, and the Netherlands' NCSC delay product launches and inflate compliance expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Self-Healing Networks Market |
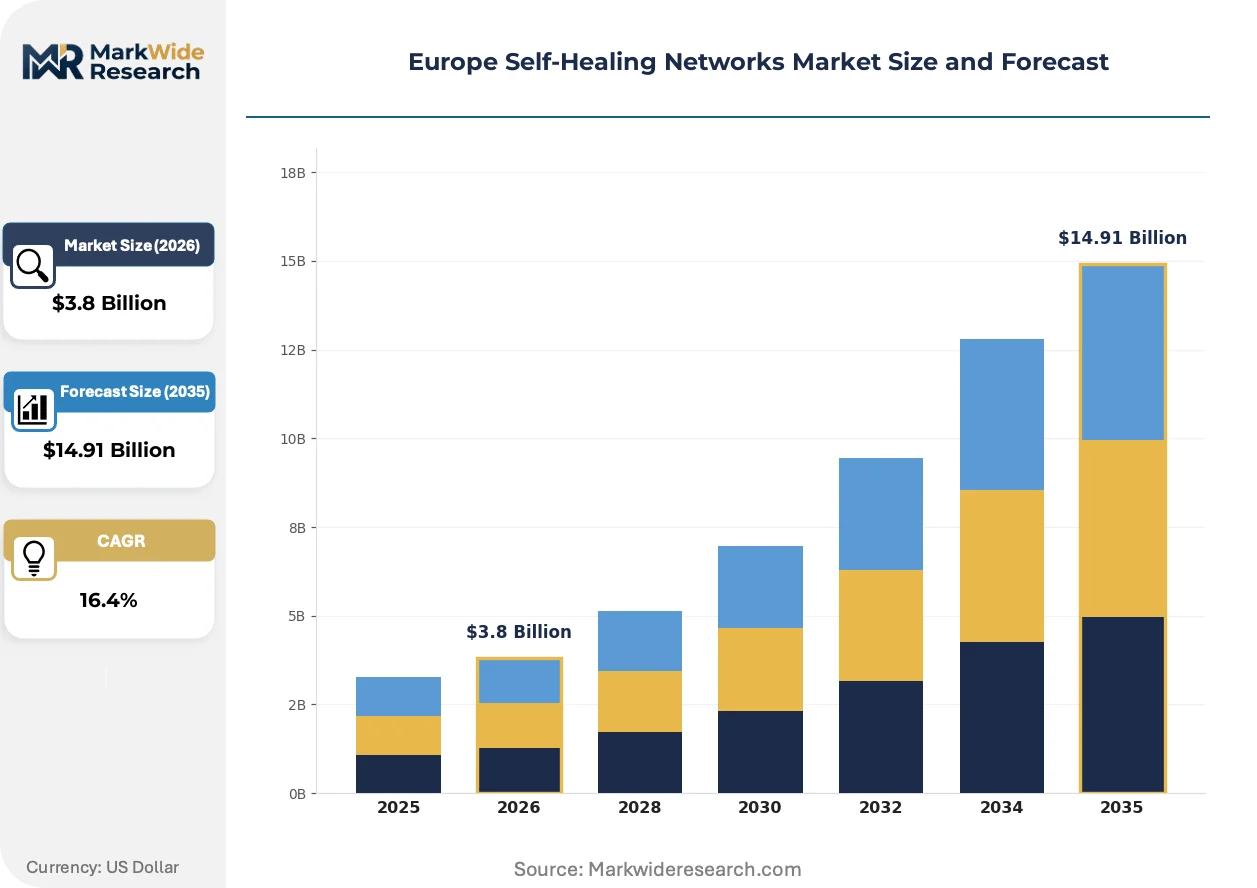
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Artificial Intelligence, Data Analytics, Network Automation Application: Telecommunications, Smart Grids, IoT Devices, Data Centers End User: Telecom Operators, Utility Companies, Enterprise Businesses, Managed Service Providers Service Type: Consulting, Integration, Support, Maintenance |
| Companies Covered | Deutsche Telekom, Ericsson, Elisa Polystar, Cisco Systems, Nokia Corporation, Hewlett Packard Enterprise, Siemens, NEC, IBM Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Self-Healing Networks Market Evolving Landscape
Autonomous network architectures are migrating from pilot deployments to production-grade infrastructure, with European operators prioritizing predictive capabilities over reactive monitoring systems.
Intent-based networking software is electrifying how telecom operators translate service-level objectives into automated infrastructure adjustments. Deutsche Telekom and BT Group are deploying these systems across metropolitan fiber and mobile cores. This technology is compressing mean-time-to-repair metrics from hours to milliseconds while reducing operational headcount requirements.
The EU AI Act's risk classification framework for algorithmic decision systems is mandating explainability and human oversight protocols for autonomous remediation engines. Vendors must now document training data provenance and decision logic to obtain CE marking for high-risk applications. German and French regulators are enforcing these requirements most stringently, with conformity assessment bodies in Munich and Paris experiencing twelve-month backlogs.
Outcome-based infrastructure contracts are displacing traditional equipment procurement across Nordic utility consortia. Transmission system operators in Denmark and Sweden now compensate vendors on network availability metrics rather than capital expenditure. This shift concentrates most visibly among regional grid modernization programs where uptime guarantees exceed 99.999 percent.
Europe Self-Healing Networks Market Segmentation
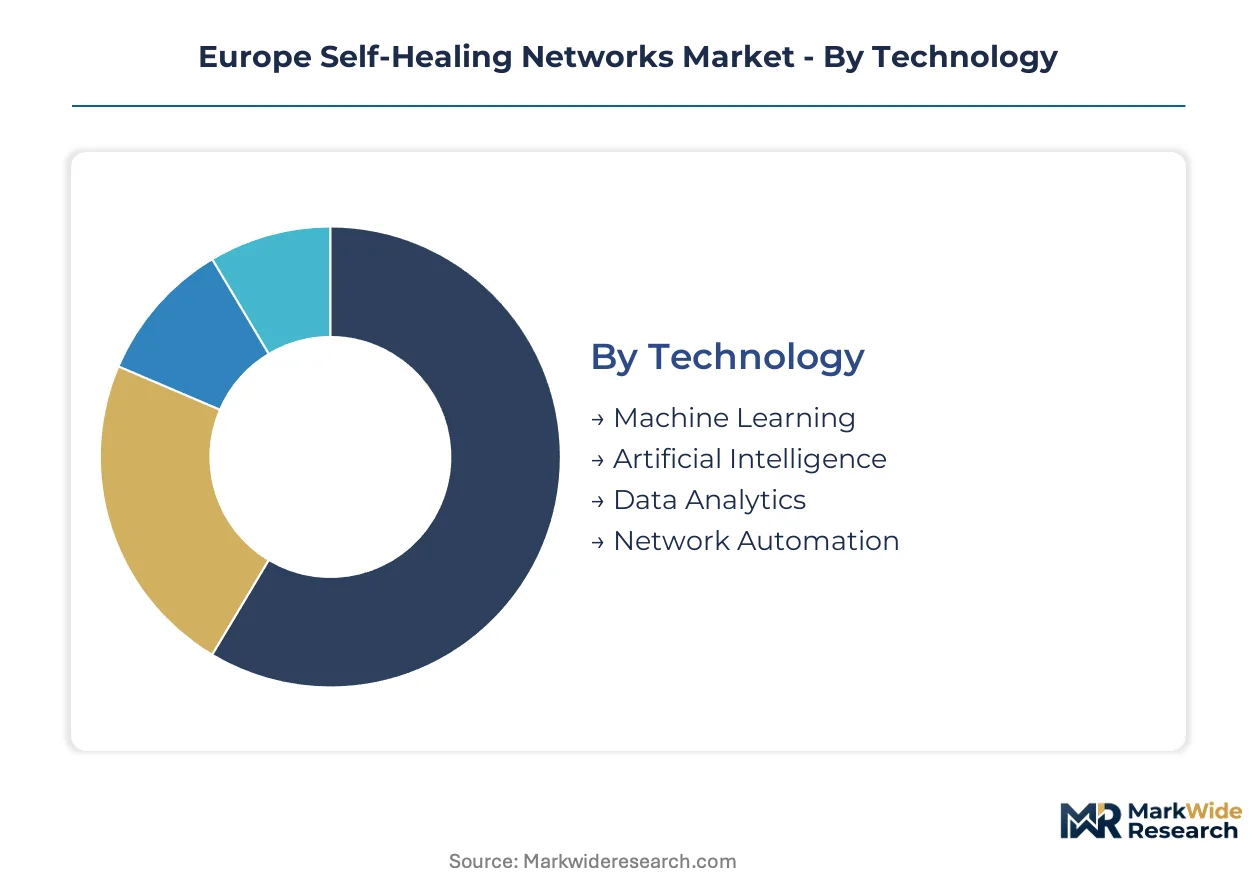
Self-healing networks demand heterogeneous technology stacks and service delivery models across European telecom and utility verticals. Procurement patterns diverge sharply between capital-intensive infrastructure owners and outsourced managed service arrangements.
Technology:
Supply concentration among specialized AI accelerator vendors shapes deployment economics for European network operators.
- Artificial Intelligence:Closed-loop control architectures employ neural networks for real-time fault detection and autonomous remediation decisions. Deutsche Telekom and BT Group deploy these systems across metropolitan fiber cores to compress mean-time-to-repair metrics. The EU AI Act imposes conformity assessment obligations that extend procurement cycles.
- Machine Learning:Predictive models analyze telemetry streams to anticipate equipment degradation before service impact. Scandinavian utility operators prioritize this layer for smart grid modernization programs with 99.999 percent uptime guarantees. Intent-based networking software translates business policies into machine-executable configurations.
- Network Automation:Orchestration platforms enable zero-touch provisioning and policy-driven infrastructure adjustments across multi-vendor environments.
- Data Analytics:Real-time processing engines correlate cross-domain telemetry to identify root causes of cascading failures in complex network topologies.
Artificial Intelligence absorbs the bulk of installed capacity; Machine Learning is expanding most quickly.
Application:
End-use requirements vary dramatically across latency-sensitive telecommunications and availability-critical utility infrastructure.
- Telecommunications:5G standalone rollouts in Germany, France, and the United Kingdom demand sub-second fault remediation for industrial IoT quality-of-service guarantees. Ericsson and Nokia anchor supply relationships with integrated fiber and mobile operators.
- Smart Grids:Transmission system operators in Denmark and Sweden compensate vendors on network availability metrics rather than capital expenditure. EU Green Deal decarbonization mandates accelerate deployment across Scandinavia and the Low Countries.
- Data Centers:Hyperscale facilities require autonomous thermal and power management to maintain service-level agreements for cloud workloads.
- IoT Devices:Massive sensor deployments in manufacturing and logistics drive edge-computing remediation capabilities with constrained computational resources.
Telecommunications captures dominant expenditure share; Smart Grids exhibits the steepest expansion trajectory.
End User:
Customer type determines contract structure, with utility procurement favoring outcome-based availability agreements over equipment-centric telecom sourcing.
- Telecom Operators:Deutsche Telekom, Orange, and BT Group pilot autonomous remediation protocols across converged fiber and mobile footprints. These operators absorb the dominant share of end-user expenditure for zero-touch automation platforms.
- Utility Companies:Regional transmission and distribution operators in Poland and Romania exhibit underpenetrated smart grid infrastructure with accelerating EU cohesion fund allocations. Longer contract durations and stricter uptime requirements produce structurally higher margins.
- Enterprise Businesses:Manufacturing and financial services firms deploy self-healing campus networks to maintain operational continuity for digital transformation initiatives.
- Managed Service Providers:Outsourced network operations specialists aggregate demand across mid-market enterprises lacking internal automation expertise.
Telecom Operators command the largest addressable base; Utility Companies are gaining share fastest.
Service Type:
Delivery model selection reflects internal capability maturity and regulatory documentation burdens across European member states.
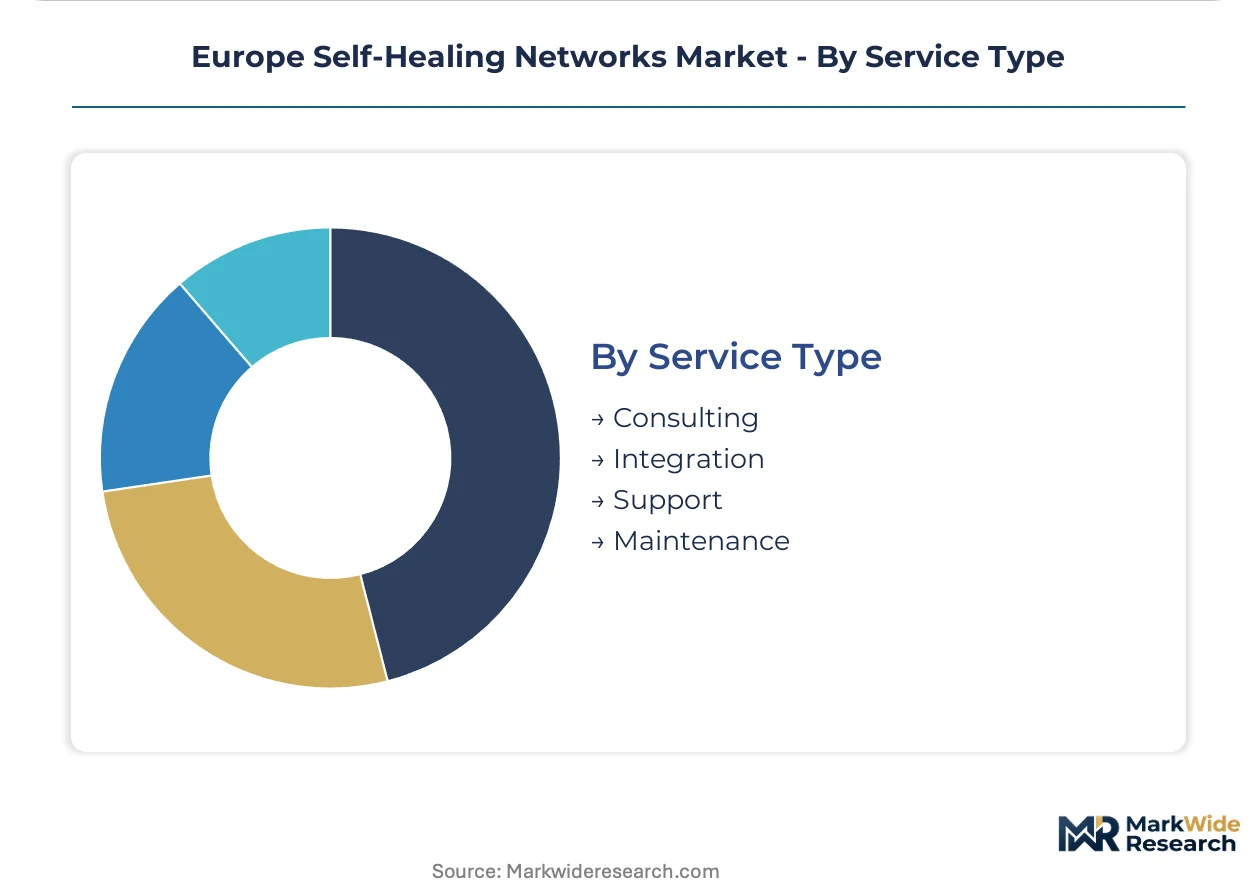
- Integration:System integrators bridge legacy brownfield protocols with open-standard autonomous remediation architectures. France's ANSSI and Germany's Federal Network Agency enforce multi-vendor interoperability certification requirements that inflate deployment complexity.
- Consulting:Advisory services translate EU AI Act conformity assessment obligations into technical documentation and testing protocols for algorithmic decision systems controlling critical infrastructure.
- Support:Continuous engineering assistance maintains closed-loop control architectures with sub-second response thresholds.
- Maintenance:Predictive operational models displace reactive maintenance frameworks through machine-learning-driven fault prediction modules.
Integration services absorb the bulk of professional services revenue; Consulting is climbing the fastest amid regulatory compliance pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin anchors European autonomous network deployment through Deutsche Telekom's metropolitan fiber pilots, while regional procurement patterns diverge sharply between Nordic utility modernization and Mediterranean telecom consolidation.
Germany
Deutsche Telekom's converged fiber-mobile infrastructure drives demand for intent-based networking software across metropolitan zones. The Federal Network Agency enforces multi-vendor interoperability certification that extends deployment timelines for zero-touch platforms. Munich hosts conformity assessment bodies experiencing twelve-month backlogs for EU AI Act documentation.
United Kingdom
BT Group pilots autonomous remediation protocols across converged network footprints to meet 5G standalone quality-of-service guarantees. National cybersecurity directives from the National Cyber Security Centre reshape procurement criteria for critical infrastructure automation. London concentrates managed service provider activity for mid-market enterprises lacking internal automation expertise.
France
Orange deploys closed-loop control architectures for industrial IoT applications requiring sub-second fault remediation. ANSSI enforces sector-specific resilience mandates that directly shape vendor qualification for algorithmic systems controlling critical infrastructure. Paris-based conformity assessment bodies impose stringent explainability requirements for autonomous remediation engines.
Scandinavia
Transmission system operators in Denmark and Sweden compensate vendors on network availability metrics exceeding 99.999 percent rather than capital expenditure. EU Green Deal decarbonization mandates accelerate smart grid modernization across Nordic utility consortia. Copenhagen and Stockholm host outcome-based infrastructure contract negotiations that displace traditional equipment procurement.
Poland
Regional distribution operators exhibit underpenetrated smart grid infrastructure with accelerating EU cohesion fund allocations for network resilience investments. The country's national telecom regulator enforces uptime requirements that drive procurement of predictive operational models. Warsaw clusters system integrators bridging legacy brownfield protocols with open-standard autonomous architectures.
Europe Self-Healing Networks Market Competitive Landscape
Premium-margin players sit above commodity-margin players across algorithmic sophistication and regulatory compliance depth, with the vendor base consolidating around three structural tiers. Tier-one incumbents leverage integrated fiber-mobile footprints to bundle autonomous remediation with core infrastructure contracts. Tier-two specialists concentrate on intent-based networking software for multi-vendor environments. Tier-three regional system integrators compete on deployment velocity and legacy protocol bridging. M&A activity targets machine-learning talent pools, while strategic partnerships with conformity assessment bodies compress CE marking timelines for high-risk algorithmic systems.
Among Nordic-origin specialists, Elisa Polystar exemplifies the predictive analytics archetype for telecom operator environments. Within the integrated infrastructure tier, Nokia Corporation and Ericsson occupy positions that span radio access through digital operations center portfolios. Siemens represents the industrial automation convergence archetype, bridging utility grid modernization with autonomous network management. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning across European procurement cycles.
| Leading Market Players |
|---|
| Deutsche Telekom |
| Ericsson |
| Elisa Polystar |
| Cisco Systems |
| Nokia Corporation |
| Hewlett Packard Enterprise |
| Siemens |
| NEC |
| IBM Corporation |
| Others |
Value Network & Pricing Analysis
Outcome-based procurement mandates from Nordic transmission system operators are forcing vendors to restructure revenue models around availability guarantees rather than equipment sales, compressing margins for hardware-centric suppliers while elevating software and services pricing power. This shift feeds back into supply chain configuration, with vendors prioritizing component sourcing that supports predictive maintenance capabilities over lowest-unit-cost procurement.
Pricing Analysis
Network availability metrics exceeding 99.999 percent anchor value-based pricing for utility sector deployments, with Danish and Swedish transmission operators compensating vendors on uptime performance rather than capital expenditure. Price differentiation rests on EU AI Act conformity assessment depth and machine-learning model explainability certification, with German and French regulatory tiers commanding premium positioning. Cost compression in commodity hardware tiers is intensifying due to semiconductor supply constraints, while telecom operators in Germany and the United Kingdom exhibit highest price sensitivity due to 5G rollout capex pressures.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke logistics for specialized AI accelerators and network processing units. Manufacturing concentrates in Taiwan, South Korea, and Germany for advanced semiconductors and precision optical components. Raw material dependencies include silicon wafers, rare earth elements for magnetics, and high-purity copper for fiber interconnects. Single-source vulnerability around EUV lithography equipment creates structural risk exposure. Distribution runs through authorized value-added resellers with certified integration capabilities for multi-vendor environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors capable of documenting algorithmic decision logic for EU AI Act conformity assessment, with compliance documentation burdens forcing mid-tier system integrators toward acquisition or exit.
For Market Incumbents:Lock in long-term outcome-based contracts with Scandinavian utility consortia before competitor certification cycles complete. Acquire machine-learning engineering teams in Poland and Romania where talent costs lag Western European levels. Prioritize backward integration into predictive analytics software to defend margin position against intent-based networking specialists.
For New Entrants and Emerging Players:Begin with consulting and documentation services for EU AI Act conformity assessment, where twelve-month backlogs in Munich and Paris create immediate revenue visibility. Polish and Romanian smart grid modernization offers the most penetrable geography given accelerating EU cohesion fund allocations. Position around legacy protocol bridging expertise, as brownfield telecom and utility environments resist seamless open-standard integration.
For Investors and Strategic Acquirers:Re-rating potential sits with vertically integrated mid-cap specialists combining algorithmic development with established conformity assessment body relationships, given CE marking timeline compression as the catalyst. Long-term viability favors vendors with recurring revenue exposure under outcome-based infrastructure contracts rather than equipment-centric models. Monitor backlog durations at Paris and Munich conformity assessment bodies as the signal for competitive access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment Partnership | CE marking timeline compression secures market access ahead of competitors in Germany and France. |
| Intent-Based Networking Platform Launch | Deutsche Telekom and BT Group pilot deployments validate machine-executable policy translation capabilities. |
| Smart Grid Modernization Joint Venture | Polish and Romanian distribution operators leverage EU cohesion fund allocations for network resilience. |
| Predictive Analytics Talent Acquisition | Machine-learning engineering scarcity in Scandinavia drives competitive positioning for utility contracts. |
| Digital Twin Integration Partnership | Danish and Swedish transmission operators combine real-time simulation with autonomous remediation. |
Research Methodology
Regulatory filings from the European Telecommunications Standards Institute, EU AI Act implementation guidance, and national cybersecurity directives formed the secondary backbone for market sizing and compliance pathway mapping. Primary interviews with network operations executives at major telecom operators, smart grid program directors at Scandinavian utilities, and system integration specialists across Germany and France validated deployment timelines and procurement criteria. SEC filings and EU public procurement databases provided vendor revenue attribution. Bottom-up and top-down triangulation reconciled segment-level technology adoption with aggregate infrastructure investment flows.
Bottom-up modeling built from individual operator deployment announcements and utility modernization program budgets, while top-down analysis cross-checked against aggregate European telecom and utility capex surveys. Segmentation dimensions included technology layer, application vertical, end-user archetype, and service delivery model, with geographic regulatory clusters treated as distinct adoption curves. CAGRs were derived from logistic diffusion curves fitted to historical automation deployment patterns, with 5G standalone rollout schedules and EU Green Deal implementation timelines as primary demand inputs.
Underlying measurement precision varies by segment; telecommunications operator expenditure carries tighter precision than emerging utility company adoption where procurement cycles remain elongated. Forecasts reflect documented assumptions around regulatory enforcement timing and semiconductor supply normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Private LTE Market
Network Technology
Virtual Router Market
Network Technology
CPE Router Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Global Intelligent Network Market
Network Technology
Radio Modem Market
Network Technology
Mobile Accelerator Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Open RAN Market
Network Technology
Router and Switch Market
Network Technology
Network Devices Market
Network Technology
Low-Power WAN Market
Network Technology
Global Home Networking Device Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Global Active Network Management Market
Network Technology
Managed MPLS Market