
 Global 5G Smart Antenna Market | 2026-2036
Global 5G Smart Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Global 5G Smart Antenna Market Foresight
3GPP Release 17 certification is redrawing competitive boundaries for millimeter-wave suppliers. Qualcomm Technologies leverages its modem-to-antenna design integration to sustain R&D intensity across sub-6 GHz and mmWave portfolios. Huawei Technologies Co. Ltd. anchors manufacturing scale through captive semiconductor fabrication and dominates baseband-to-radiated-element vertical control. Samsung Electronics Co. Ltd. competes aggressively in vRAN-integrated massive MIMO, particularly where open RAN interfaces create substitution opportunities against incumbent radio vendors.
5G smart antennas are active electronically steered arrays that dynamically shape radiation patterns through phase-controlled element networks, typically operating across 600 MHz to 71 GHz with beamwidth precision under one degree for tracking mobile users. These systems serve the primary commercial purpose of spectral efficiency multiplication in dense cellular environments where passive antennas cannot resolve interference-limited capacity constraints. Massive MIMO antenna configurations lead infrastructure deployments by unit volume, while beamforming antenna architectures command margin concentration due to digital front-end complexity and calibration IP. Adaptive antenna segments show structural acceleration in private network deployments where enterprises require interference-nulling capabilities for coexistence with unlicensed spectrum operations.
FCC Part 30 rules in the United States, ETSI EN 302 567 in Europe, and MIIT 5G license conditions in China collectively shape product certification timelines, spectrum band availability, and power-density limits that determine which antenna architectures achieve commercial scale. The EU AI Act and emerging network equipment security frameworks under CSRD reporting obligations add compliance layers for vendors supplying European telecom operators. Stakeholders must monitor whether 3GPP Release 18 specifications for AI-native air interfaces trigger hardware redesign cycles that obsolete current digital beamforming ASIC investments before depreciation schedules complete.
Market Dynamics
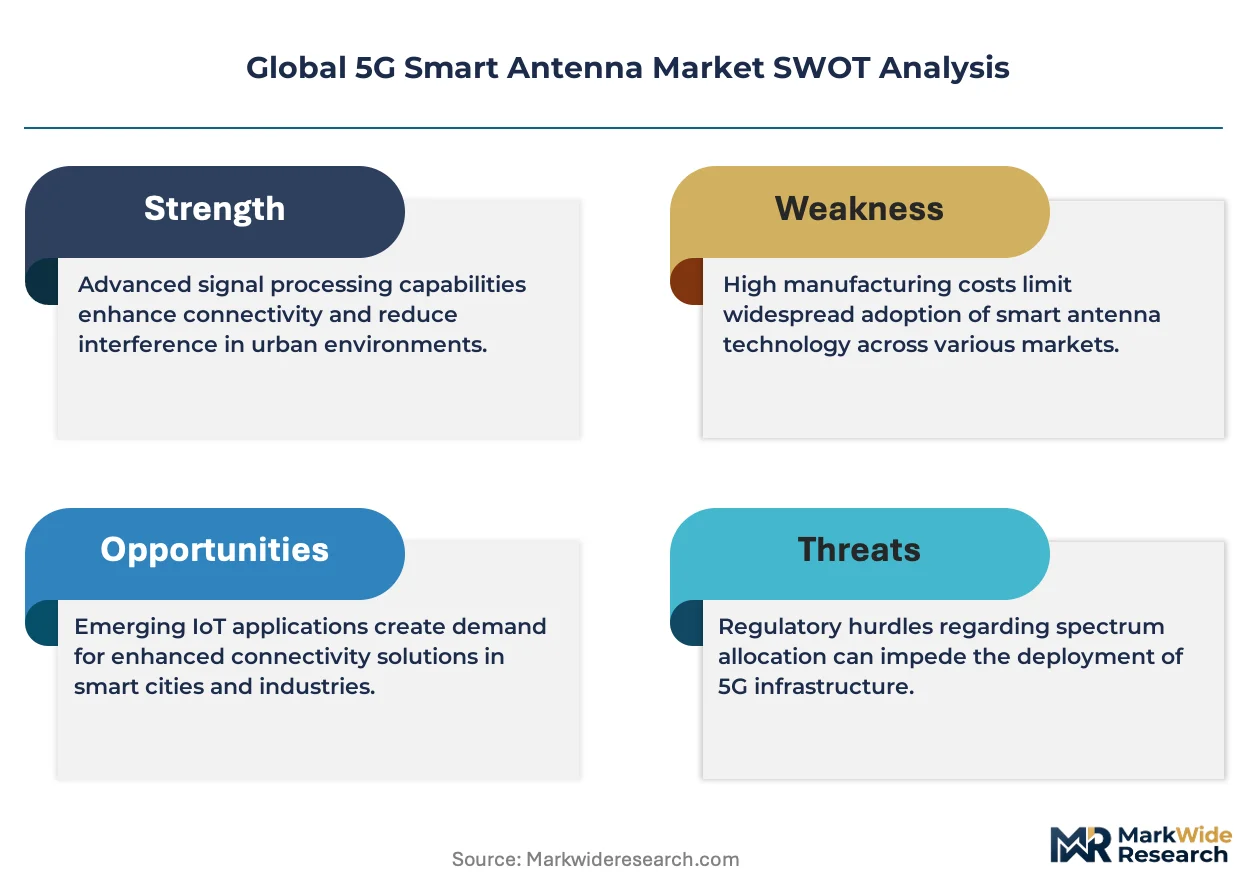
The 5G smart antenna market is being restructured by the transition from hybrid analog-digital beamforming to fully digital architectures, which demands new semiconductor supply chains and recalibrates vendor competitive advantage around ASIC design capabilities.
Growth Catalysts
- MIIT 5G-Advanced spectrum allocation:China's accelerated licensing of 6 GHz and millimeter-wave bands is forcing infrastructure refresh cycles and expanding addressable unit demand for 64T64R massive MIMO configurations.
- Private industrial networks:Manufacturing campuses in Germany and South Korea are deploying adaptive antenna systems for deterministic latency, creating a parallel demand channel outside traditional mobile network operator procurement.
- Beamforming algorithm maturation:Real-time channel state information processing at the edge is reducing handover latency below 10 milliseconds, enabling mobility use cases previously blocked by link stability constraints.
Market Restraints
- Gallium nitride substrate scarcity:RF power amplifier foundry capacity in Taiwan and Japan is fully committed through 2027, constraining output expansion for high-efficiency antenna-integrated radio units.
- FCC Part 30 power-density limits:Millimeter-wave small cell deployments in dense US urban corridors face site-by-site environmental review, extending permitting timelines and compressing deployment velocity.
- Passive antenna residual competitiveness:Rural coverage scenarios with low subscriber density sustain demand for simpler sector antennas, limiting the addressable premium for active beamforming solutions.
Strategic Opportunities
- India DOT 5G spectrum harmonization:The country's 2024 mid-band auction completion and subsequent network buildout create a multi-year equipment procurement window for sub-6 GHz massive MIMO suppliers.
- Open RAN interface standardization:O-RAN Alliance 7.2x split specifications are enabling disaggregated antenna-radio combinations, allowing specialist antenna vendors to bypass incumbent integrated system suppliers.
- Terrestrial-satellite integration:3GPP NTN specifications for non-terrestrial networks are driving hybrid antenna designs that combine cellular and LEO satellite connectivity for maritime and aviation applications.
Industry Challenges
- Electromagnetic compatibility certification:Multi-band antenna systems must satisfy ETSI EN 302 567, FCC Part 27, and MIIT radio approval processes simultaneously, multiplying test matrix complexity and time-to-revenue.
- Legacy 4G infrastructure coexistence:Dynamic spectrum sharing implementations require antenna systems to maintain backward-compatible radiation patterns while optimizing 5G capacity, constraining design freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 5G Smart Antenna Market |
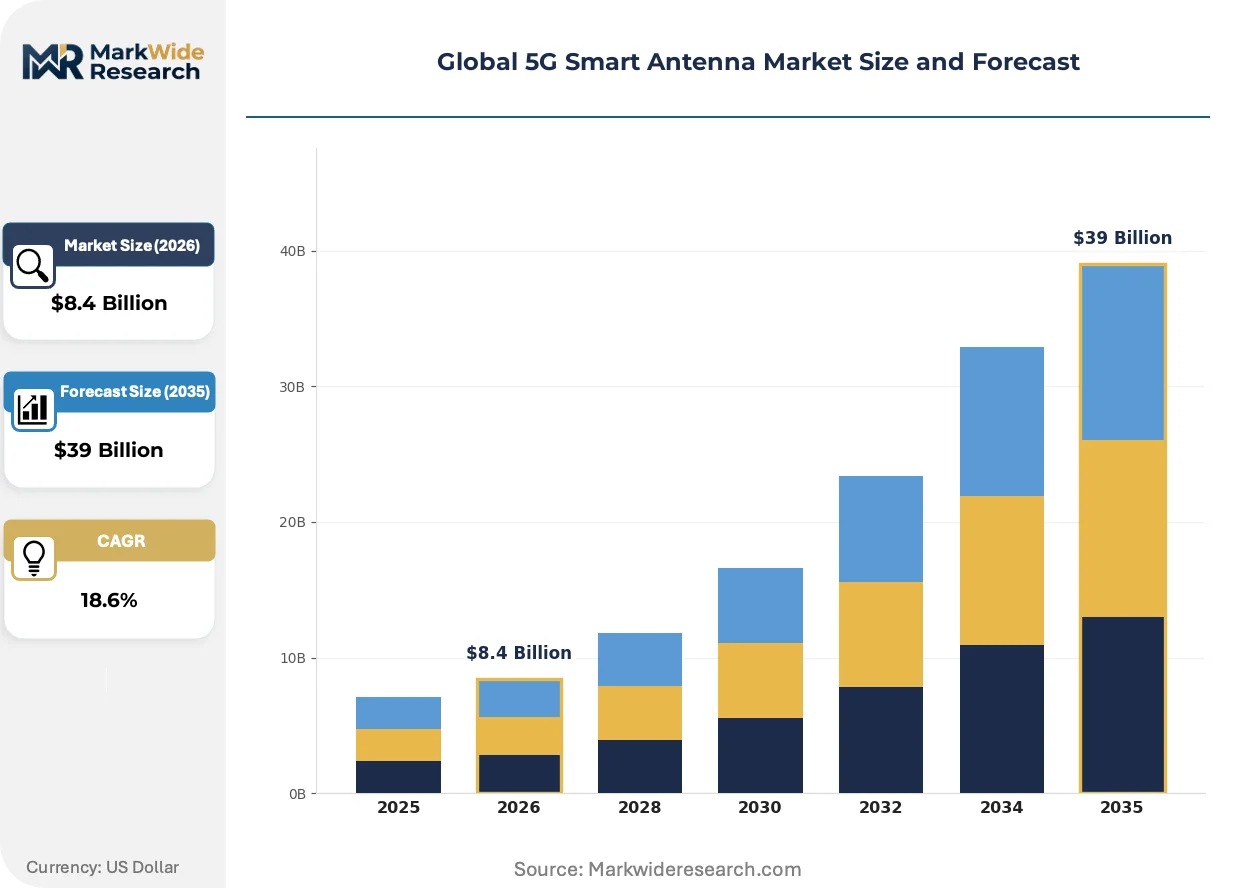
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phased Array Antenna, Massive MIMO Antenna, Adaptive Antenna, Beamforming Antenna Technology: Time Division Duplex, Frequency Division Duplex, Spatial Division Duplex, Hybrid Duplex Application: Smart Cities, Industrial Automation, Autonomous Vehicles, Fixed Wireless Access, Public Safety End User: Telecom Operators, Network Equipment Providers, Enterprises, Government Agencies |
| Companies Covered | Huawei Technologies Co. Ltd., Qualcomm Technologies, Inc., Samsung Electronics Co. Ltd., Nokia Corporation, Ericsson, Broadcom Inc., ZTE Corporation, Mitsubishi Electric Corporation, Keysight Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 5G Smart Antenna Market Shifts & Advancements
Antenna architecture is fragmenting into modular subsystems as digital front-end processing migrates toward the radiating edge, compressing traditional hardware value chains and enabling new specialist entrants.
Integrated antenna-filter combinations are decomposing the conventional discrete component supply chain for base station radio heads. Tier-one infrastructure vendors in South Korea and Finland are qualifying these consolidated modules for 3.5 GHz massive MIMO deployments. The technology is decomposing procurement relationships that previously separated antenna, filter, and radio suppliers into distinct vendor tiers.
ETSI's expanded cybersecurity certification framework for network equipment is mandating secure boot and firmware attestation in antenna-integrated radios sold to European operators. This regulatory layer is extending product development cycles by eight to fourteen months for vendors without existing Common Criteria evaluations. German and French operators are now requiring CSRD-aligned supply chain disclosure from antenna suppliers, favoring vendors with captive semiconductor fabrication.
Enterprise buyers are consolidating antenna procurement under systems integrators rather than contracting directly with radio vendors. Industrial automation deployers in Japan's Aichi manufacturing corridor and Germany's Ruhr industrial cluster are sourcing pre-integrated private network packages where antenna performance is specified but sub-vendor selection is opaque. This channel shift is most pronounced in mining and port automation verticals where end-to-end latency guarantees override component-level brand preferences.
Global 5G Smart Antenna Market Segmentation
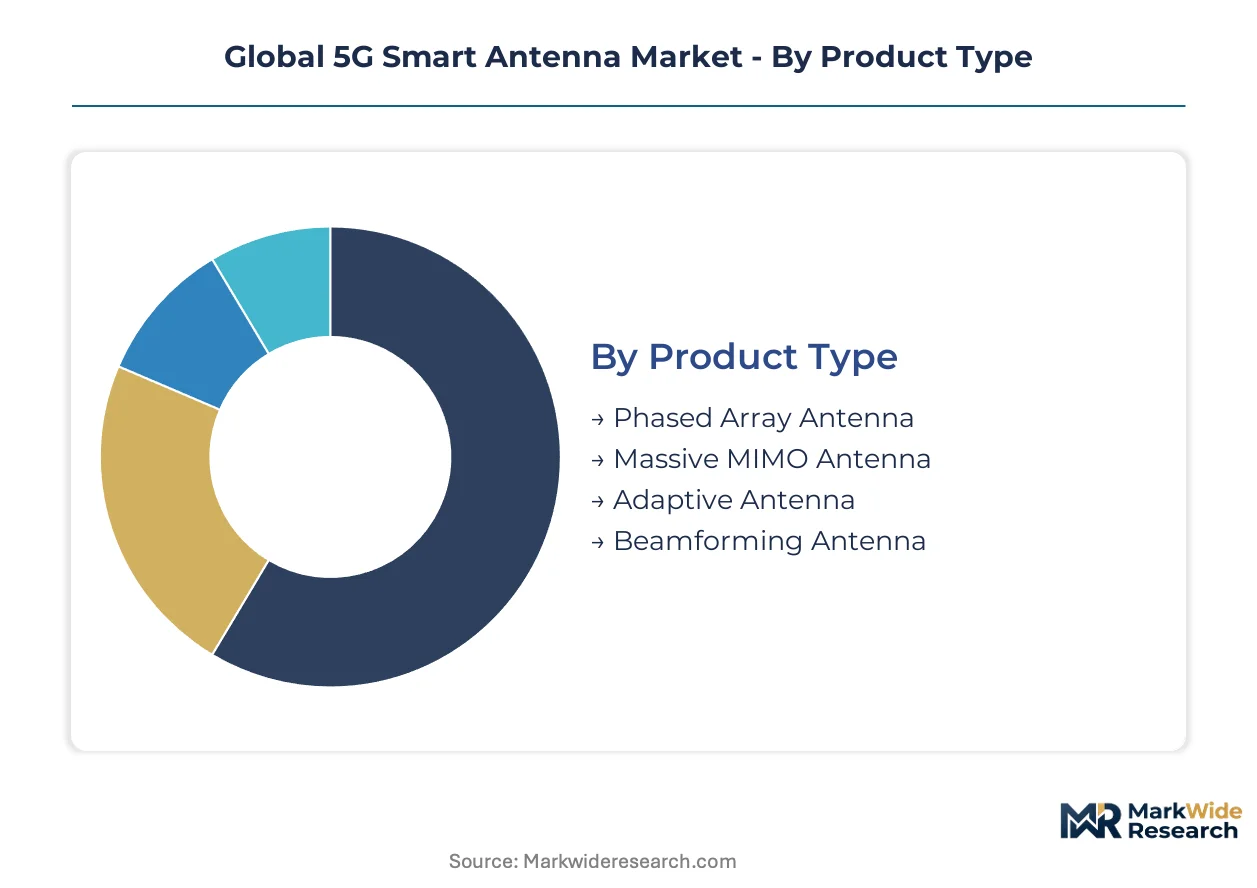
Antenna architecture choices determine spectral efficiency gains and infrastructure economics across deployment scenarios. Product type and technology selections cascade into application suitability and procurement channel dynamics, creating distinct margin profiles that reshape vendor positioning.
Product Type:
Margin concentration pools in configurations with digital front-end complexity and calibration intellectual property, while unit volume leadership sits with infrastructure-scale deployments.
- Massive MIMO Antenna:Active electronically steered arrays with 64 or more radiating elements enable spatial multiplexing gains through independent beam steering per user. South Korean telecom operators in Seoul and Busan are densifying urban corridors with 64T64R configurations to resolve interference-limited capacity constraints. The dominant share belongs to Massive MIMO Antenna, while Beamforming Antenna is closing the gap fastest.
- Beamforming Antenna:Digital and hybrid analog-digital architectures dynamically shape radiation patterns through phase-controlled element networks, typically achieving beamwidth precision under one degree. China's manufacturing corridors in Guangdong and Jiangsu provinces are scaling production for domestic 5G-Advanced networks, with MIIT spectrum allocations forcing infrastructure refresh cycles.
- Phased Array Antenna:Solid-state implementations with gallium nitride power amplifiers serve millimeter-wave small cell deployments where FCC Part 30 power-density limits apply.
- Adaptive Antenna:Real-time interference-nulling capabilities support private network deployments in Germany's Ruhr industrial cluster and Japan's Aichi manufacturing corridor.
Massive MIMO Antenna commands infrastructure procurement volumes, while Beamforming Antenna captures premium positioning through ASIC design differentiation.
Technology:
Cost tier stratification separates legacy implementations from next-generation architectures requiring new semiconductor supply chains.
- Time Division Duplex:Unpaired spectrum operation enables flexible uplink-downlink ratio configuration for asymmetric traffic patterns in China's sub-6 GHz deployments. MIIT licensing frameworks favor TDD for mid-band allocations, concentrating manufacturing scale among domestic equipment providers in Shenzhen and Beijing.
- Frequency Division Duplex:Paired spectrum with simultaneous transmit-receive operation dominates US and European millimeter-wave rollouts where FCC Part 30 and ETSI EN 302 567 specifications apply. Rural coverage scenarios in the United States sustain demand for FDD implementations where subscriber density does not justify massive MIMO complexity.
- Hybrid Duplex:Combined TDD-FDD architectures support dynamic spectrum sharing implementations requiring backward-compatible radiation patterns.
- Spatial Division Duplex:Experimental multi-user MIMO extensions enable simultaneous same-frequency transmission through spatial separation algorithms.
TDD implementations lead unit shipments in Asia-Pacific manufacturing corridors, while FDD maintains defensive positions in North American and European spectrum allocations.
Application:
Customer type concentration varies sharply across use cases, with enterprise direct procurement emerging fastest in industrial verticals.
- Smart Cities:Dense urban sensor networks and video analytics backhaul drive pole-mounted small cell deployments in Seoul, Singapore, and Barcelona. Municipal procurement cycles favor integrated antenna-radio units with simplified installation protocols.
- Industrial Automation:Deterministic latency requirements in Germany's automotive manufacturing plants and South Korea's semiconductor fabrication facilities are accelerating adaptive antenna adoption outside traditional mobile network operator channels. Enterprise buyers in Japan's Aichi prefecture are consolidating procurement under systems integrators rather than contracting directly with radio vendors.
- Fixed Wireless Access:Residential broadband substitution in US rural markets and Indian peri-urban corridors leverages beamforming precision to overcome non-line-of-sight propagation challenges.
- Autonomous Vehicles:V2X communication requirements in Michigan's testing corridors and Bavaria's automotive R&D clusters demand low-latency handover capabilities below 10 milliseconds.
- Public Safety:Mission-critical network hardening in France's Sécurité Civile deployments and US FirstNet infrastructure prioritizes electromagnetic compatibility certification under multi-jurisdiction test matrices.
Smart Cities anchor current infrastructure spending, while Industrial Automation is gaining share fastest through private network procurement channels.
End User:
Procurement authority fragmentation creates channel complexity, with enterprise buyers increasingly specifying performance while delegating sub-vendor selection.
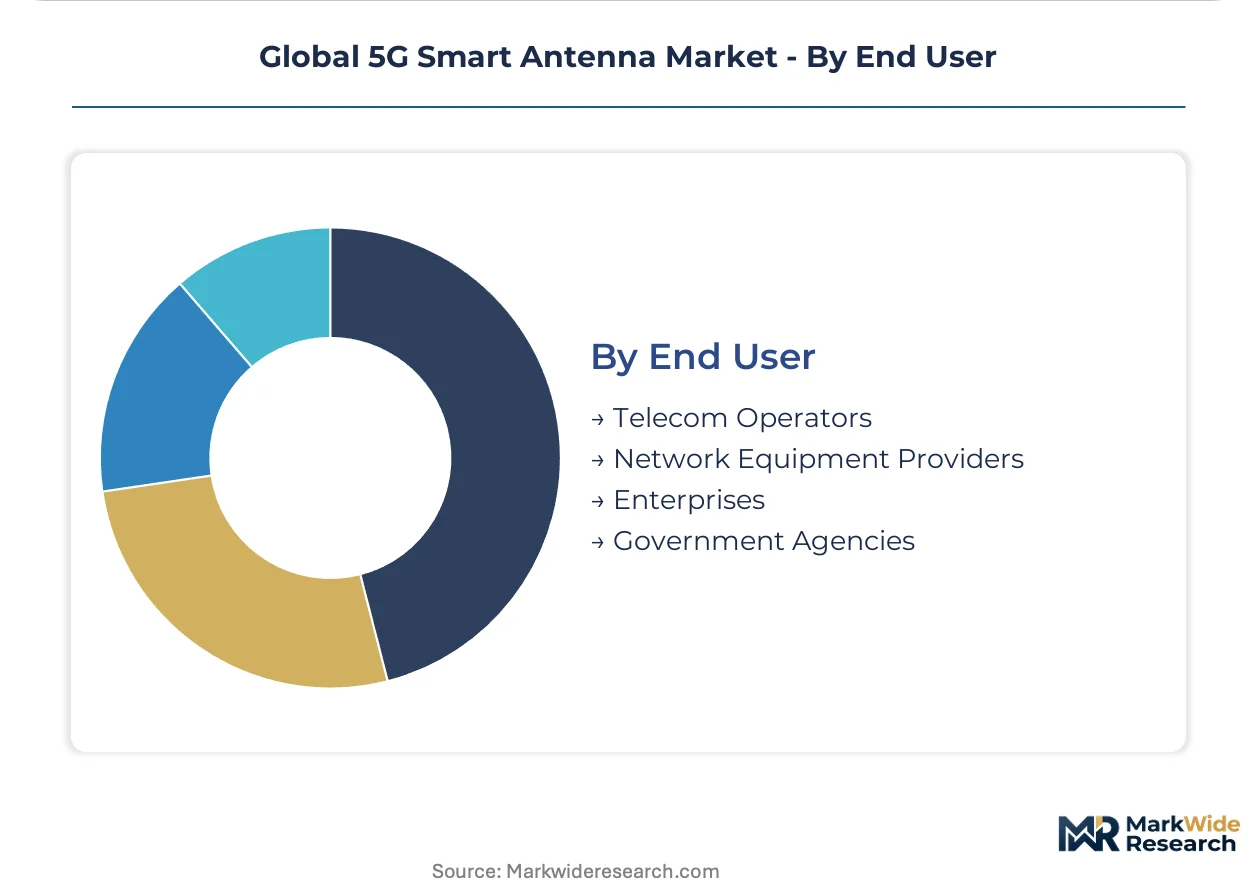
- Telecom Operators:Verizon, Deutsche Telekom, and Reliance Jio drive volume procurement through centralized radio access network modernization programs. O-RAN Alliance 7.2x split specifications are enabling disaggregated antenna-radio combinations that bypass incumbent integrated system suppliers.
- Enterprises:Mining operators in Western Australia's Pilbara region and port automation deployers in Rotterdam are sourcing pre-integrated private network packages where antenna performance is specified but component-level brand preferences are overridden by end-to-end latency guarantees.
- Network Equipment Providers:Specialist antenna vendors are qualifying integrated antenna-filter modules for 3.5 GHz massive MIMO deployments, decomposing traditional procurement relationships that previously separated antenna, filter, and radio suppliers.
- Government Agencies:Defense and public safety procurement in the United States, France, and Japan mandates secure boot and firmware attestation under ETSI cybersecurity certification frameworks, extending product development cycles by eight to fourteen months for vendors without existing Common Criteria evaluations.
Telecom Operators retain volume leadership in open market procurement, while Enterprises are expanding addressable demand fastest through vertical-specific network deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom operators anchor procurement volumes in East Asian manufacturing corridors, while industrial automation deployers in Western Europe and North America are fragmenting demand through private network channels. Equipment vendors calibrate product roadmaps against three distinct regulatory frameworks: MIIT spectrum auctions in China, FCC Part 30 power-density rules in the United States, and ETSI cybersecurity certification in Europe. Urban densification projects in Seoul, Singapore, and Barcelona concentrate pole-mounted small cell deployments for smart city backhaul.
China
MIIT's accelerated 5G-Advanced licensing of 6 GHz and millimeter-wave bands is forcing infrastructure refresh cycles across Guangdong and Jiangsu provinces. Domestic equipment providers in Shenzhen and Beijing scale 64T64R massive MIMO production for captive supply to state-owned telecom operators. The Yangtze River Delta manufacturing cluster dominates beamforming antenna output for sub-6 GHz networks.
South Korea
SK Telecom and KT Corporation are densifying Seoul and Busan urban corridors with 64T64R configurations to resolve interference-limited capacity constraints. The Korea Communications Commission's spectrum allocation framework prioritizes mid-band TDD implementations for manufacturing campuses in Gyeonggi Province. Samsung Electronics anchors vRAN-integrated massive MIMO supply from its Suwon R&D complex.
United States
Verizon and T-Mobile are expanding millimeter-wave infrastructure rollouts under FCC Part 30 rules, though site-by-site environmental review extends permitting timelines in dense urban corridors. Fixed wireless access deployers leverage beamforming precision for residential broadband substitution in rural markets. Michigan's automotive testing corridors demand sub-10 millisecond handover capabilities for V2X communication networks.
Germany
Deutsche Telekom and Vodafone Germany are procuring adaptive antenna systems for deterministic latency in Ruhr industrial cluster automation plants. The EU AI Act and CSRD reporting obligations extend product development cycles by eight to fourteen months for vendors without Common Criteria evaluations. ETSI EN 302 567 specifications shape certification timelines for millimeter-wave small cell deployments.
India
Reliance Jio and Bharti Airtel are executing multi-year equipment procurement windows following DOT's 2024 mid-band auction completion. Sub-6 GHz massive MIMO suppliers qualify integrated antenna-filter modules for peri-urban fixed wireless access corridors. Manufacturing scale concentrates in Karnataka and Tamil Nadu electronics clusters serving domestic network buildout demand.
Global 5G Smart Antenna Market Competitive Landscape
Player mix skews toward integrated infrastructure vendors with captive semiconductor fabrication and modem-to-antenna design integration capabilities. Market structure concentrates around three strategic archetypes: Asian conglomerates with vertical control over baseband-to-radiated-element supply chains, North American semiconductor specialists with ASIC design differentiation, and European telecom equipment vendors with open RAN interface expertise. Competitive moves center on O-RAN Alliance 7.2x split specification compliance and integrated antenna-filter module qualification for 3.5 GHz massive MIMO deployments.
Among Asian integrated system suppliers, Huawei Technologies Co. Ltd. and Samsung Electronics Co. Ltd. exemplify the captive fabrication archetype, while Qualcomm Technologies, Inc. occupies a position representing North American modem-to-antenna design integration specialists. These three anchors illustrate how vendor competitive advantage recalibrates around ASIC design capabilities as architectures shift from hybrid analog-digital beamforming to fully digital implementations. Specialist antenna vendors leveraging O-RAN disaggregation represent an emerging challenger tier bypassing incumbent integrated suppliers.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| Qualcomm Technologies, Inc. |
| Samsung Electronics Co. Ltd. |
| Nokia Corporation |
| Ericsson |
| Broadcom Inc. |
| ZTE Corporation |
| Mitsubishi Electric Corporation |
| Keysight Technologies |
| Others |
Supply & Pricing Matrix
Ninety-day gallium nitride substrate lead times from Taiwan and Japan foundries compress procurement flexibility for antenna-integrated radio units, concentrating pricing power with RF power amplifier suppliers and forcing equipment vendors into cost-plus contracts with gallium nitride price indexation.
Pricing Analysis
Cost-plus contracts with gallium nitride price indexation dominate procurement between antenna vendors and foundry partners, with pricing stratifying across 64T64R massive MIMO, 32T32R mid-tier, and 16T16R economy configurations based on digital front-end ASIC complexity and calibration IP intensity. Certification grade under ETSI cybersecurity frameworks and FCC Part 30 compliance tiers create additional price differentiation. Cost compression in millimeter-wave small cell tiers is intensifying because gallium nitride substrate scarcity limits output expansion. Enterprise buyers in private network deployments show lowest price sensitivity, prioritizing deterministic latency guarantees over unit economics.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam and Busan-Los Angeles trade lanes elevate inbound logistics costs for antenna-filter module shipments to European and North American assembly facilities. Manufacturing scale concentrates in China, South Korea, and Taiwan, with the Yangtze River Delta and Gyeonggi Province anchoring beamforming antenna production. Supply chains draw from gallium nitride substrates, silicon-based digital beamforming ASICs, and precision calibration equipment. Single-source vulnerability in Taiwan RF power amplifier foundries represents the dominant structural risk. Distribution runs through telecom operator centralized procurement programs and systems integrator channels for enterprise verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors with captive semiconductor fabrication and modem-to-antenna design integration capabilities, while specialist entrants face ASIC design capability gaps that constrain competitive positioning.
For Market Incumbents: Secure gallium nitride foundry capacity through multi-year offtake agreements with Taiwan and Japan suppliers to defend against substrate scarcity-driven margin erosion. Deepen backward integration into digital beamforming ASIC design to sustain R&D intensity across sub-6 GHz and millimeter-wave portfolios as 3GPP Release 18 specifications approach. For New Entrants and Emerging Players: O-RAN Alliance 7.2x split specification compliance gaps in vRAN-integrated massive MIMO deployments offer entry points where incumbent radio vendors face disaggregation pressure. Target India's multi-year equipment procurement window following DOT spectrum harmonization, positioning integrated antenna-filter modules for Reliance Jio and Bharti Airtel sub-6 GHz buildouts through qualification partnerships with network equipment providers. For Investors and Strategic Acquirers: Long-term, this sits as a semiconductor-specialist consolidation play because beamforming algorithm maturation and AI-native air interface specifications will obsolete current digital front-end investments before depreciation schedules complete. Acquisition targets should demonstrate O-RAN disaggregation expertise or captive gallium nitride supply arrangements. The signal to watch is 3GPP Release 18 hardware redesign cycle announcements triggering stranded asset risk in hybrid analog-digital beamforming portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Design Capability Acquisition | Secures digital beamforming IP as architectures shift from hybrid to fully digital implementations. |
| Gallium Nitride Foundry Partnership | Locks in RF power amplifier supply from Taiwan and Japan through 2027 capacity constraints. |
| O-RAN 7.2x Split Certification | Enables disaggregated antenna-radio combinations bypassing incumbent integrated system suppliers. |
| Integrated Antenna-Filter Module Qualification | Decomposes traditional procurement relationships separating antenna, filter, and radio suppliers. |
| ETSI Cybersecurity Certification Investment | Accelerates European market access by meeting Deutsche Telekom and Vodafone Germany secure boot requirements. |
Research Methodology
A standing panel of RAN engineering directors, telecom procurement executives, semiconductor foundry account managers, and private network systems integrators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against 3GPP specification documents, FCC spectrum auction records, MIIT license condition filings, and ETSI certification databases. Bottom-up antenna shipment modeling and top-down infrastructure spending analysis triangulated market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including antenna architecture type, duplex technology implementation, application vertical, and end-user procurement channel. CAGRs were derived from year-over-year growth rate progression analysis. Industry-specific forecast inputs incorporated MIIT 5G-Advanced spectrum allocation timelines and O-RAN Alliance specification release schedules.
Forecasts assume regulatory continuity in FCC Part 30, ETSI EN 302 567, and MIIT licensing regimes; material policy shifts in power-density limits or cybersecurity certification timelines would require re-modeling. Specific risk factors include gallium nitride substrate supply disruptions, 3GPP specification delays, and trade restriction escalation affecting semiconductor equipment access. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global GPS Market
Network Technology
Passive Optical Network Market
Network Technology
Wi-Fi Extender Market
Network Technology
MENA Wireless Routers Market
Network Technology
Optical Network Equipment Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
Global Network Probe Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
Data Center Switches Market
Network Technology
CPE Router Market
Network Technology
Global Self-Organizing Network Market
Network Technology
Low-Power WAN Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Network Performance Monitoring Market