
 IT Connector Market | 2026-2036
IT Connector Market Size, Share, and Industry Trends Forecast 2026-2036
IT Connector Market Foresight
The EU Green Deal is decoupling connector procurement from legacy plating chemistries across European data center builds. TE Connectivity leverages its European manufacturing footprint to sustain compliance-advantaged product lines. Amphenol Corporation anchors North American supply through vertical integration into precision stamping and plating operations. Molex competes on high-density interconnect portfolios for hyperscale server architectures.
An IT connector is an electromechanical component engineered to establish removable interfaces between electronic subsystems, typically specified by contact pitch, insertion force, impedance tolerance, and cycle durability. These components enable signal integrity, power delivery, and protocol translation across computing, telecommunications, and industrial control equipment. Fiber optic connectors command premium positioning as cloud infrastructure scales bandwidth beyond copper limitations. USB and HDMI connectors occupy mature, high-volume segments where margin compression favors manufacturing scale over innovation differentiation.
FCC equipment authorization rules govern electromagnetic emissions from connector assemblies sold into US telecommunications infrastructure. ECHA REACH restrictions and EU RoHS substance bans shape material selection for contacts, housings, and platings across European supply chains. China's MIIT issues GB standards for information technology equipment interoperability, affecting import qualification protocols. Stakeholders must monitor regulatory divergence between jurisdictions as connector platforms globalize and regional compliance thresholds tighten.
Market Dynamics
Copper-to-optical transitions in data center interconnects are forcing connector manufacturers to requalify entire product portfolios for 800G and 1.6T signaling speeds. This material shift is compressing legacy backplane connector demand while amplifying fiber optic assembly requirements across hyperscale server deployments.
Growth Catalysts
- EU RoHS substance restrictions:The directive's hazardous substance bans are accelerating material substitutions toward lead-free platings and halogen-free substrates, creating upgrade cycles across European enterprise infrastructure.
- Hyperscale server architectures:Cloud operators are specifying high-density interconnect portfolios that prioritize signal integrity over cost, pulling advanced connector technologies into mass deployment.
- China's domestic cloud buildouts:MIIT's GB standards for information technology equipment are driving massive procurement volumes for high-speed backplane and fiber optic connectors within state-backed data center expansions.
Market Restraints
- Precious metal input volatility:Palladium and gold price swings for contact platings directly compress gross margins on high-reliability connector lines serving telecommunications infrastructure.
- Optical component supply concentration:Laser diode and photodetector sourcing clusters in East Asian foundries create single-point vulnerability for fiber optic connector assembly lines.
- Copper bandwidth ceiling:Signal attenuation beyond 112 Gbps PAM4 signaling limits copper backplane reach, forcing premature architectural obsolescence in legacy data center designs.
Strategic Opportunities
- Edge computing micro-data centers:Distributed AI inference nodes in Germany and France require ruggedized connector systems rated for extended temperature and vibration tolerance outside traditional facilities.
- CPO (Co-Packaged Optics) integration:The convergence of silicon photonics with switch ASIC packaging is opening connector design partnerships directly with semiconductor foundries rather than through traditional OEM channels.
- EU Green Deal procurement mandates:Public sector data center construction in the Netherlands and Sweden now specifies circular economy criteria for connector recyclability and carbon footprint disclosure.
Industry Challenges
- Signal integrity engineering scarcity:The specialized electromagnetic simulation expertise required for 224 Gbps channel design concentrates within a handful of engineering teams across the industry.
- Multi-jurisdiction certification timelines:Simultaneous FCC equipment authorization, CE marking, and MIIT GB compliance testing extends product launch windows by 8-14 months for globally distributed platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Connector Market |
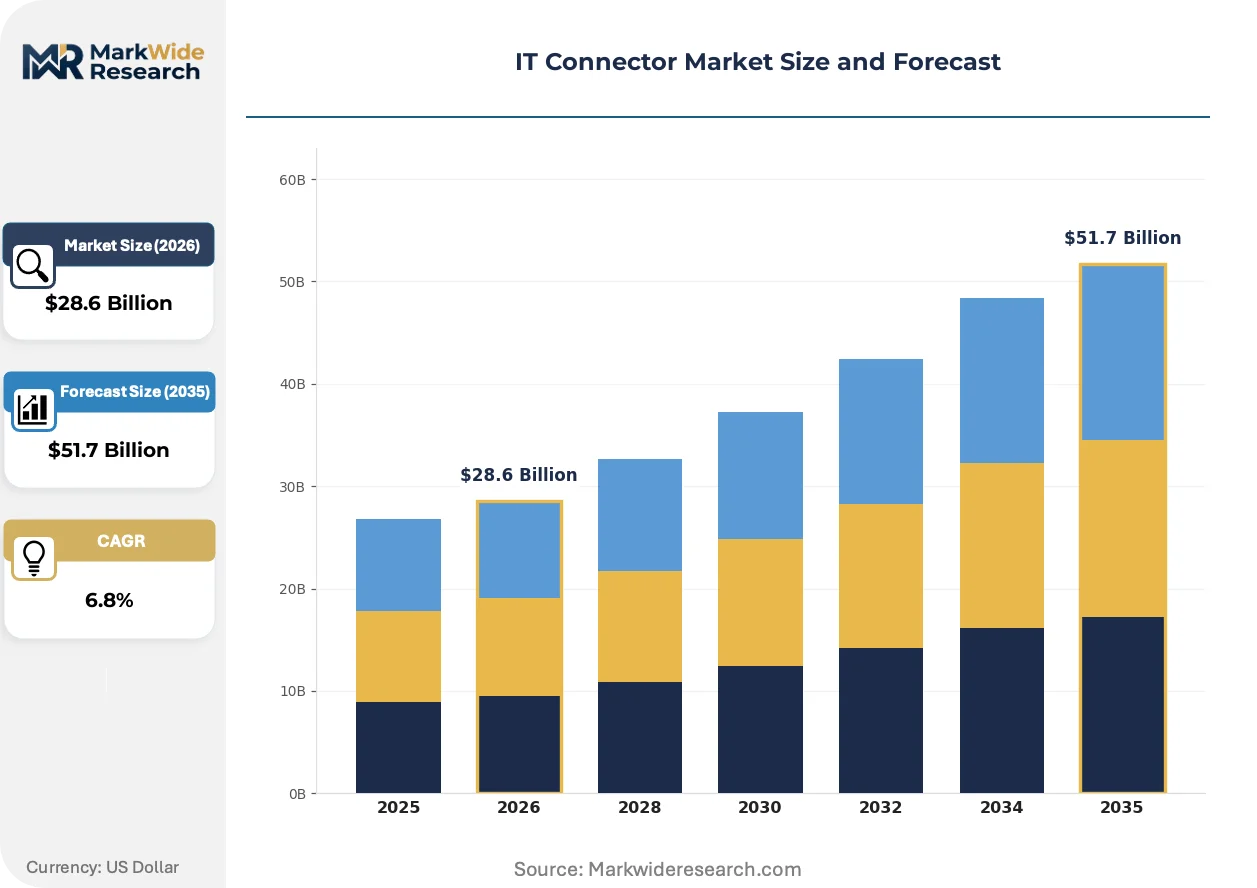
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Connectors, HDMI Connectors, Ethernet Connectors, Fiber Optic Connectors Application: Data Transmission, Power Supply, Multimedia, Networking Deployment: On-Premises, Cloud-Based, Hybrid, Remote End User: Enterprises, SMEs, Educational Institutions, Government |
| Companies Covered | TE Connectivity, Amphenol Corporation, Molex, Hirose Electric, Aptiv, 3M Company, Samtec, Japan Aviation Electronics Industry, Foxconn Interconnect Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Connector Market Shifts & Advancements
Active optical cable assemblies are compressing the traditional discrete connector market by integrating transceiver functionality directly into cable endpoints. This integration trend is redrawing competitive boundaries between connector specialists and optical component suppliers.
Silicon photonics-based optical engines are electrifying data center interconnect economics by collapsing the cost and power penalties historically separating electrical and optical signaling. Hyperscale operators in the United States are deploying these engines at rack-scale densities exceeding 50,000 ports per facility. The technology is electrifying supplier selection criteria, favoring partners with co-design capabilities across optical, mechanical, and thermal domains rather than discrete component vendors.
ECHA REACH restrictions on Substances of Very High Concern are tightening disclosure requirements for connector contact platings and housing polymers sold into European telecommunications infrastructure. Manufacturers must now document full material composition down to 0.1% weight concentration for authorization compliance. German automotive and industrial connector divisions are absorbing these compliance costs fastest, leveraging existing chemical management systems from adjacent product lines.
Consolidated procurement frameworks among the largest cloud operators are compressing supplier counts and unbundling traditional distribution relationships. Direct material qualification programs now bypass tier-one distributors for high-volume backplane and optical interconnect categories. This concentration is most visible in the United States, where three hyperscale buyers account for the majority of 400G and above port deployments, dictating connector roadmap priorities through joint development agreements rather than market-driven product cycles.
IT Connector Market Segmentation
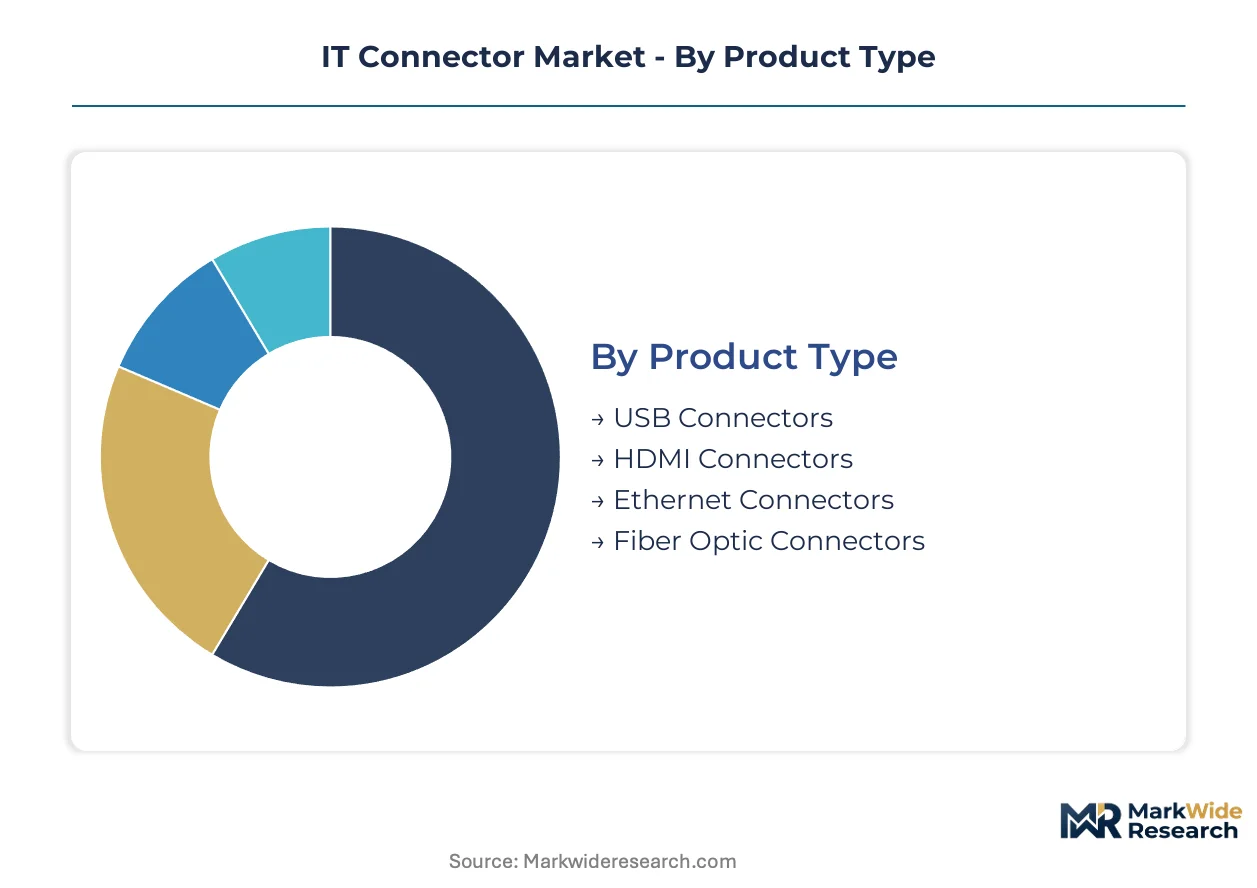
IT connector procurement patterns diverge sharply across deployment environments and signal requirements. Hyperscale operators prioritize fiber optic density while enterprise refresh cycles sustain copper interconnect volumes. Material specifications and regulatory compliance thresholds further fragment supplier selection criteria across end-use categories.
Product Type:
Contact pitch, insertion force ratings, and impedance tolerance specifications define competitive positioning within each connector family. Signal integrity requirements at 800G and above are compressing legacy copper portfolios while amplifying optical assembly demand.
- Fiber Optic Connectors:These assemblies employ precision ferrule alignment and polished end-face geometries to minimize insertion loss across single-mode and multimode fiber deployments. Cloud infrastructure buildouts in the United States and China are absorbing massive volumes as bandwidth requirements exceed copper physical limits. MIIT GB standards and FCC equipment authorization rules impose divergent qualification protocols on suppliers.
- Ethernet Connectors:RJ45 and modular jack configurations dominate enterprise networking with standardized 8P8C contact arrangements rated for 10/100/1000 Mbps through 10GBase-T signaling. Data center operators in Germany and the Netherlands specify shielded variants for electromagnetic compatibility under EU EMC Directive requirements.
- USB Connectors:Type-C reversible interfaces with 24-pin contact arrays support USB4 and Thunderbolt protocols up to 40 Gbps transmission rates.
- HDMI Connectors:19-pin high-definition multimedia interface assemblies serve consumer electronics and commercial display installations with HDCP content protection handshake requirements.
Fiber optic connectors lead on scale; USB connectors lead on momentum across consumer and peripheral attachment applications.
Application:
Functional requirements determine contact plating specifications, housing materials, and cycle durability ratings. Power delivery applications demand higher current-carrying capacity and thermal management compared to signal-only interconnects.
- Data Transmission:High-speed differential pair configurations with controlled impedance maintain signal integrity across backplane and cable assembly applications. Hyperscale server deployments in Virginia and Oregon specify these interconnects for 112 Gbps PAM4 and 224 Gbps signaling lanes.
- Networking:Shielded twisted-pair and fiber optic terminations enable switch-to-switch and switch-to-server connectivity across enterprise and telecommunications infrastructure. ECHA REACH disclosure requirements for contact platings shape material selection for European telecommunications deployments.
- Power Supply:High-current contact designs with enhanced thermal dissipation support server rack power distribution and external adapter connections.
- Multimedia:Consumer-facing interfaces prioritize ergonomic insertion force and cycle durability over signal performance specifications.
Data transmission commands the largest procurement volumes; networking applications are expanding most quickly as edge computing architectures proliferate.
Deployment:
Environmental exposure and accessibility constraints determine ruggedization requirements and service life specifications. Remote and edge installations demand wider operating temperature ranges than climate-controlled facilities.
- Cloud-Based:Hyperscale data center deployments concentrate demand for high-density, hot-swappable interconnect systems with 5,000+ cycle durability ratings. Operators in Iowa and North Carolina specify these for 50,000+ port facility densities.
- On-Premises:Enterprise-owned infrastructure sustains demand for modular, field-replaceable connector systems with standardized tool-less installation. German automotive and industrial facilities favor IP67-sealed variants for production floor environments.
- Hybrid:Mixed cloud-private architectures require interoperable connector platforms spanning colocation facilities and corporate data centers.
- Remote:Distributed micro-data centers and edge nodes specify extended temperature range components rated for -40°C to +85°C operation.
Cloud-based deployment anchors volume concentration; remote deployment is gaining share fastest as AI inference pushes compute toward network edges.
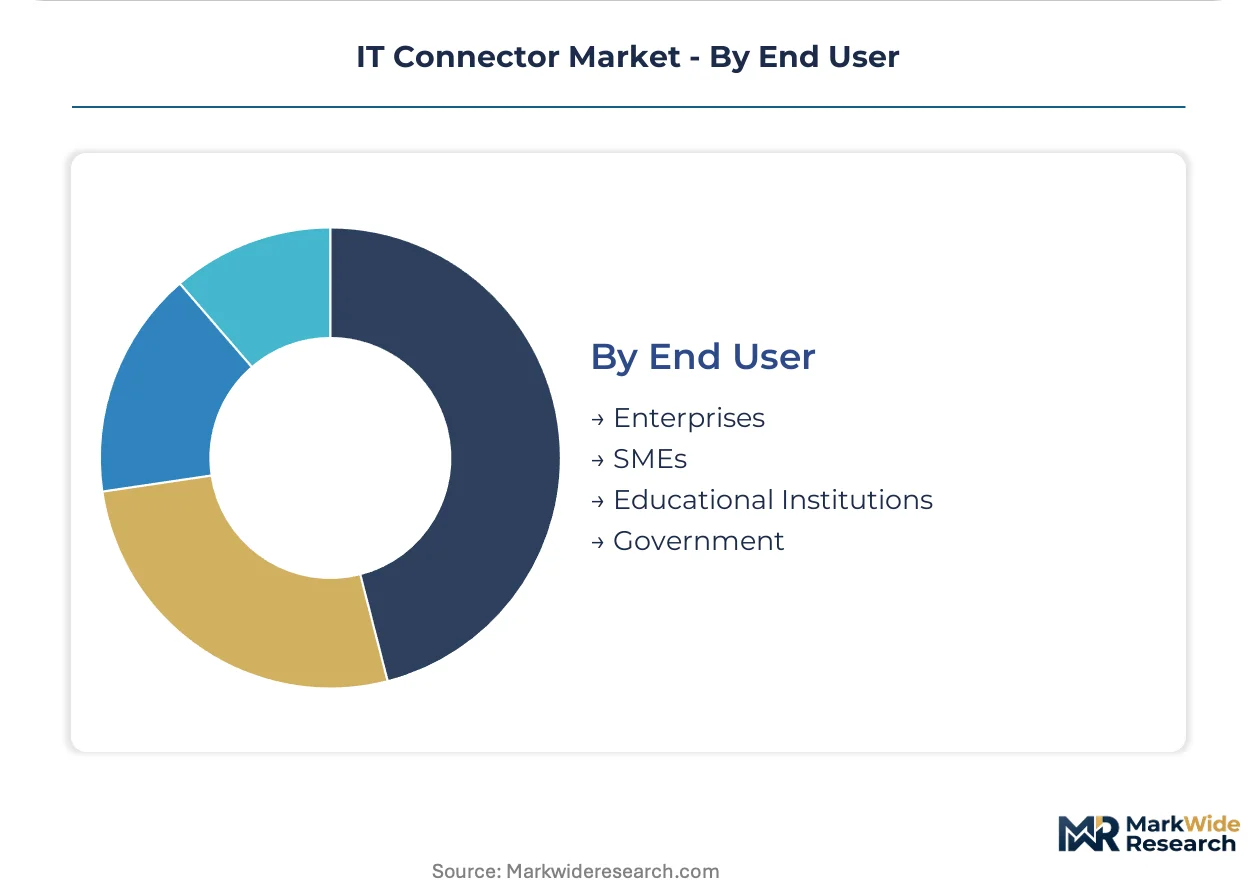
End User:
Procurement sophistication and qualification rigor vary substantially across organizational scale and sector. Government and educational buyers operate under distinct compliance and budgetary frameworks compared to commercial enterprises.
- Enterprises:Large organizations operate direct material qualification programs bypassing distribution for high-volume backplane and optical interconnect categories. Fortune 500 technology firms in California and Washington state dictate roadmap priorities through joint development agreements.
- Government:Public sector data center construction operates under circular economy procurement mandates in the Netherlands and Sweden, requiring carbon footprint disclosure and recyclability documentation for connector assemblies.
- SMEs:Mid-market organizations rely on distributor stocking programs and standardized product configurations with shorter lead times.
- Educational Institutions:University and research facility procurement emphasizes cost optimization over performance specifications for general computing infrastructure.
Enterprises dominate absolute spending; government segments show the steepest compliance-driven specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electromagnetic simulation engineers and precision plating technicians concentrate in Germany, the United States, and Japan, anchoring high-speed connector design capabilities. These talent clusters determine where next-generation interconnect architectures take shape. Regional regulatory divergence around substance restrictions and equipment authorization timelines fragments supplier qualification pathways.
United States
Hyperscale data center buildouts in Virginia and Oregon absorb massive volumes of fiber optic and high-density backplane connectors. FCC equipment authorization rules govern electromagnetic emissions from connector assemblies sold into telecommunications infrastructure. The Pacific Northwest corridor hosts engineering teams specializing in 224 Gbps signal integrity simulation for next-generation server architectures.
Germany
Automotive and industrial automation sectors sustain demand for ruggedized connector systems with extended temperature ratings. ECHA REACH restrictions on Substances of Very High Concern mandate full material composition disclosure down to 0.1% weight concentration for European telecommunications deployments. Bavaria's manufacturing belt integrates chemical management systems from adjacent automotive product lines to absorb compliance costs fastest.
China
State-backed cloud infrastructure expansions drive procurement volumes for high-speed backplane and fiber optic connectors under MIIT GB standards. Domestic foundries cluster laser diode and photodetector sourcing for fiber optic connector assemblies. The Yangtze River Delta anchors optical component supply concentration that creates single-point vulnerability for assembly lines.
Japan
Precision ferrule alignment and polished end-face geometries for single-mode fiber deployments originate from established optoelectronics manufacturing bases. METI industrial standards shape information technology equipment interoperability requirements affecting import qualification protocols. The Kanto region maintains captive production of high-reliability contact platings for telecommunications infrastructure.
Netherlands
Public sector data center construction now specifies circular economy criteria for connector recyclability and carbon footprint disclosure under EU Green Deal procurement mandates. Edge computing micro-data centers in distributed AI inference nodes require ruggedized systems rated for extended temperature tolerance. The Randstad logistics hub facilitates just-in-time delivery of halogen-free substrate materials across European supply chains.
IT Connector Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the IT connector landscape, with integrated manufacturers maintaining captive stamping and plating operations while specialized firms outsource precision machining. The market structure concentrates around three to five dominant suppliers capable of joint development agreements with hyperscale operators. Two strategic archetypes define competitive positioning: vertically integrated precision manufacturers controlling upstream material conversion, and technology licensors partnering with semiconductor foundries on co-packaged optics integration. Capacity expansion and strategic partnerships represent the dominant competitive moves, as qualification timelines for 800G and 1.6T signaling speeds extend product launch windows.
Among diversified industrial technology conglomerates, TE Connectivity and 3M Company exemplify the integrated manufacturing archetype with European and North American production footprints. Amphenol Corporation occupies a position representing North American supply anchoring through in-house control over precision stamping operations. These three entities sit within the tier capable of sustaining direct material qualification programs that bypass traditional distribution channels for high-volume backplane and optical interconnect categories.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Molex |
| Hirose Electric |
| Aptiv |
| 3M Company |
| Samtec |
| Japan Aviation Electronics Industry |
| Foxconn Interconnect Technology |
| Others |
Supply & Pricing Matrix
Hyperscale procurement consolidation across Virginia and Oregon data center corridors is forcing connector suppliers to absorb precious metal volatility while maintaining 800G signal integrity guarantees, compressing margins on high-reliability copper-to-optical transitions.
Pricing Analysis
Bundled active optical cable assemblies command premium positioning against discrete connector components as transceiver integration collapses traditional procurement categories. Three-tier pricing structure across premium, standard, and economy levels separates CPO-integrated silicon photonics partnerships from modular field-replaceable systems and commodity copper backplane variants. Price differentiation hinges on certification tier—FCC equipment authorization and ECHA REACH compliance add 15-25% cost premiums—and volume scale, with direct material qualification programs extracting steepest discounts. Pricing pressure stems from consolidated procurement frameworks among three dominant cloud operators dictating roadmap priorities through joint development agreements. SMEs and educational institutions exhibit highest price sensitivity, while government buyers under EU Green Deal mandates prioritize circular economy criteria over unit cost.
Supply Chain Analysis
China's MIIT domestic-content requirements for state-backed cloud infrastructure are reshaping sourcing patterns, compelling foreign suppliers to localize assembly operations or surrender procurement eligibility. Manufacturing gravity centers on China for laser diode and photodetector foundries, Japan for precision ferrule alignment and polished end-face geometries, and Germany for ECHA REACH-compliant plating chemistries. Raw material dependencies include palladium and gold for contact platings, halogen-free substrate polymers, and single-mode fiber cores. Single-source vulnerability concentrates in Yangtze River Delta optical component clusters. Distribution runs through direct material qualification programs that bypass tier-one distributors for high-volume backplane and optical interconnect categories, with residual volume flowing through specialized electronics distributors serving SME and industrial automation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where hyperscale operators now specify signal integrity over cost, pulling advanced connector technologies into mass deployment and rewarding suppliers with co-design capabilities across optical, mechanical, and thermal domains.
For Market Incumbents: Hedge against silicon photonics displacement by deepening partnerships with semiconductor foundries on CPO integration rather than defending discrete connector market share. Prioritize captive plating operations to buffer palladium and gold price volatility threatening gross margins on telecommunications infrastructure lines. Accelerate ECHA REACH-compliant product line expansion to capture EU Green Deal procurement mandates specifying circular economy criteria for connector recyclability. For New Entrants and Emerging Players: Launch via specialized distribution partnerships targeting German automotive and industrial automation sectors requiring IP67-sealed ruggedized systems with extended temperature ratings. Penetrate edge computing micro-data center deployments in France and Netherlands where distributed AI inference nodes demand -40°C to +85°C rated components outside incumbent hyperscale supply relationships. Differentiate through electromagnetic simulation expertise for 224 Gbps channel design, the scarcest capability concentration across the industry. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale connector designers possessing silicon photonics co-packaging capabilities but lacking hyperscale qualification relationships. Long-term viability favors entities controlling upstream precision stamping and captive plating operations against commodity copper backplane obsolescence. Monitor qualification timeline compression for 1.6T signaling speeds as the inflection indicator separating roadmap leaders from laggards.| Strategic Initiative | Industry Significance |
|---|---|
| CPO Integration Partnership | Direct collaboration with TSMC and Intel Foundry Services redefines competitive boundaries beyond traditional OEM channels. |
| EU RoHS Compliance Acceleration | Lead-free plating and halogen-free substrate investments capture Green Deal procurement mandates in Netherlands and Sweden. |
| Edge Computing Product Line Expansion | Ruggedized -40°C to +85°C rated connectors address distributed AI inference nodes across German and French micro-data centers. |
| Direct Material Qualification Bypass | Elimination of tier-one distributor margins strengthens positioning with three dominant hyperscale buyers controlling 400G+ port deployments. |
| Signal Integrity Engineering Acquisition | Specialized electromagnetic simulation teams for 224 Gbps channel design concentrate competitive advantage in Virginia and Oregon engineering corridors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center procurement directors, connector platform engineers, telecommunications infrastructure planners, and precision plating operations managers with secondary validation against FCC equipment authorization filings, ECHA REACH substance restriction updates, MIIT GB standard releases, and hyperscaler capital expenditure disclosures. Bottom-up build-ups across product type, application, deployment, and end-user segments triangulated against top-down market sizing from trade flow analysis and industry association data.
Historical reference periods anchored the forecast window through backward extension of copper-to-optical transition timelines and hyperscale facility deployment cadences observed across the analysis window. The modeling framework segmented by connector family, signaling speed tier, deployment environment, and geographic regulatory cluster, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion schedules. Key inputs included palladium and gold price trajectory assumptions, 800G/1.6T port deployment forecasts from hyperscaler infrastructure disclosures, and EU RoHS substance restriction implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under acute precious metal price spikes or accelerated silicon photonics substitution curves. The analytical envelope holds within boundaries defined by multi-jurisdiction certification timeline extensions, single-source optical component supply disruptions, and hyperscale procurement consolidation dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
DNS DHCP and IPAM Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
Global Network Monitoring Market
Network Technology
Global Network Probe Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Carrier Routing Equipment Market
Network Technology
Optical Networking Market
Network Technology
Protocol Analyzer Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
ISP Management Systems Market
Network Technology
Global Network Switches Market
Network Technology
Global Internet Transit Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
Passive Optical Network Market
Network Technology
Structured Cabling Market
Network Technology
5G CPE Device Market