
 Protocol Analyzer Market | 2026-2036
Protocol Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Protocol Analyzer Market Analysis
FCC Open RAN interoperability mandates is consolidating compliance costs for new entrants while favoring incumbents with certified testing portfolios. Keysight Technologies leverages its calibration laboratory network to sustain turnkey validation contracts with tier-one carriers. VIAVI Solutions anchors its position through embedded software partnerships with semiconductor foundries. Rohde & Schwarz competes on毫米波 test coverage for emerging 6G research programs.
A protocol analyzer is an instrument or software system that captures, decodes, and analyzes digital communication traffic across physical and virtual network interfaces, typically supporting line rates from 1 Gbps to 800 Gbps with nanosecond timestamp resolution. Its primary commercial purpose is to verify protocol conformance, diagnose interoperability failures, and characterize latency distributions in production networks. Hardware-based portable systems dominate margin pools due to specialized FPGA-based triggering engines and premium pricing for field-deployable ruggedization. Cloud-based deployment represents the fastest-expanding segment as hyperscalers shift continuous monitoring to virtualized tap fabrics. Integrated solutions are maturing as vendors bundle protocol analysis with application performance management dashboards.
FCC equipment authorization rules and EU CE marking under the Radio Equipment Directive shape product certification timelines and geographic market access for analyzer manufacturers. ISO/IEC 17025 laboratory accreditation requirements from national metrology institutes constrain which vendors can issue traceable calibration certificates recognized by carrier procurement departments. NIST cybersecurity framework alignment is becoming a de facto filter for enterprise buyers evaluating protocol analyzer vendors. Stakeholders must monitor how Open RAN disaggregation creates demand for multi-vendor protocol validation workflows that span radio units, distributed units, and centralized units from different suppliers.
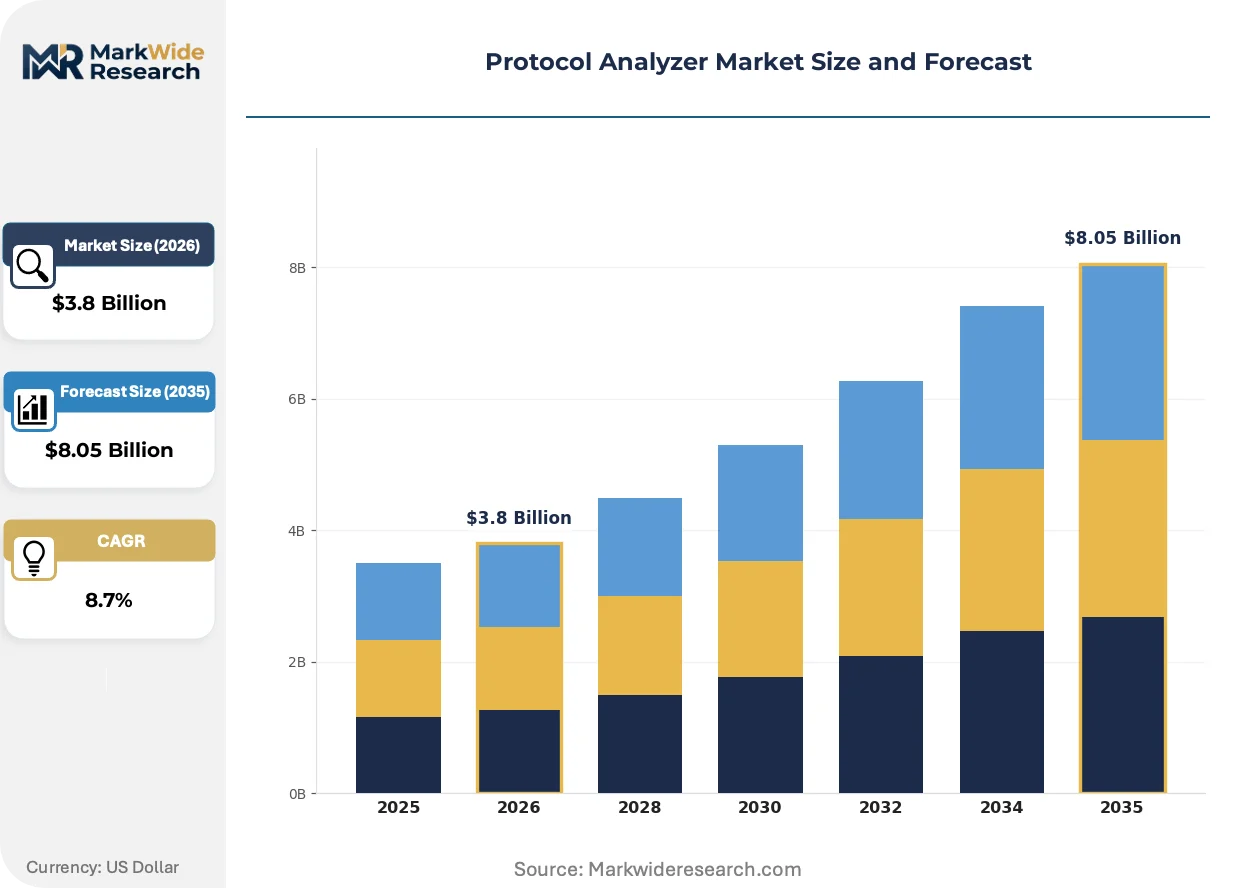
Market Dynamics
Network disaggregation under Open RAN architectures is fragmenting validation workflows across multi-vendor radio, distributed, and centralized units, forcing protocol analyzer vendors to engineer modular test suites that span heterogeneous hardware ecosystems rather than single-supplier environments.
Growth Catalysts
- FCC Open RAN interoperability mandates:US carriers must certify multi-vendor configurations, expanding protocol analyzer procurement for compliance validation across disaggregated network elements.
- Automotive Ethernet adoption:German OEMs deploy high-bandwidth in-vehicle networks for autonomous systems, creating dedicated demand for automotive-grade protocol analysis with nanosecond timing precision.
- 5G standalone rollout:Telecommunication operators in South Korea and Japan require continuous signaling verification as they migrate from non-standalone to core network architectures.
Market Restraints
- FPGA supply concentration:Specialized programmable logic for triggering engines sources from a concentrated foundry base in Taiwan, exposing hardware vendors to allocation risk.
- ISO/IEC 17025 accreditation barriers:National metrology institutes constrain which vendors can issue traceable calibration certificates recognized by carrier procurement departments.
- Software-defined radio substitution:Low-cost SDR platforms with open-source protocol stacks capture price-sensitive segments in academic and startup environments.
Strategic Opportunities
- Cloud-native virtualization:Hyperscalers in the United States shift continuous monitoring to virtualized tap fabrics, opening subscription revenue models for software-defined protocol analysis.
- 6G research programs:Millimeter-wave and sub-terahertz test requirements in Germany and Japan create premium hardware demand ahead of standardization.
- NIST cybersecurity framework alignment:Enterprise buyers filter vendor selection on security posture, rewarding early compliance investments with preferred supplier status.
Industry Challenges
- Multi-vendor integration complexity:Disaggregated Open RAN deployments require protocol analyzers to correlate timing across radio units, distributed units, and centralized units from different suppliers with divergent implementation quirks.
- Certification timeline compression:FCC equipment authorization and EU CE marking under the Radio Equipment Directive create sequential bottlenecks that delay product launches in parallel markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protocol Analyzer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Portable Systems, Integrated Solutions Application: Network Management, Security Analysis, Performance Monitoring, Protocol Testing End User: Telecommunication, IT, Automotive, Aerospace Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized |
| Companies Covered | Keysight Technologies, VIAVI Solutions, Anritsu Corporation, Teledyne LeCroy, Rohde & Schwarz, EXFO Inc., NetScout Systems, Tektronix, Spirent Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protocol Analyzer Market Emerging Trajectories
Artificial intelligence is embedding into protocol analysis workflows, compressing root-cause identification from hours to minutes and reshaping how engineering teams allocate diagnostic expertise across distributed network operations.
FPGA-based triggering engines with programmable state machines is unifying previously separate capture, decode, and analysis functions into single hardware platforms. Tier-one carriers in the United States and Germany are consolidating test bench footprints as these integrated systems replace discrete instruments. The structural consequence is margin compression for point-solution vendors while full-stack suppliers capture expanded validation contracts.
EU CE marking under the Radio Equipment Directive tightens electromagnetic compatibility and spectrum efficiency requirements for protocol analyzers operating in unlicensed bands. Manufacturers must redesign front-end architectures to meet harmonized standards before accessing European markets. Automotive OEMs in Germany are accelerating compliance investments to secure supply chain qualification for connected vehicle programs.
Buyer organizations are unbundling hardware procurement from calibration and maintenance services, treating test equipment as capital assets while outsourcing metrology traceability to accredited laboratory networks. Carrier procurement departments in Japan and South Korea now separate analyzer purchase orders from multi-year service agreements. This bifurcation pressures vendors to defend recurring revenue through software subscriptions rather than captive service contracts.
Protocol Analyzer Market Segmentation
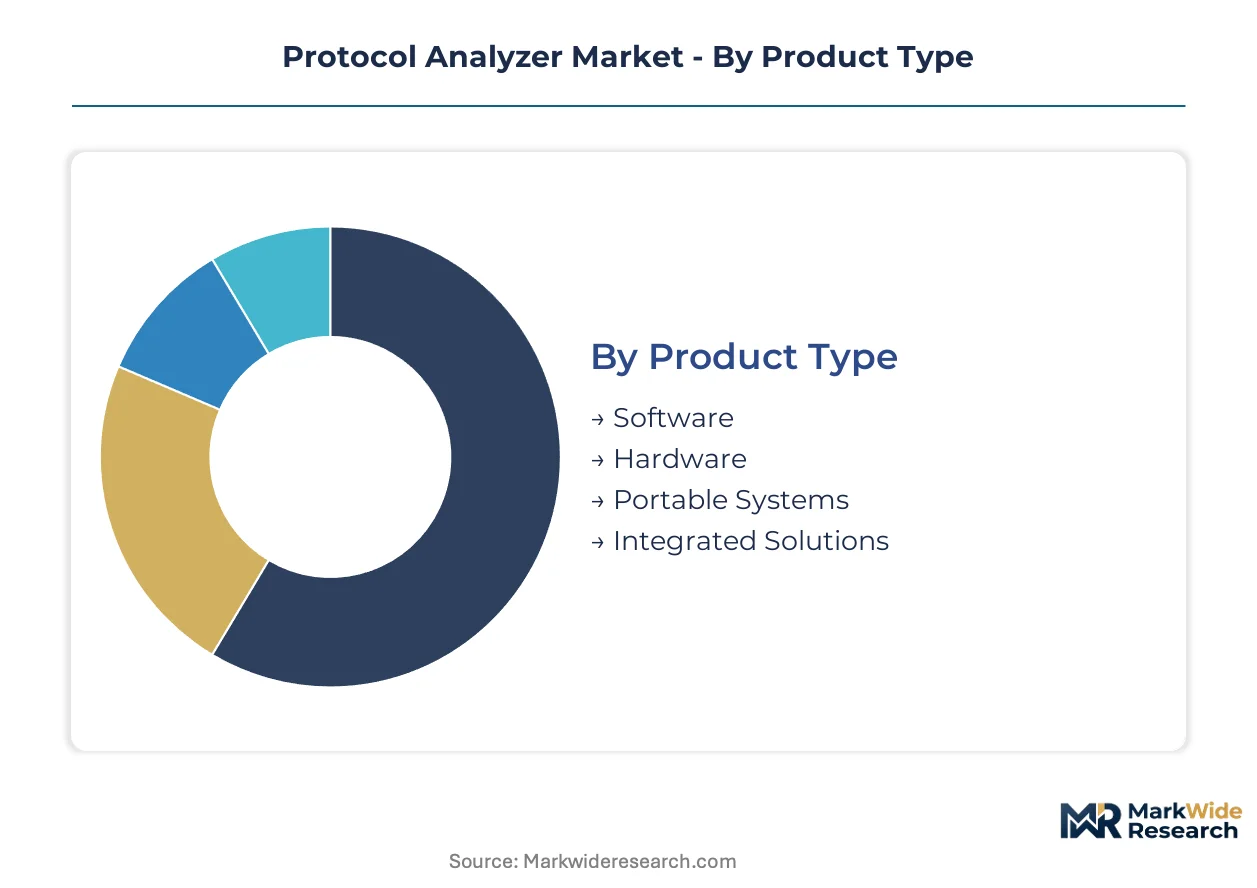
Protocol analyzer procurement patterns diverge sharply between capital-intensive hardware refresh cycles and recurring software subscriptions. Segmentation reveals how vendor portfolios must straddle legacy test bench consolidation alongside cloud-native virtualization demands.
Product Type:
Customization intensity varies from off-the-shelf software licenses to bespoke FPGA configurations engineered for specific carrier validation environments.
- Hardware:FPGA-based systems with programmable state machines unify capture, decode, and analysis functions. Demand concentrates with tier-one US carriers consolidating test bench footprints under Open RAN interoperability mandates. These systems command premium pricing for nanosecond timestamp resolution and ruggedized field deployment.
- Software:Protocol decoding engines deploy on standard compute infrastructure with subscription licensing models. German automotive OEMs and Japanese hyperscalers drive procurement for continuous integration pipelines and automated regression testing.
- Portable Systems:Battery-operated handheld units with integrated antennas serve field technicians diagnosing live network faults in South Korean 5G standalone rollouts.
- Integrated Solutions:Bundled hardware-software platforms with embedded application performance management dashboards target enterprise buyers seeking unified observability stacks.
Leading the category by volume: Hardware. Expanding most quickly: Software.
Application:
Cost tier stratification separates enterprise-grade continuous monitoring from project-based compliance validation engagements.
- Network Management:Real-time topology discovery and fault correlation across disaggregated radio, distributed, and centralized units. US telecommunication operators scale deployment for 5G core network migration, requiring multi-vendor protocol correlation capabilities.
- Security Analysis:Deep packet inspection with behavioral anomaly detection identifies lateral movement and protocol-level attacks. Financial services buyers in Japan filter vendor selection through NIST cybersecurity framework alignment requirements.
- Performance Monitoring:Latency distribution characterization and jitter analysis for quality-of-service verification in production environments.
- Protocol Testing:Conformance validation against 3GPP, IEEE, and IETF specifications for equipment authorization submissions to the FCC.
Dominant by procurement value: Network Management. Steepest expansion trajectory: Security Analysis.
End User:
Customer maturity determines whether buyers prioritize turnkey validation contracts or in-house engineering customization.
- Telecommunication:Carriers in the United States, South Korea, and Japan drive the largest hardware procurement volumes for RAN disaggregation compliance. FCC Open RAN mandates force multi-vendor certification workflows spanning radio units, distributed units, and centralized units.
- Automotive:German OEMs integrate Ethernet protocol analyzers for autonomous vehicle development, demanding automotive-grade timing precision and electromagnetic compatibility under EU CE marking requirements.
- IT:Enterprise data center operators and cloud service providers adopt virtualized tap fabrics for east-west traffic visibility.
- Aerospace:Satellite communications and avionics manufacturers require MIL-STD-810 ruggedization and extended temperature operation.
Telecommunication leads absolute spending. Automotive climbs fastest on connected vehicle program investments.
Deployment:
Supply concentration in Taiwan-based FPGA foundries shapes hardware availability, while software delivery escapes physical constraints entirely.
- Cloud-Based:Virtualized protocol analysis functions deployed on hyperscaler infrastructure enable elastic scaling for traffic spike events. US-based cloud operators shift continuous monitoring to software-defined tap fabrics, opening subscription revenue models.
- On-Premises:Dedicated appliance deployment in carrier central offices and enterprise data centers satisfies low-latency triggering requirements and data sovereignty constraints.
- Hybrid:Split architectures process high-volume capture locally while streaming metadata to cloud analytics engines for cross-site correlation.
- Virtualized:Containerized protocol analysis microservices integrate with Kubernetes orchestration for DevOps-aligned network operations.
On-Premises retains installed base dominance. Cloud-Based gains share fastest on hyperscaler virtualization investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Protocol analyzer procurement concentrates where 5G deployment, Open RAN mandates, and automotive Ethernet adoption intersect. Carriers in three countries drive hardware volumes, while semiconductor and automotive clusters in two others shape specialized demand.
United States
FCC Open RAN interoperability mandates force tier-one carriers to certify multi-vendor radio, distributed, and centralized unit configurations. The FCC's equipment authorization rules compress product launch timelines for analyzer vendors seeking market access. Silicon Valley hyperscalers and Austin-based cloud operators are shifting continuous monitoring to virtualized tap fabrics, opening subscription revenue models for software-defined protocol analysis.
Germany
Automotive OEMs in Stuttgart and Munich integrate Ethernet protocol analyzers for autonomous vehicle development programs requiring nanosecond timing precision. EU CE marking under the Radio Equipment Directive tightens electromagnetic compatibility requirements for test equipment accessing European markets. The country's national metrology institute enforces ISO/IEC 17025 accreditation constraints that determine which vendors can issue traceable calibration certificates recognized by carrier procurement departments.
Japan
Telecommunication operators in Tokyo and Osaka require continuous signaling verification as they migrate from non-standalone to 5G standalone core network architectures. METI research funding accelerates millimeter-wave test requirements for emerging 6G programs ahead of international standardization. Yokohama-based carrier procurement departments now separate analyzer purchase orders from multi-year calibration service agreements, pressuring vendors to defend recurring revenue through software subscriptions.
South Korea
5G standalone rollout drives demand for portable battery-operated handheld units serving field technicians diagnosing live network faults in Seoul and Busan. The country's national telecommunications regulator shapes equipment authorization timelines for analyzer manufacturers seeking market entry. Pangyo Techno Valley hosts concentrated R&D activity where domestic carriers validate disaggregated Open RAN deployments across multi-vendor hardware ecosystems.
China
Domestic equipment manufacturers scale protocol analyzer deployment for base station export certification required by destination market regulators. MIIT equipment approval processes create sequential bottlenecks that delay parallel product launches in Europe and North America. Shenzhen and Beijing semiconductor clusters drive demand for embedded software partnerships with foundries producing specialized FPGA-based triggering engines.
Protocol Analyzer Market Vendor Landscape
United States producers anchor the premium hardware tier; German and Japanese specialists hold positions in calibration-accredited and millimeter-wave test segments. The vendor base stratifies across three tiers: full-stack suppliers with turnkey validation contracts, point-solution vendors facing margin compression from integrated FPGA platforms, and emerging software-native entrants capturing cloud virtualization demand. Two dominant competitive moves are reshaping positioning: M&A activity consolidating test bench footprints under single-supplier relationships, and strategic partnerships embedding protocol analysis into semiconductor foundry design flows.
Within the full-stack supplier tier, Keysight Technologies, VIAVI Solutions, and Rohde & Schwarz represent distinct geographic and capability archetypes. Keysight Technologies, a Delaware corporation, exemplifies the calibration laboratory network model sustaining carrier relationships through traceable metrology services. VIAVI Solutions occupies a position bridging embedded software partnerships with semiconductor foundries and cloud-native virtualization roadmaps. Rohde & Schwarz, a German GmbH, anchors the millimeter-wave specialization vector targeting 6G research programs ahead of standardization timelines.
| Leading Market Players |
|---|
| Keysight Technologies |
| VIAVI Solutions |
| Anritsu Corporation |
| Teledyne LeCroy |
| Rohde & Schwarz |
| EXFO Inc. |
| NetScout Systems |
| Tektronix |
| Spirent Communications |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up test equipment specialists have consolidated fragmented calibration service networks, tightening pricing discipline through captive metrology traceability while locking in multi-year service agreements with tier-one carriers. This ownership structure reinforces supply-side concentration in Taiwan-based FPGA foundries, where specialized programmable logic for triggering engines commands allocation priority and extends hardware lead times.
Pricing Analysis
Short lead-time availability commands substantial premiums in hardware procurement, while spot inventory liquidation in software licenses attracts price-sensitive academic buyers. Three-tier pricing structure across premium, standard, and economy levels separates FPGA-based portable systems with nanosecond resolution from virtualized software subscriptions and entry-level SDR alternatives. Pricing pressure stems from software-defined radio substitution in price-sensitive segments, compressing margins at the economy tier. Academic and startup environments exhibit highest price sensitivity, whereas telecommunication operators prioritize certification-grade hardware regardless of cost.
Supply Chain Analysis
Workforce availability constraints in Taiwan, Germany, and the United States shape manufacturing capacity for precision test equipment assembly. Specialized FPGA-based triggering engines, high-speed ADC components, and ruggedized enclosure materials constitute critical input dependencies. Single-source vulnerability in Taiwan-based foundry concentration exposes hardware vendors to allocation disruption. Distribution runs through direct carrier procurement departments and accredited laboratory networks, with software delivery bypassing physical logistics entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FPGA foundry capacity constraints prop hardware pricing power, creating supply-constrained dynamics that favor vendors with secured wafer commitments and long-term foundry partnerships.
For Market Incumbents: Deepen embedded software partnerships with semiconductor foundries to secure preferential allocation of specialized programmable logic during supply crunches. Expand ISO/IEC 17025 accreditation coverage across calibration laboratory networks to defend against emerging software-native entrants threatening service revenue. Software-defined radio substitution and cloud-native virtualization represent parallel threats requiring dual-track response. For New Entrants and Emerging Players: Begin with cloud-native protocol analysis targeting hyperscaler virtualization demand in the United States, where subscription licensing models bypass capital expenditure barriers. Academic and startup environments offer most penetrable white-space due to price sensitivity and reduced certification requirements. Go-to-market through DevOps-aligned channel partnerships with Kubernetes orchestration platforms accelerates adoption. For Investors and Strategic Acquirers: Distressed-cycle entries favor calibration-accredited mid-caps in Germany and Japan, where national metrology institute relationships create durable competitive moats. Long-term viability hinges on 6G research program positioning and millimeter-wave test capability development ahead of standardization. Watch Open RAN deployment acceleration as inflection indicator for multi-vendor validation workflow demand.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | ISO/IEC 17025 accreditation from NIST-recognized institutes secures carrier procurement qualification. |
| Embedded Software Partnership | Semiconductor foundry integration locks in FPGA allocation priority for triggering engine supply. |
| Cloud-Native Virtualization Roadmap | Hyperscaler tap fabric deployment opens recurring subscription revenue beyond hardware cycles. |
| 6G Millimeter-Wave R&D Investment | METI-funded research programs in Japan create premium hardware demand ahead of standardization. |
| Open RAN Multi-Vendor Certification Suite | FCC interoperability mandates force tier-one carriers toward consolidated validation contracts. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with test equipment procurement managers at tier-one carriers, calibration laboratory directors, semiconductor foundry supply chain leads, and automotive OEM network validation engineers. FCC equipment authorization databases, EU CE marking registries, METI research funding disclosures, and carrier capital expenditure reports provided demand-side triangulation against bottom-up vendor shipment estimates.
Granularity-level modeling deployed product-type, application, end-user, and deployment-mode dimensions at country-level resolution across the projection horizon. CAGRs derived from S-curve adoption modeling for 5G standalone rollout and Open RAN disaggregation timelines, with FPGA supply concentration and ISO/IEC 17025 accreditation constraints as supply-side boundary conditions. Hyperscaler virtualization investments and automotive Ethernet adoption curves served as cross-referencing demand inputs.
FPGA allocation disruption, Open RAN mandate delay, and 6G standardization timeline slippage are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding foundry capacity expansion and carrier procurement cycle continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Enterprise Network Equipment Market
Network Technology
MENA Wireless Routers Market
Network Technology
Router and Switch Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Managed Switches Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Cloud Managed Access Points Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Network Equipment Market
Network Technology
Germany Residential Gateway Market
Network Technology
Global GPS Market
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Power Over Ethernet (Poe) Solutions Market
Network Technology
SP Routing and Ethernet Switching Market
Network Technology
Unified Network Management Market
Network Technology
Fiber to the Home (FTTH) Market