
 Network Performance Monitoring Market | 2026-2036
Network Performance Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Network Performance Monitoring Market Outlook
Software-defined feature licensing is decoupling network performance monitoring from perpetual hardware appliance sales. SolarWinds sustains broad channel penetration across mid-market IT departments with modular subscription tiers. LogicMonitor specializes in cloud-native infrastructure metrics, competing directly with hyperscaler-native tooling. Zabbix leverages open-source distribution to occupy cost-sensitive segments across European and Asian telecom providers.
Network performance monitoring encompasses the continuous measurement, analysis, and diagnostic evaluation of packet transmission rates, latency thresholds, jitter coefficients, and bandwidth utilization across routed and switched infrastructure. These systems detect path degradation, identify congestion bottlenecks, and trigger automated remediation workflows to preserve service-level agreements for mission-critical applications. Cloud-based solutions are capturing the fastest expansion as enterprises retire on-premises probe hardware in favor of elastic, API-driven telemetry ingestion. The services layer—spanning implementation, tuning, and managed observability—now carries the deepest margin pools as vendor technical specialization outpaces customer in-house expertise. Hardware retains residual demand within government and defense segments where air-gapped compliance requirements prevent cloud telemetry egress.
FCC net neutrality proceedings and NIST cybersecurity framework mandates shape how US-based enterprises architect passive versus active monitoring topologies, with encryption visibility requirements driving lawful intercept-compatible probe deployments. The EU AI Act and GDPR cross-border data governance rules constrain where European network metadata may be processed, fragmenting vendor cloud delivery architectures. Stakeholders must weigh sovereignty-compliant hosting against the latency penalties of region-locked telemetry pipelines as regulatory jurisdictions proliferate.
Market Dynamics
Zero-trust security mandates are forcing enterprises to abandon perimeter-based monitoring for continuous packet-level inspection across hybrid cloud environments, restructuring procurement priorities toward API-native telemetry platforms.
Growth Catalysts
- FCC Net Neutrality Proceedings:US financial services firms are accelerating deployment of real-time latency monitoring to safeguard high-frequency trading infrastructure against traffic prioritization uncertainties.
- Hyperscale Data Center Buildouts:Concentrated demand from Virginia, Texas, and Oregon cloud campuses is intensifying network observability requirements for east-west traffic visibility.
- NIST Cybersecurity Framework:Federal cloud migration directives mandate continuous monitoring compliance, pulling agencies toward passive probe architectures with lawful intercept capabilities.
Market Restraints
- Encryption Visibility Costs:TLS 1.3 and perfect forward secrecy protocols require expensive SSL decryption appliances at every network edge, inflating total cost of ownership for distributed enterprises.
- European Cloud Fragmentation:GDPR cross-border data governance rules constrain where network metadata may be processed, forcing vendors to maintain redundant regional infrastructure.
- Probe Hardware Residual Demand:Air-gapped government and defense segments resist cloud telemetry egress, locking vendors into low-margin perpetual appliance sales.
Strategic Opportunities
- EU AI Act Compliance Layer:Automated network anomaly detection systems face new algorithmic transparency requirements, creating demand for explainable AI monitoring modules in Frankfurt and Amsterdam data centers.
- 5G Network Slicing:Telecom operators in South Korea and Japan require granular per-slice performance metrics, opening specialized instrumentation contracts for radio access network monitoring.
- Managed Observability Services:Vendor technical specialization now outpaces customer in-house expertise, enabling recurring revenue streams through implementation, tuning, and 24/7 incident response.
Industry Challenges
- Legacy SNMP Migration Friction:Decades of accumulated MIB-based tooling resist replacement by streaming telemetry protocols, complicating hybrid monitoring architectures.
- Site Reliability Engineer Scarcity:Expertise in Prometheus, Grafana, and eBPF kernel instrumentation concentrates in San Francisco and Seattle labor markets, inflating compensation for distributed enterprise hiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Performance Monitoring Market |
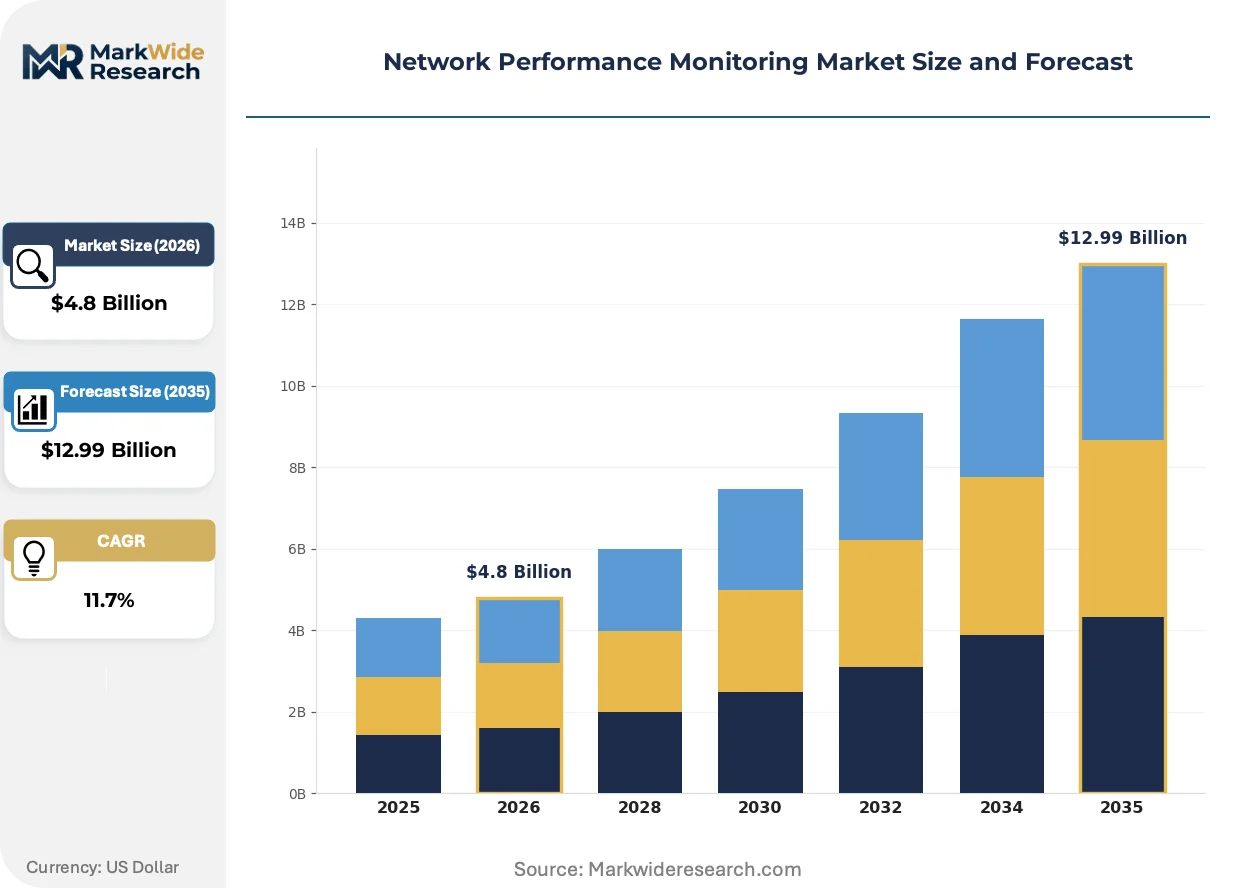
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Cloud-based Solutions Deployment Model: On-premises, Cloud, Hybrid, Managed Services End User: Enterprises, Telecom Providers, Data Centers, Government Application: Network Security, Traffic Analysis, Performance Optimization, Monitoring Tools |
| Companies Covered | Paessler PRTG, ManageEngine OpManager, SolarWinds, NinjaOne, Domotz, Auvik, Zabbix, Selector, LogicMonitor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Performance Monitoring Market Strategic Shifts
eBPF kernel instrumentation is collapsing the boundary between network and application performance visibility, enabling unified telemetry pipelines that merge packet capture with container runtime metrics.
Extended Berkeley Packet Filter technology is decentralizing monitoring agent deployment from dedicated appliance racks to every Linux host kernel. Cloud-native enterprises are standardizing on eBPF-based collectors for containerized workloads, eliminating the need for mirrored switch ports and span sessions. This compression of data collection topology is decentralizing vendor competitive advantage from hardware probe density to software agent efficiency.
The EU AI Act's risk classification framework for automated decision systems is mandating algorithmic audit trails for network anomaly detection. European enterprises must now document training data provenance and model drift for AI-driven root cause analysis tools. Financial services and critical infrastructure operators in Germany and France are responding by procuring monitoring platforms with built-in explainability dashboards and human-in-the-loop escalation workflows.
Enterprise buyers are unbundling implementation and tuning services from perpetual license purchases, treating network observability as a consumable operational expense rather than capital equipment. Systems integrators and managed service providers are capturing margin pools previously retained by product vendors through multi-year operational contracts. This reconfiguration of procurement authority is most visible in United States mid-market healthcare and retail verticals, where IT headcount constraints favor outsourced expertise over in-house platform mastery.
Network Performance Monitoring Market Segmentation
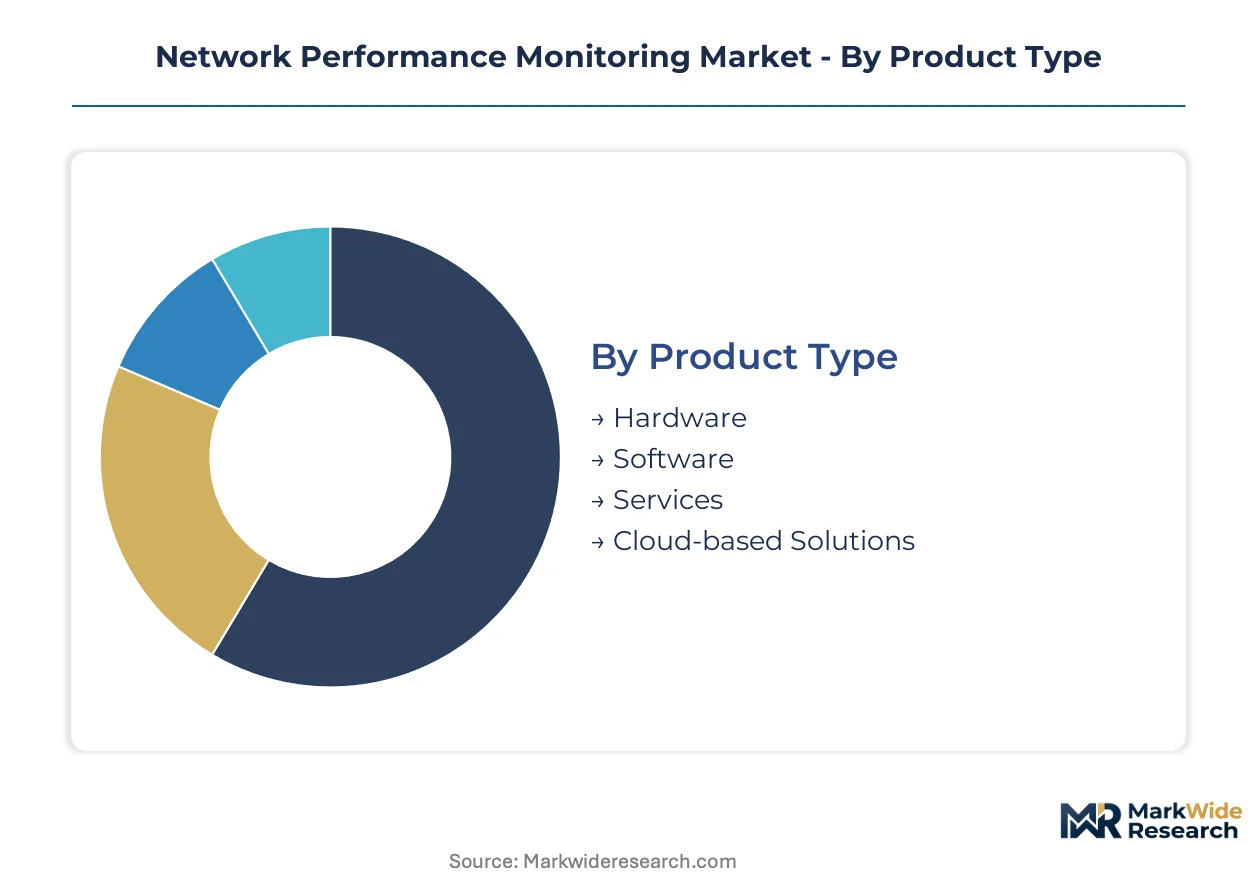
Network performance monitoring procurement splits sharply between capital-intensive hardware buyers and operational-expense-driven cloud adopters. Deployment architecture choices now determine vendor selection more than feature parity, as telemetry elasticity requirements reshape budget allocation patterns across IT organizations.
Product Type:
Hardware procurement concentrates among defense and critical infrastructure operators with air-gapped compliance mandates. Software and services capture expanding share as subscription economics displace perpetual licensing.
- Hardware:Dedicated probe appliances, packet brokers, and network tap devices deliver deep packet inspection at line rate. Demand clusters within US federal agencies and European defense ministries where NIST frameworks and EU NIS2 directives prohibit cloud telemetry egress.
- Software:Agent-based collectors and flow analysis platforms deploy across virtualized infrastructure. Financial services firms in New York and London prioritize these for east-west traffic visibility within private data centers.
- Services:Implementation, tuning, and managed observability contracts now carry the deepest margin pools. US mid-market healthcare and retail verticals outsource platform mastery due to IT headcount constraints.
- Cloud-based Solutions:API-driven telemetry ingestion scales elastically with containerized workloads. Enterprises retiring on-premises probe hardware favor these for hybrid and multi-cloud architectures.
Volume sits with Hardware; growth tilts toward Cloud-based Solutions.
Deployment Model:
Compliance posture and data sovereignty requirements dictate architecture selection more than technical capability. Hybrid deployments are fragmenting as regulators impose stricter cross-border data governance.
- On-premises:Complete control over telemetry storage and processing satisfies GDPR data localization and US federal security mandates. German automotive manufacturers and French energy operators maintain these for operational technology network segmentation.
- Cloud:Elastic compute for analytics and storage reduces capital burden. Japanese and South Korean enterprises adopt these for rapid 5G network slicing instrumentation without infrastructure procurement cycles.
- Hybrid:Split architectures preserve sensitive traffic analysis on-premises while offloading historical storage. US healthcare systems use these to segment HIPAA-protected patient data from operational metrics.
- Managed Services:Third-party operation of monitoring infrastructure transfers staffing risk. UK and Australian enterprises with limited Site Reliability Engineer availability contract these for 24/7 incident response.
Revenue concentrates in Hybrid; Managed Services are climbing the fastest.
End User:
Scale of infrastructure and regulatory exposure create divergent feature requirements. Procurement authority is shifting from network operations to security and cloud platform teams.
- Enterprises:Distributed branch offices and multi-cloud estates require unified visibility. US retail chains and European logistics operators prioritize these for SD-WAN performance assurance.
- Telecom Providers:Radio access networks and core infrastructure demand carrier-grade scale. South Korean and Japanese operators invest here for 5G per-slice quality of service monitoring.
- Data Centers:Hyperscale campuses in Virginia, Texas, and Oregon drive east-west traffic visibility requirements. Colocation providers need these to offer differentiated SLA-backed cross-connect services.
- Government:Classified and critical national infrastructure mandates specialized compliance. US federal cloud migration directives and EU critical entity designations shape procurement specifications.
Volume sits with Enterprises; expansion tilts toward Data Centers.
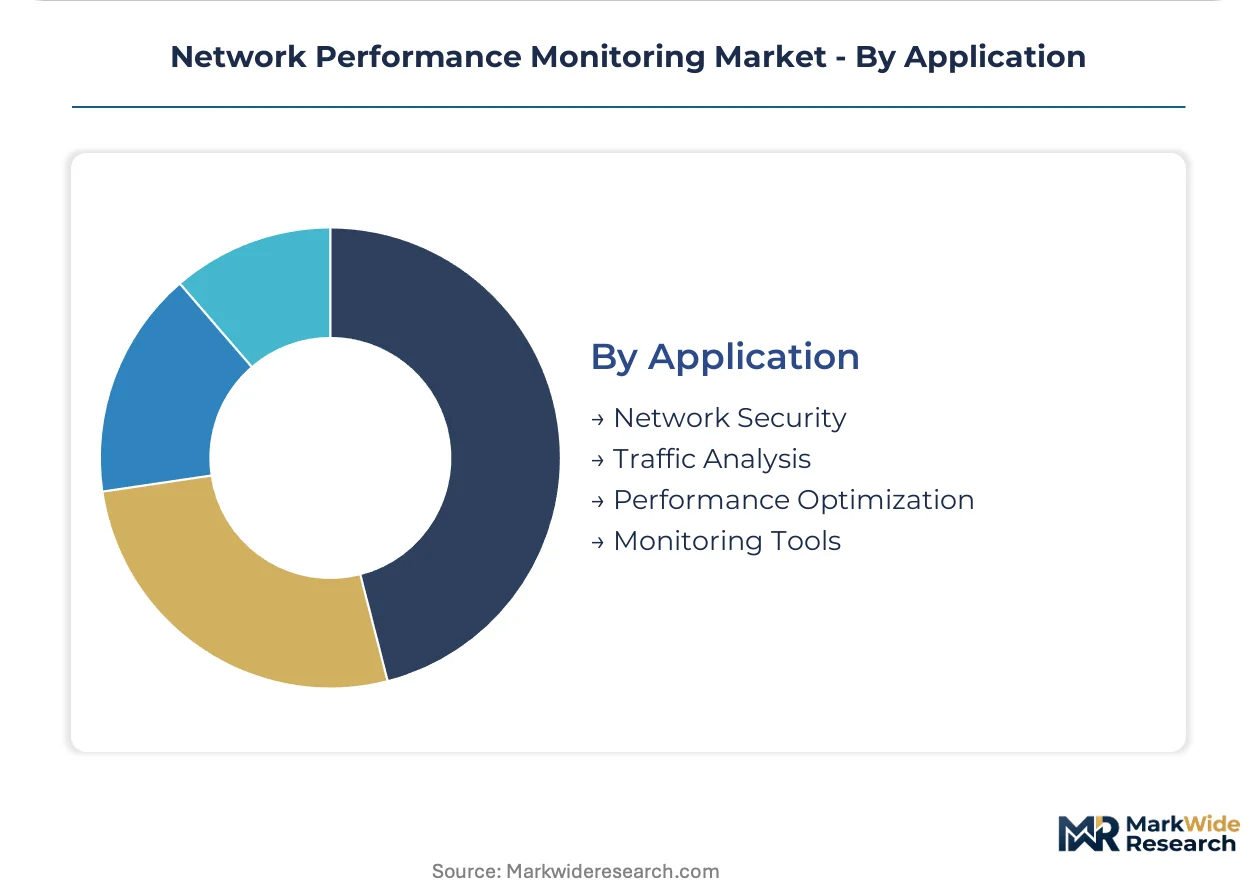
Application:
Security and performance use cases are converging as zero-trust architectures mandate continuous inspection. Tool unification is reducing point solution proliferation.
- Network Security:Threat detection and encrypted traffic analysis require SSL decryption and behavioral analytics. US financial services deploy these for SEC-mandated market manipulation surveillance.
- Traffic Analysis:Flow records and packet capture support capacity planning and anomaly detection. European telecom regulators require these for net neutrality compliance monitoring.
- Performance Optimization:Latency, jitter, and bandwidth utilization tuning preserves application SLAs. High-frequency trading infrastructure in Chicago and Frankfurt depends on these for microsecond-level precision.
- Monitoring Tools:Dashboards, alerting, and automated remediation workflows consolidate operational visibility. DevOps teams in San Francisco and Seattle standardize on these for cloud-native service reliability.
Revenue concentrates in Network Security; Performance Optimization gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in US software corridors while consumption spreads across regulated financial centers and hyperscale data center clusters. European demand fragments under sovereignty constraints. Asian expansion centers on 5G infrastructure buildouts.
United States
FCC net neutrality proceedings and NIST cybersecurity framework mandates drive procurement of lawful intercept-compatible probe architectures. Federal cloud migration directives pull agencies toward passive monitoring systems with air-gapped compliance capabilities. Virginia, Texas, and Oregon hyperscale campuses intensify east-west traffic visibility requirements for colocation providers.
Germany
Automotive manufacturers and energy operators maintain on-premises telemetry for operational technology network segmentation under GDPR data localization rules. The EU AI Act's algorithmic transparency requirements shape procurement of explainable anomaly detection platforms. Frankfurt and Munich data centers host sovereignty-compliant processing for financial services monitoring.
United Kingdom
Managed observability services capture share among enterprises with limited Site Reliability Engineer availability. NHS digital transformation programs mandate continuous network performance assurance for patient data systems. London's financial services sector deploys microsecond-precision latency monitoring for trading infrastructure.
South Korea
Telecom operators invest in granular per-slice performance metrics for 5G network slicing instrumentation. Seoul Capital Area cloud providers adopt elastic API-driven telemetry without infrastructure procurement cycles. MFDS-aligned critical infrastructure operators specify carrier-grade scale for radio access network monitoring.
Japan
METI industrial digitization programs accelerate retirement of on-premises probe hardware in favor of containerized workload visibility. Osaka and Nagoya manufacturing clusters integrate network and application performance telemetry through kernel instrumentation. Financial services firms in Tokyo prioritize automated remediation workflows for mission-critical trading systems.
Network Performance Monitoring Market Competitive Environment
Capital-heavy hardware appliance producers compete with asset-light cloud-native platform designers for procurement authority. The vendor base stratifies across three tiers: hyperscaler-aligned SaaS platforms, channel-dependent modular subscription providers, and open-source distribution specialists. Strategic differentiation centers on agent efficiency versus probe density, API elasticity versus perpetual license lock-in. Dominant competitive moves include geographic infrastructure expansion for sovereignty compliance and managed services bundling to capture recurring revenue streams.
Within the open-source distribution tier, Zabbix exemplifies cost-sensitive market penetration across European and Asian telecom providers. SolarWinds occupies the channel-dependent modular subscription position with broad mid-market IT department penetration. LogicMonitor represents the cloud-native infrastructure metrics archetype, competing directly with hyperscaler-native tooling for elastic telemetry ingestion contracts.
| Leading Market Players |
|---|
| Paessler PRTG |
| ManageEngine OpManager |
| SolarWinds |
| NinjaOne |
| Domotz |
| Auvik |
| Zabbix |
| Selector |
| LogicMonitor |
| Others |
Value Chain & Pricing Dynamics
eBPF kernel instrumentation expertise concentrates in San Francisco and Seattle labor markets, inflating compensation premiums that compress margins in economy-tier SaaS offerings while widening spreads between premium managed services and self-hosted deployments.
Pricing Analysis
Margin tightening in economy-tier software subscriptions traces to hyperscaler-native tooling price competition and customer consolidation onto unified observability platforms. Pricing stratifies across premium managed observability contracts, standard SaaS API tiers, and economy self-hosted agent deployments. Cost-down pressure on standard tiers accelerates because European GDPR-compliant hosting requires redundant regional infrastructure investment. Government and defense buyers exhibit lowest price sensitivity due to air-gapped compliance mandates prohibiting cloud alternatives.
Supply Chain Analysis
Regional distribution centers in Virginia, Texas, and Oregon hyperscale campuses anchor hub-and-spoke patterns for probe hardware fulfillment to federal agencies and defense contractors. Component manufacturing draws from Taiwan for packet processing silicon, South Korea for memory modules, and domestic US facilities for lawful intercept-certified chassis assembly. Single-source vulnerability concentrates in specialized SSL decryption ASICs subject to export control restrictions. Distribution runs through channel partners serving mid-market IT departments and direct enterprise sales for carrier-grade deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Network performance monitoring vendors are racing to deepen upstream control over eBPF agent development and kernel instrumentation IP to escape commodity telemetry collection margins.
For Market Incumbents: Deploy managed observability service bundling to capture recurring revenue streams and defend against hyperscaler-native tooling substitution. Expand Frankfurt and Amsterdam sovereignty-compliant hosting capacity to meet EU AI Act algorithmic audit requirements. Channel control through systems integrator partnerships protects mid-market penetration against open-source Zabbix displacement. For New Entrants and Emerging Players: Cloud-native API-first positioning offers the most penetrable wedge for European telecom providers seeking 5G network slicing instrumentation without legacy SNMP migration friction. Target South Korean and Japanese operators with per-slice quality of service modules. Freemium container visibility tiers accelerate land-and-expand cycles among DevOps teams standardizing on Prometheus and Grafana. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated monitoring platform developers given NIST cybersecurity framework compliance mandates accelerating federal procurement cycles. Acquisition target archetypes include eBPF kernel instrumentation specialists and regional managed services providers with existing GDPR-compliant infrastructure. The signal to watch is FCC net neutrality rulemaking direction affecting latency-sensitive financial services infrastructure investment.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying packet capture with container runtime metrics collapses vendor point solution proliferation. |
| Geographic Expansion | Frankfurt and Amsterdam data center builds satisfy EU AI Act algorithmic transparency hosting requirements. |
| Strategic Partnership | Systems integrator alliances transfer implementation risk while capturing mid-market healthcare procurement authority. |
| Acquisition of Specialist Firm | eBPF kernel instrumentation targets enable telemetry agent efficiency advantages over hardware probe density. |
| Product Launch | Explainable AI monitoring modules address European financial services algorithmic audit trail mandates. |
Study Parameters
SEC filings, hyperscaler capex disclosures, and hyperscale data center development permits formed the secondary backbone for infrastructure investment trend validation. Primary interviews with network operations directors, Site Reliability Engineers, federal IT procurement officers, and channel sales heads at systems integrators cross-referenced deployment architecture preferences against vendor pricing disclosures. Bottom-up telemetry platform adoption modeling and top-down IT budget allocation analysis triangulated segment-level demand estimates.
Historical trendline analysis of subscription revenue recognition patterns and perpetual license displacement rates informed growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization scale, vertical regulatory exposure, integration complexity with existing SNMP infrastructure, and regional data sovereignty requirements. CAGRs derived from elasticity-adjusted adoption curves incorporating 5G network slicing instrumentation contracts and federal cloud migration directive compliance spending.
The model holds under steady regulatory enforcement of GDPR cross-border data governance and NIST cybersecurity framework mandates; deviation in FCC net neutrality proceedings or EU AI Act implementation timing would shift procurement priority rankings. Forecasts reflect documented assumptions regarding hyperscaler-native tooling competitive pressure and eBPF instrumentation standardization velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Cloud Managed Access Points Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
Hyperconnectivity Market
Network Technology
Residential Routers Market
Network Technology
Global Active Network Management Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Sand Lane Systems Market
Network Technology
Self-Healing Networks Market
Network Technology
Global Intelligent Network Market
Network Technology
Low-Power WAN Market
Network Technology
Wi-Fi Router Market
Network Technology
Managed MPLS Market
Network Technology
Europe SD-WAN Market
Network Technology
Global 5G Smart Antenna Market