
 Data Center Switches Market | 2026-2036
Data Center Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Switches Market Outlook
PCIe 5.0 and CPO (Co-Packaged Optics) readiness certifications are reorganizing supplier eligibility for next-generation data center fabrics. Cisco Systems leverages its merchant silicon partnerships to sustain switching portfolio breadth across enterprise and cloud segments. Arista Networks anchors its position through EOS software consistency across 100G to 800G platforms. Juniper Networks competes via Apstra intent-based automation in cloud provider deployments.
Data center switches are high-performance packet forwarding devices engineered for sub-microsecond latency, supporting port densities exceeding 64 x 400G in a single chassis, designed to interconnect servers, storage, and network functions within centralized or distributed computing facilities. Layer 3 switches now capture the dominant margin pool as routing intelligence migrates deeper into access tiers. Edge computing deployments represent the fastest-expanding deployment segment as latency-sensitive workloads push processing toward network peripheries.
NIST cybersecurity frameworks and the EU F-Gas Regulation constrain thermal management and component sourcing choices for switch vendors serving regulated verticals. The FCC's equipment authorization process gates market access for radio-frequency-adjacent management modules in US-bound products. Buyers must monitor CPO interoperability testing progress and regional energy efficiency mandates as primary determinants of procurement timing and vendor shortlisting.
Market Dynamics
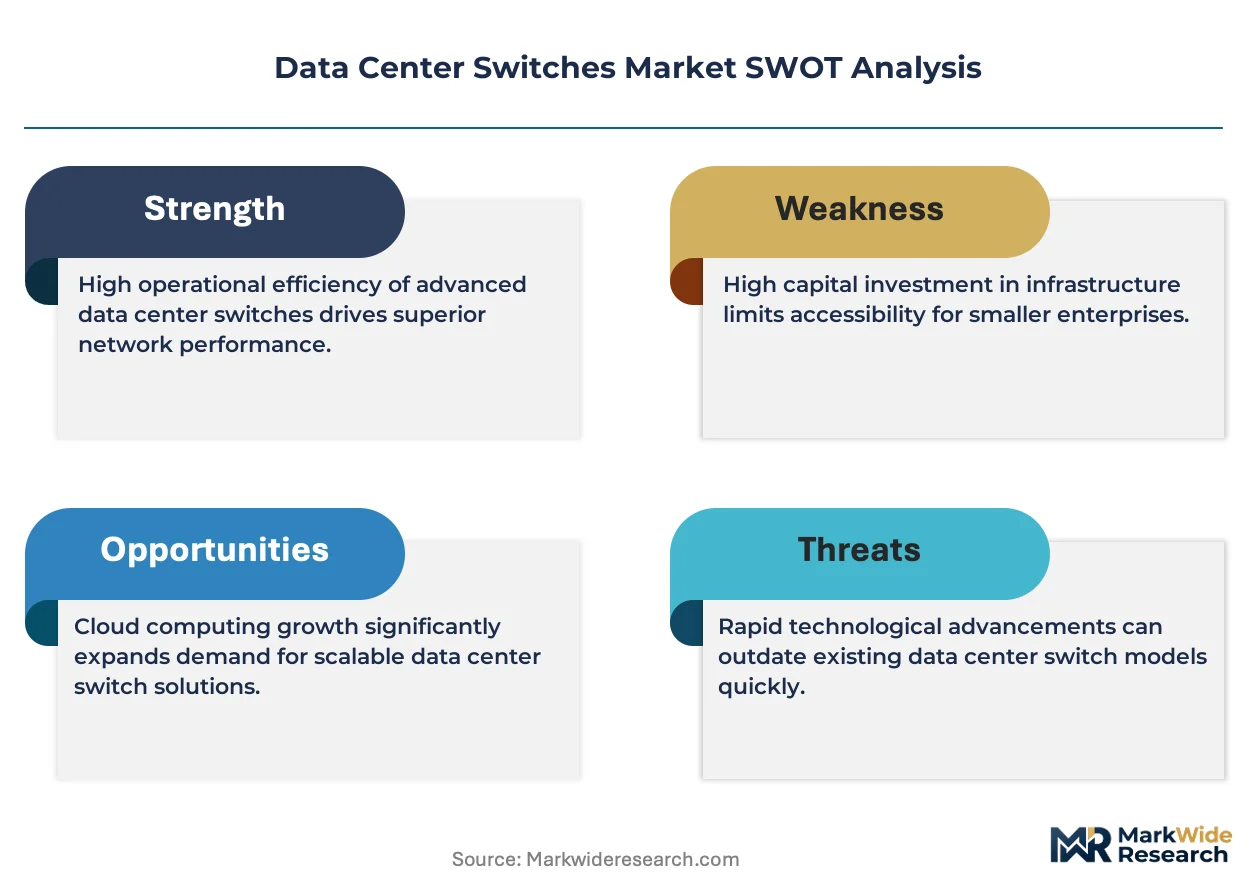
The transition to 400G and 800G Ethernet speeds is compressing hardware refresh cycles and forcing infrastructure operators to requalify supplier relationships around PCIe 5.0 and CPO readiness.
Growth Catalysts
- Hyperscale cloud expansion:Physical infrastructure footprints in Northern Virginia and Dallas-Fort Worth corridors are absorbing record switch volumes as operators provision AI training clusters.
- EU F-Gas Regulation:Thermal management mandates are accelerating liquid-cooled switch designs that command premium positioning in regulated European verticals.
- Edge computing latency requirements:Distributed inference workloads are pulling high-port-density switches into metropolitan edge facilities previously served by aggregation-tier hardware.
Market Restraints
- Merchant silicon concentration:Switching ASIC supply concentrates among three foundry-dependent vendors, creating allocation risk during foundry node transitions.
- Copper interconnect limitations:Signal integrity constraints at 112G PAM4 are forcing premature optical transition in rack-scale deployments.
- FCC equipment authorization:Radio-frequency-adjacent management modules face 6-9 month approval timelines that gate US market entry for new product families.
Strategic Opportunities
- India data center buildout:Domestic cloud operators and colocation providers are greenfielding facilities that bypass legacy 10G/25G architectures entirely.
- Co-Packaged Optics convergence:Integration of silicon photonics with switch ASICs enables 51.2Tbps single-chip designs that slash power-per-bit by half.
- CE marking pathway:EU Cybersecurity Act certification requirements are creating first-mover advantage for vendors with pre-certified supply chains.
Industry Challenges
- Intent-based networking skill scarcity:Enterprise IT organizations lack personnel fluent in API-driven fabric automation, slowing Apstra-class deployments.
- Multi-generational interoperability:400G switches must maintain backward compatibility with 100G leaf architectures during multi-year migration windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Switches Market |
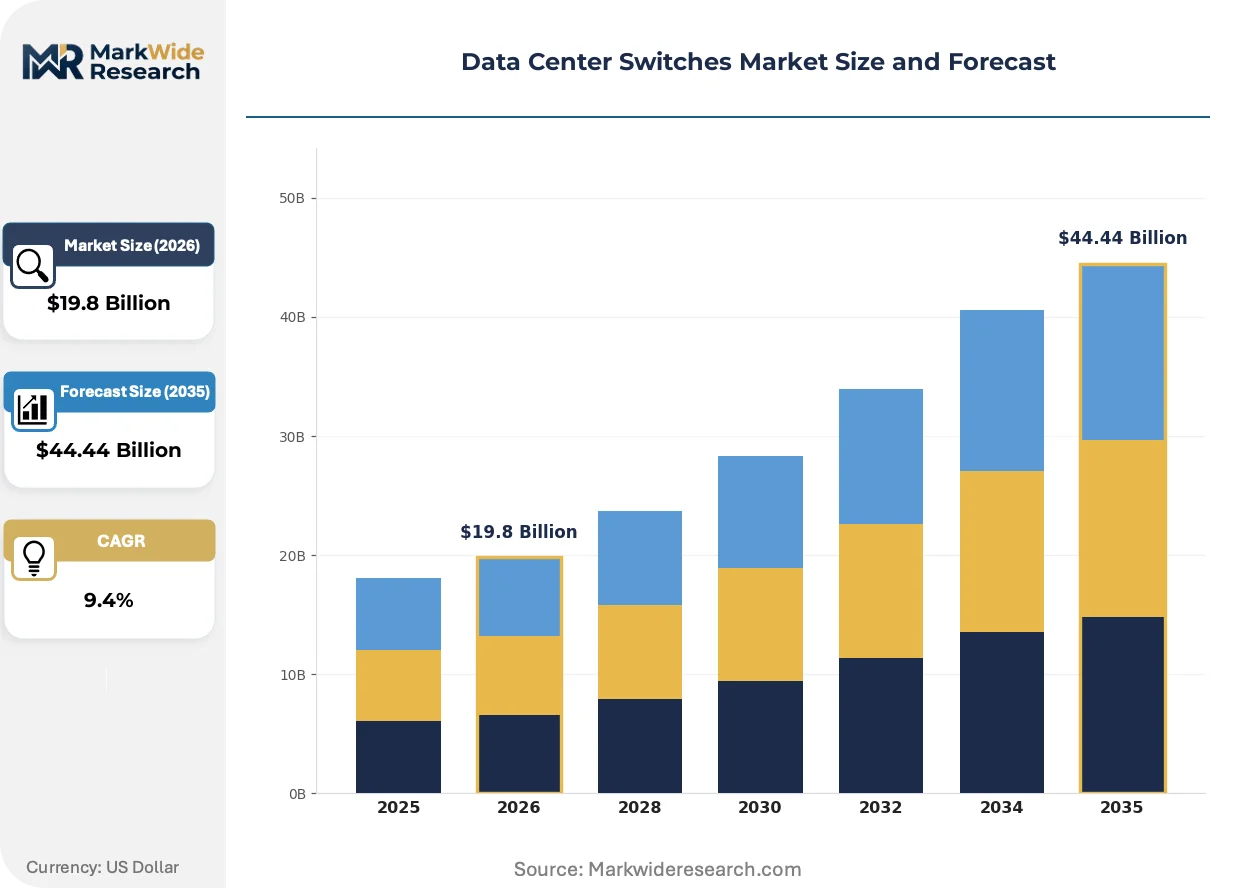
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $44.44 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Layer 2 Switches, Layer 3 Switches, Multilayer Switches, Managed Switches Deployment: On-Premises, Cloud, Hybrid, Edge Computing Technology: Ethernet, InfiniBand, Fibre Channel, VXLAN End User: Telecommunications, BFSI, Government, Healthcare |
| Companies Covered | Cisco Systems, Arista Networks, Juniper Networks, Hewlett Packard Enterprise, Huawei Technologies, Dell Technologies, Extreme Networks, Broadcom, NVIDIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Switches Market Strategic Shifts
Silicon photonics integration and software-defined fabric management are rewriting cost structures and supplier qualification criteria across data center network tiers.
Co-Packaged Optics is displacing pluggable transceiver modules in high-density spine switches. Hyperscale operators are deploying CPO-enabled 51.2T platforms in production AI clusters during 2024-2025 qualification cycles. This technology is displacing traditional optical interconnect margins and consolidating value capture within switch silicon vendors.
REACH substance restrictions are tightening compliance obligations for switch PCB substrates and thermal interface materials. European data center operators now mandate full material disclosure upstream of procurement decisions. German industrial colocation providers have established dedicated supply chain audit functions to verify RoHS and REACH conformity.
Subscription-based network operating system licensing is replacing perpetual software purchases in enterprise segments. Buyers are trading capital expenditure predictability for operational flexibility, with multi-year EOS-style agreements displacing traditional hardware-software bundling. This pattern is most pronounced in US financial services and healthcare verticals facing NIST cybersecurity framework compliance deadlines.
Data Center Switches Market Segmentation
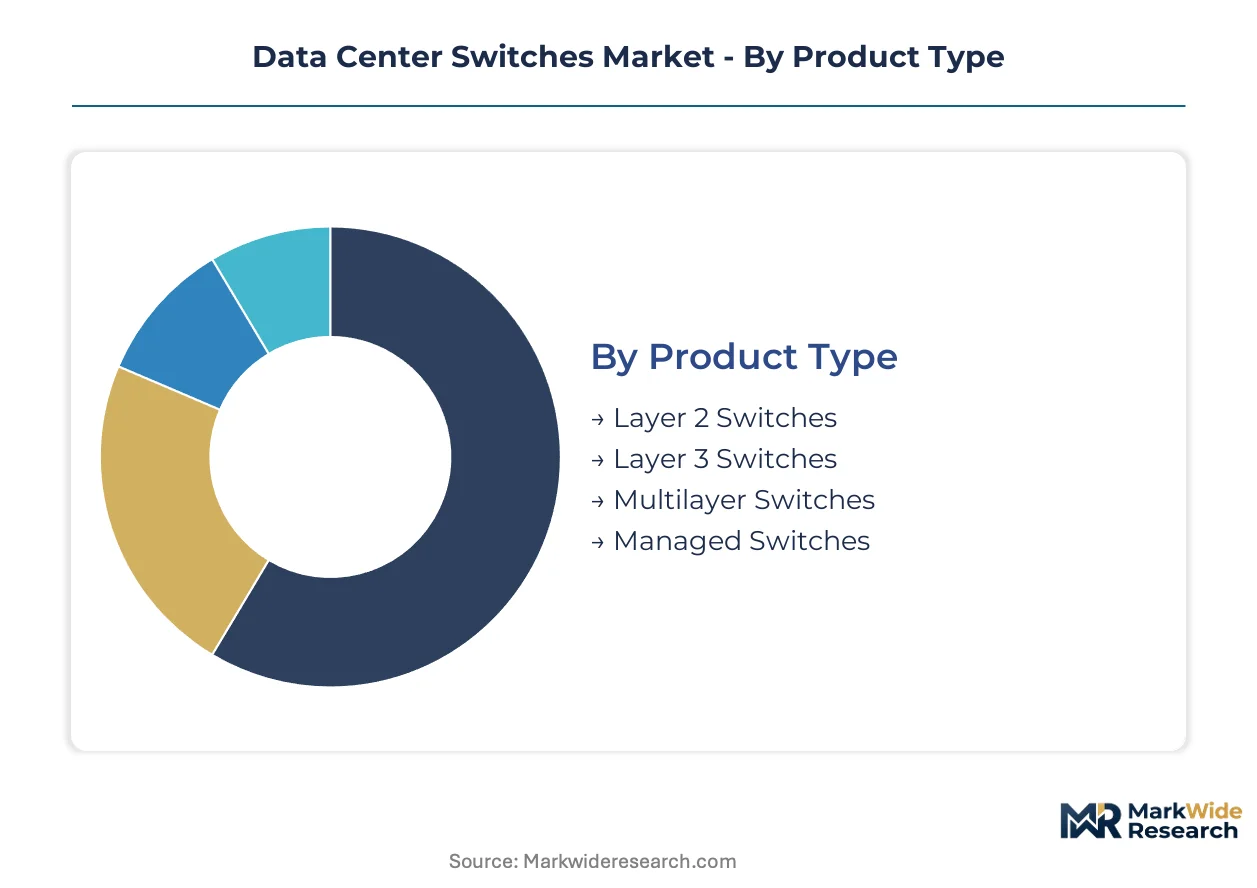
Segmentation in the data center switches market determines procurement channel access, with enterprise IT sourcing through value-added resellers while hyperscale operators negotiate direct with original equipment manufacturers. Channel mix varies sharply by deployment scale and technical complexity tier.
Product Type:
Layer 2 and Layer 3 switches flow predominantly through distributor networks serving mid-market enterprises, while multilayer platforms reach buyers via direct sales teams and systems integrators handling complex fabric deployments.
- Layer 2 Switches:These devices operate at the data link layer, handling MAC address-based forwarding without IP routing intelligence. Demand concentrates in small-to-mid enterprise server closets and remote office deployments across Germany and Japan, constrained by flat network scalability limits.
- Layer 3 Switches:Hardware-integrated routing engines enable inter-VLAN traffic management and policy-based forwarding at wire speed. Northern Virginia hyperscale facilities and Dallas-Fort Worth AI training clusters absorb the dominant volume, driven by spine-leaf architecture mandates requiring distributed routing intelligence.
- Multilayer Switches:Unified platforms combining switching, routing, and deep packet inspection capabilities for converged infrastructure.
- Managed Switches:Remote configuration and monitoring capabilities via SNMP or REST APIs for distributed enterprise edge locations.
Layer 3 switches dominate installed base. Multilayer switches are where expansion concentrates.
Deployment:
Cost tier stratification separates commodity on-premises hardware from premium cloud-integrated platforms, with hybrid and edge deployments commanding intermediate pricing bands reflecting software-defined orchestration requirements.
- On-Premises:Customer-owned and operated switch infrastructure within enterprise-owned facilities, requiring full capital expenditure and operational staffing. Financial services compliance mandates in New York and London drive refresh cycles, constrained by data sovereignty requirements blocking cloud migration.
- Cloud:Switches deployed within hyperscale operator facilities, consumed as embedded infrastructure within compute and storage services. India's domestic cloud buildout and Brazil's expanding colocation market absorb expanding volumes, enabled by wholesale bandwidth pricing and tax incentives for local data residency.
- Hybrid:Orchestrated fabrics spanning private data centers and public cloud interconnects, requiring consistent policy enforcement across administrative boundaries.
- Edge Computing:High-port-density switches in metropolitan facilities serving latency-sensitive inference and content delivery workloads.
On-premises retains the largest installed base. Edge computing is climbing the fastest.
Technology:
Volume concentration favors Ethernet for general-purpose workloads, with alternative protocols capturing specialized high-performance computing and storage networking niches where latency tolerances tighten.
- Ethernet:Dominant packet-switched networking standard with speeds from 1G to 800G, supported by broad interoperability certification. Migration to 400G and 800G speeds in United States and Chinese hyperscale corridors accelerates hardware replacement, constrained by PCIe 5.0 ecosystem readiness and CPO interoperability testing timelines.
- InfiniBand:Low-latency, high-throughput interconnect optimized for HPC clusters and AI training fabrics. Research computing centers in Switzerland and South Korea deploy expanding volumes, driven by RDMA requirements for GPU-to-GPU communication in large language model training.
- Fibre Channel:Lossless, deterministic storage area networking protocol for enterprise SAN environments.
- VXLAN:Network virtualization overlay technology enabling multi-tenant Layer 2 extension across Layer 3 infrastructure.
Ethernet dominates installed base. InfiniBand is where expansion concentrates.
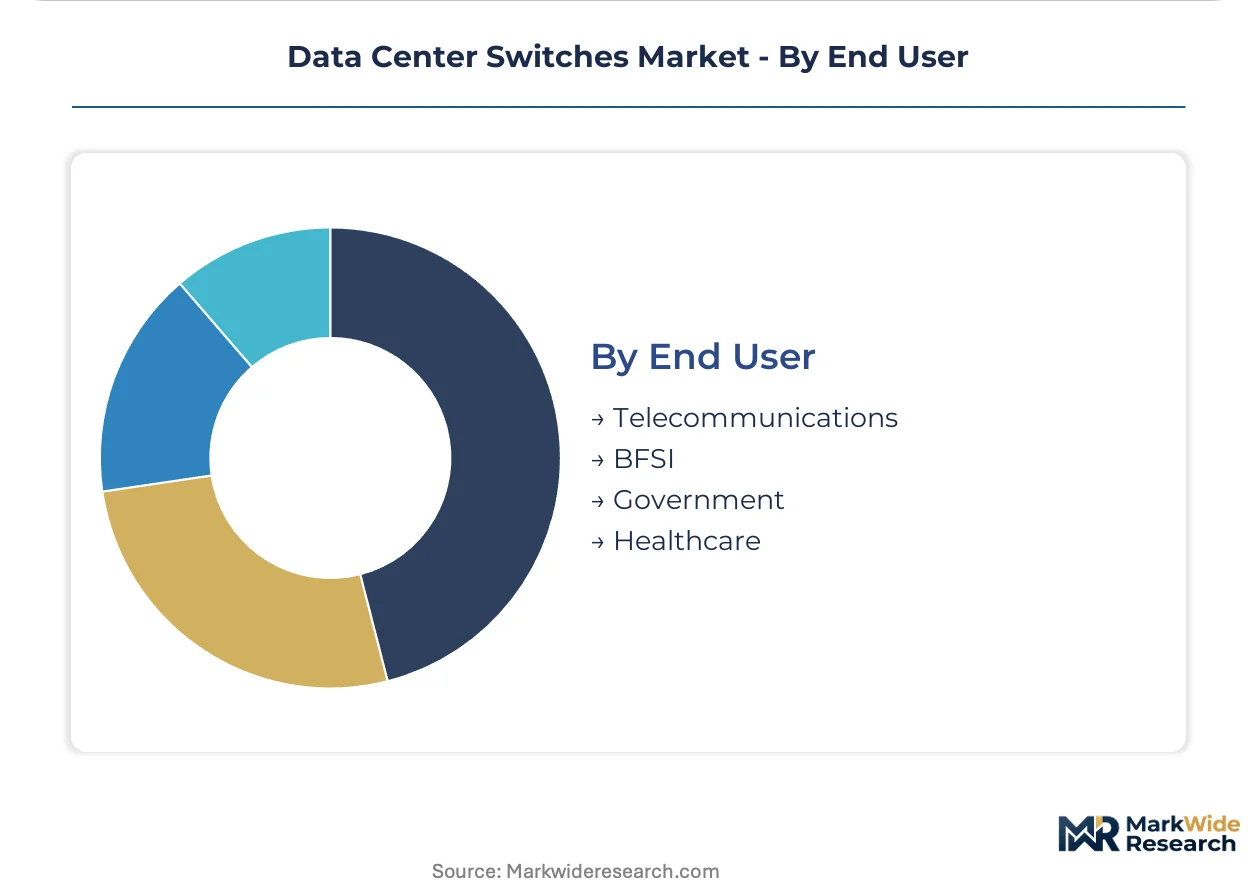
End User:
Customer type determines sales cycle length and solution bundling depth, with telecommunications carriers demanding extensive professional services while BFSI procurement emphasizes compliance documentation and audit trails.
- Telecommunications:Carrier-grade switches for 5G core networks, edge data centers, and content delivery infrastructure. Deployment in Saudi Arabia's NEOM corridor and Australia's suburban edge facilities accelerates, driven by network function virtualization mandates and latency targets for augmented reality services.
- BFSI:High-availability switching for trading floors, payment processing, and regulatory data archives. Frankfurt and Singapore financial districts sustain replacement demand, constrained by NIST cybersecurity framework deadlines and ECB operational resilience requirements.
- Government:Certified secure switching for defense, intelligence, and civilian agency data centers.
- Healthcare:HIPAA-compliant network infrastructure connecting electronic health record systems and medical imaging archives.
Telecommunications dominates installed base. BFSI is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax incentives for domestic cloud infrastructure are redirecting data center investment flows across multiple jurisdictions. Sovereign data residency mandates are forcing switch procurement localization in emerging markets. Energy efficiency regulations are reshaping equipment qualification criteria in established corridors.
United States
Hyperscale operators are expanding AI training clusters in Northern Virginia and Dallas-Fort Worth metro corridors. The FCC's equipment authorization process gates market access for radio-frequency-adjacent management modules. Northern Virginia's data center corridor absorbs record switch volumes as operators provision liquid-cooled facilities.
Germany
Industrial colocation providers are establishing dedicated supply chain audit functions for RoHS and REACH conformity verification. The EU F-Gas Regulation constrains thermal management choices for switch vendors serving regulated verticals. Frankfurt's financial district sustains replacement demand driven by ECB operational resilience requirements.
India
Domestic cloud operators and colocation providers are greenfielding facilities that bypass legacy 10G/25G architectures entirely. The PLI scheme incentivizes local manufacturing of networking equipment for data center applications. Maharashtra and Karnataka host expanding hyperscale campuses serving South Asian cloud demand.
China
MIIT standards for data center energy efficiency are accelerating 400G and 800G migration timelines. Dual carbon goals constrain power density thresholds for switch deployments in eastern provinces. The Yangtze River Delta and Pearl River Delta concentrate domestic cloud operator expansion and AI infrastructure buildout.
Saudi Arabia
NEOM corridor deployments are accelerating carrier-grade switch procurement for 5G core networks and edge data centers. The central bank and communications regulator enforce data localization requirements for financial services infrastructure. Riyadh and the Eastern Province absorb expanding volumes from network function virtualization mandates.
Data Center Switches Market Competitive Environment
Player mix skews toward diversified networking incumbents with merchant silicon partnerships. The supplier base concentrates around three strategic tiers: full-stack infrastructure vendors, cloud-optimized specialists, and component-level silicon providers. Consolidation pressures favor vendors with intent-based automation software and CPO-ready hardware platforms. Competitive moves center on PCIe 5.0 ecosystem partnerships and liquid-cooled chassis certifications.
Within the cloud-optimized tier, Arista Networks and Juniper Networks exemplify vendors competing via software consistency and automation capabilities. Among diversified infrastructure providers, Cisco Systems occupies a position representing merchant silicon partnership strategies across enterprise and cloud segments. Component-level positioning includes Broadcom and NVIDIA, which anchor value capture in switching ASIC and accelerated networking silicon respectively.
| Leading Market Players |
|---|
| Cisco Systems |
| Arista Networks |
| Juniper Networks |
| Hewlett Packard Enterprise |
| Huawei Technologies |
| Dell Technologies |
| Extreme Networks |
| Broadcom |
| NVIDIA |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day lead times for merchant switching ASICs concentrate pricing power with foundry-dependent silicon vendors and force buyers into long-term allocation commitments. This inventory compression cascades through chassis assembly tiers, amplifying cost pass-through to hyperscale operators while squeezing margin buffers for enterprise-focused distributors.
Pricing Analysis
Certification level (CE marking for EU Cybersecurity Act compliance, FCC equipment authorization for US-bound modules) creates the primary spread between premium and standard tiers. Subscription-based network operating system licensing now dominates enterprise procurement, displacing perpetual purchases. Pricing pressure stems from merchant silicon commoditization in 400G leaf switch segments. Hyperscale operators exhibit lowest price sensitivity due to volume scale; mid-market enterprises show highest sensitivity to total cost of ownership shifts.
Supply Chain Analysis
TSMC advanced node allocation in Taiwan underwrites switching ASIC supply security for the entire market. Foundry output from South Korea and specialized substrate manufacturing from Japan anchor upstream capacity. Supply chains draw from silicon photonics components, high-speed PCB laminates, and liquid-cooled thermal interface materials. Single-source vulnerability concentrates in 3nm and 5nm foundry nodes. Distribution runs through direct OEM contracts for hyperscale buyers and value-added reseller networks for enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data center switches market sits in a cyclical recovery phase as AI infrastructure buildouts trigger the strongest hardware refresh cycle since cloud migration began. Hyperscale capital expenditure expansion provides the cyclical driver justifying near-term positioning.
For Market Incumbents: Consolidate merchant silicon partnerships through exclusive allocation agreements securing 51.2Tbps CPO-ready ASIC supply. Deepen liquid-cooled chassis certifications ahead of EU F-Gas Regulation enforcement windows. Defensive positioning requires pre-emptive PCIe 5.0 ecosystem lock-in to block emerging competitors from qualification cycles.
For New Entrants and Emerging Players: Anchor in India's greenfield data center buildout where legacy 10G/25G bypass creates architecture-agnostic procurement windows. Target domestic cloud operators in Maharashtra and Karnataka seeking alternatives to incumbent pricing. Go-to-market leverage rests on PLI scheme-compliant local manufacturing partnerships.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure consolidation play because switching ASIC value capture is migrating toward silicon photonics integration and away from chassis assembly. Acquisition focus should target component-level specialists with CPO-ready IP. Watch hyperscale qualification cycle announcements as inflection indicators for vendor share shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| CPO-Ready Platform Launch | Silicon photonics integration enables 51.2Tbps single-chip designs that halve power-per-bit for AI clusters. |
| Liquid Cooling Certification | EU F-Gas Regulation compliance opens premium positioning in Frankfurt and Northern Virginia regulated verticals. |
| Merchant Silicon Partnership | Exclusive allocation agreements with foundry-dependent vendors secure supply through node transition periods. |
| Intent-Based Automation Integration | Apstra-class fabric management addresses enterprise skill scarcity slowing cloud-optimized deployment adoption. |
| Edge Computing SKU Expansion | High-port-density switches capture metropolitan inference workloads pulling processing from core facilities. |
Study Parameters
Initial hypotheses were tested against primary input from data center infrastructure executives, network engineering leads at hyperscale operators, procurement managers at colocation providers, and channel sales directors at value-added resellers, then refined against secondary validation from SEC filings, hyperscaler capital expenditure disclosures, FCC equipment authorization databases, and customs trade records. Bottom-up vendor shipment estimates triangulated with top-down infrastructure investment flow analysis.
Variance decomposition across port speed transitions, deployment model shifts, and geographic buildout patterns anchored the analytical framework. Segmentation dimensions modeled include product type (Layer 2/3/multilayer), deployment architecture (on-premises/cloud/hybrid/edge), and end-user vertical. CAGRs derived from unit economics modeling of port shipments and average selling price trajectories. Forecast inputs incorporated foundry node transition timelines and regulatory compliance deadline clustering.
Material uncertainties — foundry allocation disruptions, CPO interoperability testing delays, and energy efficiency mandate acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding merchant silicon supply continuity and hyperscale capex commitment durability. Revision becomes warranted when FCC authorization backlogs exceed nine months or EU F-Gas enforcement timelines compress unexpectedly.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Fiber to the Home (FTTH) Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Cloud Managed Access Points Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Global Active Network Management Market
Network Technology
Mobile Network Optimization Market
Network Technology
Global Home Networking Device Market
Network Technology
Global Carrier Ethernet Equipment Market
Network Technology
Dark Fiber Market
Network Technology
Low-Power WAN Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
IT Connector Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
Network Packet Broker Market