
 Open RAN Market | 2026-2036
Open RAN Market Size, Share, and Industry Trends Forecast 2026-2036
Open RAN Market Analytics
Disaggregation of the radio access network stack is rewriting how telecom infrastructure gets deployed and upgraded. NEC Corporation leverages its longstanding relationships with Japanese operators to anchor early commercial deployments. Mavenir Systems specializes in cloud-native software layers that compete against incumbent hardware-centric vendors. Samsung Electronics extends its semiconductor manufacturing scale into radio unit production, positioning it to control costs across the Open RAN supply chain.
Open RAN denotes a standards-based architecture that separates baseband processing functions into centralized units, distributed units, and radio units communicating through open interfaces such as the O-RAN Alliance's 7.2x split. This architecture enables mobile operators to mix vendors across network layers, reducing dependency on single-supplier lock-in while introducing software-defined flexibility previously confined to core networks. Cloud-native deployment types are attracting the deepest R&D investment as operators seek elastic capacity scaling, while virtualized RAN network components carry the heaviest integration complexity and thus command premium professional services margins. Radio units remain the most mature segment with established hardware supply chains, whereas distributed units represent the fastest-growing configuration as edge computing requirements intensify latency-sensitive processing demands.
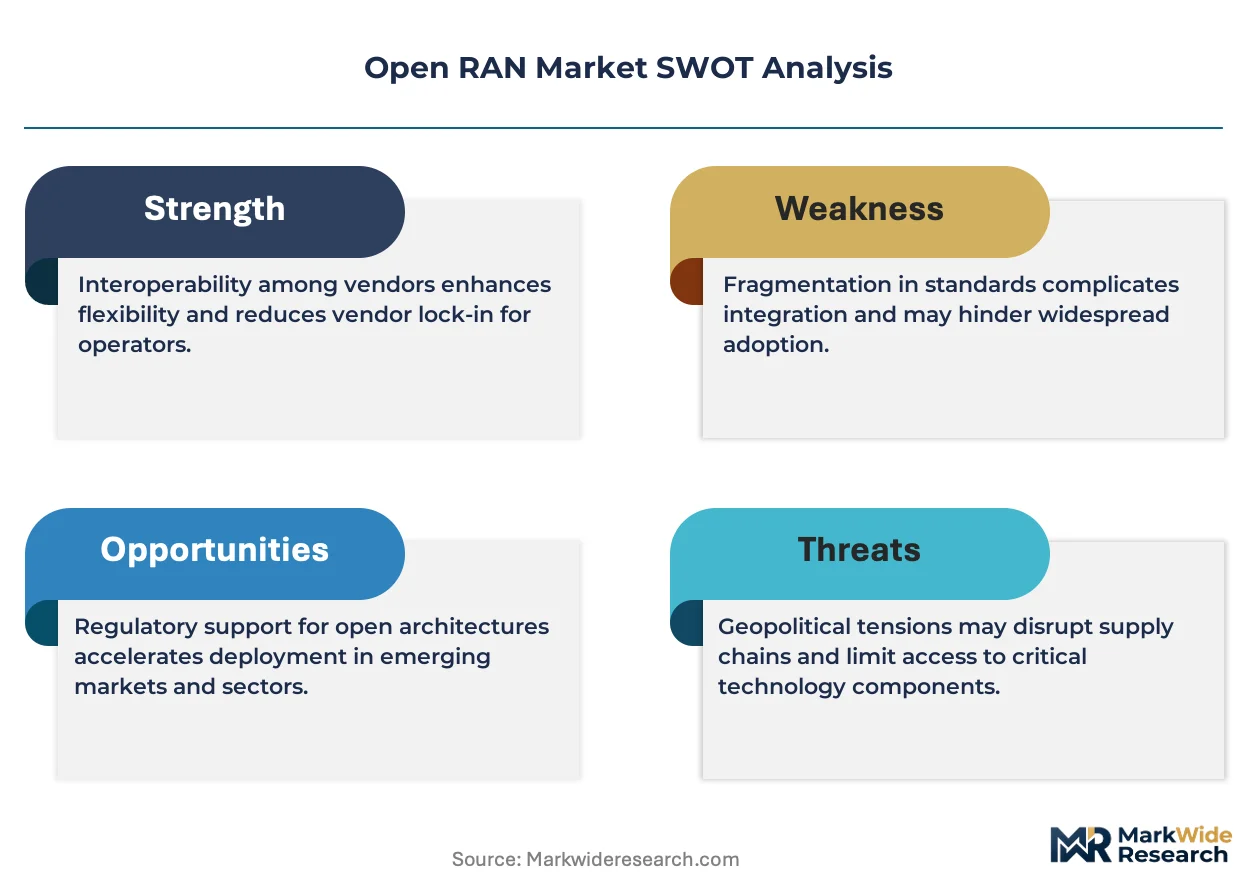
The O-RAN Alliance's security specifications and the Federal Communications Commission's rip-and-replace mandates are tightening vendor eligibility criteria across multiple jurisdictions. ETSI's NFV standards and the UK's Telecoms Security Act further constrain which integration levels qualify for national infrastructure contracts. Stakeholders must monitor whether interoperability certification timelines keep pace with operator deployment schedules as procurement shifts from pilot programs to multi-site rollouts.
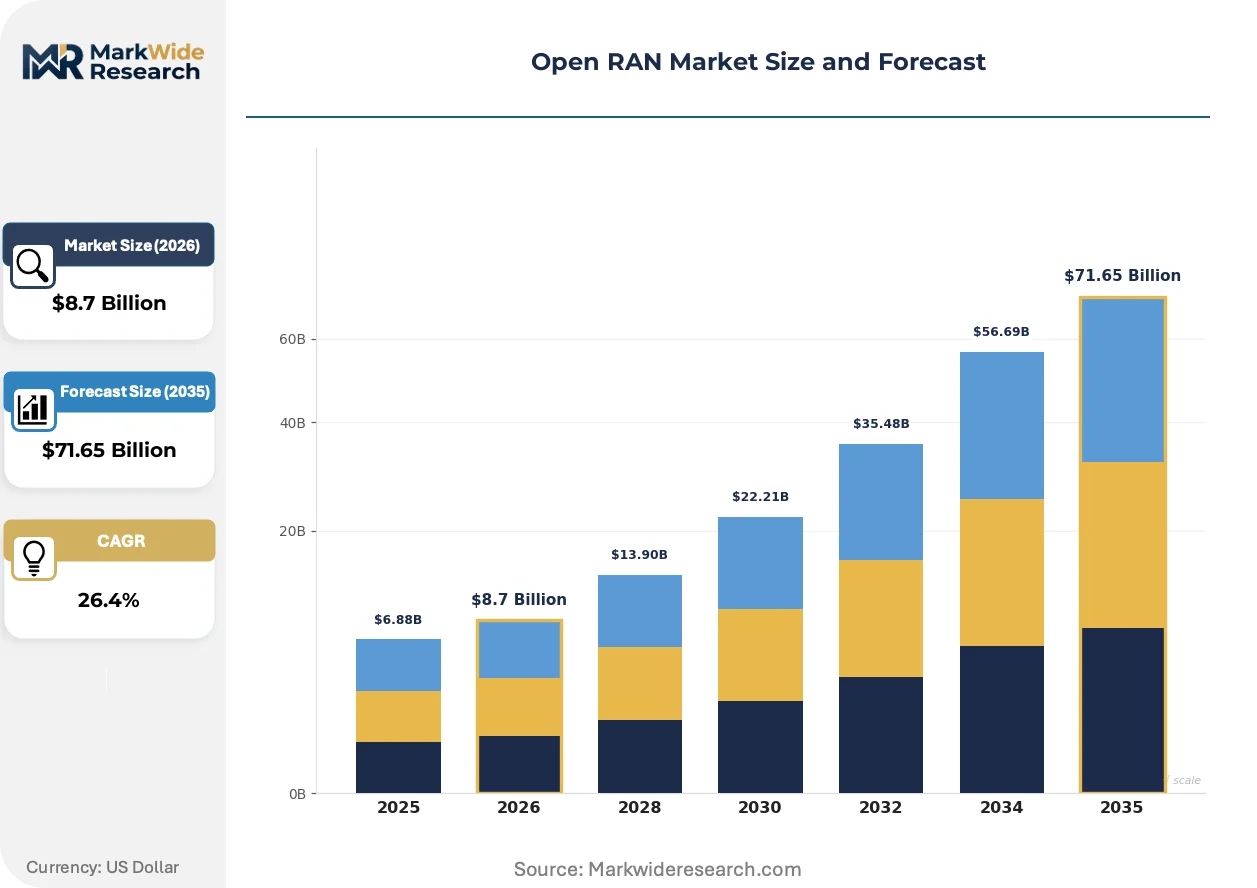
Market Dynamics
Disaggregation of the radio access network stack is forcing mobile operators to reconfigure procurement relationships and integration workflows. The O-RAN Alliance's interface specifications and national security mandates are simultaneously enabling vendor diversification while raising compliance barriers.
Growth Catalysts
- FCC Rip-and-Replace Mandates:US operators must remove designated vendor equipment from live networks, creating immediate demand for interoperable radio units and baseband software from qualified alternative suppliers.
- Industrial Campus Deployments:Manufacturing facilities in Germany require localized, low-latency connectivity that Open RAN architectures deliver through edge-distributed processing units.
- O-RAN Alliance Specifications:The 7.2x split standardization enables multi-vendor interoperability, reducing single-supplier dependency for mobile network operators.
Market Restraints
- Integration Cost Volatility:System integration expenses for multi-vendor deployments fluctuate with the availability of skilled radio frequency engineers and software-defined networking specialists.
- Radio Unit Supply Concentration:Semiconductor fabrication capacity constraints in East Asia limit the scalable production of massive MIMO radio units needed for dense urban deployments.
- EU Cybersecurity Certification:The EU's Cybersecurity Act imposes extended evaluation timelines that delay vendor qualification for critical national infrastructure contracts.
Strategic Opportunities
- Private Network Expansion:Mining operations and port authorities in Australia are deploying standalone Open RAN systems for mission-critical communications beyond public network coverage.
- AI-Driven Network Optimization:Machine learning algorithms are converging with RAN intelligent controllers to enable real-time spectral efficiency gains and predictive maintenance.
- Japan's Beyond 5G Program:METI funding incentives accelerate domestic vendor development and create reference architectures for export to Southeast Asian operators.
Industry Challenges
- Interoperability Certification Backlogs:O-RAN Alliance testing lab capacity constraints delay commercial deployment timelines for multi-vendor configurations.
- Legacy Hardware Depreciation:Operators face stranded asset risks as existing integrated RAN equipment reaches end-of-life before Open RAN migration completes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Open RAN Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $71.65 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Cloud-native, On-premise, Hybrid, Edge Computing Network Component: Radio Unit, Distributed Unit, Centralized Unit, Virtualized RAN End User Type: Mobile Network Operators, Enterprises, Governments, Neutral Host Integration Level: Full Stack, Open Source, Proprietary, Mixed |
| Companies Covered | NEC Corporation, Mavenir Systems, Inc., Ericsson, Airspan, Rakuten Symphony, Nokia Corporation, Fujitsu Limited, ZTE, Samsung Electronics Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Open RAN Market Evolving Landscape
Cloud-native software architectures are displacing hardware-centric deployment models across the radio access network. This transformation is compressing upgrade cycles and enabling elastic capacity scaling previously confined to core network functions.
Open RAN software stacks are hybridizing containerized microservices with traditional virtual machine orchestration to balance deployment flexibility against operational stability. Tier-one operators in South Korea are piloting these hybrid configurations for urban macro sites. The approach is compressing vendor lock-in durations while introducing new complexity in lifecycle management tooling.
The EU's Cybersecurity Act and associated ENISA certification schemes are mandating formal security assurance for network equipment across member states. Vendors must demonstrate supply chain integrity and secure development practices to qualify for public procurement. Radio unit manufacturers face the steepest compliance burden due to hardware-software interdependencies.
Enterprise buyers are consolidating vendor relationships around systems integrators capable of delivering complete Open RAN deployments rather than procuring disaggregated components separately. This pattern is most visible in Germany's industrial automation sector, where manufacturing conglomerates demand single-accountability deployment partners. Systems integrators are capturing margin pools that previously flowed to original equipment manufacturers.
Open RAN Market Segmentation
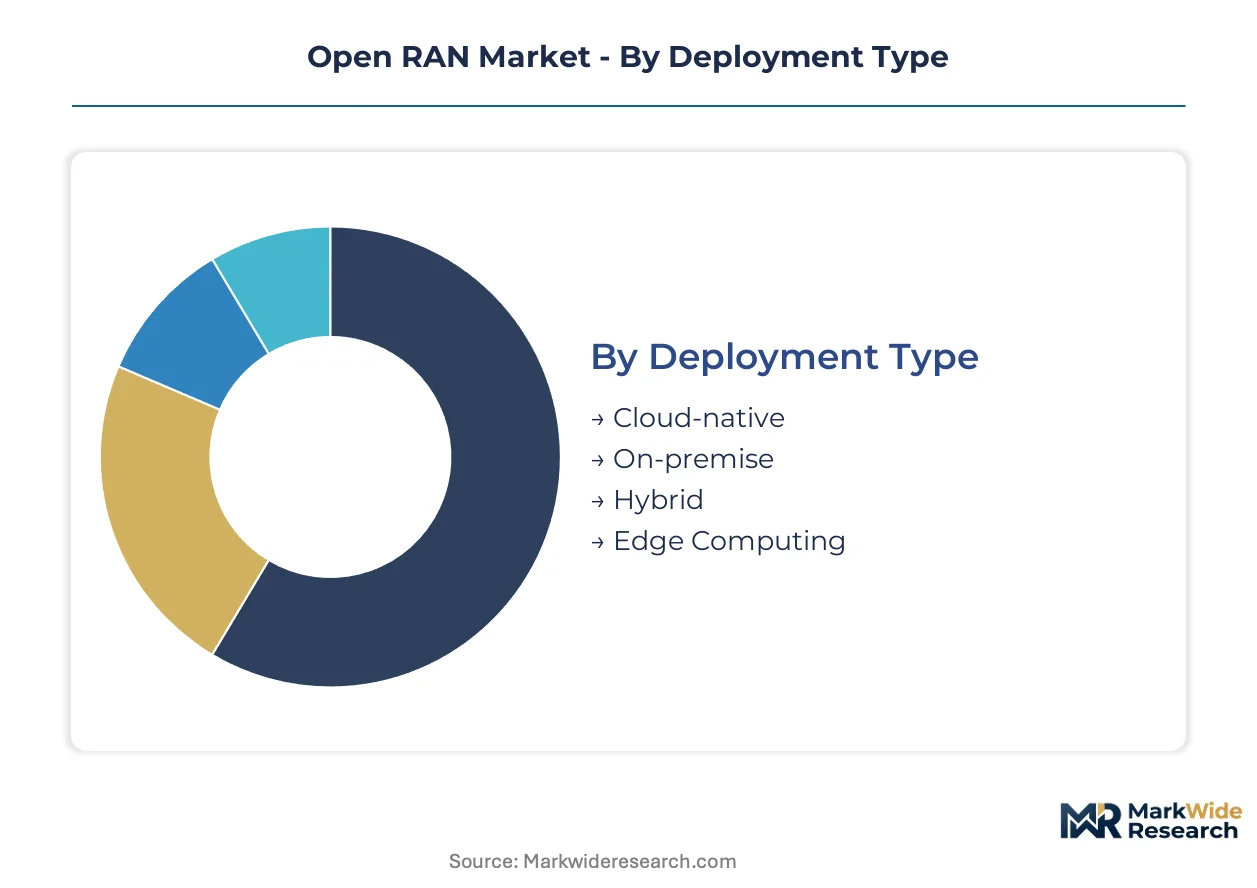
Segmentation in Open RAN reveals how disaggregation fractures traditional procurement patterns. Each dimension exposes different margin pools, integration risks, and vendor qualification barriers that reshape competitive positioning across deployment scenarios.
Deployment Type:
After-sales service intensity varies dramatically across deployment architectures, with cloud-native configurations demanding continuous platform engineering support while edge computing deployments require localized field maintenance networks.
- Cloud-native:Containerized microservices orchestrated through Kubernetes enable elastic scaling of RAN functions. Deutsche Telekom's campus network deployments in Germany are concentrating procurement here as industrial automation demands rapid capacity adjustments. The 7.2x split standardization allows disaggregated upgrades without hardware swaps.
- Edge Computing:Distributed processing nodes positioned at cell towers or aggregation points minimize latency for time-sensitive applications. Australian mining operations and port authorities are deploying standalone configurations for mission-critical communications beyond public network coverage, creating specialized integration service demand.
- Hybrid:Blends containerized and virtual machine workloads to balance operational stability against deployment flexibility.
- On-premise:Traditional bare-metal installations retain relevance for operators with existing data center investments and conservative migration timelines.
By volume, Radio Unit leads. By growth pace, Edge Computing is ahead.
Network Component:
Cost tier differentiation separates commodity hardware from software-defined value creation, with radio units competing on semiconductor scale while virtualized layers capture recurring license revenue.
- Radio Unit:Hardware transmitting and receiving radio frequency signals, encompassing massive MIMO arrays and mmWave modules. Samsung Electronics leverages semiconductor manufacturing scale to control production costs, though East Asian fabrication capacity constraints limit scalable supply for dense urban deployments.
- Distributed Unit:Real-time baseband processing functions handling layer 1 and layer 2 protocols with strict latency requirements. Germany's industrial automation sector is driving procurement concentration as manufacturing facilities require localized, low-latency connectivity that edge-distributed architectures deliver.
- Centralized Unit:Non-real-time processing and coordination functions consolidated in regional data centers.
- Virtualized RAN:Software-defined implementations of baseband functions decoupled from proprietary hardware.
By installed base, Radio Unit dominates. By expansion trajectory, Distributed Unit is climbing the fastest.
End User Type:
Customer type determines procurement sophistication, with mobile network operators managing multi-vendor complexity while enterprises demand single-accountability deployment partners.
- Mobile Network Operators:Tier-one carriers deploying disaggregated infrastructure across macro and small cell networks. Japanese operators are accelerating procurement under METI's Beyond 5G funding incentives, creating reference architectures for Southeast Asian export markets.
- Enterprises:Manufacturing conglomerates, mining groups, and logistics operators building private 5G networks. Germany's industrial sector is consolidating vendor relationships around systems integrators capable of delivering complete deployments rather than procuring disaggregated components separately.
- Governments:Public sector buyers prioritizing cybersecurity certification and supply chain integrity for critical infrastructure.
- Neutral Host:Third-party infrastructure providers serving multiple operators from shared radio access networks.
By contract value, Mobile Network Operators lead. By deal velocity, Enterprises is gaining share fastest.
Integration Level:
Margin structure correlates directly with integration depth, with full stack offerings capturing systems integration premiums while open source configurations commoditize hardware layers.
- Full Stack:Single-vendor or tightly integrated multi-vendor solutions with unified lifecycle management. Systems integrators are capturing margin pools that previously flowed to original equipment manufacturers, particularly in Germany's industrial automation sector where manufacturing conglomerates demand single-accountability partners.
- Open Source:Community-developed software components with commercial support overlays. The O-RAN Alliance's security specifications and FCC rip-and-replace mandates are tightening vendor eligibility criteria, creating qualification barriers that favor established contributors with certification resources.
- Proprietary:Vendor-locked implementations retaining traditional integrated RAN economics.
- Mixed:Hybrid configurations combining open interfaces with proprietary optimization layers.
By deployment count, Full Stack leads. By strategic interest, Open Source is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports Open RAN architectures to Southeast Asian operators seeking proven deployment models. German industrial automation clusters import distributed unit technologies for campus network integration. South Korean semiconductor fabrication supplies radio unit components to tier-one carriers across multiple continents.
United States
FCC rip-and-replace mandates compel operators to remove designated vendor equipment, generating immediate procurement of interoperable radio units and baseband software. The FCC's equipment authorization rules tighten vendor eligibility timelines for critical infrastructure contracts. Dense urban deployments in New York and Los Angeles concentrate multi-vendor integration activity as carriers accelerate macro site modernization.
Germany
Industrial automation facilities in the Ruhr region and Bavaria require localized low-latency connectivity that edge-distributed processing units deliver. The EU Cybersecurity Act imposes extended evaluation timelines that delay vendor qualification for national infrastructure contracts. Deutsche Telekom's campus network deployments in Baden-Württemberg create reference architectures for manufacturing conglomerates consolidating vendor relationships around single-accountability deployment partners.
Japan
METI's Beyond 5G funding incentives accelerate domestic vendor development for commercial Open RAN rollouts. The country's national telecommunications regulator enforces interoperability certification aligned with O-RAN Alliance specifications. Tokyo-based operators anchor early commercial deployments, creating exportable reference architectures for Southeast Asian markets seeking proven migration pathways.
South Korea
Tier-one carriers pilot hybrid containerized-virtual machine configurations for urban macro sites, compressing vendor lock-in durations. The national radio frequency regulator coordinates spectrum allocation for disaggregated network architectures. Seoul's metropolitan deployment clusters concentrate cloud-native R&D investment as operators seek elastic capacity scaling for dense population coverage.
Australia
Mining operations in Western Australia and port authorities deploy standalone Open RAN systems for mission-critical communications beyond public network coverage. The national critical infrastructure security framework mandates supply chain integrity assessments for network equipment procurement. Queensland's resource extraction corridors generate specialized integration service demand for edge computing configurations in remote operational environments.
Open RAN Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: established telecommunications infrastructure vendors with integrated hardware-software portfolios, cloud-native software specialists disaggregating traditional RAN stacks, and systems integrators capturing margin pools through complete deployment accountability. Dominant competitive moves include strategic partnerships between semiconductor fabricators and radio unit manufacturers, plus geographic expansion through reference architecture licensing to regional operators.
Within the established infrastructure tier, NEC Corporation and Fujitsu Limited represent Japanese vendors leveraging longstanding operator relationships to anchor commercial deployments. Samsung Electronics Co. Ltd. occupies a scale-driven position extending semiconductor manufacturing capabilities into radio unit production. Mavenir Systems, Inc. exemplifies the cloud-native software specialist archetype competing against hardware-centric incumbents through containerized baseband implementations.
| Leading Market Players |
|---|
| NEC Corporation |
| Mavenir Systems, Inc. |
| Ericsson |
| Airspan |
| Rakuten Symphony |
| Nokia Corporation |
| Fujitsu Limited |
| ZTE |
| Samsung Electronics Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Radio unit fabrication undercapacity in Taiwan and South Korea is compressing supplier margins while amplifying pricing power for qualified vendors serving FCC-mandated replacement cycles. This utilization squeeze propagates through multi-vendor deployment contracts, forcing systems integrators to absorb cost volatility or pass through semiconductor-linked surcharges to mobile network operators.
Pricing Analysis
Cloud-native 5G software commands premium subscription tiers against virtualized RAN legacy pricing and emerging edge-native configurations. Three-tier pricing structure across premium certification-grade, standard interoperability-compliant, and economy single-vendor tiers separates procurement based on O-RAN Alliance compliance depth. Pricing pressure stems from East Asian foundry bottlenecks constraining massive MIMO radio unit supply. Mobile network operators exhibit highest price sensitivity due to stranded asset risks from legacy RAN depreciation, while mining conglomerates in Australia accept premium pricing for mission-critical standalone deployments.
Supply Chain Analysis
Extended payment terms from Japanese operators are straining working capital for Korean radio unit fabricators and German systems integrators. Semiconductor supply concentrates in Taiwan, South Korea, and Japan, with advanced node fabrication feeding radio unit production and legacy processes supplying distributed unit processors. Gallium nitride substrates, FPGA chipsets, and precision RF filters constitute critical input dependencies. Single-source vulnerability in mmWave module assembly creates chokepoint exposure. Distribution runs through tier-one systems integrators consolidating procurement accountability for industrial campus deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN architecture substitution threatens incumbent integrated RAN vendors as disaggregation enables cloud-native software specialists to capture baseband processing value pools. Incumbents must navigate this technology transition without accelerating their own hardware revenue erosion.
For Market Incumbents: Pre-empt margin compression by anching full-stack integration partnerships with Japanese operators under METI's Beyond 5G funding umbrella. Certify proprietary optimization layers for O-RAN Alliance 7.2x split compliance to defend against containerized baseband substitutes. Capture systems integration premiums in Germany's industrial automation corridor before pure-play software vendors establish reference architectures.
For New Entrants and Emerging Players: Pursue white-space capture in Australian mining and port authority standalone deployments where incumbent presence remains thin. Target edge computing configurations for distributed unit procurement in resource extraction corridors demanding localized low-latency processing. Lead with AI-driven RAN intelligent controller offerings that compress vendor lock-in durations for operators seeking predictive maintenance capabilities.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native software specialists with demonstrated O-RAN Alliance certification velocity and established Kubernetes orchestration capabilities for containerized baseband functions. Long-term viability hinges on multi-vendor interoperability testing scale and recurring platform engineering revenue models. Watch for inflection signals in Southeast Asian operator procurement patterns as Japanese reference architectures achieve export adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| O-RAN Alliance Certification Investment | Accelerates vendor qualification timelines for FCC-mandated replacement procurement cycles. |
| Edge Computing Configuration Development | Captures latency-sensitive demand from German industrial automation campus networks. |
| AI-Driven RAN Intelligent Controller Launch | Enables predictive maintenance revenue streams for Australian mining standalone deployments. |
| Systems Integrator Partnership Formation | Consolidates single-accountability deployment relationships with manufacturing conglomerates. |
| Semiconductor Fabrication Scale-Up | Relieves massive MIMO radio unit supply constraints constraining dense urban rollouts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with mobile network operator procurement directors, systems integrator deployment leads, O-RAN Alliance technical committee members, and semiconductor fabrication supply managers; and secondary validation against FCC equipment authorization databases, METI funding disclosure filings, EU Cybersecurity Act certification registries, and O-RAN Alliance interoperability test reports. Bottom-up deployment volume estimates triangulated against top-down infrastructure spending projections.
Forecast inputs considered deployment type evolution, network component substitution elasticities, and end-user procurement sophistication across the projection horizon. Segmentation modeling incorporated cloud-native versus edge computing deployment architectures, radio unit versus distributed unit versus centralized unit component tiers, and mobile network operator versus enterprise versus government buyer categories. CAGRs derived from unit economics analysis of multi-vendor integration cost trajectories and semiconductor supply expansion scenarios.
Sensitivities concentrate around O-RAN Alliance testing lab capacity expansion, EU Cybersecurity Act evaluation timeline compression, and East Asian foundry utilization normalization. Forecasts reflect documented assumptions regarding interoperability certification velocity and operator migration pacing from pilot programs to multi-site rollouts. Macroeconomic contraction, regulatory fragmentation, or generative AI disruption of network optimization workflows would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Mobile Backhaul Market
Network Technology
Global Home Networking Device Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
DNS DHCP and IPAM Market
Network Technology
Mobile Network Optimization Market
Network Technology
Virtual Router Market
Network Technology
Data Center Switches Market
Network Technology
IT Connector Market
Network Technology
UK B2B Fixed Connectivity Market
Network Technology
Global Network Switches Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Global Wireless Router Market
Network Technology
Optical Networking Market
Network Technology
Gigabit Ethernet Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
Network Packet Broker Market