
 Database Management Platform Market | 2026-2036
Database Management Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Database Management Platform Market Analysis
The shortage of cloud-native database architects is unwinding legacy migration timelines for enterprises. Oracle sustains dominance in relational database installations across Fortune 500 accounts. Snowflake specializes in elastic data warehousing for multi-cloud environments. MongoDB anchors developer-led adoption through its document-oriented architecture and open-source community.
A database management platform is a software system that stores, retrieves, and manipulates structured and unstructured data through query languages such as SQL, NoSQL, or NewSQL protocols, serving as the foundational infrastructure for enterprise applications, analytics pipelines, and transactional systems. Relational databases still occupy the largest installed base but face margin compression from open-source alternatives, while NoSQL and NewSQL variants are capturing growth in real-time streaming and distributed computing workloads where horizontal scalability determines procurement decisions.
FDA guidelines on data integrity for pharmaceutical records, HIPAA security rules for protected health information, and GDPR cross-border transfer requirements in Europe are elevating encryption, audit logging, and residency controls to mandatory procurement criteria. The SEC's cybersecurity disclosure rules for publicly traded firms add another compliance layer for financial services deployments. Stakeholders must weigh sovereign data laws against cloud provider global footprints when architecting multi-region database strategies.
Market Dynamics
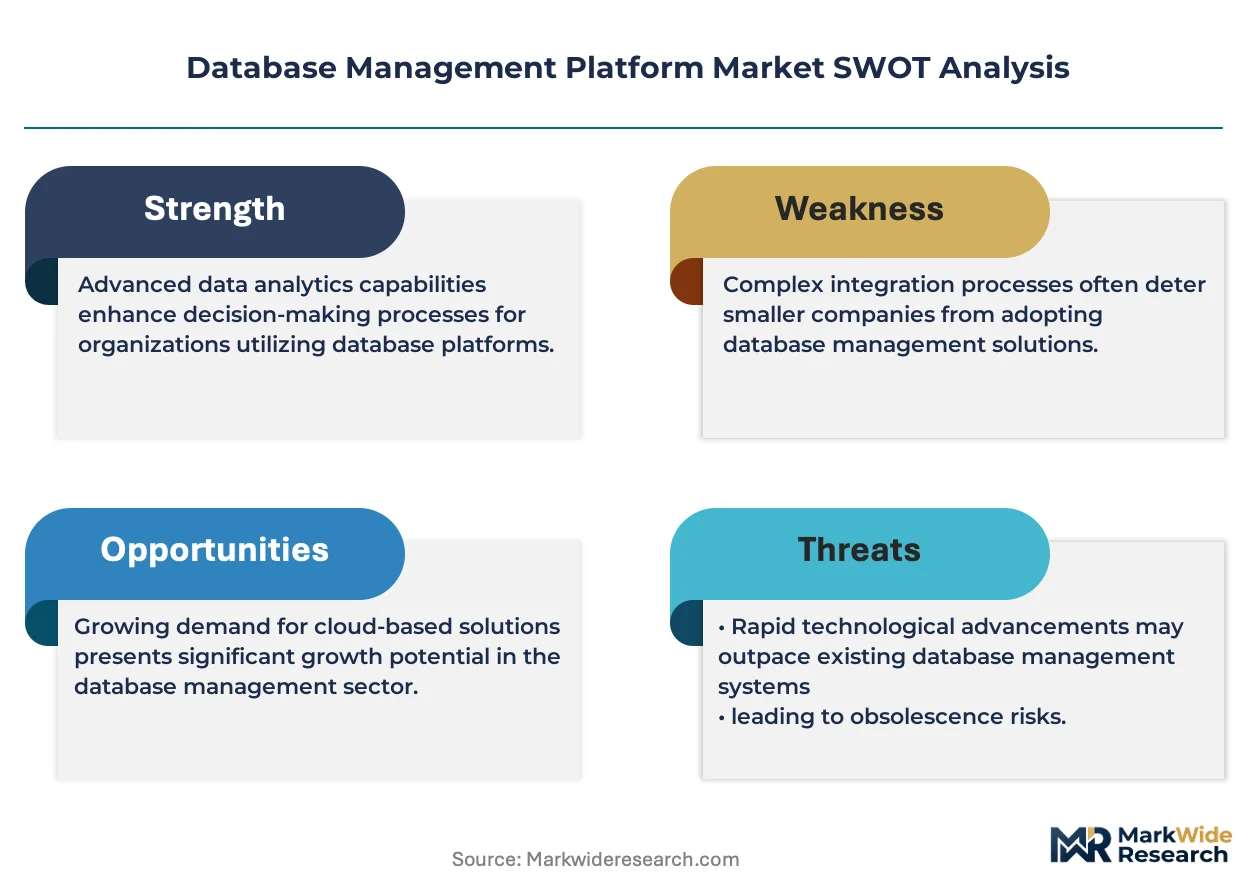
Cloud-native database architectures are forcing wholesale infrastructure replacement cycles as enterprises abandon on-premise relational systems for elastic, API-driven data services. This structural migration is compressing legacy vendor maintenance revenue while elevating consumption-based pricing models.
Growth Catalysts
- HIPAA security rule expansion:Healthcare providers in the United States are accelerating encrypted database deployments to satisfy breach notification mandates and audit trail requirements for protected health information.
- Real-time fraud detection:Financial services firms are procuring stream-processing database engines to handle sub-millisecond transaction validation across payment networks and digital asset exchanges.
- GDPR Article 44 compliance:European enterprises are investing in sovereign cloud database instances with residency controls to satisfy cross-border data transfer restrictions and avoid regulatory penalties.
Market Restraints
- Specialized talent scarcity:Cloud-native database architects command premium compensation, extending migration timelines and inflating professional services costs for enterprise implementations.
- Input cost concentration:Hyperscaler compute and storage pricing from Amazon Web Services, Microsoft Azure, and Google Cloud Platform creates vendor lock-in exposure and margin pressure for managed database providers.
- Latency constraints:Edge computing workloads in manufacturing and autonomous systems expose the physical limitations of centralized cloud database architectures, constraining certain real-time applications.
Strategic Opportunities
- India's data localization mandate:The country's central bank and telecommunications regulator are compelling foreign database providers to establish domestic infrastructure, creating captive demand for regional cloud partnerships.
- AI-ML inference integration:Convergence between vector databases and large language model pipelines is opening new revenue streams for platforms supporting embedding storage and semantic search.
- SEC cybersecurity disclosure:Publicly traded firms must now report material database breaches, expanding the addressable market for audit logging and governance automation tools.
Industry Challenges
- Schema migration complexity:Enterprises struggle to translate decades of stored procedures and trigger logic from Oracle and SQL Server into cloud-native equivalents without functional regression.
- Multi-cloud certification backlog:Database platforms seeking FedRAMP, ISO 27001, and SOC 2 Type II attestations face 12-18 month evaluation timelines that delay federal and enterprise procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Database Management Platform Market |
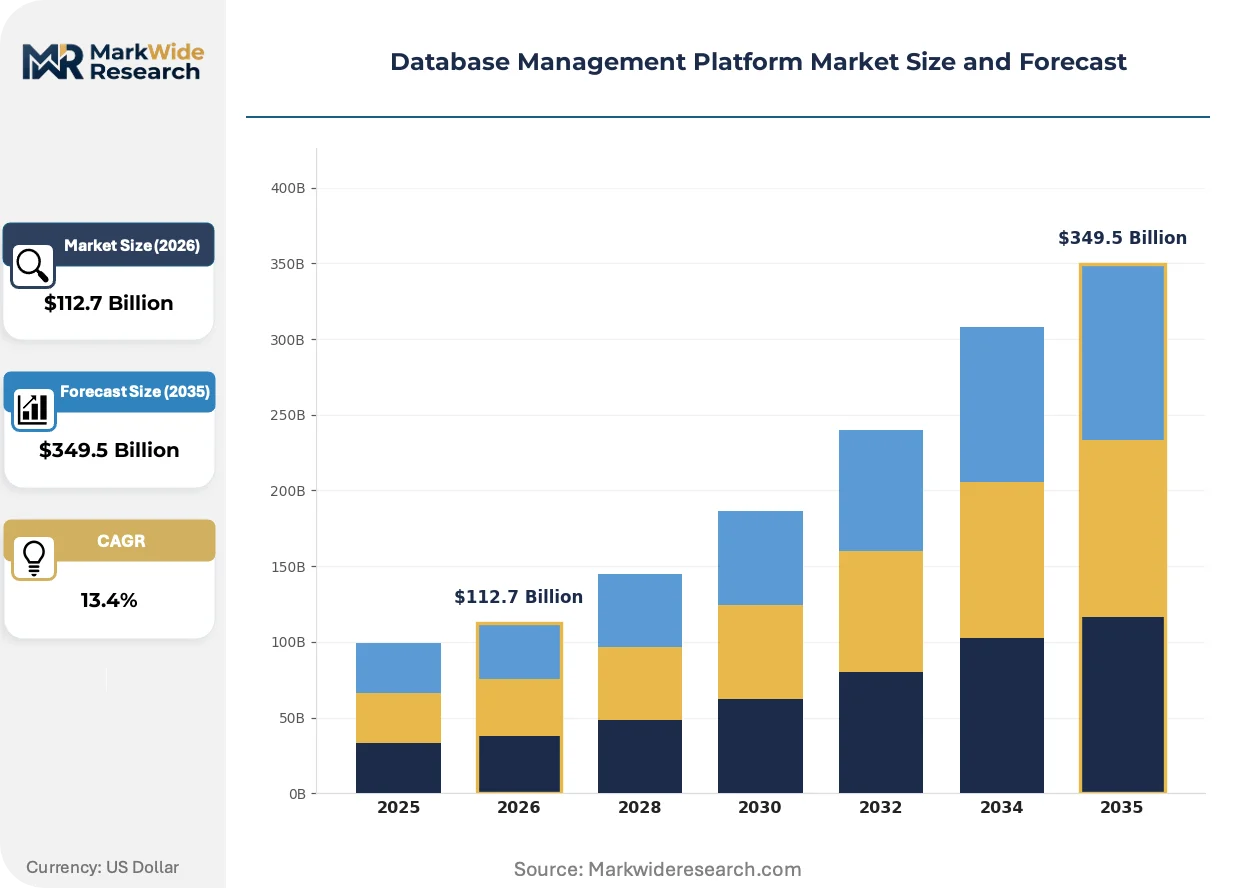
| Market Size in 2026 | $112.7 Billion |
| Market Size in 2035 | $349.5 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Relational Database, NoSQL Database, In-Memory Database, NewSQL Database Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Healthcare, Financial Services, Retail, Telecommunications Technology: Machine Learning, AI Integration, Data Analytics, Blockchain |
| Companies Covered | Oracle, Microsoft, AWS, Google Cloud, IBM, SAP, Snowflake, Databricks, MongoDB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Database Management Platform Market Emerging Trajectories
Serverless database provisioning is collapsing the traditional boundary between infrastructure and application layers, enabling developers to deploy data services without capacity planning. This operational model is reshaping how platforms compete on developer experience rather than raw performance benchmarks.
Vector database engines designed for embedding storage and similarity search are supplanting traditional keyword indexes in recommendation systems and retrieval-augmented generation pipelines. E-commerce platforms and enterprise software vendors are adopting these engines to power semantic product discovery and internal knowledge bases. The technology is compressing time-to-value for AI-enabled applications while demanding new skill sets from database administrators.
GDPR enforcement actions from CNIL in France and ICO in the United Kingdom are elevating data minimization and purpose limitation to core architectural requirements. Database platforms must now implement automated retention policies and granular access logging by default. Financial services and healthcare verticals in Europe are responding by procuring platforms with native privacy engineering capabilities rather than retrofitting compliance onto legacy systems.
Consumption-based pricing for database services is displacing perpetual licensing and fixed-capacity subscriptions across mid-market buyers. Value-added resellers and systems integrators are restructuring compensation models around usage growth rather than upfront license fees. This shift is most visible in North American SaaS companies and digital-native enterprises that prefer operational expenditure alignment with revenue scaling.
Database Management Platform Market Segmentation
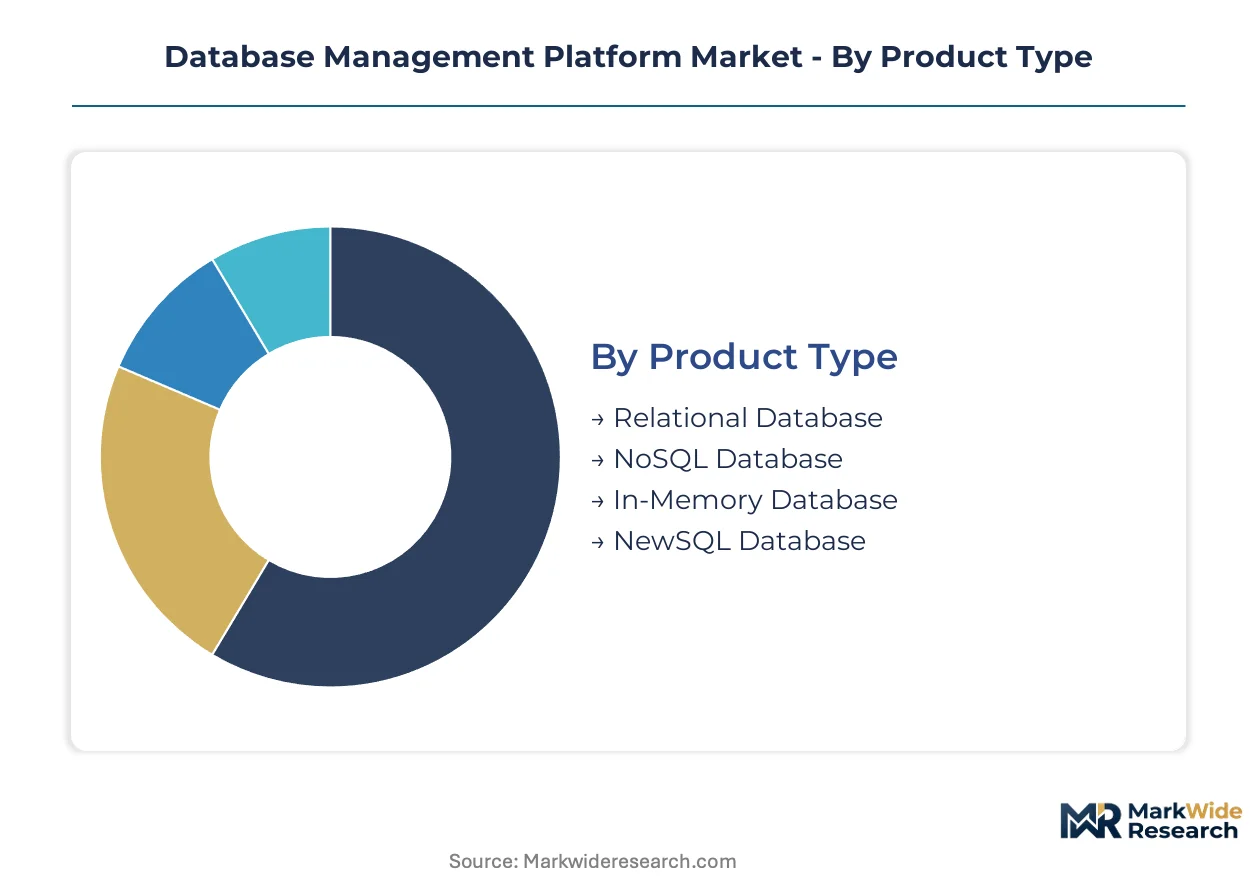
Database management platforms fragment across four structural dimensions that reshape procurement criteria and vendor positioning. Product architecture determines scalability ceilings and migration complexity. Deployment economics separate capital-intensive incumbents from consumption-based challengers.
Product Type:
Margin pools concentrate in relational database maintenance contracts and NoSQL expansion licenses, with in-memory and NewSQL variants capturing premium pricing for latency-sensitive workloads.
- Relational Database:Structured data organized in tables with ACID compliance and SQL query interfaces. Financial services firms in the United States and Germany sustain demand for Oracle and SQL Server installations despite cloud migration pressure. Legacy stored procedures and trigger logic create switching costs that defend incumbent margins.
- NoSQL Database:Schema-flexible architectures using document, key-value, wide-column, or graph models for distributed data. Developer-led adoption in California and Bangalore favors MongoDB and Cassandra for real-time applications where horizontal scaling trumps transactional consistency.
- In-Memory Database:Volatile storage engines optimized for sub-millisecond response times.
- NewSQL Database:Distributed SQL implementations combining transactional guarantees with horizontal elasticity.
Relational Database holds installed capacity. NoSQL Database is rotating up the share rankings.
Deployment Model:
Cloud-Based deployments concentrate revenue growth, while On-Premises and Hybrid configurations retain margin in regulated verticals with data residency constraints.
- Cloud-Based:Fully managed database services with API provisioning and consumption billing. Enterprises in Texas and New York accelerate adoption to align operational expenditure with revenue scaling. GDPR Article 44 compliance requirements in France and Germany drive sovereign cloud instance procurement.
- Hybrid:Split workloads across on-premise and cloud infrastructure with unified management planes. Healthcare providers under HIPAA security rules maintain sensitive patient data on-premise while bursting analytics to cloud environments.
- On-Premises:Self-managed infrastructure with perpetual licensing.
- Managed Services:Third-party operational support for database administration.
On-Premises retains the largest footprint. Cloud-Based is climbing the fastest.
End User:
Financial Services and Healthcare verticals command premium pricing due to compliance complexity, while Retail and Telecommunications drive volume through scale deployments.
- Financial Services:Real-time transaction processing, fraud detection, and regulatory reporting. Banks and payment networks in New York and London procure stream-processing engines for sub-millisecond validation. SEC cybersecurity disclosure rules expand audit logging requirements.
- Healthcare:Electronic health records, clinical analytics, and patient data management. Hospital systems across the United States deploy encrypted databases to satisfy HIPAA breach notification mandates and audit trail specifications.
- Retail:Customer data platforms and inventory optimization.
- Telecommunications:Network performance monitoring and subscriber data management.
Financial Services commands pricing power. Healthcare is gaining share fastest.
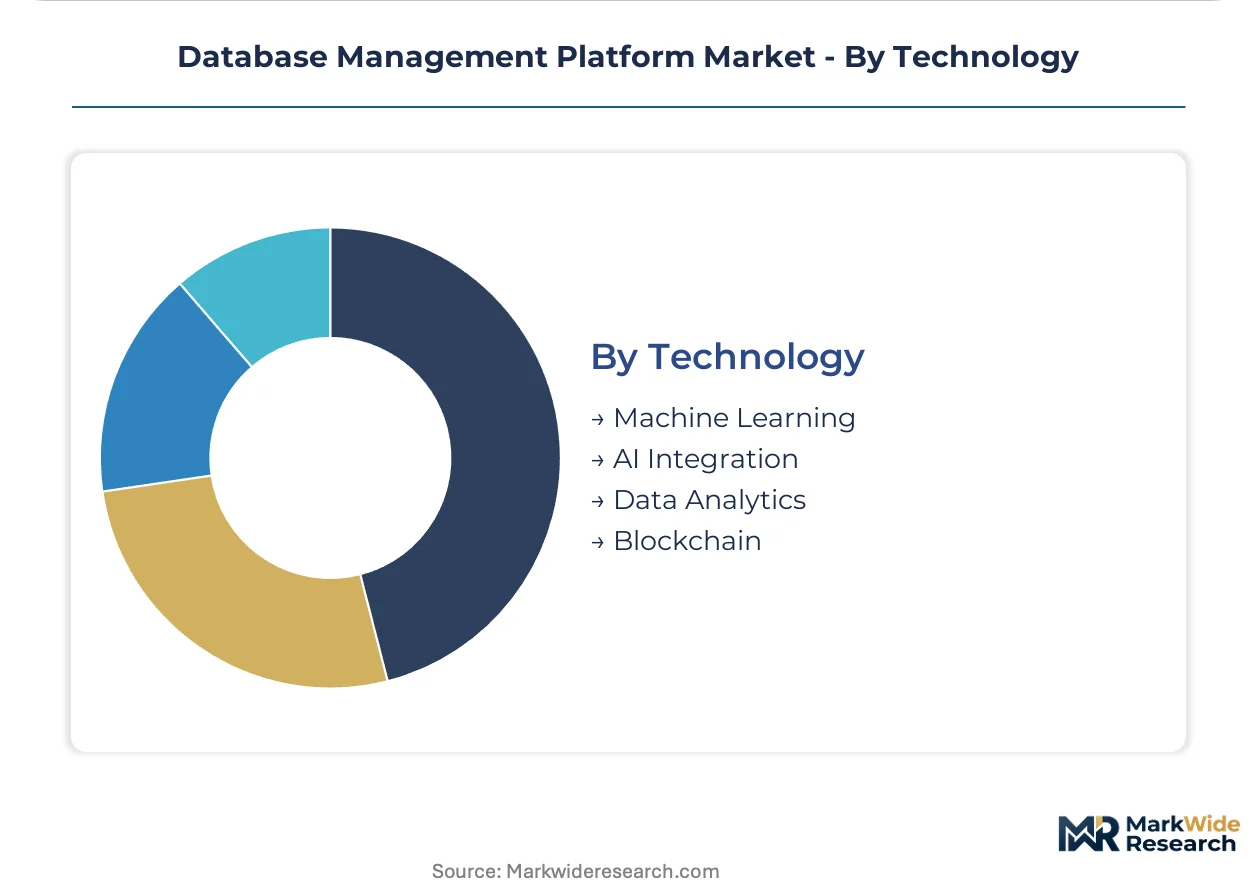
Technology:
AI Integration and Data Analytics concentrate venture funding and platform R&D, while Machine Learning and Blockchain attach as modular capabilities.
- AI Integration:Native vector storage, embedding pipelines, and semantic search for large language model applications. E-commerce platforms in California and enterprise software vendors adopt these engines for product discovery and internal knowledge bases.
- Data Analytics:Query optimization, columnar storage, and massively parallel processing for business intelligence workloads. Snowflake and Databricks capture growth in multi-cloud data warehousing across North American SaaS companies.
- Machine Learning:Automated query tuning and anomaly detection.
- Blockchain:Immutable audit trails and decentralized consensus mechanisms.
Data Analytics anchors current spending. AI Integration shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Financial services firms in the United States prioritize real-time fraud detection engines, while European enterprises emphasize sovereign data residency. Asian markets concentrate investment in elastic data warehousing for digital commerce platforms.
United States
Financial services and healthcare verticals dominate procurement. HIPAA security rule expansion compels hospital systems to deploy encrypted databases with comprehensive audit trails. Enterprise clusters in New York and California accelerate cloud-native migrations to satisfy SEC cybersecurity disclosure mandates for publicly traded firms.
Germany
Industrial manufacturing and automotive sectors anchor relational database maintenance contracts. GDPR Article 44 cross-border transfer restrictions elevate sovereign cloud instance demand. The Frankfurt Rhine-Main metropolitan region concentrates procurement of compliance-engineered platforms with automated retention policies.
India
Digital-native enterprises and fintech startups drive NoSQL adoption for horizontal scaling. RBI data localization mandates compel foreign providers to establish domestic infrastructure. Bangalore and Mumbai emerge as captive demand centers for regional cloud partnerships serving banking and telecommunications verticals.
United Kingdom
Financial services in London procure stream-processing engines for sub-millisecond transaction validation. ICO enforcement actions elevate data minimization to core architectural requirements. The capital's enterprise software vendors integrate vector databases for semantic search in AI-enabled applications.
Japan
Manufacturing and telecommunications sectors sustain demand for high-availability transactional systems. METI guidelines on data governance influence procurement criteria for multi-region architectures. Tokyo and Osaka clusters prioritize hybrid deployments balancing on-premise latency with cloud analytics elasticity.
Database Management Platform Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier combines hyperscale cloud infrastructure with managed database services, while specialists concentrate on document-oriented, vector, or stream-processing engines. Three archetypes dominate: relational incumbents defending maintenance revenue, cloud-native challengers capturing consumption-based growth, and open-source community platforms driving developer-led adoption. Competitive moves center on strategic partnerships with AI/ML pipeline providers and geographic expansion through sovereign cloud certifications.
Within the cloud-native challenger tier, Snowflake and Databricks exemplify the elastic data warehousing archetype for multi-cloud environments. MongoDB occupies a distinct position anchoring developer-led adoption through document-oriented architecture. Oracle represents the relational incumbent archetype sustaining dominance across Fortune 500 maintenance contracts despite migration pressure.
| Leading Market Players |
|---|
| Oracle |
| Microsoft |
| AWS |
| Google Cloud |
| IBM |
| SAP |
| Snowflake |
| Databricks |
| MongoDB |
| Others |
Supply Flow & Price Mechanics
Capacity reservation contracts with hyperscalers lock in compute access and price visibility for managed database providers navigating AWS, Azure, and GCP input cost concentration. These arrangements tether margin stability to multi-year infrastructure commitments while exposing providers to utilization risk if consumption patterns diverge from projections.
Pricing Analysis
Consumption-based billing dominates cloud-native deployments, with three-tier pricing structure across premium enterprise, standard professional, and economy developer levels differentiating by compliance certification and support SLAs. Price differentiation hinges on FedRAMP authorization tier and geographic data residency controls. Cost compression in mid-market SaaS tiers is intensifying because open-source alternatives erode relational database maintenance premiums. Digital-native startups exhibit highest price sensitivity; Fortune 500 financial services firms prioritize audit-grade security over per-unit cost.
Supply Chain Analysis
Just-in-time provisioning preferences among cloud-native enterprises contrast with strategic stockpiling of on-premise hardware by healthcare providers under HIPAA breach notification mandates. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States; flash storage production anchors in China, Japan, and South Korea. Supply chain risk centers on single-source vulnerability for advanced node processors. Distribution runs through hyperscaler marketplaces and value-added reseller networks serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Database management platforms constitute a defensive-moat market where switching costs from stored procedure logic and schema dependencies protect incumbent positions against cloud-native challengers.
For Market Incumbents: Consolidate maintenance revenue through extended support contracts for Oracle and SQL Server installations while accelerating sovereign cloud certifications for GDPR Article 44 compliance in France and Germany. Acquire vector database specialists to anchor AI-ML inference capabilities before open-source alternatives commoditize embedding storage. Threat substitution from Snowflake and Databricks consumption models demands defensive API compatibility layers. For New Entrants and Emerging Players: Anchor in India's data localization mandate by establishing domestic infrastructure partnerships with Mumbai and Bangalore cloud regions before foreign hyperscalers complete RBI-compliant deployments. Target healthcare mid-market buyers in Texas and Florida where HIPAA security rule expansion creates procurement urgency for encrypted database alternatives lacking legacy migration complexity. Go-to-market through channel partners with existing EHR integration expertise. For Investors and Strategic Acquirers: Cloud-native challengers with FedRAMP authorization backlog clearance represent prime acquisition targets as federal procurement windows open. Long-term viability rests on differentiation durability against hyperscaler managed service bundling. Signal to watch is sovereign cloud certification velocity in India and Germany as geographic moat construction indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Unlocks GDPR Article 44 procurement in France, Germany, and Netherlands enterprise accounts. |
| Vector Database Integration | Captures AI-ML inference workloads from Databricks and Snowflake expansion into semantic search. |
| HIPAA-Compliant Managed Service | Addresses breach notification mandate urgency among United States hospital systems. |
| Open Source Community Cultivation | Replicates MongoDB developer-led adoption model for document-oriented architectures. |
| Hyperscaler Marketplace Listing | Reduces customer acquisition friction through AWS, Azure, and GCP consumption billing integration. |
Methodological Framework
Two parallel data streams informed the analysis: structured conversations with CTOs, cloud architects, healthcare CIOs, and financial services database administrators; and secondary validation through SEC cybersecurity disclosures, hyperscaler capex reports, GDPR enforcement actions from CNIL and ICO, and hospital procurement databases. Bottom-up sizing of cloud-native deployments triangulated against top-down relational maintenance contract value estimates.
Across the analysis window, forecasts modeled deployment model, organization size, vertical compliance complexity, and regional data sovereignty requirements. CAGRs derived from elasticity coefficients linking cloud consumption growth to enterprise digital transformation spending. Industry-specific inputs included HIPAA audit frequency trends and RBI data localization implementation timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained hyperscaler pricing power and stable regulatory enforcement intensity; material deviation would warrant model refresh. Revision becomes warranted when sovereign cloud certification backlogs clear or vector database commoditization accelerates beyond projected rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Marketing Automation Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Electrical Digital Twins Market
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Global Cloud POS Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market
Digital Solutions
Personality Assessment Solutions Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Change Management Software Market
Digital Solutions
Location Targeted Mobile Advertising Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Warehouse Digital Twin Simulation and Optimization Market
Digital Solutions
Business As a Service Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Utility Bill Management System Market