
 E-Clinical Solution Software Market | 2026-2036
E-Clinical Solution Software Market Size, Share, and Industry Trends Forecast 2026-2036
E-Clinical Solution Software Market Analysis
Platform licensing revenue is tilting from perpetual on-premises contracts toward recurring cloud subscriptions across the E-Clinical Solution Software landscape. Veeva Systems leverages its native cloud architecture to capture recurring revenue from large pharmaceutical sponsors. Oracle Corporation anchors its position through deep integration with enterprise resource planning stacks that sponsors already operate. IQVIA competes by embedding real-world data assets directly into trial planning workflows, creating differentiated value beyond pure software licensing.
E-Clinical Solution Software comprises integrated digital platforms that manage clinical trial design, patient recruitment, electronic data capture, regulatory submission, and post-market surveillance through standardized data formats such as CDISC SDTM and CDASH. These systems automate protocol compliance, adverse event reporting, and audit trail generation to accelerate regulatory approval timelines for investigational therapies. Cloud-based deployment now leads among new implementations, while Artificial Intelligence and Machine Learning segments represent the fastest-growing technology layer as sponsors deploy predictive analytics for patient enrollment forecasting and risk-based monitoring. Electronic Health Records integration remains mature with slower growth but occupies stable margin pools through long-term hospital system contracts.
FDA 21 CFR Part 11 in the United States and EMA Good Clinical Practice guidelines in Europe mandate electronic signature validity, data integrity controls, and complete audit trails, which shape vendor product roadmaps and create compliance-driven switching costs for established sponsors. ISO 14155 and ICH E6(R2) standards further constrain system design by requiring risk-proportionate quality management across trial documentation. Sponsors must monitor how FDA digital health guidance and EU AI Act risk classifications will reshape validation requirements for algorithmic features embedded in clinical software.
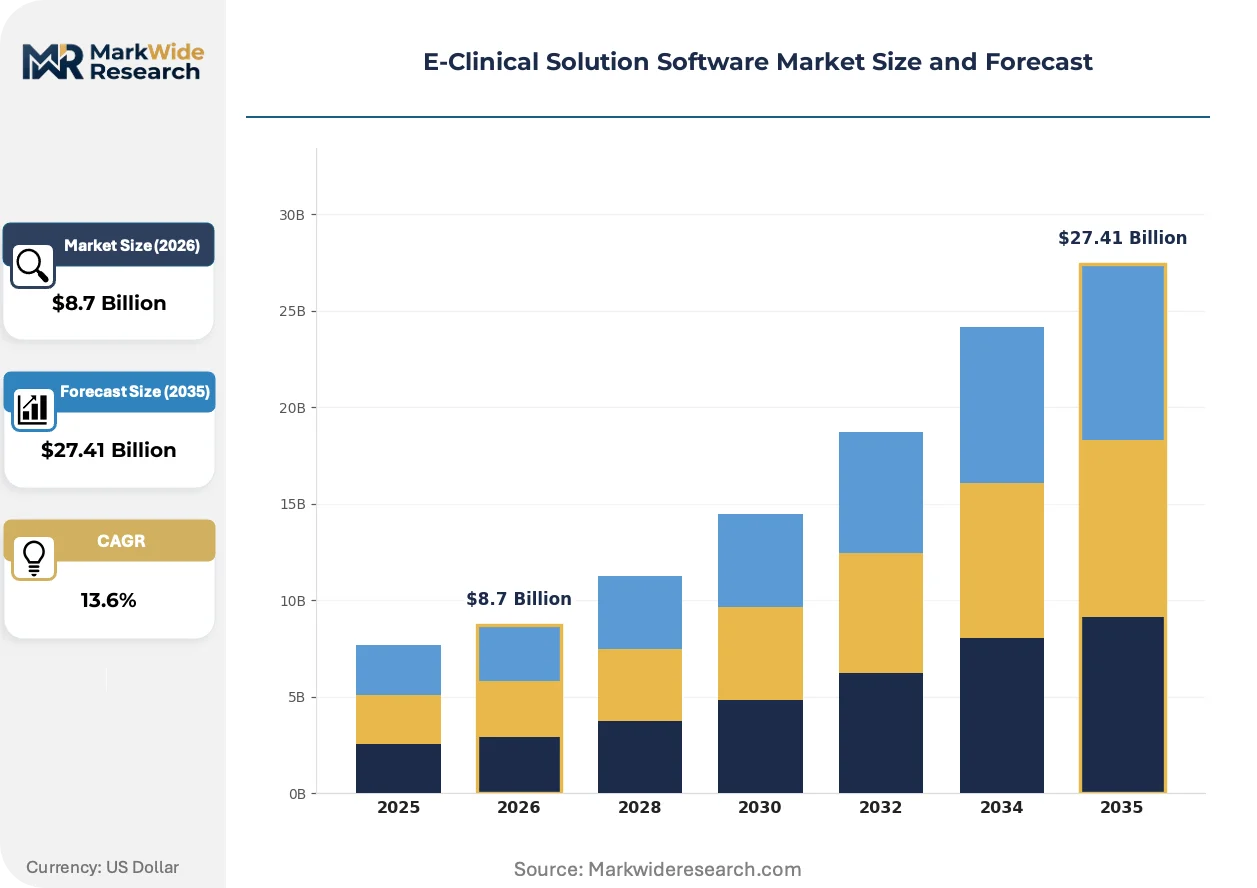
Market Dynamics
Cloud-native architectures are compressing deployment cycles and forcing legacy on-premise vendors to rebuild their stacks, while FDA 21 CFR Part 11 validation requirements lock sponsors into compliant platforms and create steep switching costs that protect incumbent positions.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature and audit trail mandates in the United States compel pharmaceutical sponsors to replace paper-based systems with validated electronic platforms, creating compliance-driven replacement cycles.
- Artificial Intelligence integration:Machine learning algorithms for patient enrollment forecasting and risk-based monitoring are expanding software utility beyond data capture into predictive trial management.
- Contract Research Organizations:CROs managing multi-site trials across dispersed geographies require centralized cloud platforms for real-time protocol coordination and data harmonization.
Market Restraints
- Validation cost structure:FDA-compliant software validation requires extensive documentation, IQ/OQ/PQ protocols, and third-party audit expenses that disproportionately burden mid-tier sponsors.
- Technical debt in legacy integration:Established pharmaceutical sponsors operate entrenched enterprise resource planning stacks that resist seamless API connectivity with modern e-clinical platforms.
- Substitution from open-source frameworks:Academic medical centers and government-funded trials increasingly deploy non-commercial CDISC-compliant tools for basic electronic data capture functions.
Strategic Opportunities
- EU AI Act risk classification:Algorithmic clinical trial features face emerging validation requirements in Europe, creating first-mover advantage for vendors pre-building explainable AI documentation frameworks.
- Decentralized trial models:Direct-to-patient data capture through wearable devices and telemedicine platforms opens new software categories for remote monitoring and electronic patient-reported outcomes.
- Real-world evidence convergence:Integration of electronic health records with trial databases enables post-market surveillance extensions that stretch software contracts beyond study completion.
Industry Challenges
- CDISC standardization complexity:Mapping diverse data sources to SDTM and CDASH formats requires specialized biostatistical expertise that vendors struggle to staff at scale.
- Multi-tenant security architecture:Cloud platforms serving competing pharmaceutical sponsors must demonstrate data isolation and access controls that satisfy sponsor information security audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Clinical Solution Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Trial Management, E-Consent, Data Management, Electronic Health Records End User: Pharmaceutical Companies, Biotech Firms, Contract Research Organizations, Academic Institutions Deployment: Cloud-based, On-premises, Hybrid, Mobile Applications Technology: Artificial Intelligence, Machine Learning, Blockchain, Data Analytics |
| Companies Covered | Veeva Systems, Oracle Corporation, IQVIA, Medidata Solutions, Parexel International Corporation, Clario, Signant Health, eClinical Solutions LLC, Anju Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Clinical Solution Software Market Emerging Trajectories
Artificial intelligence is penetrating trial execution workflows, regulatory frameworks are hardening around algorithmic decision-making, and procurement patterns are tilting toward outcome-contingent contracting models that tie vendor fees to enrollment milestones.
Generative AI for protocol drafting and regulatory submission authoring is rendering obsolete manual document preparation by medical writers and biostatisticians. Large pharmaceutical sponsors are piloting natural language processing tools for informed consent generation and case report form design. This compression of document development timelines is collapsing traditional service-based revenue models for clinical research consultants.
EMA Good Clinical Practice guidelines and the EU AI Act are jointly constraining how algorithmic patient screening and risk prediction tools deploy across European trials. Vendors must now document training data provenance, model performance metrics, and human oversight protocols to satisfy dual regulatory scrutiny. Mid-sized sponsors without dedicated regulatory technology teams are delaying AI feature adoption until compliance templates mature.
Subscription pricing tied to patient enrollment velocity is displacing fixed per-study licensing across sponsor-vendor negotiations. Large CROs and pharmaceutical companies are demanding usage-based models that align software costs with actual trial progression rather than protocol initiation. This shift is most visible in North American Phase II and III oncology trials where enrollment volatility creates demand for cost flexibility.
E-Clinical Solution Software Market Segmentation
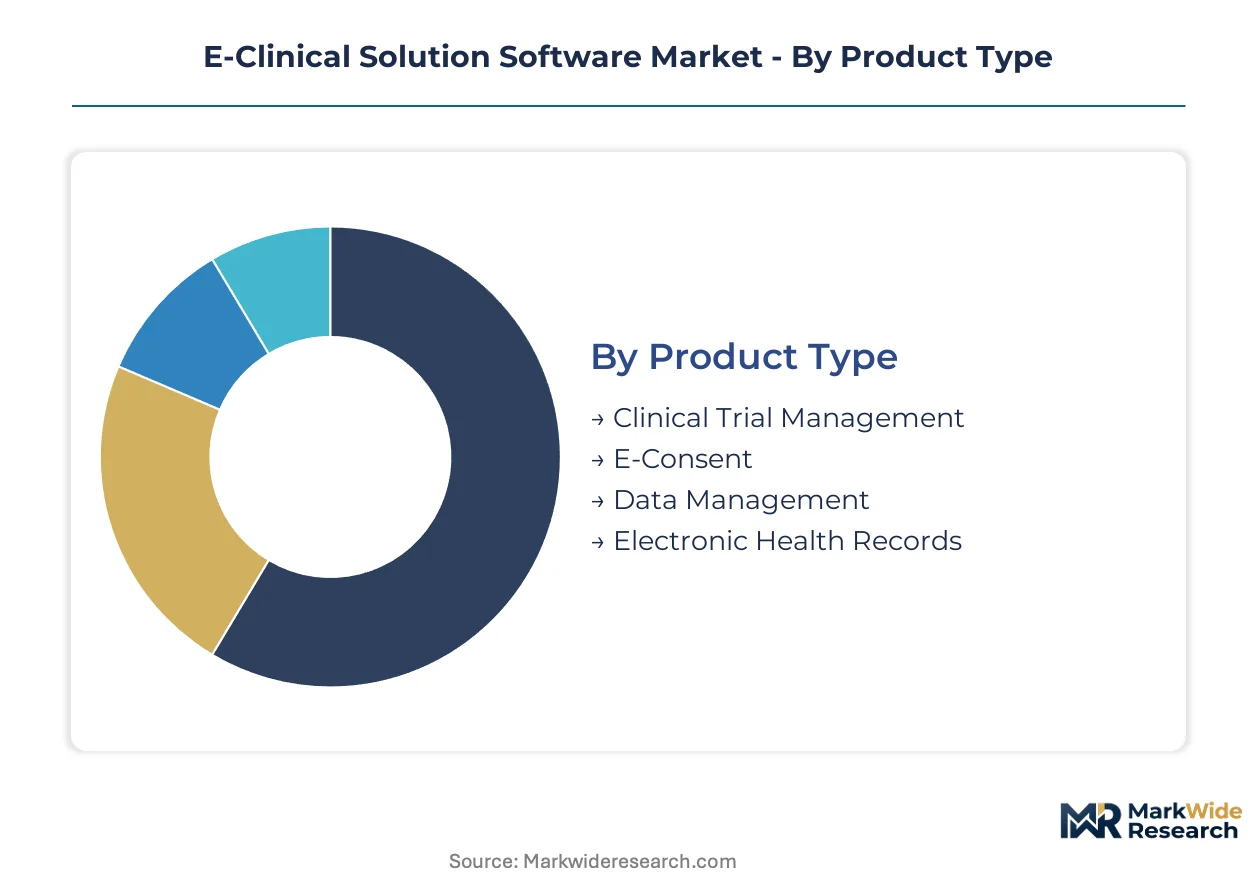
E-Clinical solution software segments diverge sharply by compliance burden, integration complexity, and customer procurement maturity. Sponsors select platforms based on trial phase, therapeutic area data density, and existing enterprise architecture commitments.
Product Type:
Application focus determines functional depth, regulatory validation requirements, and contract renewal patterns across the software stack.
- Clinical Trial Management:Centralized platforms orchestrate protocol design, site monitoring, and regulatory submission timelines through workflow automation. Large pharmaceutical sponsors in the United States concentrate procurement here, driven by FDA 21 CFR Part 11 audit trail mandates and multi-site coordination complexity.
- Data Management:Electronic data capture systems with CDISC SDTM mapping capabilities dominate mid-market budgets. Contract Research Organizations across dispersed geographies require these platforms for real-time query resolution and database lock acceleration.
- E-Consent:Digital informed consent modules with multimedia patient education reduce protocol deviation rates.
- Electronic Health Records:Hospital-anchored systems with long-term service contracts occupy stable margin pools through enterprise IT integration.
Clinical Trial Management holds installed capacity. Data Management is rotating up the share rankings.
End User:
Customer type shapes pricing power, implementation speed, and feature customization demands.
- Pharmaceutical Companies:Large sponsors demand validated enterprise deployments with dedicated customer success teams and custom API development. United States-based firms anchor procurement volume, compelled by FDA inspection readiness requirements and portfolio-scale standardization.
- Contract Research Organizations:Multi-tenant platform requirements dominate CRO procurement, with real-time dashboards for sponsor visibility and cross-study resource allocation. These customers prioritize rapid study startup and global site onboarding velocity.
- Biotech Firms:Venture-funded developers favor subscription elasticity and rapid deployment without capital expenditure.
- Academic Institutions:Grant-funded researchers deploy open-source alternatives for basic electronic data capture.
Pharmaceutical Companies command pricing premiums. Contract Research Organizations are expanding seat counts fastest.
Deployment:
Infrastructure choice reflects data sovereignty requirements, IT governance maturity, and total cost of ownership calculations.
- Cloud-based:Native SaaS architectures with automatic validation documentation and elastic compute scaling capture new implementation majority. United States sponsors lead adoption, leveraging AWS and Azure compliance certifications for FDA audit defense.
- Hybrid:Split configurations with sensitive patient data on-premises and analytics workloads in cloud environments address European data residency constraints. German and French sponsors concentrate here, navigating GDPR clinical data processing requirements.
- On-premises:Legacy validated environments persist at established sponsors with sunk infrastructure investments.
- Mobile Applications:Patient-facing data capture tools for decentralized trials and electronic patient-reported outcomes.
Cloud-based deployment captures new logo growth. Hybrid is climbing the fastest among replacement cycles.
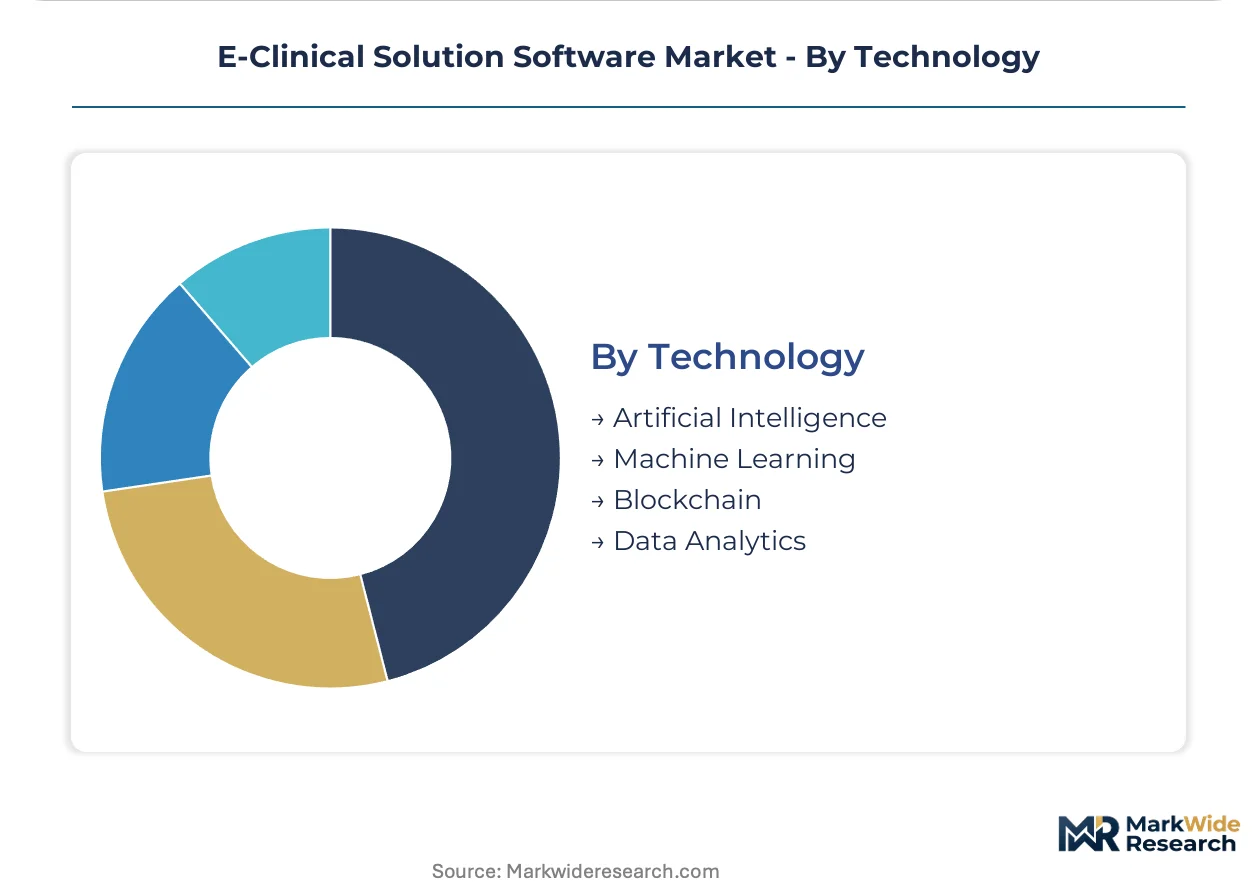
Technology:
Capability layer determines competitive differentiation, development cost structure, and regulatory scrutiny intensity.
- Artificial Intelligence:Predictive algorithms for patient enrollment forecasting, site selection optimization, and risk-based monitoring signal detection. United States sponsors pilot these capabilities under FDA digital health guidance, while European deployments face emerging EU AI Act documentation requirements.
- Machine Learning:Supervised learning models trained on historical trial data automate query generation and data quality flagging. Large CROs embed these tools to compress database lock timelines and reduce manual biostatistical review.
- Data Analytics:Descriptive and diagnostic dashboards for operational KPIs and regulatory submission preparation.
- Blockchain:Distributed ledger pilots for consent audit trails and clinical data provenance tracking.
Artificial Intelligence attracts development investment. Machine Learning is gaining share fastest in commercial deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development for clinical trials concentrates heavily in the United States, with secondary engineering hubs in Germany and the United Kingdom supporting European regulatory compliance. Cloud infrastructure investments by major sponsors are expanding validated data center footprints across Switzerland and Singapore to address data residency requirements.
United States
FDA 21 CFR Part 11 mandates and Phase III trial density drive enterprise procurement of validated electronic platforms. Large pharmaceutical sponsors in Massachusetts and New Jersey anchor demand for audit-trail-compliant systems. The Boston-Cambridge biotech corridor generates concentrated demand for cloud-native trial management deployments.
Germany
EMA Good Clinical Practice alignment and GDPR clinical data processing requirements shape vendor selection criteria. Munich and Frankfurt host major pharmaceutical headquarters demanding hybrid cloud configurations. German sponsors prioritize on-premises data sovereignty for sensitive patient records alongside cloud analytics workloads.
United Kingdom
MHRA post-Brexit regulatory autonomy and NHS digital transformation programs accelerate e-clinical adoption. London and the Golden Triangle research cluster concentrate biotech software procurement. UK-based Contract Research Organizations expand multi-tenant platform deployments for global sponsor visibility.
Switzerland
Swissmedic validation requirements and pharmaceutical headquarters density support premium software licensing. Basel and Zurich anchor European operations for major vendors seeking regulatory credibility. Swiss sponsors demand extensive IQ/OQ/PQ documentation for algorithmic trial features.
India
CDSCO digital health initiatives and CRO cost arbitrage drive adoption of cloud-based data management platforms. Hyderabad and Bangalore emerge as delivery centers for global trial coordination services. Indian CROs deploy electronic data capture systems for multinational sponsor contracts.
E-Clinical Solution Software Market Vendor Landscape
Cloud-native specialists and enterprise software incumbents split the market into distinct competitive spheres. Consolidation pressure favors vendors with validated regulatory documentation and multi-tenant security architectures. Three archetypes dominate: vertical SaaS platforms with native compliance, diversified technology conglomerates with ERP integration, and data-centric service providers embedding real-world evidence. Competitive moves center on AI feature differentiation and subscription pricing models tied to enrollment milestones.
Within the vertical SaaS tier, Veeva Systems exemplifies cloud-native architecture designed for life sciences compliance from inception. Oracle Corporation occupies a position as the enterprise integration anchor, leveraging database and ERP relationships with established pharmaceutical sponsors. IQVIA represents the convergence of software licensing with proprietary clinical data assets, creating differentiated trial planning workflows beyond pure technology provision.
| Leading Market Players |
|---|
| Veeva Systems |
| Oracle Corporation |
| IQVIA |
| Medidata Solutions |
| Parexel International Corporation |
| Clario |
| Signant Health |
| eClinical Solutions LLC |
| Anju Software |
| Others |
Supply Flow & Price Mechanics
Overcapacity in cloud infrastructure across the United States is compressing margins for SaaS vendors while simultaneously accelerating sponsor migration from on-premise legacy systems, creating a feedback loop where utilization signals dictate both supplier investment discipline and buyer negotiating leverage.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across the E-Clinical Solution Software landscape by imposing validation documentation burdens that stratify offerings. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade platforms with dedicated compliance teams from mid-market SaaS bundles and open-source alternatives. Price differentiation rests on certification depth and integration complexity rather than raw feature count. Cost compression in the mid-market tier is intensifying because CROs demand usage-based models tied to enrollment velocity. Academic institutions and grant-funded researchers exhibit the highest price sensitivity, while large pharmaceutical sponsors in Massachusetts and New Jersey accept premium pricing for audit-trail guarantees.
Supply Chain Analysis
Amazon Web Services, Microsoft Azure, and Google Cloud Platform hold the dominant capacity positions for validated clinical data hosting, with specialized health cloud providers occupying niche compliance tiers. Engineering talent concentrates in the United States, Germany, and the United Kingdom, where regulatory expertise and CDISC standardization knowledge cluster around pharmaceutical headquarters and CRO delivery centers. Raw material dependencies include specialized biostatistical labor, cybersecurity certification frameworks, and proprietary real-world data assets. Single-source vulnerability runs through concentrated cloud infrastructure regions, where AWS us-east-1 outages could disrupt multi-site trial coordination. Distribution runs through direct enterprise sales teams for large sponsors and channel partnerships with CROs for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source CDISC-compliant frameworks and non-commercial electronic data capture tools pose a credible substitution threat to incumbent vendors, particularly among academic medical centers and government-funded trials where budget constraints override compliance premium tolerance.
For Market Incumbents: Harden multi-tenant security architectures to demonstrate data isolation capabilities that satisfy sponsor information security audits, while deepening real-world evidence integration to stretch contract durations beyond study completion. Vertical integration into proprietary clinical data assets creates switching costs that offset open-source substitution pressure. FDA digital health guidance evolution represents the critical regulatory threat requiring pre-built explainable AI documentation frameworks. For New Entrants and Emerging Players: Mid-tier biotech firms in the Boston-Cambridge corridor represent the most penetrable entry point, as these venture-funded developers prioritize subscription elasticity and rapid deployment without capital expenditure. Decentralized trial infrastructure for wearable device data capture and telemedicine platforms offers a second white-space target with limited incumbent saturation. A cloud-native architecture with automatic FDA validation documentation provides the strongest go-to-market angle against legacy rebuilds. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical SaaS platforms with native life sciences compliance, as these vendors capture multi-year subscriptions with 90%+ renewal rates driven by regulatory switching costs. Acquisition targets should demonstrate pre-built EU AI Act documentation capabilities and established CRO channel relationships. The signal to watch is enrollment-velocity pricing adoption rates among North American Phase II oncology trials, where usage-based model penetration indicates vendor pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Oracle leverages ERP relationships to embed e-clinical modules within existing pharmaceutical technology stacks. |
| Strategic Partnership | CRO alliances with cloud-native vendors accelerate multi-site trial startup velocity and global site onboarding. |
| Acquisition of Specialist Firm | Real-world data asset purchases enable trial planning workflows that differentiate beyond pure software licensing. |
| Product Launch | Generative AI protocol drafting tools collapse document development timelines and displace manual medical writing services. |
| Geographic Expansion | Swiss and Singapore data center investments address GDPR and emerging Asian data residency requirements for global sponsors. |
Methodological Framework
The analysis maps clinical trial management, electronic data capture, and decentralized trial platforms, each validated through conversations with regulatory affairs leads at pharmaceutical sponsors, CRO operations directors, and hospital IT procurement managers. Primary interview data triangulates against FDA 510(k) filings, ClinicalTrials.gov protocol registrations, EMA Good Clinical Practice inspection reports, and CDISC implementation guidelines. Bottom-up segment sizing reconciles with top-down pharmaceutical R&D expenditure allocation models to ensure cross-validation integrity.
Assumptions regarding FDA 21 CFR Part 11 enforcement intensity and EU AI Act risk classification timelines were held fixed across the projection horizon, while cloud adoption velocity and AI feature penetration were modeled as scenario-dependent variables. Segmentation dimensions include deployment model, sponsor size tier, therapeutic area data density, and regional regulatory cluster. CAGRs were derived from enrollment-linked pricing elasticity curves and historical replacement cycle patterns for validated electronic systems. Forecast inputs incorporate CRO seat expansion rates and biotech funding environment signals.
Practitioners should monitor FDA digital health guidance revisions and EU AI Act implementing acts for early signals of algorithmic validation requirement shifts. Forecasts reflect these assumptions alongside modeled sponsor procurement behavior. Quarterly review of CRO multi-tenant platform adoption rates and open-source framework penetration at academic institutions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Programming Software Market
Software & Services
Digital Illustration App Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
User Feedback Software Market
Software & Services
Bridge Analysis Software Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Queue Manager Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Co-Browsing Software Market
Software & Services
Global Gamification Software Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Digital Painting Software Market
Software & Services
Global Qualitative Data Analysis Software Market
Software & Services
Apache Spark Market
Software & Services
Video Management Software (VMS) Market