
 Private Network Services Market | 2026-2036
Private Network Services Market Size, Share, and Industry Trends Forecast 2026-2036
Private Network Services Market Outlook
Germany is fragmenting as a once-consolidated vendor geography, with new spectrum licensees and systems integrators eroding the position of legacy telecom incumbents. Cisco Systems leverages its enterprise routing heritage to anchor hybrid deployment contracts across European manufacturing zones. Huawei Technologies sustains deep R&D pipelines in 5G private network cores despite access restrictions in select Western markets. Ericsson competes through end-to-end radio and core bundling aimed at industrial verticals.
Private network services denote dedicated, non-public telecommunications infrastructure delivering controlled bandwidth, sub-50 millisecond latency, and localized data sovereignty for enterprise and institutional operators. These systems employ cellular radio access networks, software-defined cores, and edge computing nodes to isolate traffic from commercial carrier infrastructure while supporting deterministic quality-of-service guarantees. Managed services and private LTE deployments command expanding margin pools as end users prioritize operational support over capital ownership. SD-WAN and 5G technology segments attract disproportionate investment as enterprises replace aging MPLS backbones with programmable, cloud-native connectivity fabrics.
The FCC governs CBRS and mmWave spectrum auctions that determine which enterprises may self-deploy private cellular infrastructure in the United States. ETSI standards and CE marking requirements shape equipment interoperability and market access across European Union member states. The EU AI Act and national cybersecurity frameworks are layering compliance obligations onto network architectures that process automated industrial data. Stakeholders must weigh spectrum licensing strategies against vendor lock-in risks as regulatory fragmentation deepens between jurisdictions.
Market Dynamics
The FCC's CBRS spectrum reforms have dismantled carrier gatekeeping over private cellular deployment, forcing infrastructure vendors to compete directly with enterprise IT departments for control of campus network architectures.
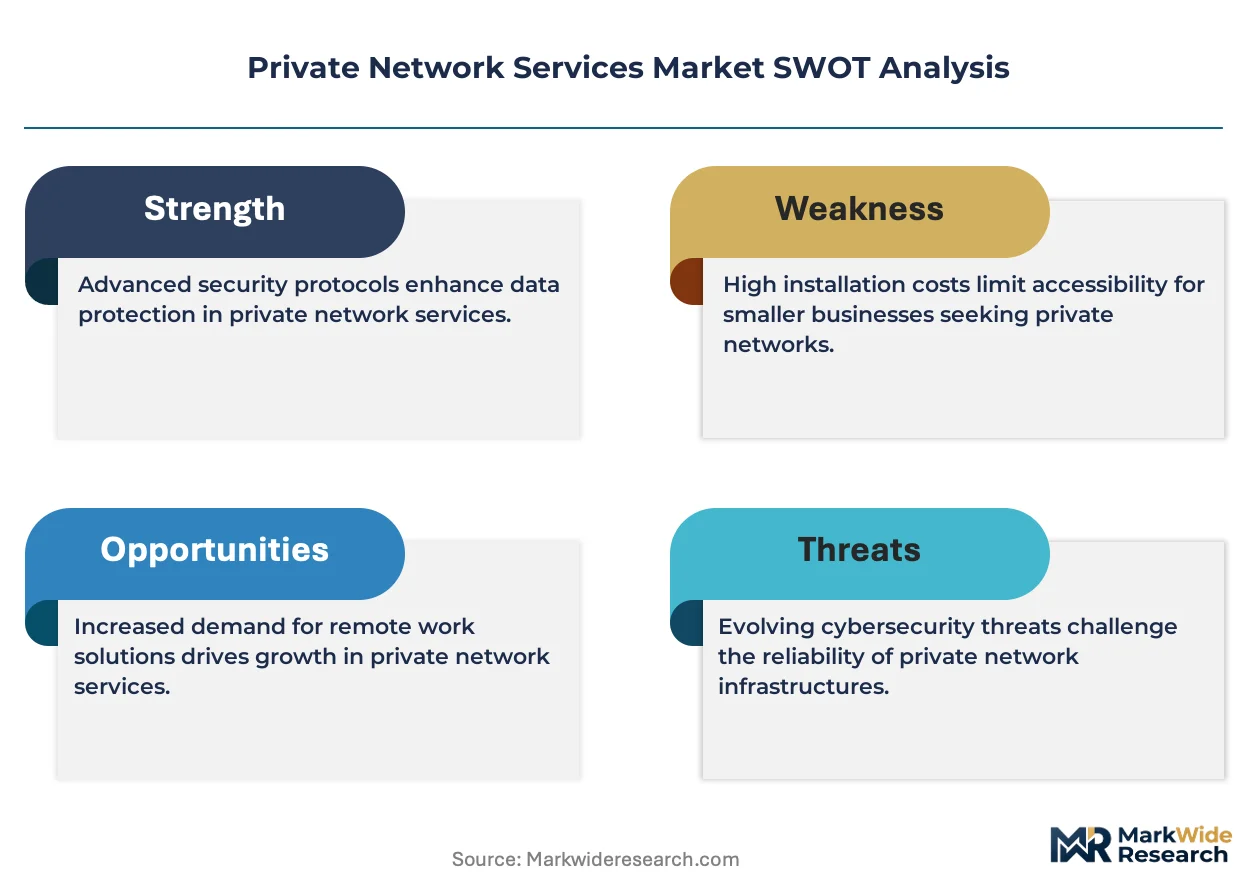
Growth Catalysts
- Automotive smart factories:German manufacturers are building campus-wide private LTE infrastructure to synchronize robotic assembly lines with sub-50 millisecond latency guarantees.
- CBRS spectrum access:The FCC's three-tiered licensing framework in the United States allows industrial operators to self-deploy 5G without commercial carrier intermediaries.
- Edge computing convergence:Containerized network functions deployed at factory premises enable localized data sovereignty for mission-critical automation systems.
Market Restraints
- Radio unit supply concentration:Specialized 5G massive MIMO hardware depends on concentrated semiconductor fabrication in East Asian foundries.
- Site acquisition costs:Dense small cell deployment for indoor coverage requires expensive building access negotiations with facility owners.
- Legacy MPLS substitution drag:Enterprises with multi-year managed WAN contracts face contractual penalties that delay private network migration.
Strategic Opportunities
- Indian manufacturing corridors:The country's PLI scheme incentives for electronics and automotive production create demand for dedicated industrial connectivity.
- EU AI Act compliance infrastructure:Automated industrial data processing mandates are layering network security requirements that private cellular architectures satisfy.
- Neutral host models:Multi-tenant private networks serving adjacent industrial parks offer shared infrastructure economics previously unavailable to mid-size enterprises.
Industry Challenges
- Radio frequency engineering scarcity:Campus propagation modeling and interference mitigation require specialized talent pools concentrated among legacy telecom operators.
- Multi-vendor integration complexity:Disaggregated open RAN architectures force enterprise IT teams to orchestrate software from incompatible supplier ecosystems.
- CE marking certification timelines:European equipment authorization processes delay deployment schedules for urgent factory digitization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Network Services Market |
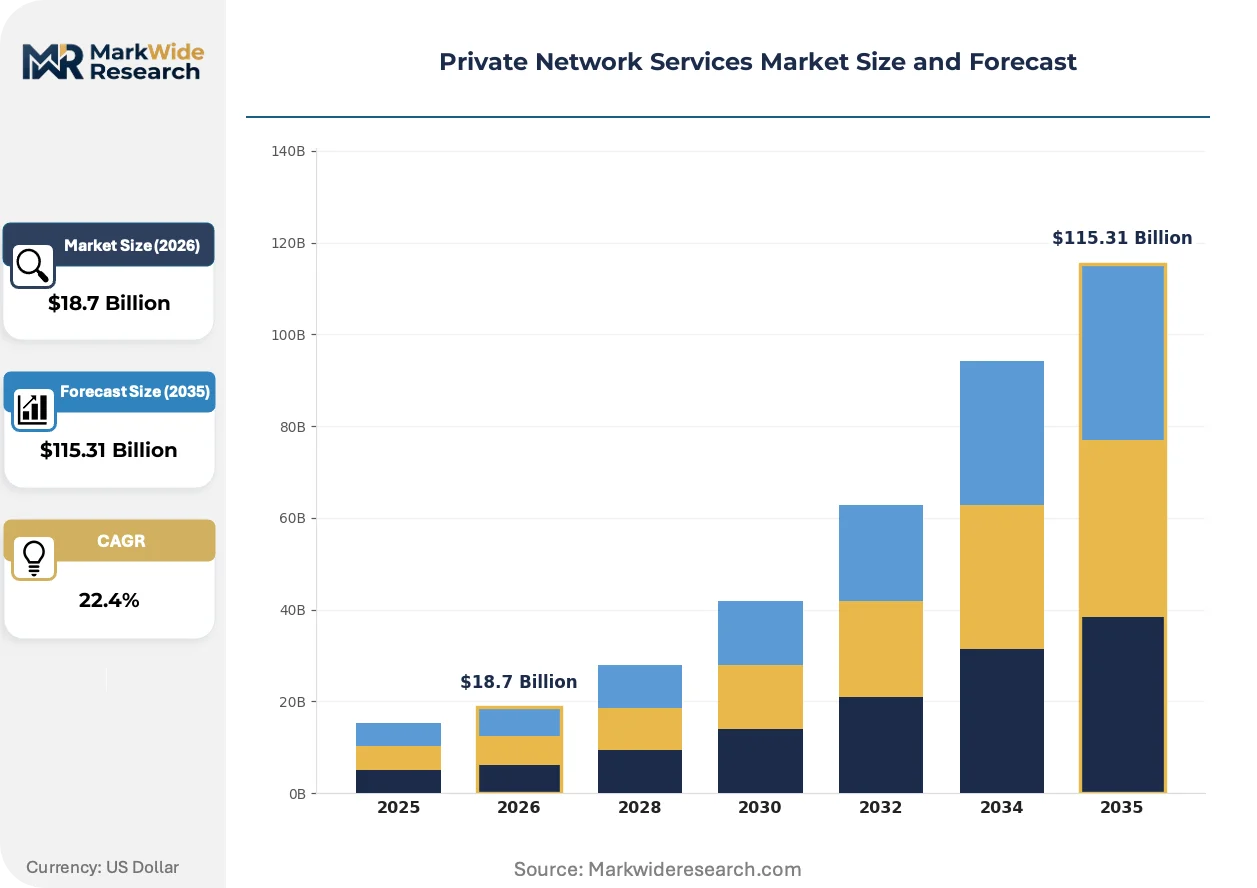
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Connectivity, Virtual Private Networks, Managed Services, Private LTE Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Healthcare Providers, Industrial Firms, Educational Institutions, Retail Enterprises Technology: SD-WAN, MPLS, 5G, Wi-Fi 6 |
| Companies Covered | Cisco Systems, Verizon Communications, AT&T, Huawei Technologies, Nokia, Ericsson, Microsoft, Palo Alto Networks, Juniper Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Network Services Market Strategic Shifts
Open RAN disaggregation is fragmenting vendor control over radio access networks, while cloud-native core architectures compress the boundary between enterprise IT and telecom infrastructure.
Cloud-native 5G core software running on commodity servers is rendering obsolete proprietary hardware-dependent mobile packet cores that locked enterprises into single-vendor upgrade cycles. Automotive and logistics operators in Germany and the United States are deploying these containerized platforms within six-month procurement windows. The shift compresses capital requirements and accelerates feature velocity for industrial automation use cases.
The EU AI Act's risk-based classification system imposes cybersecurity documentation obligations on networks processing automated manufacturing data. Equipment vendors must now embed audit trails and explainability interfaces into private network management systems. German automotive suppliers are prioritizing core suppliers with pre-certified compliance architectures to accelerate plant deployment schedules.
Enterprise buyers are unbundling network equipment procurement from managed service contracts, treating private 5G as a software-defined infrastructure layer rather than a telecom service. Industrial conglomerates in Japan and South Korea are building in-house radio planning capabilities and sourcing open RAN components directly. This pattern concentrates negotiation leverage with hardware vendors while marginalizing traditional systems integrators.
Private Network Services Market Segmentation
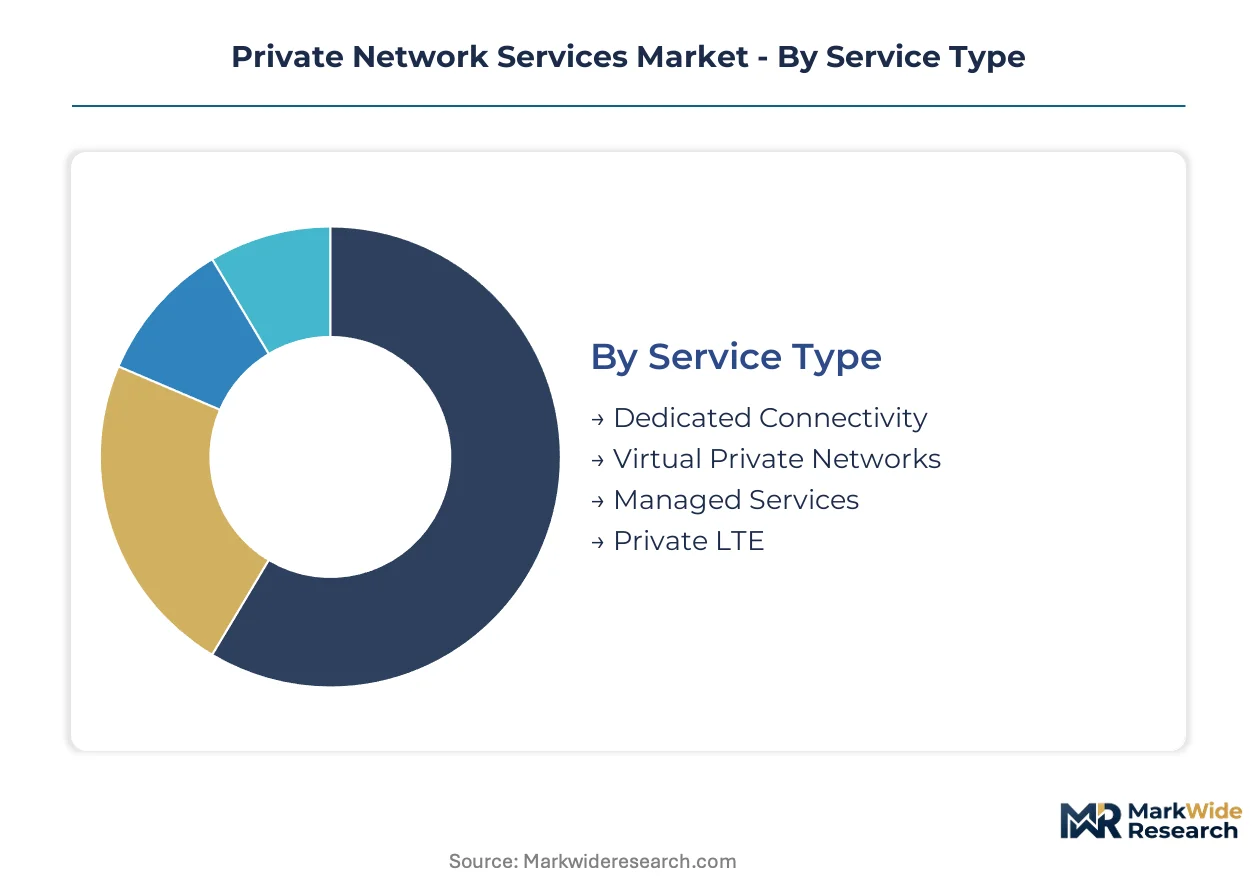
Private network services fragment across four distinct classification axes that determine procurement patterns, margin structures, and vendor selection criteria. Each segmentation layer reveals divergent buyer priorities: industrial operators prioritize deterministic latency guarantees while healthcare systems emphasize data sovereignty compliance. Understanding these cross-cutting dimensions enables suppliers to align capability roadmaps with specific wallet concentration points.
Service Type:
Mature connectivity offerings anchor enterprise budgets while emerging private cellular formats capture the steepest expansion trajectories.
- Managed Services:Third-party operational support covering network monitoring, incident response, and capacity planning under fixed-fee contracts. German automotive manufacturers favor this model to avoid building in-house RF engineering teams for smart factory deployments.
- Private LTE:Dedicated cellular infrastructure using licensed or shared spectrum with localized core networks and guaranteed quality-of-service parameters. Industrial firms in the United States leverage CBRS spectrum allocations to self-deploy without carrier intermediaries, though radio unit supply constraints delay some campus rollouts.
- Dedicated Connectivity:Physical layer separation through fiber or microwave links providing uncontended bandwidth.
- Virtual Private Networks:Overlay encryption and tunneling atop shared public infrastructure.
Managed Services handles the majority of throughput; Private LTE is climbing the fastest on share.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises builds from operational-expense cloud subscriptions.
- Hybrid:Orchestrated workload placement across on-premises radio access, cloud-hosted core functions, and edge computing nodes. Cisco Systems anchors European manufacturing contracts with this architecture, balancing data sovereignty requirements against scalability needs.
- Edge Computing:Containerized network functions deployed at factory premises or hospital campuses to minimize latency and retain sensitive data locally. The EU AI Act's risk-based classification system accelerates demand for these architectures among German automotive suppliers processing automated manufacturing data.
- Cloud-Based:Fully virtualized network functions delivered as subscription services.
- On-Premises:Physical hardware ownership with dedicated facility space and power.
Hybrid deployments dominate current contract values; Edge Computing shows the steepest expansion trajectory.
End User:
Application-specific requirements drive divergent technical specifications across vertical buyer clusters.
- Industrial Firms:Manufacturing, logistics, and energy operators deploying deterministic connectivity for robotic automation and predictive maintenance. These buyers prioritize sub-50 millisecond latency guarantees and campus-wide coverage density.
- Healthcare Providers:Hospital systems and medical device networks requiring HIPAA-compliant data isolation and uninterrupted connectivity for telemedicine and remote surgery applications.
- Educational Institutions:Universities and research facilities managing high-density Wi-Fi 6 convergence with private cellular for campus mobility.
- Retail Enterprises:Store networks and distribution centers integrating inventory tracking with customer analytics platforms.
Industrial Firms command the largest deployment scale; Healthcare Providers are gaining share fastest on compliance-driven refresh cycles.
Technology:
Supply concentration in radio semiconductor fabrication shapes availability timelines for next-generation formats.
- 5G:New radio interfaces and cloud-native cores supporting massive machine-type communications and ultra-reliable low-latency service classes. Ericsson competes through end-to-end radio and core bundling aimed specifically at industrial verticals adopting this technology.
- SD-WAN:Software-defined overlay networks replacing MPLS backbones with programmable, cloud-native connectivity fabrics. Enterprises prioritize this technology to reduce branch connectivity costs while maintaining application-aware traffic steering.
- MPLS:Legacy multiprotocol label switching networks with established service level agreements.
- Wi-Fi 6:IEEE 802.11ax indoor coverage complementing cellular for non-critical device connectivity.
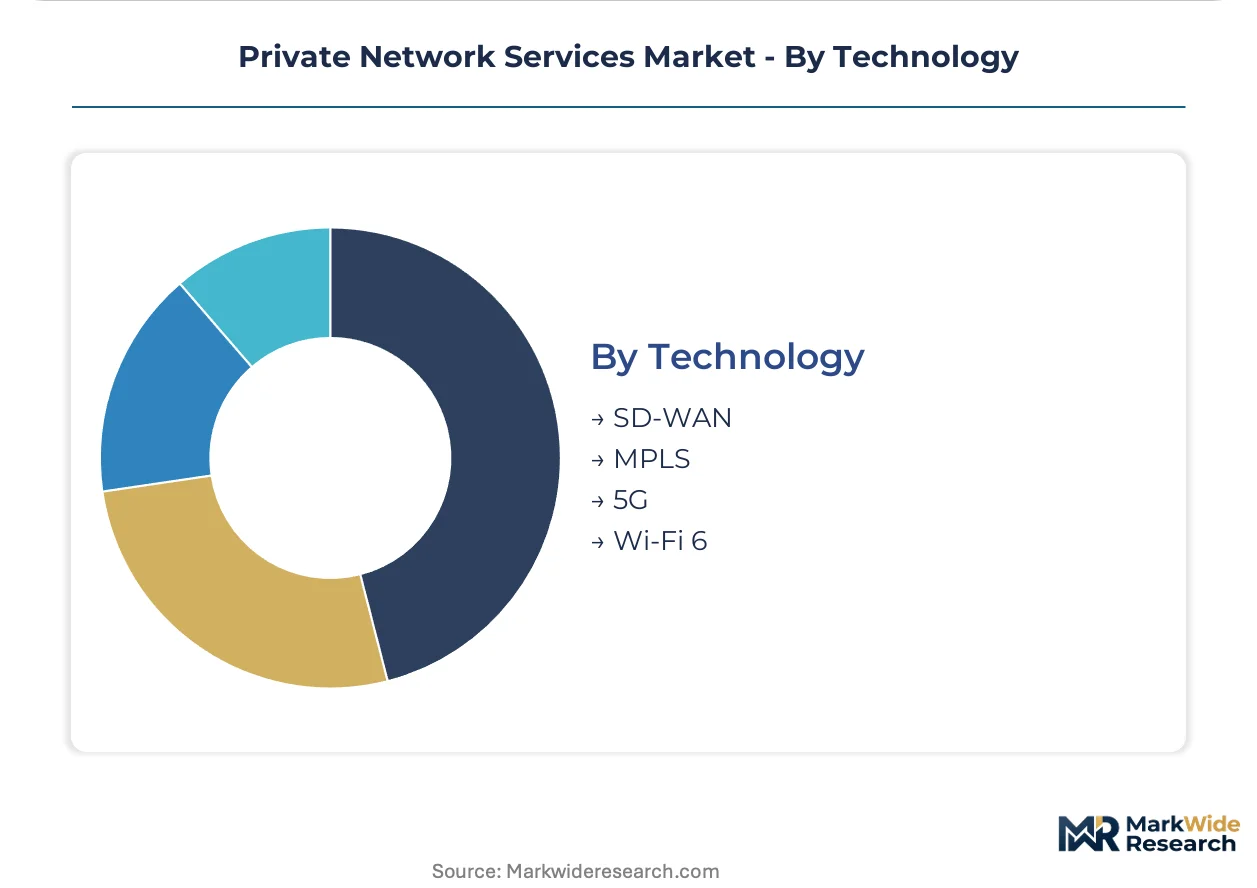
SD-WAN carries the majority of current enterprise traffic; 5G is expanding most quickly as manufacturing automation requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC governs CBRS spectrum auctions that determine which enterprises may self-deploy private cellular infrastructure in the United States. ETSI standards and CE marking requirements shape equipment interoperability and market access across European Union member states. The EU AI Act and national cybersecurity frameworks are layering compliance obligations onto network architectures that process automated industrial data.
United States
Industrial operators leverage CBRS spectrum allocations to self-deploy 5G without commercial carrier intermediaries. The FCC's three-tiered licensing framework enables priority access licenses for campus-wide deployments. Manufacturing clusters in Michigan and Ohio are synchronizing robotic assembly lines with sub-50 millisecond latency guarantees.
Germany
Automotive manufacturers are building campus-wide private LTE infrastructure for smart factory operations. The country's national cybersecurity regulator imposes documentation obligations on networks processing automated manufacturing data. Bavaria's industrial corridor hosts multiple automotive suppliers prioritizing core vendors with pre-certified compliance architectures.
China
Electronics and automotive production facilities demand dedicated industrial connectivity for mission-critical automation. The Ministry of Industry and Information Technology governs spectrum allocation and equipment certification standards. Yangtze River Delta manufacturing zones are deploying containerized network functions to minimize latency and retain sensitive data locally.
India
The country's PLI scheme incentives for electronics and automotive production create demand for dedicated industrial connectivity. TRAI spectrum policy reforms are reshaping how enterprises access dedicated wireless capacity. Gujarat and Tamil Nadu manufacturing corridors are attracting private network deployments for smart factory digitization programs.
Japan
Industrial conglomerates are building in-house radio planning capabilities and sourcing open RAN components directly. METI industrial policy frameworks support enterprise self-deployment of private cellular infrastructure. Kansai manufacturing zones exemplify the shift toward software-defined infrastructure layers rather than telecom service procurement.
Private Network Services Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. Infrastructure vendors with deep R&D pipelines in 5G private network cores compete against systems integrators leveraging enterprise routing heritage. The market structures around three archetypes: end-to-end radio and core bundlers, hybrid deployment specialists, and cloud-native platform providers. Dominant competitive moves include strategic partnerships between hardware vendors and managed service operators, plus geographic expansion through localized spectrum licensing expertise.
Within the end-to-end bundling tier, Ericsson and Nokia exemplify integrated radio-access-to-core positioning. Cisco Systems occupies a position among hybrid deployment specialists leveraging enterprise infrastructure relationships. Huawei Technologies sits within the capability-concentrated tier despite access restrictions in select Western markets, sustaining deep R&D pipelines through captive supply of semiconductor components.
| Leading Market Players |
|---|
| Cisco Systems |
| Verizon Communications |
| AT&T |
| Huawei Technologies |
| Nokia |
| Ericsson |
| Microsoft |
| Palo Alto Networks |
| Juniper Networks |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in 5G massive MIMO radio unit fabrication is compressing supplier margins while amplifying pricing power among semiconductor foundries with available wafer starts. German automotive manufacturers and US industrial operators face elongated procurement timelines that force premium payments for expedited delivery slots.
Pricing Analysis
Geographic price spreads widen substantially between North American CBRS deployments and European licensed-spectrum builds, with the former commanding 15-25% premiums due to Priority Access License auction costs. Three-tier pricing structure across premium guaranteed-latency, standard managed-service, and economy self-deploy tiers separates enterprise buyers by operational criticality. Pricing pressure stems from open RAN disaggregation commoditizing radio software while hardware concentrates. Mid-size manufacturing conglomerates exhibit acute price sensitivity, whereas mission-critical energy utilities absorb premium tiers without elasticity.
Supply Chain Analysis
Upstream gallium nitride substrate and advanced node RF semiconductor fabrication concentrates in Taiwan, South Korea, and select US facilities. Specialized 5G radio units draw from concentrated East Asian foundry capacity, high-purity substrate supply, and proprietary antenna intellectual property. Single-source vulnerability runs through TSMC's 7nm RF process nodes for massive MIMO beamforming chipsets. Distribution runs through tier-one systems integrators holding CE marking and FCC certification relationships, with direct OEM procurement emerging among Japanese industrial conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Private network services sit in early-cycle expansion as CBRS spectrum reforms and EU AI Act compliance mandates accelerate enterprise self-deployment beyond carrier-dependent models. Manufacturing automation requirements in automotive and electronics verticals sustain penetration tailwinds.
For Market Incumbents: Entrench through captive supply of 5G core software and radio semiconductor components to neutralize open RAN substitution threats. Deepen certification pre-qualification with German BSI and US NIST frameworks to accelerate deployment timelines for compliance-sensitive buyers. Prioritize hybrid deployment architectures that leverage existing enterprise routing relationships against cloud-native challengers.
For New Entrants and Emerging Players: Pursue neutral host infrastructure models serving adjacent industrial parks in India's Gujarat and Tamil Nadu manufacturing corridors, where PLI scheme incentives concentrate electronics and automotive production. Target mid-size enterprises lacking in-house RF engineering capabilities with fully-managed private LTE subscriptions. Anchor go-to-market through systems integrator partnerships rather than direct carrier competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native 5G core software sub-segments as containerization displaces proprietary hardware. Long-term viability favors platform providers with recurring managed service revenue over equipment vendors exposed to cyclical refresh cycles. Monitor FCC CBRS auction participation rates and Priority Access License utilization as inflection signals for enterprise adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Radio Software Development | Disaggregates vendor control and enables multi-source procurement for German automotive suppliers. |
| CE Marking Pre-Certification Investment | Accelerates deployment schedules for EU AI Act compliance among Bavaria industrial corridor operators. |
| Managed Service Subscription Launch | Captures recurring revenue from mid-size enterprises avoiding in-house RF engineering teams. |
| Edge Computing Node Partnership | Localizes data sovereignty for Michigan and Ohio manufacturing clusters processing automated assembly data. |
| Neutral Host Infrastructure Buildout | Delivers shared economics to adjacent industrial parks previously unserved by dedicated connectivity. |
Study Parameters
Desk research of FCC spectrum auction records, ETSI standardization documents, and carrier capex disclosures preceded structured interviews with private network procurement officers at industrial conglomerates, RF engineering directors at systems integrators, and regulatory affairs leads at equipment vendors. Primary fieldwork validated secondary findings through bottom-up deployment tracking and top-down vendor revenue triangulation.
Assumptions held spectrum licensing frameworks and semiconductor fabrication capacity constant while varying enterprise automation investment rates and open RAN adoption curves across the projection horizon. Segmentation modeling incorporated service type, deployment architecture, end-user vertical, and technology generation dimensions. CAGR derivation rested on deployment pipeline analysis and vendor booking trajectories, with cross-reference to hyperscaler edge computing investment disclosures.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or East Asian semiconductor export restrictions would shift the trajectory. Forecasts reflect documented assumptions regarding CBRS license utilization and CE marking processing timelines. Cross-checking against carrier-reported private network attachment rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Cloud Gateway Module Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
BYOD Market
Network Technology
Managed MPLS Market
Network Technology
5G CPE Device Market
Network Technology
Mobile Network Optimization Market
Network Technology
Network Telemetry Market
Network Technology
Optical Network Equipment Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Wi-Fi Extender Market
Network Technology
RTP Market
Network Technology
Europe SD-WAN Market
Network Technology
Sand Lane Systems Market
Network Technology
Virtual Customer Premises Equipment Market