
 Demand Planning Solutions Market | 2026-2036
Demand Planning Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Demand Planning Solutions Market Intelligence
Buyer concentration in the retail and automotive OEM sectors is restructuring procurement patterns for demand planning platforms. SAP SE leverages deep ERP integration to anchor enterprise accounts across manufacturing verticals. Oracle Corporation competes through database-native analytics that sustain high-velocity forecasting workloads. Kinaxis Inc. differentiates via concurrent planning architectures that dominate aerospace and pharmaceutical supply chains.
Demand planning solutions encompass software platforms that apply statistical forecasting, machine learning algorithms, and multi-echelon inventory optimization to predict future product demand across supply chain nodes. These systems typically process historical sales data, external market signals, and constraint variables to generate procurement and production plans with defined confidence intervals. Cloud-based solutions now capture the largest revenue pool as enterprises migrate from legacy on-premise installations, while hybrid deployment models are expanding fastest among pharmaceutical and food and beverage end users that require partitioned data governance. The consumer electronics vertical generates concentrated margin pools due to short product lifecycles and volatile component sourcing.
FDA digital supply chain guidance, EU AI Act algorithmic transparency requirements, and India's BIS cloud security standards are reshaping vendor certification requirements and procurement checklists. Compliance with these frameworks now determines market access for platform providers serving regulated industries. Stakeholders must evaluate how emerging algorithmic accountability rules will alter model validation costs and customer onboarding timelines.
Market Dynamics
Cloud migration mandates under the EU AI Act and FDA's digital supply chain guidance are forcing enterprise procurement teams to reevaluate vendor certification status before contract renewal cycles.
Growth Catalysts
- Algorithmic Transparency Mandates:The EU AI Act requires explainable forecasting models in high-risk supply chain applications, creating compliance-driven replacement cycles for opaque legacy systems.
- Automotive OEM Demand:Electric vehicle manufacturers deploy multi-echelon inventory optimization to manage battery cell sourcing volatility across tiered supplier networks.
- India Cloud Infrastructure Buildout:BIS cloud security standards and data localization requirements are accelerating domestic platform deployment for supply chain analytics.
Market Restraints
- Specialized Talent Scarcity:Shortages of data scientists with supply chain domain expertise inflate implementation timelines and professional services costs.
- Semiconductor Component Volatility:AI accelerator chip supply constraints limit on-premise deployment scalability for compute-intensive forecasting workloads.
- Cross-Border Data Friction:India's data localization requirements and EU GDPR restrictions complicate multi-region platform architectures for multinational enterprises.
Strategic Opportunities
- Pharmaceutical Cold Chain Expansion:Cell and gene therapy logistics create demand for temperature-constrained demand planning with real-time shelf-life tracking.
- FDA Digital Supply Chain Guidance:Drug traceability mandates open procurement budgets for serialized inventory forecasting platforms.
- Edge-AI Convergence:Lightweight machine learning inference at warehouse nodes enables sub-second replenishment decisions without cloud latency.
Industry Challenges
- ERP Integration Complexity:SAP and Oracle legacy installations require extensive API customization, extending deployment cycles.
- Model Validation Bottlenecks:FDA and EMA algorithmic accountability rules demand documented backtesting protocols that slow customer onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demand Planning Solutions Market |
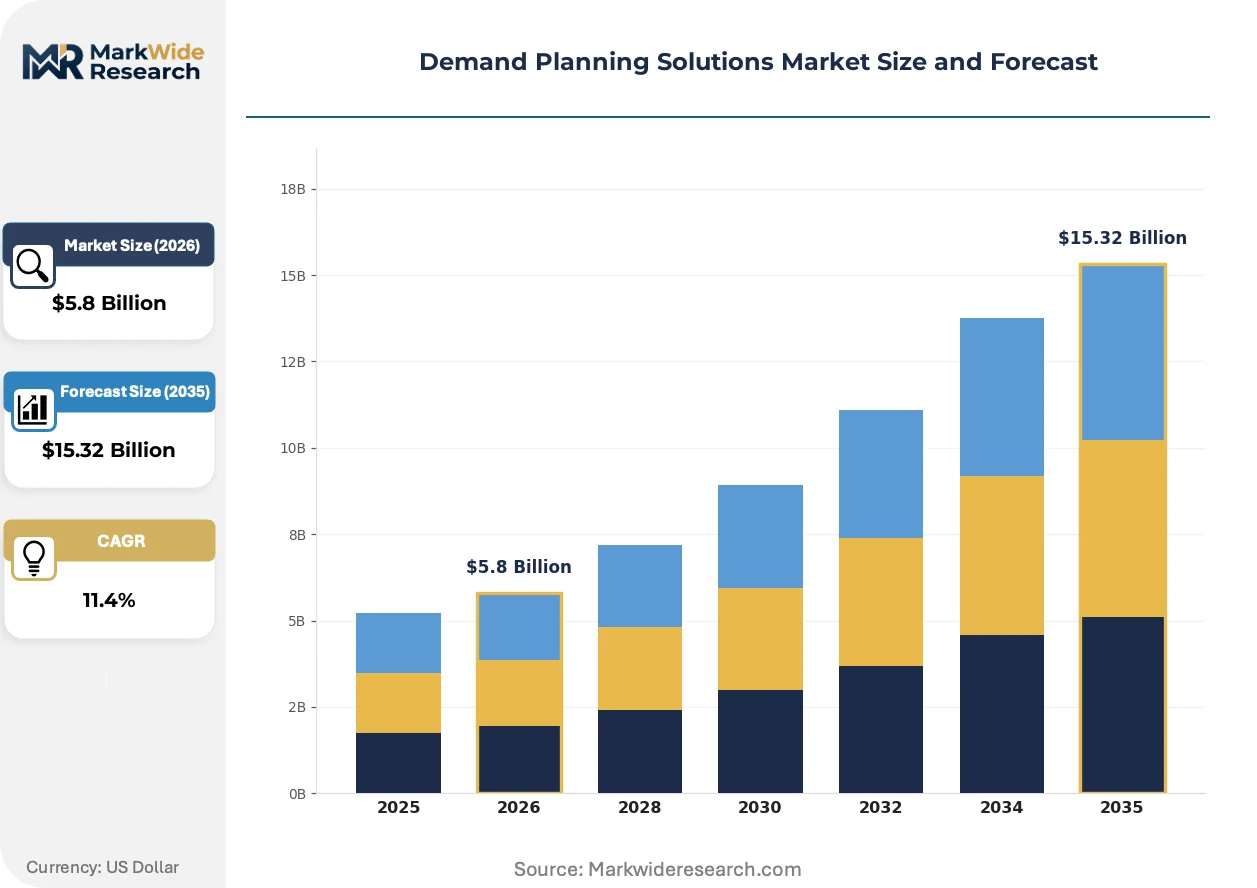
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premise Solutions, Hybrid Solutions, Software as a Service End User: Retail, Manufacturing, Healthcare, Food & Beverage Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Hybrid Cloud Industry Vertical: Consumer Electronics, Automotive OEMs, Pharmaceuticals, Apparel |
| Companies Covered | SAP SE, Oracle Corporation, Blue Yonder, Kinaxis Inc., IBM, Infor, o9 Solutions, Logility, Inc., RELEX Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demand Planning Solutions Market Strategic Shifts & Innovations
Generative AI is compressing model development cycles while regulatory pressure on algorithmic accountability is reshaping vendor roadmaps toward audit-ready architectures.
Digital twin technology is integrating physics-based simulation with statistical demand signals to generate scenario forecasts for semiconductor and aerospace supply chains. Automotive and industrial equipment manufacturers adopt these fused models fastest, replacing spreadsheet-based consensus planning. This convergence is integrating engineering constraints directly into procurement optimization, collapsing the traditional separation between product design and supply planning functions.
The EU AI Act's risk classification framework is mandating human-in-the-loop validation for automated procurement decisions above defined spend thresholds. Pharmaceutical and medical device manufacturers face the steepest compliance burdens, forcing platform vendors to build explainability dashboards and decision audit trails. German automotive suppliers and French aerospace contractors are prioritizing vendors with pre-certified algorithmic transparency modules.
Retailer buying committees are consolidating vendor relationships around integrated planning-to-fulfillment platforms, displacing point-solution forecasting tools. Mass merchant and grocery chains in the United States and Germany now require demand planning modules to demonstrate pre-built connectors to warehouse management and transportation systems. Food and beverage verticals show the fastest consolidation pace as margin pressure forces procurement teams to reduce integration overhead.
Demand Planning Solutions Market Segmentation
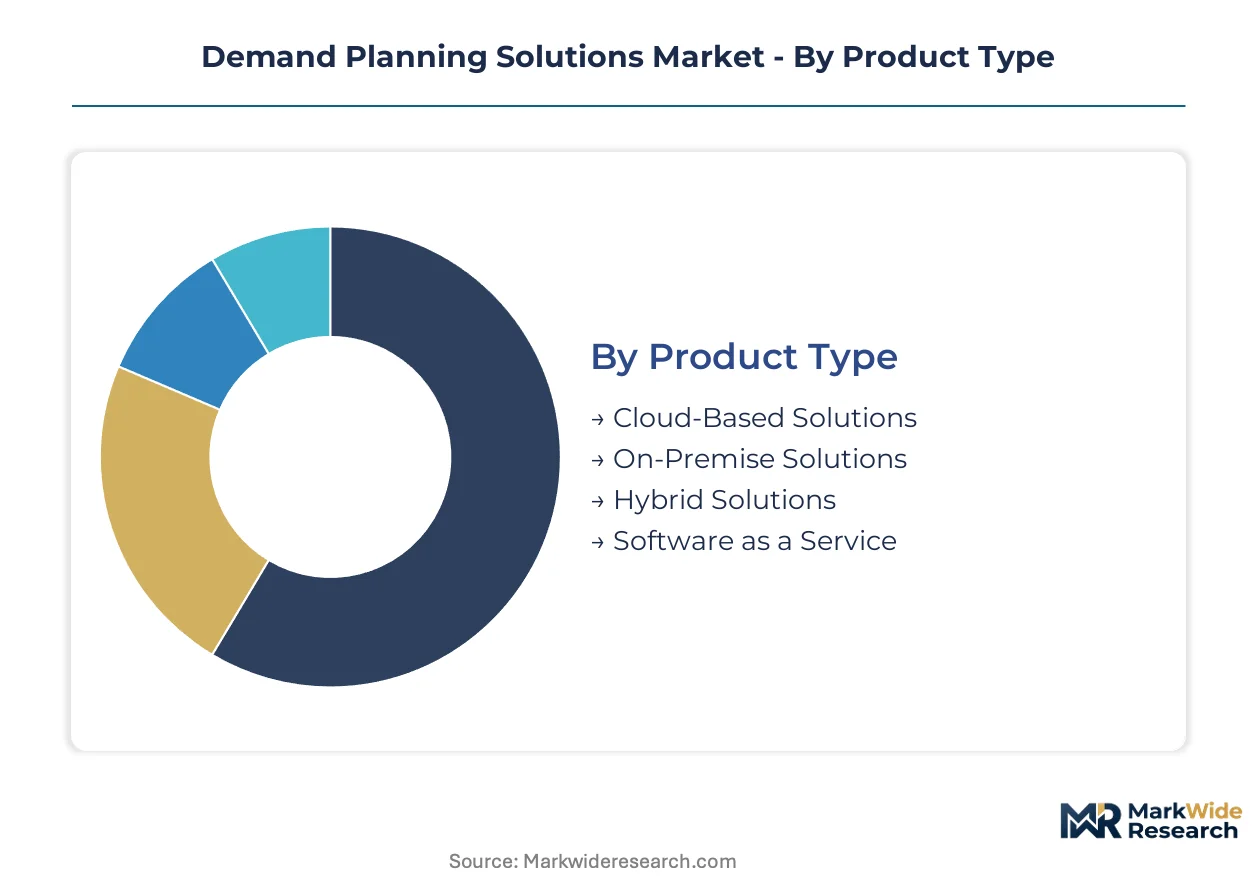
Segmentation in demand planning solutions reveals how procurement priorities diverge across infrastructure choices and industry risk profiles. Cloud deployment models and vertical-specific compliance requirements create distinct vendor selection criteria that reshape competitive positioning.
Product Type:
Supply concentration in cloud infrastructure is concentrating procurement budgets toward deployment architectures that balance scalability with data sovereignty requirements.
- Cloud-Based Solutions:These platforms deliver statistical forecasting and machine learning inference through managed infrastructure, eliminating capital expenditure for server hardware. Retail chains in the United States and Germany are deploying these systems to reduce inventory carrying costs while meeting EU AI Act algorithmic transparency mandates.
- Hybrid Solutions:Partitioned architectures separate sensitive demand data on-premise while running computational workloads in cloud environments. Pharmaceutical and food and beverage end users favor this model for compliance with FDA digital supply chain guidance and India's BIS cloud security standards.
- On-Premise Solutions:Legacy installations retain relevance in defense and classified supply chains requiring air-gapped forecasting environments.
- Software as a Service:Subscription models with pre-configured forecasting templates accelerate time-to-value for mid-market manufacturers lacking dedicated data science teams.
Today's leader: Cloud-Based Solutions. Tomorrow's challenger: Hybrid Solutions.
End User:
Cost tier differentiation separates enterprise deployments with custom model development from standardized implementations serving price-sensitive buyers.
- Retail:AI-driven forecasting modules process point-of-sale velocity, promotional calendars, and weather signals to optimize replenishment. Mass merchant and grocery chains in the United States and Germany now require pre-built connectors to warehouse management systems.
- Automotive OEMs:Electric vehicle manufacturers deploy multi-echelon inventory optimization across tiered battery cell supplier networks, integrating engineering constraints directly into procurement planning.
- Healthcare:Hospital systems and medical device distributors prioritize demand planning with serialized inventory tracking for FDA drug traceability compliance.
- Food & Beverage:Margin pressure forces procurement teams toward integrated planning-to-fulfillment platforms that reduce integration overhead.
Volume concentration favors Retail. Margin expansion potential concentrates in Automotive OEMs.
Deployment Model:
Application-specific requirements around latency, data residency, and failover resilience determine architecture selection across multinational footprints.
- Public Cloud:Shared infrastructure delivers elastic compute for seasonal demand spikes without capacity planning overhead.
- Private Cloud:Dedicated environments satisfy pharmaceutical and aerospace requirements for isolated model training and audit trails.
- Multi-Cloud:Workload distribution across AWS, Azure, and Google Cloud mitigates vendor lock-in for enterprises with existing enterprise agreements.
- Hybrid Cloud:Edge-AI inference at warehouse nodes enables sub-second replenishment decisions while maintaining centralized demand signal aggregation.
Current procurement momentum centers on Hybrid Cloud. Multi-Cloud architectures are climbing the fastest among regulated industries.
Industry Vertical:
Customer type segmentation separates high-velocity consumer sectors with short product lifecycles from capital-intensive industries with extended planning horizons.
- Consumer Electronics:Volatile component sourcing for semiconductors and displays generates concentrated margin pools for forecasting platforms that integrate supplier lead time uncertainty.
- Pharmaceuticals:Cell and gene therapy logistics create demand for temperature-constrained demand planning with real-time shelf-life tracking and EMA algorithmic accountability documentation.
- Automotive OEMs:German automotive suppliers prioritize vendors with pre-certified algorithmic transparency modules under EU AI Act risk classification frameworks.
- Apparel:Seasonal collection planning and omnichannel fulfillment complexity drive adoption of size-break forecasting and markdown optimization.
Margin capture is strongest in Consumer Electronics. Regulatory tailwinds favor Pharmaceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement intensity in the United States outpaces German investment rates, though regulatory compliance timelines in Germany accelerate vendor certification cycles more aggressively than North American procurement frameworks permit.
United States
Mass merchant and grocery chains deploy AI-driven forecasting modules to compress inventory carrying costs while integrating point-of-sale velocity with warehouse management systems. FDA digital supply chain guidance mandates serialized inventory tracking, opening procurement budgets for drug traceability platforms. The Dallas-Fort Worth logistics corridor concentrates cloud infrastructure investments for supply chain analytics.
Germany
Automotive OEMs and tiered battery cell suppliers prioritize multi-echelon inventory optimization to manage sourcing volatility across electric vehicle production networks. EU AI Act algorithmic transparency requirements force vendors to pre-certify explainable forecasting models before contract awards. Stuttgart and Munich industrial clusters anchor demand for concurrent planning architectures with embedded engineering constraints.
India
Domestic manufacturers accelerate cloud migration for supply chain analytics as data localization requirements reshape platform procurement checklists. BIS cloud security standards and CDSCO pharmaceutical traceability mandates create compliance-driven replacement cycles for legacy installations. Bangalore and Hyderabad technology corridors concentrate regional cloud infrastructure buildouts for demand planning deployments.
United Kingdom
Retail buying committees consolidate vendor relationships around integrated planning-to-fulfillment platforms, displacing point-solution forecasting tools. GDPR cross-border data restrictions complicate multi-region platform architectures for multinational enterprises with UK headquarters. The London logistics cluster drives adoption of hybrid deployment models balancing cloud scalability with partitioned data governance.
Japan
Consumer electronics manufacturers integrate volatile semiconductor and display sourcing uncertainty into forecasting platforms with shortened product lifecycles. METI supply chain resilience initiatives and JIS standards for cloud security accelerate domestic platform certification requirements. The Tokyo-Osaka industrial corridor concentrates margin pool capture for forecasting vendors serving high-velocity component markets.
Demand Planning Solutions Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered procurement segments, creating a bifurcated vendor landscape where ERP-integrated suites anchor enterprise accounts and concurrent planning specialists dominate aerospace and pharmaceutical supply chains. Market structure consolidates around three strategic archetypes: database-native analytics providers, deep ERP integration platforms, and concurrent planning architects. Dominant competitive moves include algorithmic transparency pre-certification for EU AI Act compliance and hybrid cloud architecture development for pharmaceutical data governance requirements.
Within the ERP-integrated tier, SAP SE and Oracle Corporation anchor enterprise procurement patterns across manufacturing verticals, while Kinaxis Inc. exemplifies the concurrent planning specialist archetype dominating regulated supply chains. These three entities represent the primary competitive anchors shaping vendor selection criteria, certification timelines, and platform integration standards across automotive, pharmaceutical, and retail procurement committees.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Blue Yonder |
| Kinaxis Inc. |
| IBM |
| Infor |
| o9 Solutions |
| Logility, Inc. |
| RELEX Oy |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure spot pricing indices cascade through demand planning solution tiers, compressing margins for pure-play SaaS vendors while anchoring premium pricing for hybrid architectures serving pharmaceutical and aerospace procurement committees.
Pricing Analysis
Capacity additions in India and Germany are reshaping price floors for cloud-native deployment models. Subscription tiers stratify across enterprise, mid-market, and entry-level bands, with differentiation driven by EU AI Act certification status and API integration depth. Pricing pressure stems from hyperscaler compute cost compression as AWS and Azure expand regional availability zones. Mid-market manufacturers exhibit highest price sensitivity, while automotive OEMs prioritize algorithmic transparency over license cost.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand for integrated ERP suites, while value-added resellers serve mid-market implementations requiring localization. Software development concentrates in the United States, India, and Germany, with cloud infrastructure provisioning anchored in AWS, Azure, and Google Cloud data centers. The supply chain draws from specialized AI accelerator chip fabrication, enterprise software engineering talent pools, and compliance certification services. Single-source vulnerability runs through NVIDIA GPU supply for on-premise forecasting workloads. Distribution runs through vendor-direct sales teams, systems integrators, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Demand planning solutions function as a stable compounder, with regulatory compliance mandates driving predictable replacement cycles across pharmaceutical and automotive procurement budgets.
For Market Incumbents: Lock in enterprise accounts through pre-certified EU AI Act algorithmic transparency modules and deep SAP ERP integration. Vertical integration into edge-AI hardware partnerships defends against cloud-native entrants. Prioritize hybrid cloud architecture development for pharmaceutical data governance requirements. For New Entrants and Emerging Players: Launch via cloud marketplace distribution to bypass incumbent sales cycle advantages. White-space targets include temperature-constrained demand planning for cell and gene therapy logistics and lightweight inference engines for warehouse edge nodes. Penetrate mid-market food and beverage through pre-built WMS connectors. For Investors and Strategic Acquirers: Asymmetric upside sits with concurrent planning specialists possessing aerospace and pharmaceutical reference accounts. Long-term viability favors vendors with audit-ready model validation protocols and multi-echelon optimization IP. Watch FDA digital supply chain guidance enforcement timelines as inflection indicator for serialized inventory forecasting platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Pre-Certification | EU AI Act compliance unlocks automotive and pharmaceutical procurement budgets in Germany and France. |
| Hybrid Cloud Architecture Development | Partitioned data governance satisfies FDA digital supply chain guidance for drug traceability platforms. |
| Edge-AI Inference Engine Launch | Sub-second replenishment decisions at warehouse nodes bypass cloud latency for retail chains. |
| Concurrent Planning Platform Integration | Physics-based simulation fusion collapses separation between product design and supply planning functions. |
| Pharmaceutical Cold Chain Expansion | Temperature-constrained forecasting with shelf-life tracking captures cell and gene therapy logistics demand. |
Research Approach
Multiple input streams — primary interviews with supply chain executives, platform engineering leads, and procurement officers at automotive OEMs and pharmaceutical distributors; secondary validation against FDA guidance documents, EU AI Act regulatory filings, and cloud infrastructure capex disclosures; plus customs data on enterprise software imports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across deployment model, organization size, vertical compliance intensity, and regional cloud adoption pattern dimensions. CAGRs were derived from segmented growth rate analysis applied to base-year market sizing. Industry-specific forecast inputs included pharmaceutical serialization mandate timelines and electric vehicle battery supplier network complexity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor export restriction scenarios and algorithmic accountability rule acceleration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Real Time Bidding Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
Artificial Intelligence (AI) in Marketing Market
Digital Solutions
Europe Data Virtualization Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Interactive Projector Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
IT Operations and Service Management (ITOSM) Market
Digital Solutions
Europe ICT Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Ad Network Software Market
Digital Solutions
Labor Management System in Retail Market
Digital Solutions
Computerized Maintenance Management System Market