
 Unified Monitoring Market | 2026-2036
Unified Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Unified Monitoring Market Intelligence
Consolidation among large-scale platform providers is recalibrating the competitive landscape for unified monitoring tools. Dynatrace leverages its AI-powered core to automate observability across complex cloud environments. Datadog competes on the breadth of its integrations and ease of deployment for cloud-native stacks. Splunk sustains its position through its powerful data analytics and security information and event management (SIEM) capabilities.
Unified monitoring provides a single-pane-of-glass view by aggregating and correlating performance data from diverse IT infrastructure. These platforms ingest logs, metrics, and traces to deliver holistic observability across applications, networks, and servers. Cloud-based deployment models now dominate new sales, displacing traditional on-premises installations. Within solution types, application monitoring and infrastructure monitoring form the foundational revenue streams for most vendors.
Regulatory frameworks such as Europe's GDPR and the US's HIPAA mandate stringent data security and availability reporting, directly impacting monitoring requirements. In financial services, compliance with directives from bodies like the SEC necessitates auditable performance and security logs. Vendor selection now hinges on a strategic choice between adopting a comprehensive, all-in-one platform or integrating specialized, best-of-breed monitoring tools.
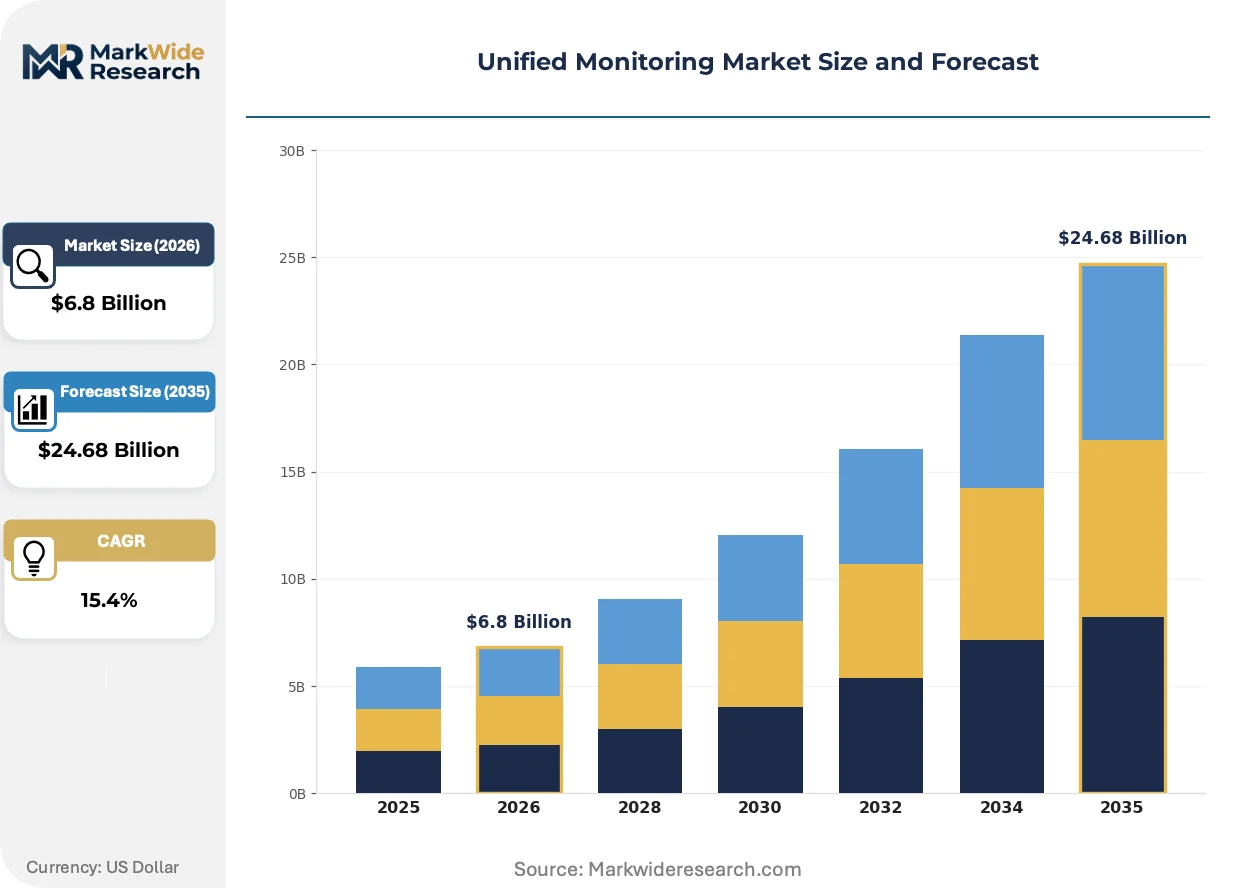
Market Dynamics
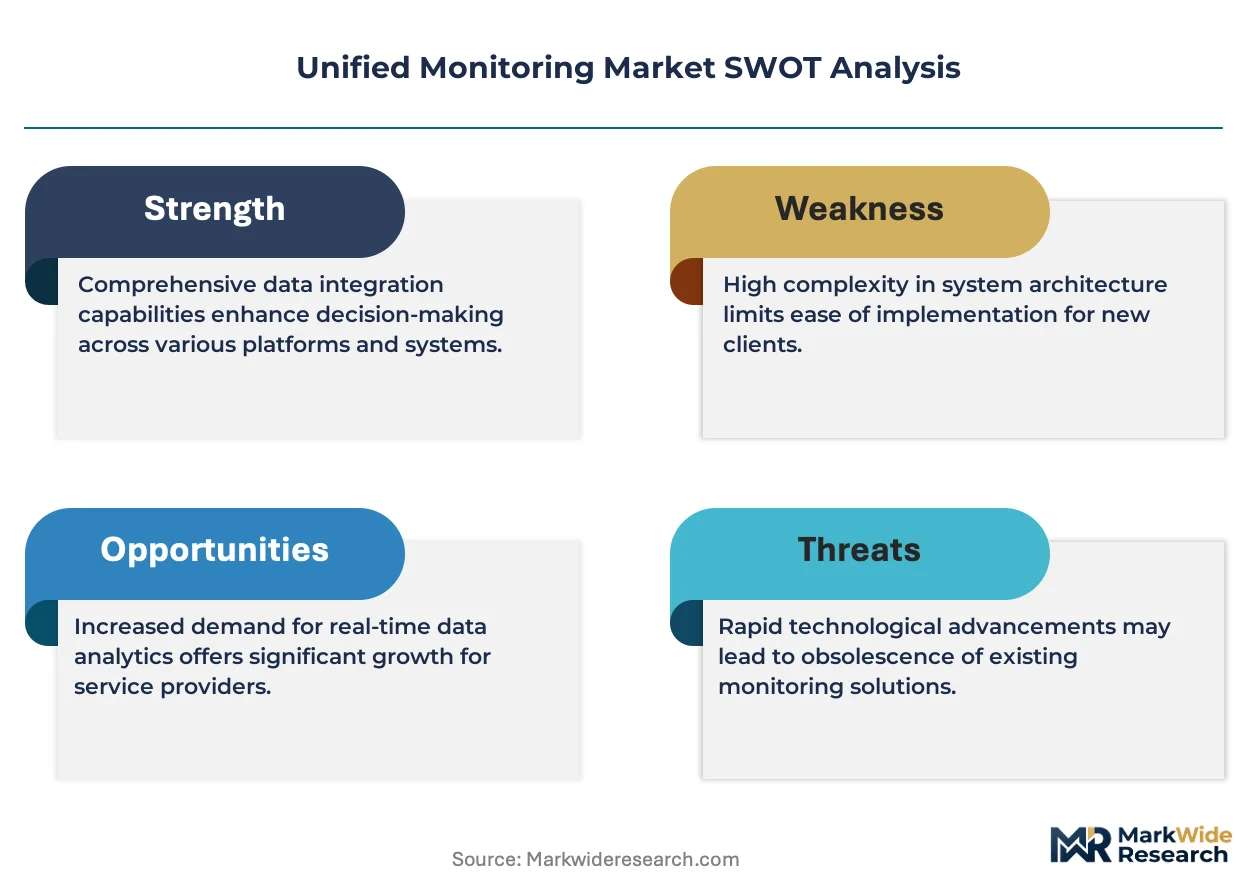
The proliferation of highly distributed and complex cloud-native architectures is the central force compelling a market shift from siloed monitoring tools toward integrated, single-pane-of-glass platforms. This transition is driven by the operational need for holistic observability across disparate IT assets.
Growth Catalysts
- AIOps Integration:The embedding of artificial intelligence for IT operations automates root cause analysis and anomaly detection, enabling teams to manage the immense data volumes generated by modern applications and infrastructure without manual intervention.
- Regulatory Mandates:Compliance frameworks, including Europe's GDPR and the US's HIPAA, require organizations to maintain auditable records of data security and system availability, directly stimulating investment in comprehensive monitoring and reporting solutions.
- Financial Services Demand:The global financial sector requires real-time performance monitoring to ensure transaction integrity, mitigate fraud, and comply with directives from regulatory bodies like the SEC, making these platforms mission-critical infrastructure.
Market Restraints
- High Total Cost of Ownership:The significant licensing and implementation costs associated with comprehensive, all-in-one unified monitoring platforms can be prohibitive for small and medium-sized enterprises with limited IT budgets.
- Legacy System Integration:Deep-rooted dependencies on proprietary, on-premises legacy systems create substantial technical friction, slowing or preventing the adoption of modern, cloud-based monitoring platforms that require open APIs for data ingestion.
- Open-Source Alternatives:The availability of powerful open-source tools like Prometheus and Grafana presents a persistent substitution threat, offering cost-effective, albeit less integrated, options for organizations with strong in-house technical expertise.
Strategic Opportunities
- Observability and Security Convergence:Integrating Security Information and Event Management (SIEM) functions with observability data provides a unified platform for both DevOps and SecOps teams, creating significant value by correlating performance issues with security events.
- Edge Computing and IoT:The expansion of IoT deployments and edge computing creates a new frontier for monitoring, presenting an opportunity for vendors to extend their platforms to manage performance and health of distributed devices and remote infrastructure.
- Expansion in Southeast Asia:Rapid digitalization and cloud adoption in emerging economies, particularly in technology hubs like Singapore and Indonesia, represent an underpenetrated market for advanced unified monitoring solutions.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of skilled Site Reliability Engineers (SREs) and DevOps professionals capable of leveraging advanced AIOps features hinders the ability of organizations to extract maximum value from their monitoring platform investments.
- Complex Migration Processes:The operational challenge of migrating data, alert configurations, and institutional knowledge from an array of disparate legacy tools to a single unified platform without causing service disruptions is a major hurdle for adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unified Monitoring Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $24.68 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge, Virtualized Solution Type: Performance Monitoring, Network Monitoring, Security Monitoring, Application Monitoring, Infrastructure Monitoring Use Case: IT Operations, Security Operations, Business Intelligence, Compliance Management, Risk Management End User: Telecommunications, Financial Services, Government Agencies, Manufacturing, Education |
| Companies Covered | Dynatrace, AppDynamics, Zenoss, Zoho Corporation, Datadog, Splunk, New Relic, Broadcom, SolarWinds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unified Monitoring Market Strategic Shifts & Innovations
The fundamental purpose of monitoring is evolving from passive data collection toward proactive, AI-driven operational intelligence. This shift transforms monitoring platforms into core systems for business resilience, moving beyond simple uptime metrics to deliver predictive insights and automated remediation.
AIOps, or AI for IT Operations, automates the analysis of vast telemetry data streams, including logs, metrics, and traces, to predict failures and accelerate root cause identification. Cloud-native enterprises and large financial institutions are rapidly adopting these capabilities to manage overwhelming system complexity. The infusion of AI into observability platforms is consolidating the market around vendors that can offer automated anomaly detection, making manual data correlation increasingly obsolete.
Europe's Digital Operational Resilience Act (DORA) imposes stringent ICT risk management and incident reporting requirements on the financial sector. This regulation compels financial entities and their critical technology partners to demonstrate continuous monitoring and verifiable system resilience. Consequently, demand for unified monitoring platforms featuring auditable logging and automated compliance reporting is intensifying across the European financial industry.
A significant behavioral shift involves enterprises moving away from procuring multiple best-of-breed, specialized monitoring tools for different parts of their IT stack. This fragmented, tool-centric purchasing model is being replaced by the adoption of single, extensible platforms providing a unified view. This strategic choice simplifies vendor management, reduces operational overhead, and is most visible among large enterprises in the United States and Western Europe.
Unified Monitoring Market Segmentation
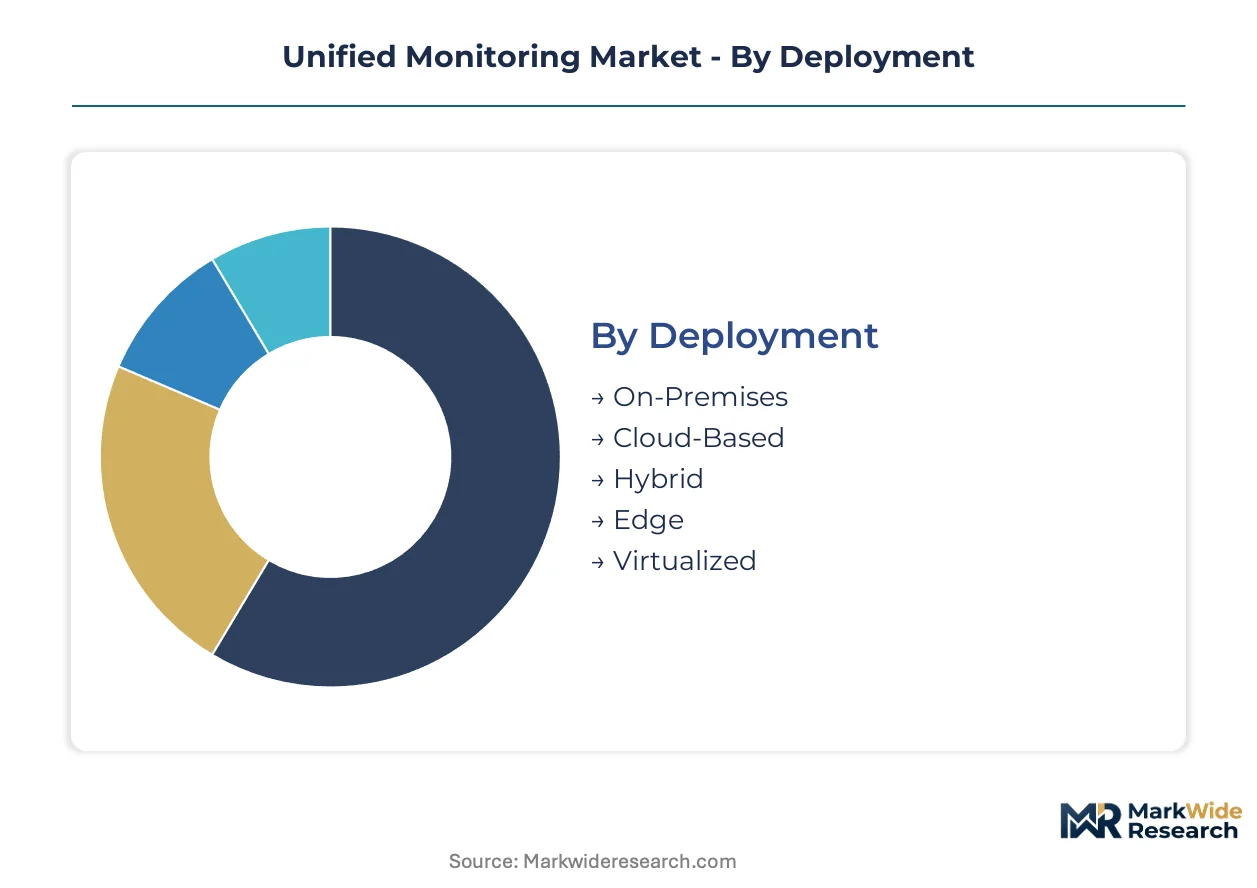
The Unified Monitoring market segmentation highlights critical distinctions in how organizations implement and consume observability solutions. Understanding these categories reveals varied operational priorities and investment patterns across different enterprise environments. Each segment reflects unique technical requirements and strategic drivers for integrated monitoring platforms.
Deployment:
Deployment choices for unified monitoring platforms significantly differentiate buyers based on their existing infrastructure, security, and operational flexibility.
- Cloud-Based:SaaS solutions hosted by the vendor, offering scalability and reduced operational overhead. Cloud-native enterprises in the United States drive demand, leveraging public cloud agility.
- Hybrid:Integrates monitoring across on-premises data centers and cloud environments, addressing complex architectures. Large financial institutions in Europe adopt hybrid models to manage sensitive data while scaling.
- On-Premises:Software on customer-managed infrastructure, favored for data sovereignty or specific security compliance.
- Edge:Monitoring capabilities for distributed edge devices and localized computing, critical for IoT and remote operational technology.
- Virtualized:Solutions deployed within virtual machine environments, providing observability for virtualized servers and network functions.
Volume sits with Cloud-Based deployments; growth tilts toward Hybrid solutions.
Solution Type:
Solution types categorize unified monitoring offerings by the specific IT layer or function they primarily address, reflecting diverse operational priorities.
- Application Monitoring:Tracks performance, availability, and user experience of software applications, including code execution. Financial services firms globally prioritize this for real-time transaction integrity and service continuity.
- Infrastructure Monitoring:Provides visibility into underlying IT infrastructure health and performance, encompassing servers, databases, and storage. Cloud-native enterprises in the United States rely on this for dynamic scaling.
- Performance Monitoring:Measures and optimizes the speed, responsiveness, and stability of IT systems and services across the stack.
- Network Monitoring:Tracks network traffic, device health, and connectivity issues, ensuring reliable data flow.
- Security Monitoring:Collects and analyzes security-related data to detect and respond to threats and vulnerabilities.
Application Monitoring and Infrastructure Monitoring form foundational revenue streams; Security Monitoring represents the fastest-growing trajectory.
Use Case:
Unified monitoring platforms address distinct organizational use cases, aligning with strategic objectives of different functional teams within an enterprise.
- IT Operations:Manages day-to-day performance, availability, and efficiency of IT systems and applications. Organizations leverage AIOps integration to automate anomaly detection and root cause analysis.
- Security Operations:Supports security operations by correlating performance data with security events, enabling rapid threat detection. SIEM and observability convergence provides a unified platform for SecOps teams.
- Business Intelligence:Uses monitoring data for insights into business process performance, customer behavior, and service impact on revenue.
- Compliance Management:Generates auditable logs and reports for regulatory mandates like GDPR and HIPAA, ensuring data security and system availability.
- Risk Management:Identifies potential system failures, security vulnerabilities, and operational bottlenecks impacting business continuity.
IT Operations commands the largest share by volume, driven by continuous operational demands across all sectors.
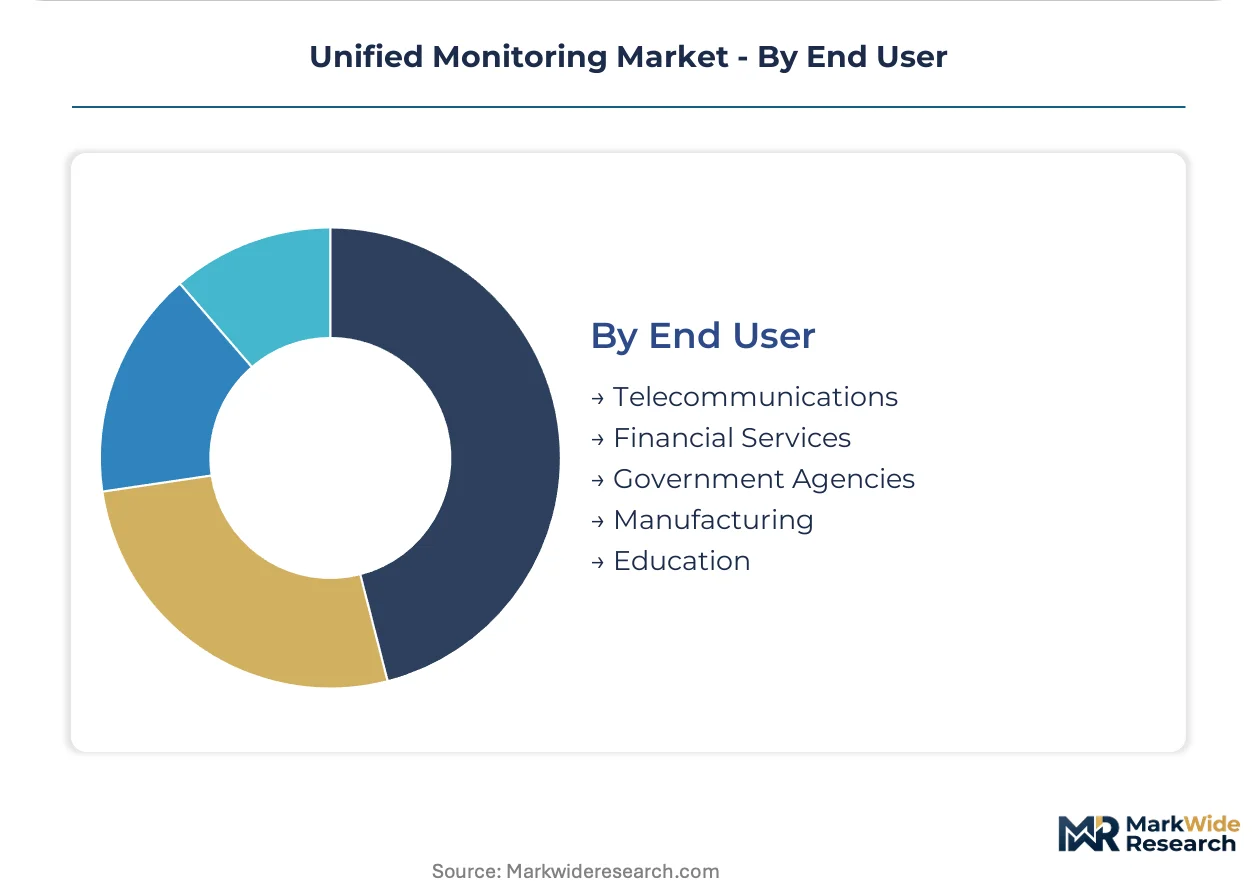
End User:
End-user segmentation highlights diverse industry verticals benefiting from unified monitoring, each with specific requirements for system resilience and data integrity.
- Financial Services:Requires real-time performance monitoring to ensure transaction integrity, mitigate fraud, and comply with SEC directives. Demand is notable in the United States, where large institutions invest heavily.
- Telecommunications:Manages complex network infrastructures, ensuring service quality and optimizing 5G/fiber optic performance. Rapid digitalization in Southeast Asia creates new demand for advanced monitoring.
- Government Agencies:Requires secure and auditable monitoring for critical public services, data protection, and national cybersecurity compliance.
- Manufacturing:Monitors OT and IT systems for predictive maintenance, supply chain optimization, and continuous production.
- Education:Manages network infrastructure, learning management systems, and student data platforms for reliable access and security.
Financial Services dominates adoption due to stringent regulatory needs, while Manufacturing is expanding its use for operational efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors the global unified monitoring market, driven by its expansive ecosystem of cloud-native enterprises and advanced data center infrastructure. This strategic positioning fosters significant demand for integrated observability solutions across diverse industry verticals. Organizations continuously seek platforms to manage complex IT environments and ensure operational resilience.
United States
Demand for unified monitoring in the United States stems from its vast concentration of cloud-native enterprises and financial services firms. HIPAA and SEC directives mandate stringent data security and system availability reporting, driving investment. Silicon Valley and major financial hubs like New York City continuously innovate in AIOps integration and comprehensive observability solutions.
Germany
German enterprises require unified monitoring for their advanced manufacturing and automotive sectors, emphasizing operational technology (OT) integration. Europe's GDPR and the upcoming DORA regulation compel organizations to ensure robust data protection and verifiable system resilience. The Rhine-Main region, with its strong industrial base, actively adopts hybrid cloud monitoring solutions to manage complex IT-OT landscapes.
Singapore
Singapore's rapid digitalization and smart nation initiatives drive demand for unified monitoring across its financial technology and logistics sectors. The Monetary Authority of Singapore (MAS) issues guidelines for technology risk management, necessitating comprehensive system oversight. Its strategic position as a Southeast Asian technology hub fosters significant adoption of cloud-based monitoring platforms for regional operations.
India
India's burgeoning IT services industry and rapidly expanding digital economy fuel substantial demand for unified monitoring solutions. The country's national cybersecurity policies and data protection frameworks influence the need for auditable logs and robust security monitoring. Bengaluru, as India's Silicon Valley, leads in adopting advanced AIOps capabilities to manage large-scale cloud deployments.
Japan
Japanese financial institutions and manufacturing giants require unified monitoring to maintain high service availability and ensure system integrity. Japan's Act on Protection of Personal Information (APPI) and industry-specific operational guidelines drive compliance-focused monitoring investments. The Tokyo metropolitan area, a global financial center, spearheads the integration of observability with security operations for enhanced resilience.
Unified Monitoring Market Key Industry Players
Global majors compete with regional champions across the unified monitoring technology stack, influencing market accessibility and innovation. The market exhibits a tiered structure, with established platform providers offering broad observability suites alongside specialized vendors focusing on niche solutions. Strategic archetypes include comprehensive platform providers, cloud-native specialists, and data analytics-centric players. Dominant competitive moves involve significant M&A activity to consolidate capabilities and strategic partnerships to expand integration ecosystems.
Specialists in AI-powered observability, such as Dynatrace, represent the advanced capabilities required for automated monitoring across complex cloud environments. Datadog, a prominent cloud-native platform provider, exemplifies the focus on broad integrations and simplified deployment for modern IT infrastructure. Splunk, a leading data analytics and security information and event management (SIEM) vendor, anchors a segment where powerful data ingestion and correlation are paramount. These firms demonstrate the varying strategic approaches to delivering holistic visibility across diverse enterprise needs.
| Leading Market Players |
|---|
| Dynatrace |
| AppDynamics |
| Zenoss |
| Zoho Corporation |
| Datadog |
| Splunk |
| New Relic |
| Broadcom |
| SolarWinds |
Cost & Logistics Intelligence
Vertical integration into platform development anchors both the supply position and pricing power for leading unified monitoring vendors. This strategic choice allows providers to control the entire observability stack, from data ingestion to advanced analytics, influencing market pricing.
Pricing Analysis
Service-level agreement bundling significantly influences pricing for unified monitoring solutions, often differentiating comprehensive platforms from modular offerings. The dominant pricing model is SaaS-tiered subscription, scaling with data volume, user count, or monitored entities. Price differentiation stems from customization level, integration depth, and specialized after-sales support. Pricing softness reflects intense competition from open-source alternatives and feature parity among commercial tools. Small and medium-sized enterprises exhibit the highest price sensitivity for foundational monitoring capabilities.
Supply Chain Analysis
Logistics for unified monitoring primarily involves digital distribution, mitigating traditional freight costs associated with physical goods. The supply of core software development talent concentrates in technology hubs across the United States, India, and parts of Europe. Key dependencies include access to skilled Site Reliability Engineers and robust cloud infrastructure capacity. A structural risk involves the scarcity of specialized AIOps talent, creating bottlenecks in advanced feature deployment. Distribution largely runs through direct sales teams and strategic channel partnerships, including cloud provider marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The unified monitoring market is currently in a technology-transition phase, as AIOps capabilities are rapidly displacing traditional, manual monitoring approaches. This shift creates distinct strategic imperatives for different market participants.
For Market Incumbents: Hedge against market fragmentation by acquiring specialized point solutions that complement existing platform capabilities. Consolidate market share through strategic partnerships with cloud hyperscalers to broaden integration ecosystems. A named threat is the sustained rise of powerful open-source alternatives, which erode pricing power for basic functionalities. Investment in advanced AIOps research and development remains a critical lever to maintain differentiation.
For New Entrants and Emerging Players: Mid-sized enterprises with complex hybrid cloud environments represent an underserved buyer archetype for unified monitoring. Target this segment by offering tailored, cost-effective solutions with simplified deployment and managed services. The most penetrable segment lies within vertical-specific compliance needs, particularly in regulated industries outside financial services. A strong go-to-market angle involves pre-built integrations for industry-specific applications and data sources.
For Investors and Strategic Acquirers: Exit pathways concentrate in established platform providers seeking to expand their feature sets or geographic reach. The long-term viability of this market over a five-to-ten-year window remains strong, driven by increasing cloud adoption and regulatory demands. An ideal acquisition target archetype is a niche AIOps or security observability specialist with proprietary intellectual property. The signal to watch is the consolidation pace among major cloud providers, indicating future integration opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Enhances ecosystem compatibility for cloud-native deployments. |
| AIOps Development | Automates anomaly detection, reducing operational overhead for IT teams. |
| Geographic Expansion | Penetrates under-served markets like Southeast Asia, capturing new customer bases. |
| Security Observability Convergence | Unifies SecOps and DevOps workflows, improving threat response. |
| Managed Services Offering | Lowers total cost of ownership for small and medium-sized enterprises. |
Research Approach
Independent corroboration across primary interviews with industry stakeholders, secondary validation from market intelligence reports, and public financial disclosures underwrites the qualitative findings. Primary research involved discussions with CTOs, DevOps engineers, IT procurement officers, and Site Reliability Engineers. Secondary data sources included regulatory filings, technology publications, cloud provider disclosures, and academic research papers. This approach employed both bottom-up and top-down triangulation to ensure data accuracy and market sizing integrity.
Rate-of-change decomposition analyzes growth drivers and restraints across the analysis window, informing the market forecast. The analytical framework modeled segmentation dimensions including deployment model, solution type, use case, end-user industry, and regional adoption patterns. Compound annual growth rates were derived from historical data trends and projected future demand. Key industry-specific forecast inputs included anticipated AIOps adoption rates and regulatory compliance spending trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to macroeconomic downturns and rapid technological shifts. Forecasts reflect assumptions documented regarding market dynamics and competitive evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Ucaas in Banking Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
United States SMS and MMS Market
Unified Communications
Cloud UC Calling Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
High Definition HD Voice Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
Unified Communication Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Ucaas in the Manufacturing Market