
 Airline Passenger Communications System Market | 2026-2036
Airline Passenger Communications System Market Size, Share, and Industry Trends Forecast 2026-2036
Airline Passenger Communications System Market Analysis
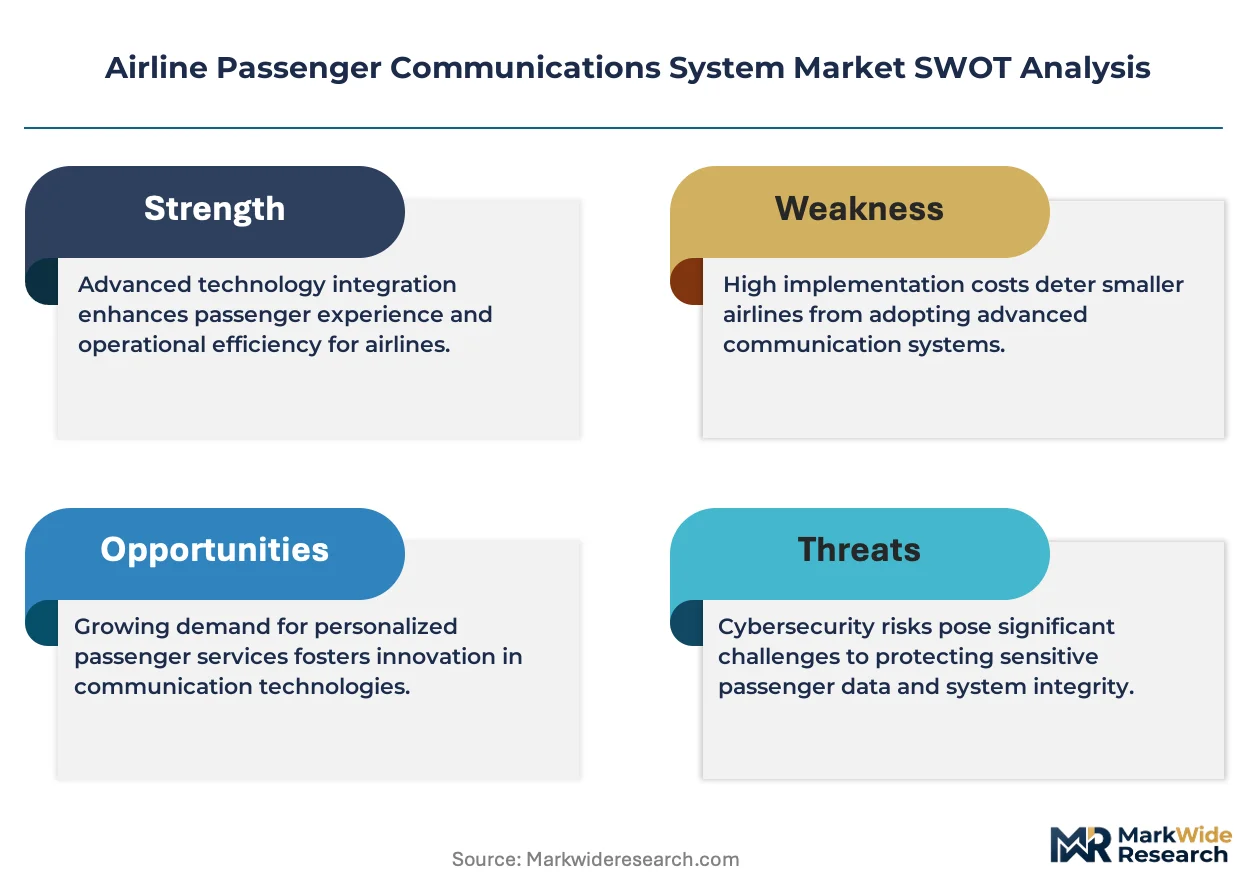
Buyer concentration among full-service carriers and premium fleet operators is hardening as these airlines consolidate vendor relationships around long-term connectivity contracts. Thales Group leverages its avionics integration depth to sustain multi-band satellite terminal programs. Viasat, Inc. competes through high-throughput Ka-band infrastructure that anchors North American fleet deployments. Honeywell International Inc. differentiates via integrated flight-deck-to-cabin communication architectures that span cockpit data link and passenger Wi-Fi domains.
An airline passenger communications system encompasses the hardware, software, and network infrastructure enabling real-time data, voice, and video exchange between aircraft and ground stations, typically operating across L-band, Ku-band, and Ka-band satellite frequencies with latency thresholds under 500 milliseconds for acceptable passenger experience. The primary commercial purpose centers on monetizing inflight connectivity through tiered service offerings while supporting crew coordination and operational telemetry. Satellite Communication leads the technology dimension due to coverage requirements over oceanic and polar routes where terrestrial alternatives fail. In-Flight Wi-Fi represents the fastest-expanding application layer as airlines bundle connectivity into loyalty programs and co-branded credit card benefits. Cloud-Based delivery models are capturing margin pools previously held by on-premise legacy stacks, particularly among low-cost carriers seeking operational flexibility without capital-heavy infrastructure commitments.
The FAA governs airworthiness certification for inflight connectivity hardware under Part 25 standards, while the FCC manages spectrum allocation for Ku and Ka bands used in domestic airspace. EASA's F-Gas Regulation and CE marking requirements shape equipment environmental compliance for European fleet operators, creating parallel certification tracks that vendors must navigate. Stakeholders should monitor pending spectrum reallocations and cybersecurity mandates from these regulators, as compliance timelines will determine which technology architectures achieve fleet-scale deployment without retrofit penalties.
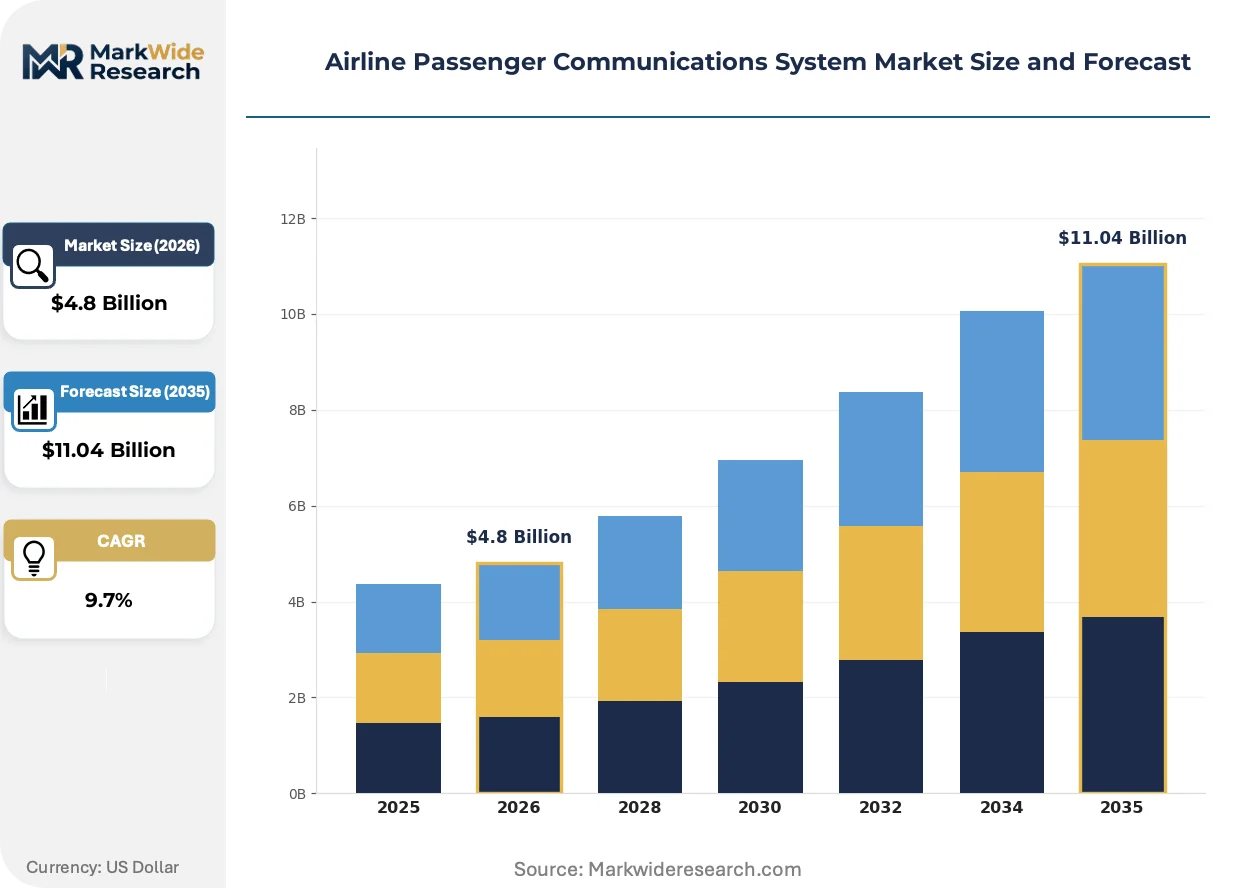
Market Dynamics
Fleet-wide connectivity mandates from full-service carriers are compressing equipment refresh cycles while Ka-band satellite deployments reshape bandwidth economics across oceanic routes.
Growth Catalysts
- FAA Part 25 Certification Streamlining:The FAA's revised airworthiness pathways for inflight connectivity hardware accelerate equipment approvals, reducing time-to-deployment for new terminal installations.
- Loyalty Program Bundling:Airlines integrate Wi-Fi access into frequent flyer tiers and co-branded credit card benefits, converting connectivity from ancillary revenue to retention infrastructure.
- China Fleet Renewal:Chinese carriers undergoing widebody replacement cycles specify factory-installed connectivity systems, embedding demand into original equipment manufacturer contracts.
Market Restraints
- Ka-band Spectrum Licensing Costs:Satellite operators face escalating orbital slot fees and national spectrum auction expenses that transmit downstream to airline customers through terminal lease structures.
- Single-Source Terminal Dependencies:Regional airlines in secondary markets encounter limited qualified installation facilities, creating geographic supply bottlenecks for STC-approved configurations.
- Terrestrial 5G Interference:C-band ground network expansion in the United States generates electromagnetic compatibility concerns that constrain antenna placement options on certain airframe types.
Strategic Opportunities
- India Low-Cost Carrier Penetration:Indian budget airlines remain largely unconnected, presenting first-mover advantages for cloud-based service delivery models that minimize upfront capital requirements.
- EASA Cybersecurity Mandates:Pending European Aviation Safety Agency network security directives will force retrofits of legacy systems, opening replacement windows for integrated flight-deck-to-cabin architectures.
- LEO-Ka Hybrid Terminals:Convergence of low-earth-orbit constellations with geostationary Ka-band infrastructure enables multi-orbit resilience that commands premium positioning in long-haul fleet specifications.
Industry Challenges
- Certified Installation Technician Scarcity:Aircraft electronics specialists with STC modification authority remain concentrated at major MRO hubs, limiting deployment velocity for regional fleet retrofits.
- Legacy ARINC 429 Integration:Older aircraft data buses require protocol gateway hardware that adds weight, complexity, and failure points to otherwise streamlined connectivity upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airline Passenger Communications System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: In-Flight Wi-Fi, Satellite Communication, 5G, VoIP Application: Entertainment Services, Emergency Communications, Flight Information, Customer Support End User: Airlines, Ground Handling Agents, Airport Authorities, Aircraft Manufacturers Delivery Model: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Honeywell International Inc., Thales Group, Airbus SE, Viasat, Inc., Wipro Limited, Collins Aerospace, Panasonic Avionics Corporation, Iridium Communications Inc., Gogo Business Aviation LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airline Passenger Communications System Market Emerging Trajectories
Software-defined networking architectures are displacing hardware-centric cabin communication systems, enabling airlines to reconfigure service tiers through remote updates rather than physical equipment swaps.
Software-defined wide area networking is decentralizing traffic management from centralized ground hubs to edge-computing nodes aboard aircraft. Low-cost carriers in Europe adopt these virtualized platforms fastest, drawn by subscription-based pricing that converts capital expenditure to operational expenditure. This architecture is decentralizing vendor lock-in, allowing airlines to switch satellite providers without replacing installed antenna hardware.
EASA's F-Gas Regulation tightens environmental compliance for cabin electronics cooling systems, compelling equipment redesigns that eliminate hydrofluorocarbon refrigerants. Manufacturers serving European fleet operators now engineer liquid-cooled terminals with natural convection alternatives. Full-service carriers with mixed US-Europe operations face parallel certification tracks that extend product development timelines.
Enterprise procurement teams now unbundle connectivity hardware from network service contracts, reversing decade-long bundled leasing conventions. Airlines with technical evaluation capabilities source antennas and modems separately from bandwidth agreements, pressuring integrated solution providers to componentize offerings. This pattern concentrates among North American and German flag carriers with established engineering departments capable of managing multi-vendor integrations.
Airline Passenger Communications System Market Segmentation
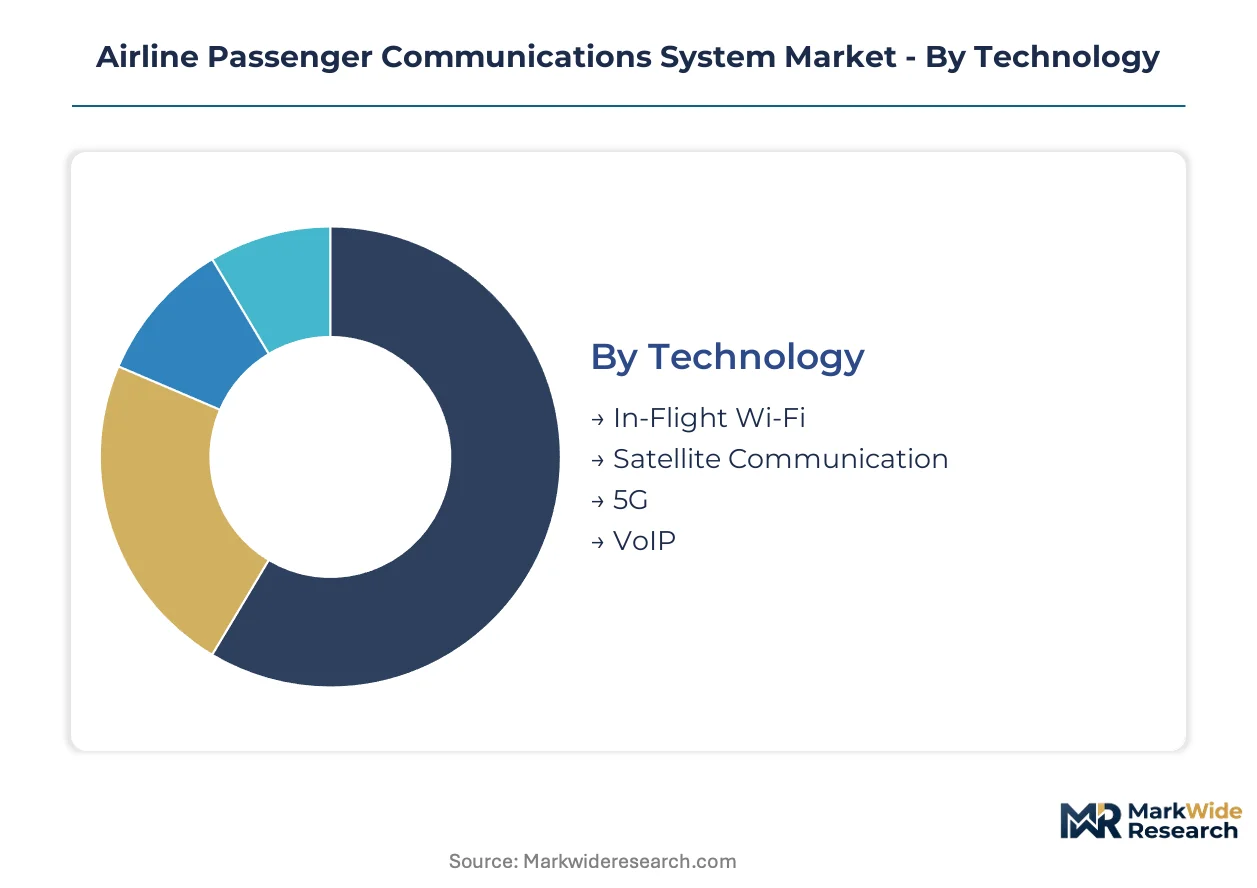
Technology integration depth varies sharply across deployment architectures in the airline passenger communications system market. Standalone systems serve discrete functions while embedded architectures fuse multiple capabilities into unified platforms, reshaping vendor competitive boundaries and airline procurement patterns.
Technology:
Integration depth spans from standalone passenger-facing services to deeply embedded avionics-integrated systems that share antenna infrastructure with flight-deck communications.
- Satellite Communication:Multi-band terminals operating across L-band, Ku-band, and Ka-band frequencies provide coverage over oceanic and polar routes where terrestrial networks fail. Demand concentrates in United States and China where full-service carriers mandate fleet-wide connectivity for premium cabin differentiation.
- In-Flight Wi-Fi:Cabin distribution systems leverage satellite or air-to-ground backhaul to deliver passenger internet access with latency thresholds under 500 milliseconds. European low-cost carriers bundle Wi-Fi into loyalty programs, converting connectivity from ancillary revenue to retention infrastructure.
- 5G:Direct air-to-ground cellular links using dedicated aviation spectrum bands enable high-throughput connectivity over continental landmasses.
- VoIP:Voice-over-IP cabin telephony systems integrate with satellite backhaul for passenger and crew calling services.
Volume placements concentrate in Satellite Communication; the faster expansion belongs to In-Flight Wi-Fi.
Application:
Cost tier differentiation separates regulatory-mandated safety systems from discretionary passenger experience investments that carriers modulate based on yield management priorities.
- Emergency Communications:Regulatory-mandated systems enable real-time coordination between flight crews and ground-based response centers during critical incidents. FAA Part 25 certification requirements and EASA safety directives drive standardization across United States and European fleet operators.
- Entertainment Services:Streaming media platforms, live television, and gaming services consume substantial bandwidth and require quality-of-service prioritization. Chinese carriers undergoing widebody replacement cycles specify factory-installed entertainment systems, embedding demand into OEM contracts.
- Flight Information:Real-time data feeds display arrival times, connecting gates, and baggage claim details to passenger devices.
- Customer Support:Two-way messaging and chat interfaces connect passengers with airline service agents during flight.
Deployment scale favors Emergency Communications; Entertainment Services are climbing the fastest as monetization models mature.
End User:
Customer type fragmentation creates divergent procurement patterns between fleet-owning airlines and infrastructure-managing ground service providers.
- Airlines:Fleet operators specify connectivity architectures during aircraft acquisition or retrofit programs, controlling passenger-facing service tiers. Full-service carriers in Germany and the United States consolidate vendor relationships around long-term connectivity contracts spanning multiple aircraft generations.
- Aircraft Manufacturers:Boeing and Airbus embed connectivity systems as line-fit options during final assembly, capturing specification authority before airline delivery. Factory-installed configurations in China reduce retrofit complexity and accelerate fleet-wide deployment timelines.
- Ground Handling Agents:Service providers manage passenger communication touchpoints within terminal facilities and during aircraft turnaround processes.
- Airport Authorities:Infrastructure operators invest in gate-area and terminal connectivity that hand off seamlessly to airborne systems.
Procurement authority concentrates in Airlines; the steepest expansion trajectory belongs to Aircraft Manufacturers as line-fit penetration deepens.
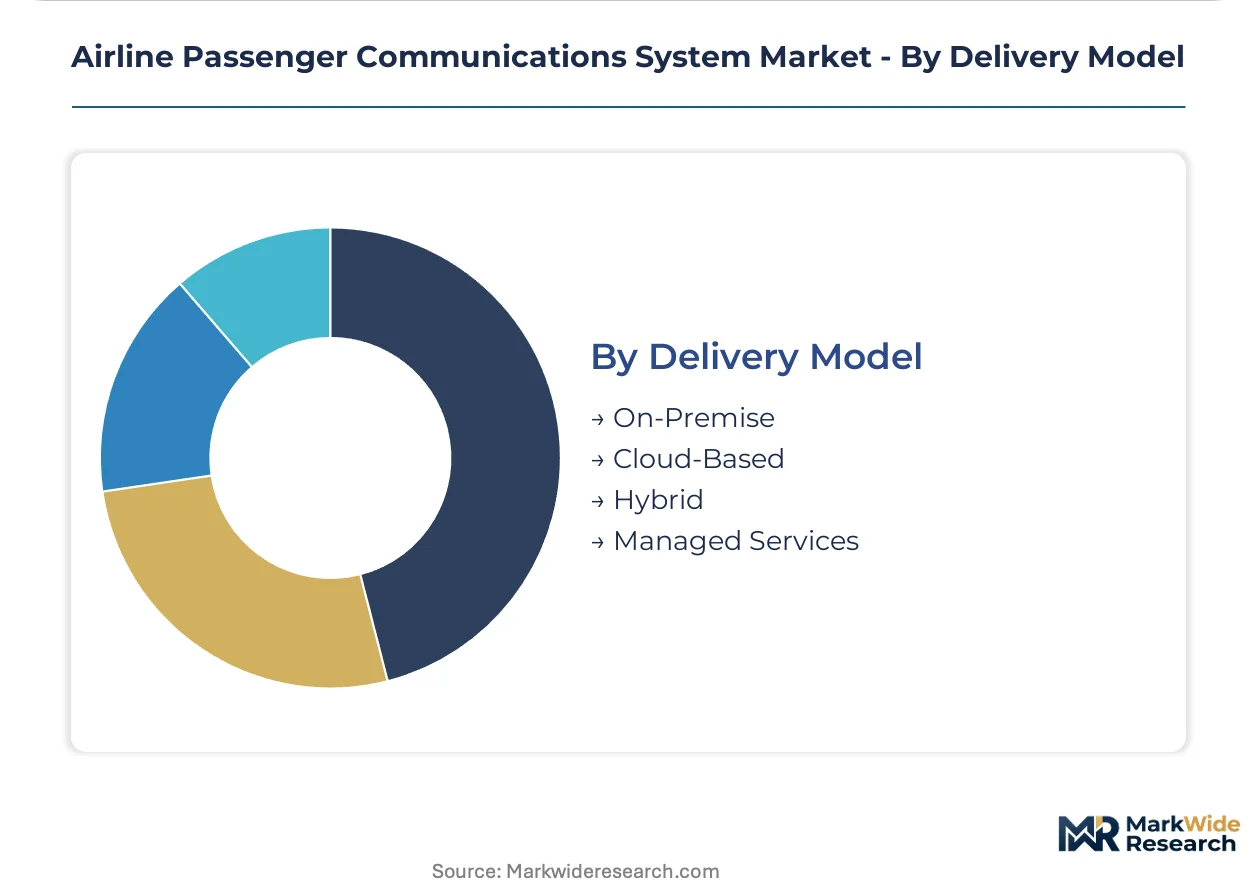
Delivery Model:
Margin structure varies across capital-intensive ownership models versus subscription-based operational expenditure frameworks that appeal to budget-constrained operators.
- Cloud-Based:Virtualized platforms enable remote service reconfiguration and satellite provider switching without physical hardware replacement. European low-cost carriers adopt these subscription models fastest, drawn by operational flexibility without capital-heavy infrastructure commitments.
- Managed Services:End-to-end outsourcing bundles hardware, bandwidth, and technical support into per-aircraft or per-passenger pricing. Indian budget airlines leverage managed service structures to overcome certified installation technician scarcity in secondary markets.
- On-Premise:Carrier-owned infrastructure requires substantial upfront capital deployment and internal technical expertise.
- Hybrid:Mixed architectures combine owned core systems with cloud-managed edge services for selective outsourcing.
Contract value concentrates in Managed Services; Cloud-Based delivery is gaining share fastest among new market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium arsenide substrate production in the United States anchors semiconductor supply chains for satellite terminal fabrication. German precision manufacturing clusters supply avionics-grade connectivity hardware to European fleet operators. Chinese rare earth processing capabilities feed magnet and antenna component demand across Asia-Pacific assembly lines.
United States
FAA Part 25 certification streamlining accelerates terminal approvals for full-service carriers retrofitting widebody fleets. The FCC manages Ku and Ka band spectrum allocation for domestic airspace operations. Seattle-Tacoma aerospace corridor concentrates STC-approved installation facilities serving Alaska Airlines and Delta fleet programs.
Germany
Lufthansa Group mandates fleet-wide connectivity specifications embedding demand into long-term vendor contracts. EASA F-Gas Regulation tightens environmental compliance for cabin electronics cooling systems. Hamburg aircraft interiors cluster hosts modification centers specializing in liquid-cooled terminal retrofits for mixed US-Europe operations.
China
COMAC C919 production ramp and widebody replacement cycles specify factory-installed connectivity systems. MIIT coordinates aviation spectrum allocation alongside satellite operator licensing frameworks. Shanghai Pudong aerospace zone concentrates OEM line-fit integration capacity for Air China and China Eastern fleet deliveries.
India
IndiGo and SpiceJet fleet expansion creates first-mover opportunities for cloud-based service delivery models. TRAI governs satellite communication licensing for aviation applications. Bangalore aviation MRO hub develops certified installation technician training programs addressing regional retrofit bottlenecks.
United Kingdom
British Airways and Virgin Atlantic loyalty program bundling converts connectivity into retention infrastructure. Civil Aviation Authority implements EASA-aligned cybersecurity mandates for network security compliance. London Gatwick modification centers specialize in legacy ARINC 429 protocol gateway integration for narrowbody retrofits.
Airline Passenger Communications System Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined virtualization and LEO-Ka hybrid architectures. The vendor base organizes around three archetypes: integrated avionics conglomerates with multi-band satellite terminal programs, high-throughput infrastructure specialists anchoring North American deployments, and cloud-native service platforms targeting low-cost carrier operational expenditure models. Consolidation pressure intensifies through long-term connectivity contract bundling and fleet-scale deployment mandates. Strategic partnerships between satellite operators and terminal manufacturers reshape competitive boundaries faster than capacity expansion alone.
Within the integrated systems tier, Honeywell International Inc. and Thales Group exemplify flight-deck-to-cabin architecture providers spanning cockpit data link and passenger Wi-Fi domains. Viasat, Inc. occupies a position among high-throughput Ka-band infrastructure anchors serving North American fleet deployments. These three entities represent divergent strategic postures: conglomerate diversification, satellite-native vertical integration, and avionics-led platform consolidation.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Thales Group |
| Airbus SE |
| Viasat, Inc. |
| Wipro Limited |
| Collins Aerospace |
| Panasonic Avionics Corporation |
| Iridium Communications Inc. |
| Gogo Business Aviation LLC |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FAA Part 25-approved terminals and uncertified commercial hardware manifests in both procurement premiums and supply chain tiering. Airlines with mixed US-Europe operations absorb parallel certification tracks through extended vendor qualification cycles, while budget carriers bypass capital-heavy ownership models entirely.
Pricing Analysis
Warranty and service bundling separates integrated managed-service contracts from unbundled hardware-plus-bandwidth procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and installation complexity. Price differentiation hinges on STC modification authority and geographic technician availability. Cost compression in regional airline retrofits is intensifying because certified installation facilities remain concentrated at major MRO hubs. Low-cost carriers exhibit highest price sensitivity; full-service flag carriers with engineering departments show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Boeing and Airbus line-fit programs, while aftermarket retrofit flows through STC-approved modification centers. Gallium arsenide substrate production in the United States, German precision manufacturing clusters, and Chinese rare earth processing capabilities anchor component sourcing. Terminal fabrication draws from semiconductor foundries, avionics-grade machine shops, and magnet/antenna component suppliers. Single-source vulnerability concentrates in gallium arsenide wafer supply. Distribution runs through OEM line-fit, airline direct procurement, and MRO channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term connectivity contract bundling is forcing weaker vendors out as full-service carriers consolidate around multi-aircraft-generation supplier relationships.
For Market Incumbents: Anticipate EASA cybersecurity mandates compressing replacement windows for legacy architectures. Backward integration into gallium arsenide substrate supply hedges semiconductor chokepoint exposure. Investment in liquid-cooled terminal R&D secures F-Gas Regulation compliance for European fleet operators. For New Entrants and Emerging Players: Satellite operator partnerships provide fastest path to fleet-scale credibility without captive infrastructure. Indian budget airlines present most penetrable segment given minimal existing connectivity penetration. Cloud-native managed service models convert capital expenditure to operational expenditure for price-sensitive buyers. For Investors and Strategic Acquirers: Re-rating potential sits with software-defined virtualization specialists given airline procurement teams unbundling hardware from network service contracts. Five-to-ten-year viability favors platforms with multi-orbit terminal architectures. Watch for LEO-Ka hybrid terminal certification milestones as inflection indicator for technology obsolescence cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Terminal Certification | FAA and EASA approvals for LEO-Ka hybrid architectures unlock premium fleet specifications. |
| Cloud-Based Service Platform Launch | Subscription models attract Indian and European low-cost carriers seeking operational flexibility. |
| Backward Integration into GaAs Supply | Captive semiconductor sourcing mitigates single-source substrate vulnerability for terminal fabrication. |
| STC-Approved Installation Network Expansion | Bangalore and secondary MRO hubs address certified technician scarcity constraining regional retrofits. |
| EASA Cybersecurity Compliance Retrofit | Network security directive adherence opens replacement windows for integrated flight-deck-to-cabin systems. |
Methodological Framework
FAA certification databases, EASA regulatory filings, and satellite operator spectrum allocation records formed the secondary backbone for equipment approval timeline analysis. Primary interviews with avionics procurement directors, MRO modification center managers, airline connectivity strategy leads, and satellite terminal engineering heads validated deployment velocity assumptions. Bottom-up triangulation across fleet installation schedules and top-down cross-check against satellite capacity expansion announcements anchored market sizing.
Bottom-up modeling across technology, application, end user, and delivery model dimensions drove volume projections over the analysis window. Segmentation spans satellite communication, in-flight Wi-Fi, 5G, and VoIP technologies; emergency communications, entertainment services, flight information, and customer support applications; airlines, aircraft manufacturers, ground handling agents, and airport authority end users; cloud-based, managed services, on-premise, and hybrid delivery models. CAGRs derived from fitted growth curves against fleet renewal cycle timing and regulatory mandate implementation schedules. Industry-specific inputs include STC modification capacity constraints and Ka-band spectrum licensing cost trajectories.
Several conditions sit outside the modeled scope, including geopolitical disruption to rare earth supply chains and unannounced satellite constellation bankruptcies. Forecasts reflect assumptions about FAA certification streamlining continuity and EASA cybersecurity directive finalization timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Ucaas in the Manufacturing Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Cloud UC Calling Market
Unified Communications
Unified Communication Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
Unified Monitoring Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
United States SMS and MMS Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
Business Cloud Voip and UC Services Market
Unified Communications
High Definition HD Voice Market