
 Global Cloud Monitoring Market | 2026-2036
Global Cloud Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Monitoring Market Foresight
Healthcare and life sciences is pivoting toward cloud-native architectures, creating fresh demand for telemetry platforms that track containerized workloads across distributed environments. IBM Corporation leverages its hybrid cloud footprint to anchor enterprise clients with on-premise-to-public bridge monitoring. Datadog sustains product velocity through deep Kubernetes and serverless instrumentation that developers prefer. Dynatrace LLC differentiates via AI-driven root-cause analysis that reduces mean-time-to-resolution for complex microservices failures.
Cloud monitoring encompasses the continuous collection, analysis, and alerting of performance metrics, logs, and traces across virtualized compute, storage, and network resources delivered via internet-based service models. The discipline relies on agent-based and agentless data ingestion at sub-minute granularity, with distributed tracing standards such as OpenTelemetry enabling cross-platform correlation of request flows through service meshes. Infrastructure Monitoring commands the largest revenue share among solution types because every cloud migration begins with visibility into compute utilization and storage latency. Application Performance Management is expanding fastest as organizations instrument custom software with code-level profiling to isolate memory leaks and thread contention in production environments. Security Monitoring carries outsized margin potential due to compliance mandates that require immutable log retention and real-time threat detection across ephemeral cloud assets.
FDA 21 CFR Part 11 requirements for electronic records in healthcare push cloud monitoring vendors to implement tamper-evident audit logging and access controls. The EU AI Act imposes conformity assessments on automated decision systems, which demands observability pipelines that document model inference inputs and drift events. ISO 27017 and SOC 2 Type II frameworks shape procurement criteria by mandating encryption key rotation visibility and privileged access monitoring in multi-tenant architectures. Stakeholders must evaluate whether their current tooling can map regulatory controls to specific cloud resource configurations without manual policy translation.
Market Dynamics
Multi-cloud sprawl is fragmenting observability architectures, forcing enterprises to consolidate telemetry pipelines across AWS, Azure, and Google Cloud environments rather than managing siloed monitoring stacks.
Growth Catalysts
- EU AI Act Conformity Assessments:Automated decision systems in European financial services and healthcare require real-time observability that documents model inference inputs and drift events.
- Kubernetes-Native Workloads:Container orchestration at scale generates exponential telemetry volumes that legacy agent-based tools cannot ingest, pulling demand toward OpenTelemetry-compatible platforms.
- FDA 21 CFR Part 11:Electronic records mandates in pharmaceutical manufacturing compel tamper-evident audit logging and access control visibility across cloud-hosted clinical trial systems.
Market Restraints
- Hyperscaler Concentration Risk:AWS, Microsoft Azure, and Google Cloud control 67% of infrastructure-as-a-service capacity, creating vendor lock-in that complicates multi-cloud monitoring standardization.
- Ephemeral Asset Tracking Costs:Serverless functions and spot instances spin up and down in seconds, requiring sub-minute granularity ingestion that multiplies data storage expenditures.
- Encryption Key Rotation Visibility:SOC 2 Type II and ISO 27017 mandates for key lifecycle documentation impose architectural constraints that legacy monitoring stacks cannot satisfy without re-platforming.
Strategic Opportunities
- Edge-to-Cloud Telemetry Convergence:Manufacturing and energy sectors are deploying 5G-connected industrial IoT sensors that require unified observability spanning factory floors and public cloud regions.
- India's Data Localization Requirements:RBI and CERT-In directives on financial data residency are creating demand for sovereign cloud monitoring infrastructure with in-country data processing.
- Outcome-Based Pricing Models:Mean-time-to-resolution guarantees and incident reduction SLAs are displacing per-seat licensing, opening margin expansion for vendors with predictive AI capabilities.
Industry Challenges
- OpenTelemetry Standardization Gaps:Instrumentation libraries vary across programming languages, forcing engineering teams to maintain custom exporters that delay production deployments.
- Observability Engineer Talent Scarcity:Hybrid skill requirements spanning distributed systems, SRE practices, and compliance frameworks command premium compensation that mid-market enterprises cannot sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Monitoring Market |
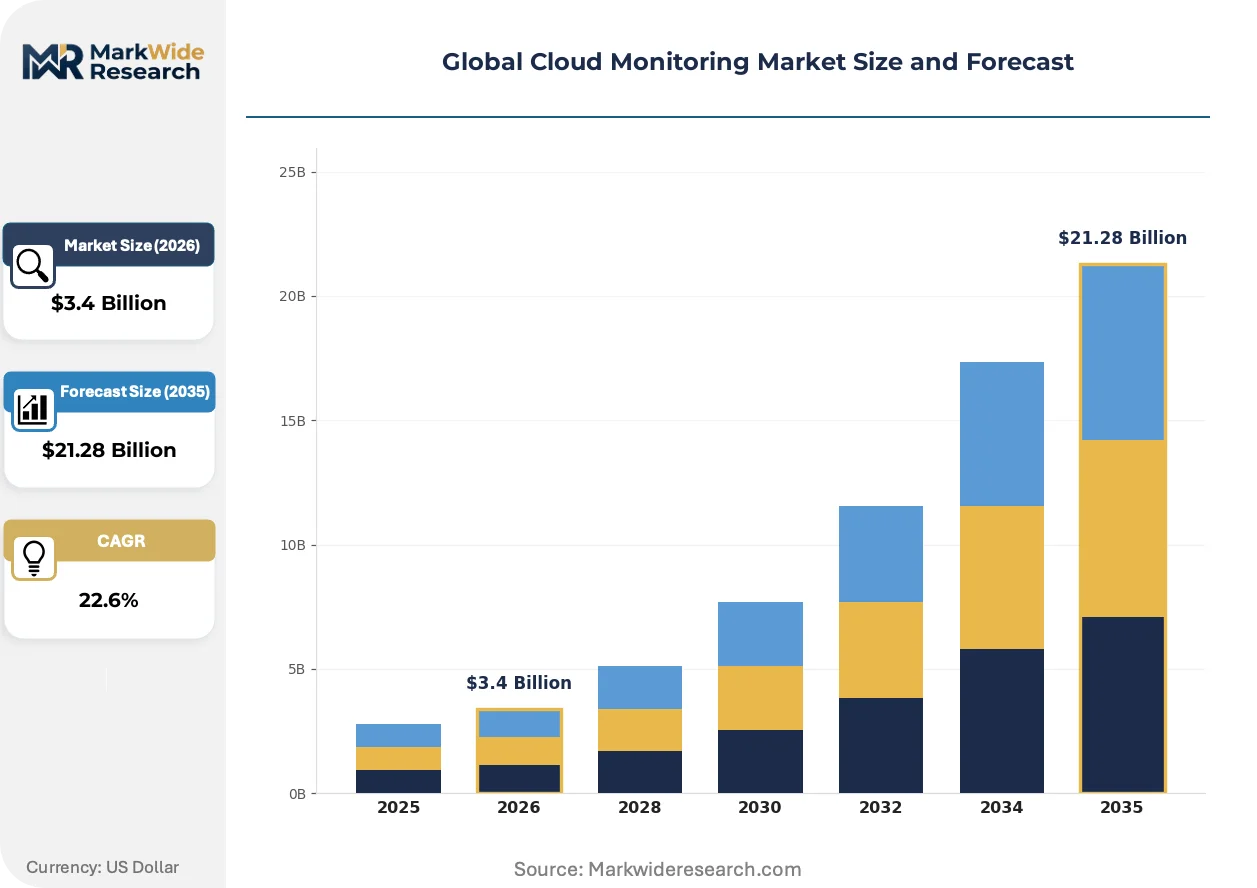
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $21.28 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Infrastructure Monitoring, Application Performance Management, Network Monitoring, Log Analytics, Security Monitoring End User Industry: Telecommunications, E-Commerce, Banking & Finance, Manufacturing, Media & Entertainment Service Model: Software as a Service, Platform as a Service, Infrastructure as a Service, Managed Services |
| Companies Covered | IBM Corporation, Datadog, Amazon Web Services, Inc., Cisco Systems, Inc., Dynatrace LLC, Microsoft, Oracle, LogicMonitor Inc., Alphabet Inc. (Google Cloud), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Monitoring Market Shifts & Advancements
Telemetry pipelines are absorbing AI-driven anomaly detection that compresses alert fatigue while extending automation into root-cause remediation workflows previously requiring human intervention.
eBPF kernel instrumentation is absorbing packet-level visibility without agent deployment overhead. Telecommunications providers and high-frequency trading firms are adopting this Linux-native technology to achieve microsecond-granularity network telemetry. The approach is absorbing market share from traditional SNMP-based monitoring by eliminating blind spots in containerized environments.
CSRD sustainability reporting mandates in the European Union are compelling cloud monitoring vendors to embed carbon intensity metrics alongside performance telemetry. Data center energy consumption must now trace to specific workloads for Scope 3 emissions disclosure. Financial services institutions in Frankfurt and Amsterdam are procuring platforms with built-in carbon accounting to satisfy 2025 filing deadlines.
Platform engineering teams are consolidating observability procurement under centralized internal developer platforms. Site reliability engineering groups are displacing fragmented tool sprawl with unified telemetry backends that expose metrics, logs, and traces through single-pane APIs. This consolidation pattern is most visible among technology-forward enterprises in the United States and United Kingdom.
Global Cloud Monitoring Market Segmentation
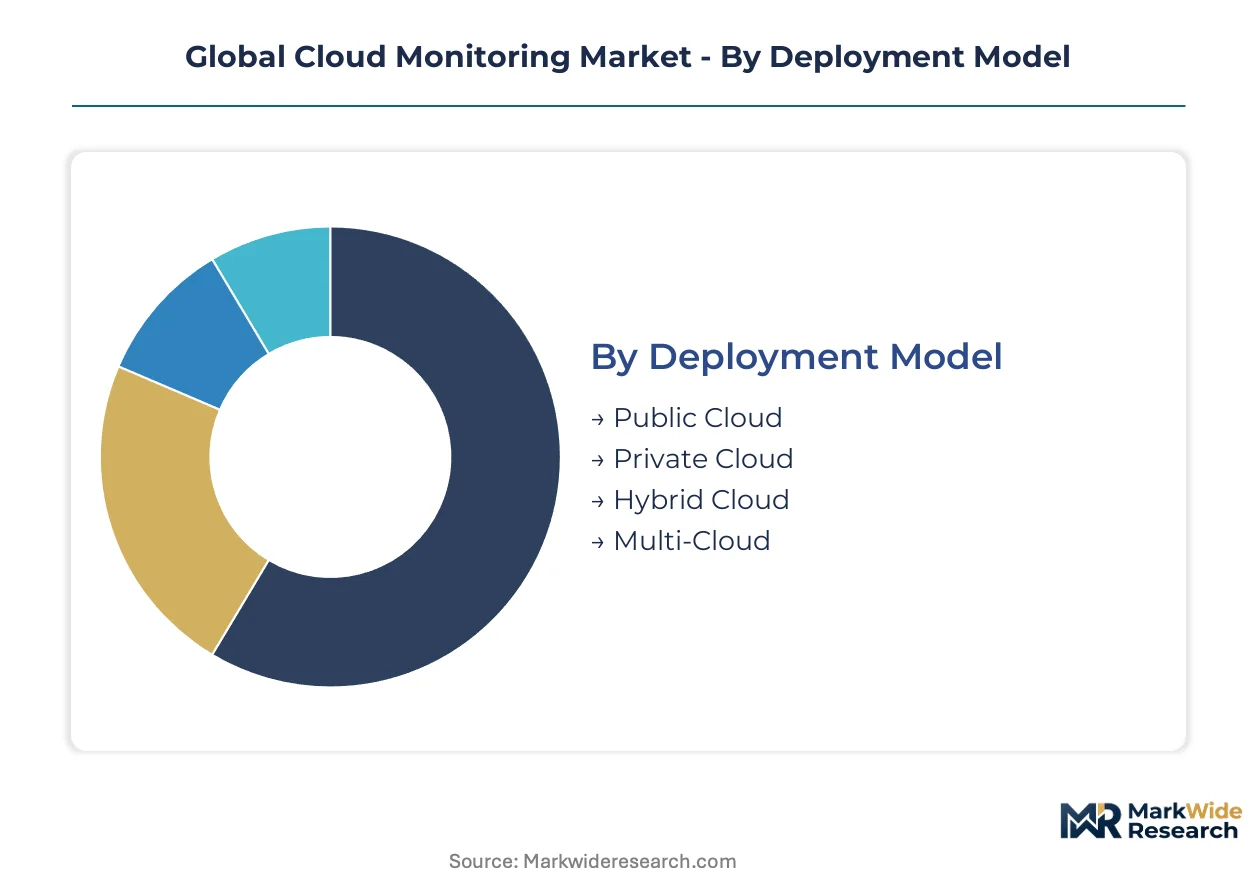
Cloud monitoring procurement patterns diverge sharply across deployment architectures and compliance postures. Buyers segment their investments based on data sovereignty requirements, workload distribution complexity, and the granularity of telemetry needed for regulatory documentation.
Deployment Model:
Volume concentrates in single-tenant configurations, while premium pricing attaches to orchestrated multi-cloud visibility.
- Public Cloud:Agentless ingestion dominates AWS, Azure, and Google Cloud environments where native tooling provides baseline visibility. Banking & Finance workloads in the United States and Germany drive demand for SOC 2 and GDPR-compliant telemetry pipelines that overlay hyperscaler primitives.
- Hybrid Cloud:Bridging on-premise VMware or OpenStack estates with public cloud regions requires unified control planes that correlate legacy SNMP metrics with cloud-native traces. Manufacturing firms in Japan and Germany prioritize this architecture to preserve capital equipment monitoring while migrating transactional systems.
- Private Cloud:Dedicated OpenShift or CloudStack deployments serve defense contractors and pharmaceutical manufacturers with air-gapped compliance mandates.
- Multi-Cloud:Federated observability across three or more hyperscalers commands the highest contract values but imposes architectural complexity for trace correlation and cost attribution.
Today's leader: Public Cloud. Tomorrow's challenger: Multi-Cloud.
Solution Type:
Application-centric tooling is climbing the fastest as microservices architectures proliferate, while infrastructure visibility remains the procurement entry point.
- Infrastructure Monitoring:Compute utilization, storage latency, and network throughput telemetry form the foundation of every cloud migration. E-Commerce platforms in India and Brazil deploy these tools first to right-size EC2 and Azure VM commitments before expanding coverage.
- Application Performance Management:Code-level profiling and distributed tracing capture memory leaks and thread contention in containerized production environments. Telecommunications providers in South Korea and the United Kingdom instrument 5G core networks with these capabilities to meet latency SLAs.
- Network Monitoring:East-west traffic visibility within Kubernetes clusters and service meshes addresses blind spots that traditional perimeter tools miss.
- Log Analytics:Centralized aggregation of structured and unstructured events supports forensic investigation and compliance audit trails for FDA 21 CFR Part 11 and EU AI Act documentation.
- Security Monitoring:Immutable log retention and real-time threat detection across ephemeral serverless functions carry the highest margin profile due to stringent ISO 27017 and SOC 2 Type II mandates.
Infrastructure Monitoring anchors current spending. Application Performance Management is expanding most quickly.
End User Industry:
Financial services outspends other verticals on a per-workload basis, while manufacturing presents the largest addressable expansion opportunity.
- Banking & Finance:Real-time fraud detection and algorithmic trading systems demand sub-second anomaly detection with automated escalation. RBI data localization rules in India and ECB oversight in Frankfurt impose sovereign cloud monitoring requirements.
- Telecommunications:5G network slicing and edge computing deployments generate telemetry volumes that legacy probe systems cannot ingest. NTT and Deutsche Telekom are consolidating observability under vendor-agnostic OpenTelemetry pipelines.
- E-Commerce:Flash sale events and seasonal traffic spikes require auto-scaling visibility that correlates customer journey metrics with infrastructure health.
- Manufacturing:Industrial IoT sensor networks and digital twin implementations are creating greenfield demand for edge-to-cloud telemetry convergence.
- Media & Entertainment:Global content delivery networks and live streaming platforms prioritize CDN performance monitoring and audience quality-of-experience metrics.
Banking & Finance sets the premium benchmark. Manufacturing offers the steepest expansion trajectory.
Service Model:
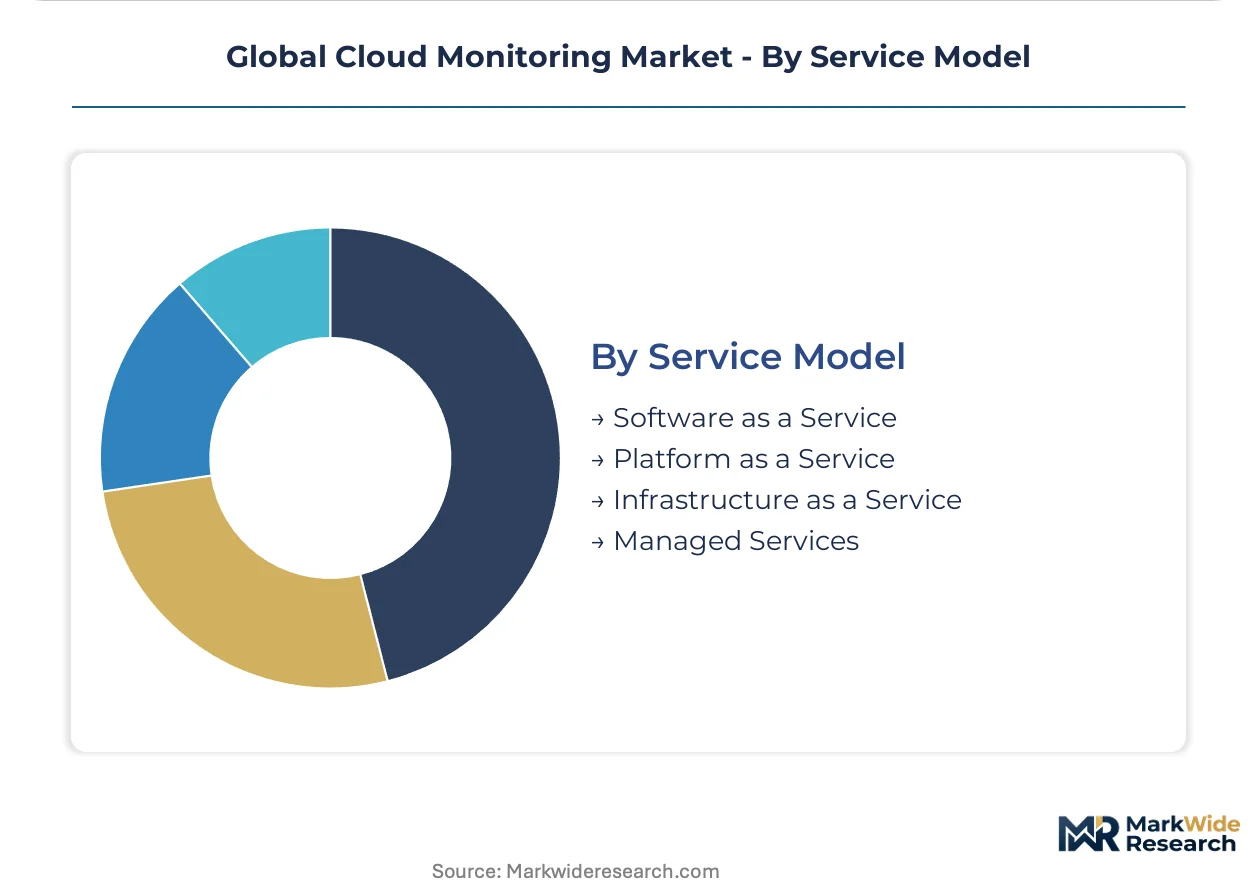
Managed services capture the highest renewal rates, while self-service platforms dominate developer-led procurement.
- Software as a Service:Pre-configured dashboards and alert policies accelerate time-to-value for mid-market enterprises without dedicated SRE teams. German Mittelstand firms favor EU-hosted SaaS instances to satisfy GDPR data residency.
- Platform as a Service:Custom instrumentation libraries and API-first telemetry backends appeal to technology-forward enterprises building internal developer platforms.
- Infrastructure as a Service:Raw compute and storage monitoring capabilities are increasingly commoditized, pressuring standalone vendors to differentiate through AI-driven analytics layers.
- Managed Services:24/7 operations center coverage and mean-time-to-resolution guarantees displace in-house observability engineering for cost-conscious healthcare and retail organizations.
Software as a Service owns current volume. Managed Services is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley hyperscaler density drives premium demand for multi-cloud visibility tools that correlate telemetry across distributed workloads. Financial services institutions in New York and London are expanding observability budgets to manage containerized architectures. Regulatory complexity in Frankfurt and Singapore is compelling real-time monitoring with automated audit trails.
United States
Banking conglomerates in New York deploy sub-second anomaly detection for algorithmic trading systems. The SEC mandates immutable log retention for electronic trading records. Seattle's cloud infrastructure cluster anchors enterprise observability development for hybrid cloud bridging.
Germany
Automotive manufacturers in Stuttgart instrument digital twin implementations with edge-to-cloud telemetry convergence. The EU AI Act imposes conformity assessments on automated decision systems in Frankfurt's financial district. Bavaria's industrial IoT sensor networks require unified observability spanning factory floors and public cloud regions.
United Kingdom
Telecommunications providers in London consolidate observability under OpenTelemetry pipelines for 5G network slicing. The FCA's operational resilience directives mandate real-time system monitoring with documented recovery procedures. The Thames Valley technology corridor hosts platform engineering teams centralizing procurement under internal developer platforms.
India
E-commerce platforms in Bangalore deploy infrastructure monitoring to right-size cloud commitments before expanding coverage. RBI data localization rules and CERT-In directives create demand for sovereign cloud monitoring infrastructure with in-country data processing. Mumbai's financial services sector requires multi-cloud visibility tools compliant with electronic records mandates.
Japan
Manufacturing firms in Toyota City prioritize hybrid cloud architectures to preserve capital equipment monitoring while migrating transactional systems. METI's cybersecurity frameworks shape procurement criteria for encryption key rotation visibility. Tokyo's telecommunications sector instruments 5G core networks with distributed tracing to meet latency SLAs.
Global Cloud Monitoring Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors integrate AI-driven analytics layers atop commoditized infrastructure monitoring. The vendor base clusters around three distinct tiers: hyperscalers bundling native tooling, independent observability platforms with OpenTelemetry compatibility, and specialized security monitoring providers. Two strategic archetypes have emerged: full-stack platforms consolidating metrics, logs, and traces under unified APIs; and point-solution specialists embedding carbon accounting or compliance documentation. M&A activity and outcome-based pricing models represent the dominant competitive vectors reshaping contract structures.
Within the full-stack platform tier, IBM Corporation and Datadog exemplify contrasting approaches to enterprise anchoring. IBM leverages its hybrid cloud footprint to bridge on-premise estates with public cloud regions for manufacturing and pharmaceutical clients. Datadog sustains product velocity through developer-preferred instrumentation for Kubernetes and serverless environments. Dynatrace LLC occupies a position in the AI-driven diagnostics segment, with its root-cause analysis capabilities reducing resolution times for microservices failures.
| Leading Market Players |
|---|
| IBM Corporation |
| Datadog |
| Amazon Web Services, Inc. |
| Cisco Systems, Inc. |
| Dynatrace LLC |
| Microsoft |
| Oracle |
| LogicMonitor Inc. |
| Alphabet Inc. (Google Cloud) |
| Others |
Supply & Pricing Matrix
EU AI Act conformity assessments for automated decision systems are compelling financial services and healthcare buyers to procure premium observability tiers with embedded compliance documentation, forcing vendors to absorb specialized engineering costs into subscription pricing while maintaining competitive entry points for mid-market SaaS adoption.
Pricing Analysis
Input-cost pass-through from OpenTelemetry instrumentation development and AI model training infrastructure is stratifying pricing across three tiers. Premium contracts for financial services in Frankfurt and New York command differentiation through SOC 2 Type II audit-ready telemetry pipelines and sub-second anomaly detection SLAs. Price erosion runs through the self-service SaaS segment as Datadog, Dynatrace, and emerging challengers compete for developer-led procurement with freemium consumption models. Healthcare organizations with FDA 21 CFR Part 11 mandates demonstrate lowest price sensitivity due to non-negotiable compliance requirements, while Indian e-commerce platforms exhibit highest elasticity as they prioritize infrastructure right-sizing over advanced APM capabilities.
Supply Chain Analysis
Workforce availability for distributed systems engineering in Bangalore, Tel Aviv, and Berlin is constraining vendor capacity expansion and elevating compensation costs that feed into managed services pricing. Cloud monitoring solution delivery draws from three concentrated supply nodes: hyperscaler-native tooling development anchored in Seattle and San Francisco Bay Area, independent platform engineering centered in New York and Boston, and specialized security monitoring development in Tel Aviv and London. Single-source vulnerability persists for eBPF kernel instrumentation expertise concentrated among Linux Foundation contributor networks. Distribution runs through direct enterprise sales for banking and telecommunications contracts, supplemented by cloud marketplace channels for developer-led SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cloud Monitoring Market functions as a regulatory compounder where EU AI Act enforcement timelines and FDA 21 CFR Part 11 audit cycles create irreversible demand for telemetry platforms with immutable documentation capabilities.
For Market Incumbents: Deploy backward integration into OpenTelemetry collector development to secure instrumentation pipeline control against emerging platform-native competitors. Incumbents must consolidate multi-cloud visibility acquisitions to preempt fragmentation from Kubernetes-native challengers, while embedding carbon accounting modules to capture CSRD-driven procurement in European manufacturing and financial services. For New Entrants and Emerging Players: Sovereign cloud monitoring infrastructure for Indian financial institutions under RBI data localization mandates represents the most penetrable white-space target. Edge-to-cloud telemetry convergence for German automotive digital twin implementations offers second-mover advantage absent from incumbent platform roadmaps. A compliance-first go-to-market positioning around EU AI Act model observability documentation accelerates enterprise sales cycles versus feature-competitive approaches. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized security monitoring providers possessing ISO 27017 certification workflows and immutable log retention architectures that hyperscalers cannot replicate without antitrust scrutiny. Long-term viability hinges on AI-driven root-cause analysis capabilities that compress mean-time-to-resolution guarantees into outcome-based contract structures. Watch for inflection when European financial services procurement committees mandate OpenTelemetry-native instrumentation as a technical prerequisite.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies metrics, logs, and traces under single-pane APIs for Kubernetes-native workloads. |
| Strategic Partnership | Hyperscaler marketplace distribution accelerates developer-led adoption in mid-market segments. |
| Acquisition of Specialist Firm | Carbon accounting capabilities satisfy CSRD Scope 3 disclosure mandates for EU manufacturing clients. |
| Geographic Expansion | In-country data processing infrastructure captures RBI-compliant sovereign cloud monitoring demand in India. |
| Product Launch | eBPF-native network telemetry eliminates agent deployment overhead for high-frequency trading environments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cloud platform engineering directors, SRE team leads at financial services institutions, healthcare compliance officers, telecommunications network architects, and manufacturing IoT operations managers with secondary validation against hyperscaler capex disclosures, SEC 10-K filings from publicly traded observability vendors, OpenTelemetry community contribution metrics, and EU regulatory implementation guidance documents. Bottom-up telemetry volume estimates and top-down enterprise IT spending allocations were triangulated to anchor market sizing.
Segment-weighting approaches distributed value across deployment models, solution types, and end-user industries with regional coefficients calibrated to sovereign data residency enforcement intensity. Deployment architecture splits reflected actual procurement patterns from hybrid cloud bridging in Japanese manufacturing through multi-cloud federation in US banking. CAGRs derived from telemetry volume elasticity relative to containerized workload expansion rates and compliance mandate phase-in schedules. Industry-specific inputs included Kubernetes cluster growth projections and FDA 21 CFR Part 11 audit frequency trends.
Inputs from hyperscaler financial disclosures and regulatory implementation timelines were available through the study window; gaps in private company telemetry revenue breakdowns introduce uncertainty bands around independent platform market share estimates. Forecasts reflect modeling assumptions about OpenTelemetry standardization velocity and EU AI Act enforcement consistency. Material deviation in FDA audit automation requirements or RBI data localization technical specifications warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Technology
Cloud Information Technology Service Management (ITSM) Market
Cloud Technology
Colombia Information Technology (IT) Market
Cloud Technology
Global Health Cloud Market
Cloud Technology
Global Cloud Systems Management Market
Cloud Technology
Telecom Cloud Orchestration Market
Cloud Technology
Cloud-Enabling Technology Market
Cloud Technology
Cloud Digital Video Recording (DVR) Market
Cloud Technology
Cloud Data Quality Radar Market
Cloud Technology
Global Cloud-Based PLM Market
Cloud Technology
Top 10 Cloud Technologies Market
Cloud Technology
Cloud Workflow Market
Cloud Technology
Cloud Engineering Market
Cloud Technology
Global Cloud Discovery Market
Cloud Technology
Cloud Native Technologies Market
Cloud Technology
Cloud-Based VDI Market
Cloud Technology
Cloud Managed Services Market