
 ASEAN Unified Communication-As-A-Service Market | 2026-2036
ASEAN Unified Communication-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Unified Communication-As-A-Service Market Outlook
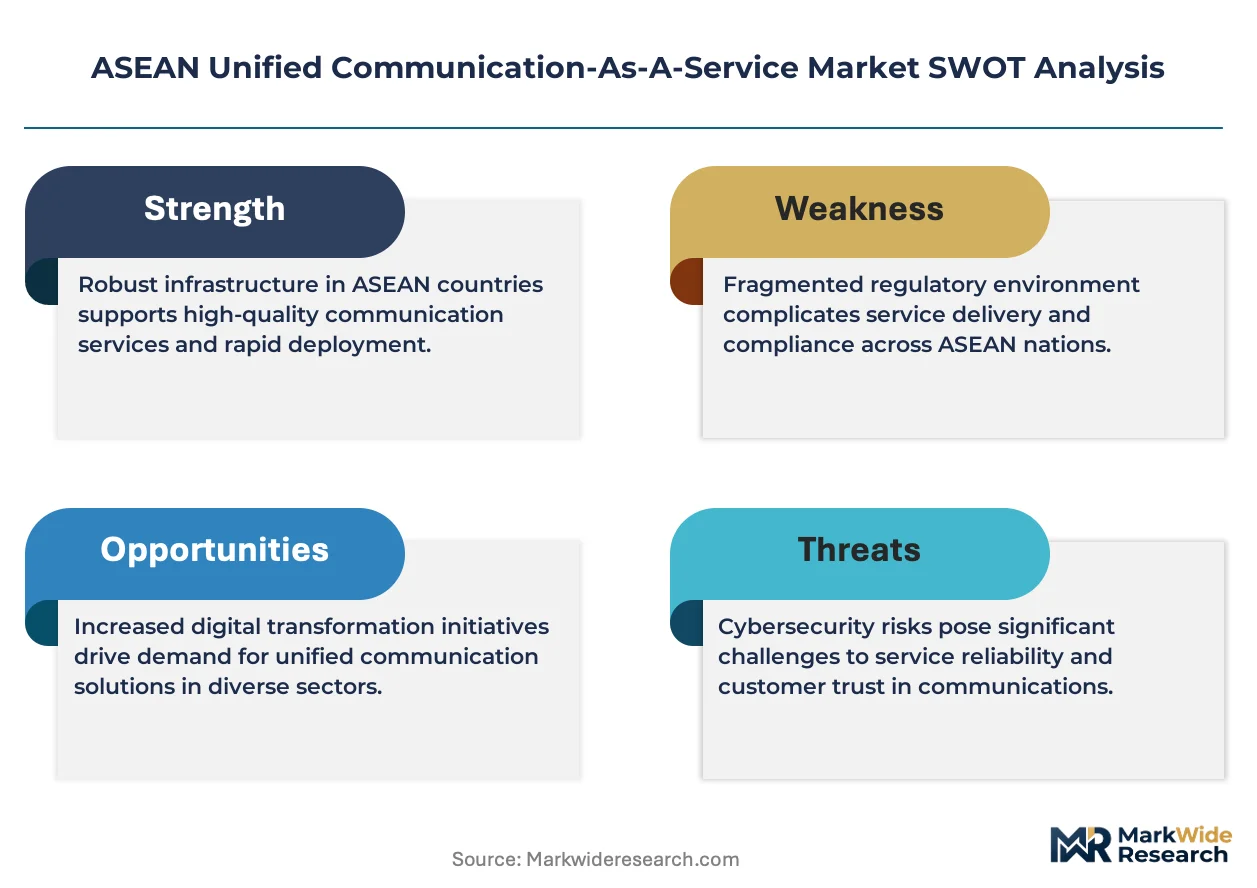
Enterprise-grade SLA tiers with sub-50ms latency guarantees and SOC 2 Type II certification is redrawing vendor qualification standards across ASEAN procurement offices. Cisco Systems Inc. leverages its Webex infrastructure and regional data residency options to anchor government and banking contracts in Singapore and Thailand. Mitel Networks Corporation specializes in hybrid cloud orchestration, sustaining relevance among manufacturing clients with on-premises legacy investments across Vietnam and Malaysia.
Unified Communication-As-A-Service delivers cloud-hosted voice, video, messaging, and collaboration tools through subscription models, typically operating on multi-tenant architectures with API-first integration to CRM and ERP systems. The platform's primary commercial purpose centers on replacing capital-intensive PBX hardware with elastic, geographically distributed communication infrastructure. Public cloud deployment dominates volume across SMEs seeking rapid provisioning without data center investment, while hybrid cloud configurations capture premium margin pools among financial institutions navigating Indonesia's OJK data localization directives and Thailand's PDPA compliance requirements. Video conferencing services within the service type dimension exhibit the steepest growth trajectory as ASEAN educational institutions and healthcare networks normalize telepresence workflows.
Singapore's IMDA licenses operational frameworks for cloud service providers, while Malaysia's PDPA and Thailand's PDPA establish cross-border data handling constraints that shape vendor architecture decisions. BIS standards in India-adjacent trade corridors indirectly influence ASEAN procurement specifications for equipment interoperability. Stakeholders must monitor how Philippines DICT cloud-first policies and emerging Vietnam cybersecurity decrees recalibrate data sovereignty requirements against multi-tenant platform economics.
Market Dynamics
Enterprise migration from on-premises PBX hardware to cloud-native communication stacks is compressing replacement cycles across Southeast Asian banking and healthcare networks. This infrastructure displacement is accelerating vendor consolidation around API-first platforms with regional data residency guarantees.
Growth Catalysts
- Indonesia OJK data localization:Banking and fintech institutions must maintain domestic data storage, forcing cloud providers to establish Jakarta-based infrastructure zones and driving contract volume.
- Telepresence normalization:Educational institutions across the Philippines and Vietnam now mandate hybrid learning capabilities, expanding video conferencing seat licenses beyond enterprise boundaries.
- SOC 2 Type II certification:Procurement offices in Singapore and Thailand require audited security controls as table stakes, filtering vendor pools toward compliant providers.
Market Restraints
- Submarine cable concentration:ASEAN internet backbone routes through Singapore and Hong Kong hubs, creating single-point latency vulnerabilities for real-time voice services during peak loads.
- Legacy PBX sunk costs:Manufacturing clients in Vietnam and Malaysia retain substantial on-premises Avaya and Cisco hardware investments, delaying full cloud migration timelines.
- Cross-border data friction:Malaysia's PDPA and Thailand's PDPA impose divergent consent and transfer requirements, complicating multi-tenant platform architecture for regional deployments.
Strategic Opportunities
- Philippines DICT cloud-first mandate:Government agencies must adopt cloud services by default, opening public sector procurement pipelines previously dominated by legacy telecom carriers.
- AI-powered real-time translation:Convergence of natural language processing with video conferencing enables seamless Bahasa Indonesia-English-Thai multilingual meetings for regional headquarters operations.
- Edge computing integration:5G network slicing in Bangkok and Jakarta allows UCaaS providers to guarantee sub-30ms latency for financial trading floors without dedicated MPLS circuits.
Industry Challenges
- SIP trunking interoperability:Fragmented legacy protocol implementations across ASEAN telcos force vendors to maintain expensive translation gateways for PSTN connectivity.
- Cybersecurity talent scarcity:Certified cloud security architects with ASEAN data protection expertise command premium compensation, constraining vendor expansion velocity.
- API integration complexity:Enterprise clients demand native connectors to region-specific ERP systems like SAP S/4HANA deployments with local customization layers, extending implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Unified Communication-As-A-Service Market |
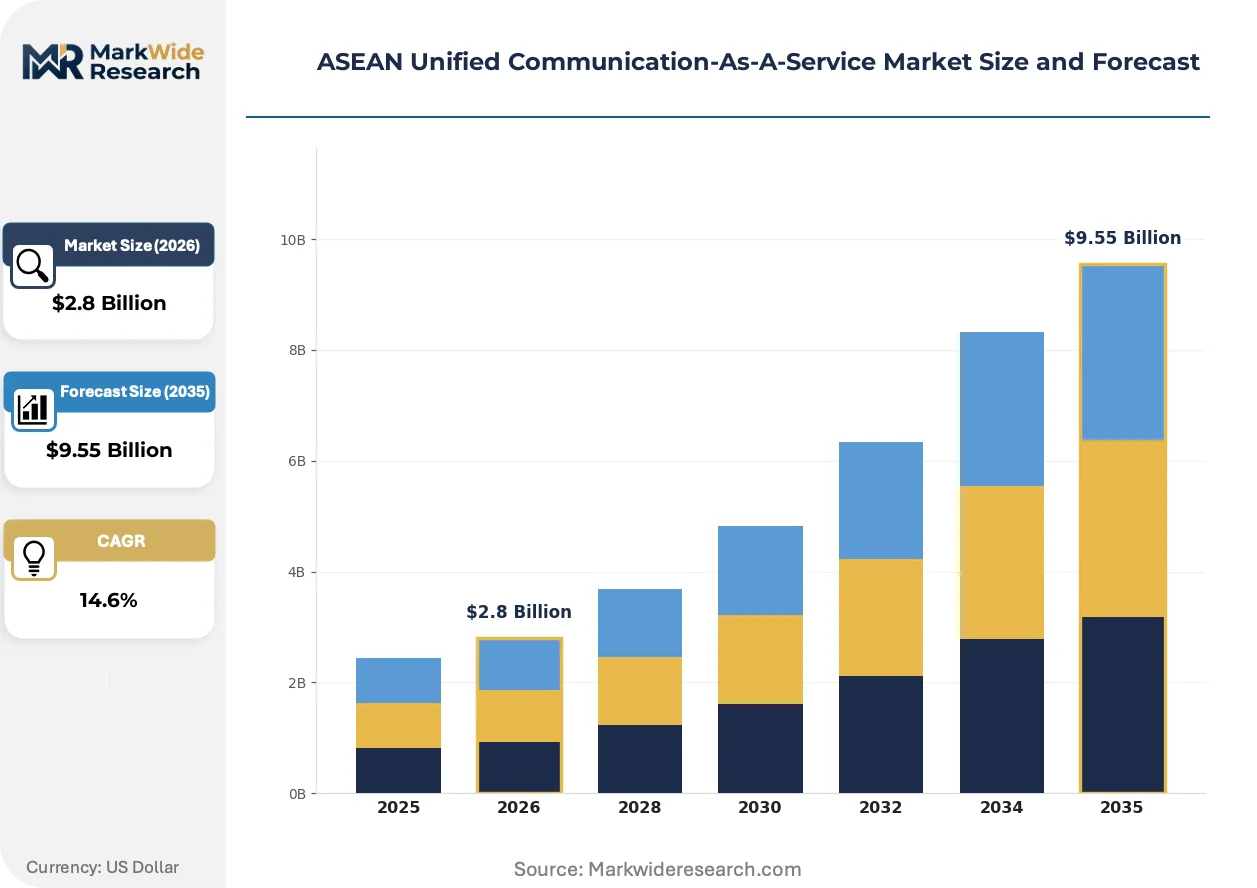
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: VoIP, Video Conferencing, Instant Messaging, Collaboration Tools Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: SMEs, Large Enterprises, Government, Educational Institutions Industry Vertical: Healthcare, Finance, Retail, Manufacturing |
| Companies Covered | Mitel Networks Corporation, Ring Central Inc., Cisco Systems Inc., 8X8 Inc., Verizon Communications Inc., Vonage Holdings Inc., Avaya Inc., Singapore Telecommunications Limited, NTT Communication Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Unified Communication-As-A-Service Market Strategic Shifts
Microservices architecture is fragmenting monolithic communication platforms into composable service meshes. This modularization enables ASEAN enterprises to license specific capabilities—voice, video, contact center—without bundled infrastructure overhead.
Containerized UCaaS delivery is decomposing traditional platform boundaries. Indonesian banks now deploy voice services through Kubernetes-orchestrated microservices while retaining on-premises session border controllers for regulatory compliance. This hybrid decomposition compresses vendor lock-in while extending infrastructure flexibility.
Singapore's IMDA licensing framework now mandates operational resilience disclosures for critical digital infrastructure providers. Financial institutions must verify their UCaaS vendors maintain geographically distributed redundancy with failover testing documentation. Thai banking regulators are adopting similar disclosure templates, harmonizing procurement due diligence across the Singapore-Bangkok corridor.
Subscription fatigue among mid-market enterprises is fragmenting long-term contract structures. Malaysian and Vietnamese SMEs now prefer month-to-month seat licensing with usage-based overage rather than annual commitments. This preference compression forces vendors to rebundle professional services and support into transparent per-user pricing without hidden implementation fees.
ASEAN Unified Communication-As-A-Service Market Segmentation
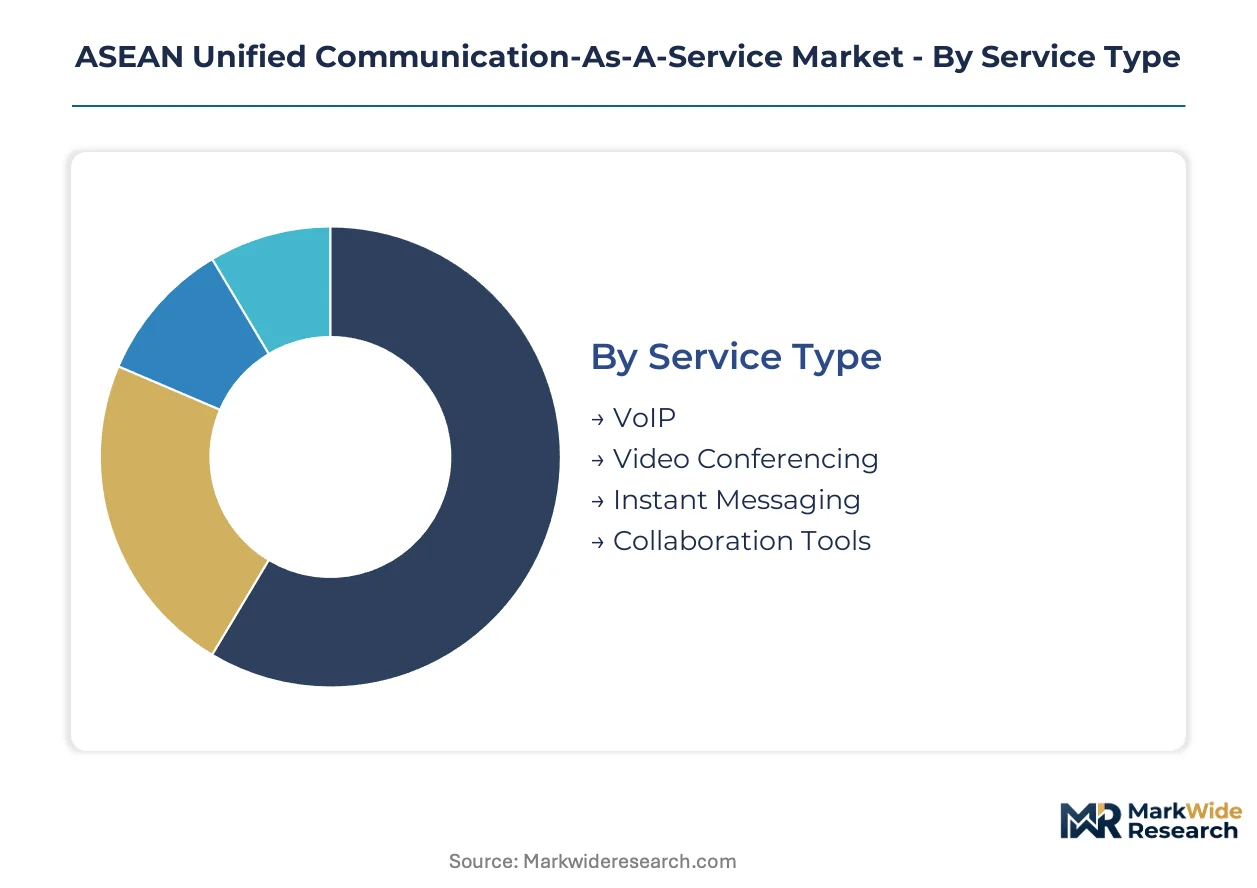
ASEAN UCaaS procurement patterns fragment across four intersecting dimensions. Service type and deployment model decisions now hinge on data sovereignty mandates from Jakarta to Bangkok, while end-user scale and industry vertical dictate API integration depth and compliance certification requirements.
Service Type:
Margin pools concentrate in video conferencing and collaboration tools as telepresence workflows normalize across Southeast Asian enterprises. VoIP retains volume leadership but faces pricing compression from commoditized SIP trunking.
- Video Conferencing:Cloud-native platforms with 4K streaming and AI-powered noise cancellation now anchor hybrid learning mandates in Philippine universities and Vietnamese healthcare networks. Indonesian banking headquarters drive demand for multi-language real-time transcription features.
- Collaboration Tools:Persistent workspace platforms with embedded document co-editing and workflow automation capture premium pricing from Singaporean professional services firms navigating IMDA operational resilience requirements. Integration with SAP S/4HANA deployments extends implementation cycles but locks in multi-year contracts.
- VoIP:Elastic cloud-hosted voice services with PSTN interoperability remain the entry point for Malaysian and Thai SME migration from legacy PBX hardware.
- Instant Messaging:Encrypted team chat with compliance archiving satisfies financial sector audit requirements in Singapore and Jakarta.
Video Conferencing holds installed capacity. Collaboration Tools is rotating up the share rankings.
Deployment Model:
Hybrid cloud configurations command the widest margin spreads as financial institutions balance elasticity against OJK and PDPA data localization directives. Public cloud dominates seat volume but faces downward pricing pressure from subscription fatigue among mid-market buyers.
- Hybrid Cloud:Kubernetes-orchestrated voice microservices with on-premises session border controllers enable Indonesian banks to satisfy domestic data storage rules while accessing cloud scalability. Manufacturing clients in Vietnam and Malaysia leverage this architecture to sweat remaining Avaya hardware investments.
- Public Cloud:Multi-tenant platforms with rapid provisioning attract ASEAN SMEs seeking zero data center capital expenditure. Singapore's IMDA licensing framework filters vendor pools toward compliant providers, concentrating procurement among SOC 2 Type II certified operators.
- Private Cloud:Single-tenant dedicated infrastructure serves Thai government agencies with classified communication requirements under PDPA cross-border transfer restrictions.
- On-Premises:Residual deployments persist in Malaysian manufacturing facilities with substantial sunk costs in Cisco and Mitel hardware.
Hybrid Cloud anchors premium contract value. Public Cloud is expanding most quickly across SME segments.
End User:
Large enterprises generate the deepest professional services attach rates, while government verticals unlock longest contract durations through DICT cloud-first mandates in the Philippines. SME segments drive seat volume but fragment pricing toward month-to-month structures.
- Large Enterprises:Regional headquarters operations in Singapore and Bangkok demand API-first integration with ERP systems and sub-50ms latency guarantees for financial trading floors. Procurement offices require audited security controls and geographically distributed redundancy documentation.
- Government:Philippine agencies must adopt cloud services by default, displacing legacy telecom carrier relationships and opening procurement pipelines for compliant UCaaS vendors. Thai public sector contracts follow similar disclosure templates harmonizing due diligence requirements.
- SMEs:Malaysian and Vietnamese mid-market buyers prefer usage-based overage pricing without hidden implementation fees, compressing vendor bundling strategies.
- Educational Institutions:Hybrid learning mandates across Philippine and Vietnamese campuses normalize video conferencing seat licenses beyond traditional enterprise boundaries.
Large Enterprises hold installed capacity. Government is rotating up the share rankings.
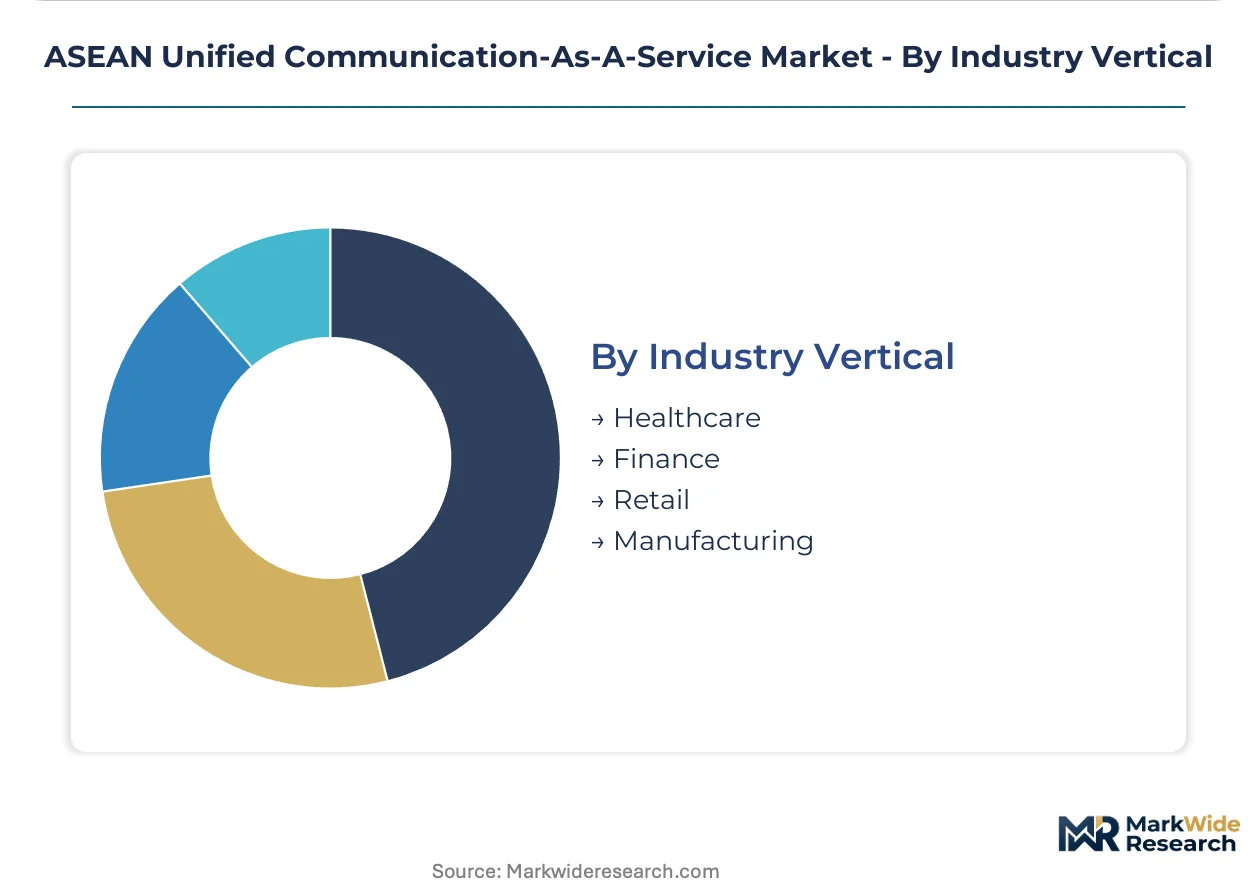
Industry Vertical:
Finance and healthcare verticals sustain the steepest pricing premiums through compliance-driven procurement, while retail and manufacturing segments prioritize cost containment over feature depth.
- Finance:Banking and fintech institutions across Indonesia's OJK corridor require Jakarta-based infrastructure zones and SOC 2 Type II certification as table stakes. Sub-30ms latency guarantees for trading floors command premium positioning against standard enterprise tiers.
- Healthcare:Telepresence normalization in Vietnamese and Philippine hospital networks drives video conferencing adoption for remote consultation workflows. Patient data protection requirements under national privacy frameworks shape vendor architecture decisions.
- Manufacturing:Hybrid cloud orchestration sustains relevance among Vietnam and Malaysia production facilities with on-premises legacy investments delaying full migration timelines.
- Retail:Distributed store networks prioritize cost-efficient VoIP and messaging for operational coordination across ASEAN multi-country footprints.
Finance holds installed capacity. Healthcare is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive SMEs in Vietnam and Malaysia gravitate toward public cloud seat licensing, while Singaporean financial institutions absorb premium hybrid cloud rates for sub-50ms latency guarantees. This demand elasticity split shapes vendor go-to-market strategies across the region.
Singapore
Enterprise-grade procurement concentrates among banking headquarters and government agencies requiring SOC 2 Type II certification. The IMDA licensing framework mandates operational resilience disclosures, filtering vendor pools toward compliant providers. Marina Bay financial district drives demand for geographically distributed redundancy documentation.
Indonesia
OJK data localization directives force cloud providers to establish Jakarta-based infrastructure zones for banking and fintech contracts. Legacy PBX replacement cycles accelerate cloud migration across the Jakarta-Surabaya corridor. Domestic data storage rules compress vendor qualification timelines for foreign operators.
Thailand
PDPA cross-border transfer restrictions shape multi-tenant platform architecture for regional deployments. Bangkok banking regulators adopt Singapore-style disclosure templates for critical digital infrastructure. Manufacturing clients in Eastern Economic Corridor retain hybrid configurations to sweat sunk hardware investments.
Vietnam
Mid-market SMEs prefer month-to-month seat licensing with usage-based overage, fragmenting vendor bundling strategies. Emerging cybersecurity decrees recalibrate data sovereignty requirements against multi-tenant economics. Ho Chi Minh City manufacturing zones sustain on-premises legacy relevance.
Philippines
DICT cloud-first mandates open public sector procurement pipelines previously dominated by legacy telecom carriers. Educational institutions normalize video conferencing seat licenses for hybrid learning workflows. Government agencies must adopt cloud services by default, displacing incumbent carrier relationships.
ASEAN Unified Communication-As-A-Service Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where premium positioning separates from volume capture. The vendor base clusters around three strategic groupings: global platform operators with regional data residency options, hybrid cloud specialists serving manufacturing legacy environments, and telecom-affiliated providers leveraging infrastructure ownership. M&A activity concentrates on API-first platform acquisitions, while geographic expansion focuses on Jakarta and Bangkok infrastructure zone establishment.
Among North American platform operators, Cisco Systems Inc., Mitel Networks Corporation, and Ring Central Inc. occupy positions across the premium-to-standard spectrum. Cisco exemplifies the enterprise-grade archetype with government and banking contract anchoring. Mitel represents hybrid cloud orchestration specialization for manufacturing legacy contexts. Ring Central sits within the volume-driven SME tier with rapid provisioning capabilities.
| Leading Market Players |
|---|
| Mitel Networks Corporation |
| Ring Central Inc. |
| Cisco Systems Inc. |
| 8X8 Inc. |
| Verizon Communications Inc. |
| Vonage Holdings Inc. |
| Avaya Inc. |
| Singapore Telecommunications Limited |
| NTT Communication Corporation |
| Others |
Value Chain & Pricing Dynamics
Annual seat-license commitments with SOC 2 Type II certification requirements lock in both Jakarta-based infrastructure access and predictable per-user cost visibility for Indonesian banking procurement offices. This contract-structure pattern concentrates pricing power among vendors with domestic data residency zones while compressing margin flexibility for operators dependent on Singapore hub routing.
Pricing Analysis
Singapore's IMDA licensing framework dictates the pricing tier structure across ASEAN procurement offices, separating SOC 2 Type II certified providers from uncertified competitors. Three-tier pricing structure across premium, standard, and economy levels reflects latency guarantees and data residency compliance grades. Cost compression in the public cloud SME tier is intensifying because Vietnamese and Malaysian mid-market buyers prefer month-to-month structures without implementation fees. Manufacturing clients with legacy Avaya investments show least price sensitivity due to hybrid orchestration requirements.
Supply Chain Analysis
Strategic stockpile preferences dominate infrastructure deployment as Indonesian banks require Jakarta-based session border controllers to satisfy OJK data localization. Hardware supply concentrates in Singapore, Taiwan, and South Korea for edge computing nodes and submarine cable termination equipment. Component dependencies include specialized VoIP chipsets, encryption modules, and Kubernetes-orchestrated microservices containers. Single-source vulnerability runs through Singapore-Hong Kong submarine cable concentration for real-time voice services. Distribution feeds from vendor direct sales teams into enterprise procurement offices and telecom-affiliated channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional services attach rates for API integration and compliance documentation are expanding faster than base seat licensing across ASEAN banking contracts. This service-layer acceleration creates recurring revenue depth beyond hardware provisioning cycles.
For Market Incumbents: Shield government and banking contract positions in Singapore and Jakarta by accelerating Jakarta infrastructure zone buildout ahead of foreign operator qualification timelines. Certification investment in Thailand's emerging PDPA disclosure templates secures first-mover advantage against hybrid cloud specialists. Channel control through telecom-affiliated partnerships limits direct access for North American platform operators.
For New Entrants and Emerging Players: Anchor in Philippine government verticals where DICT cloud-first mandates displace legacy telecom carrier relationships. Vietnamese manufacturing facilities with Avaya sunk costs represent the most penetrable segment for hybrid orchestration plays. Go-to-market angle centers on month-to-month pricing transparency without hidden implementation fees to capture SME subscription fatigue.
For Investors and Strategic Acquirers: API-first platform specialists with regional data residency options offer the strongest acquisition target archetype for long-term viability across the analysis window. These targets command premium positioning as OJK and PDPA compliance requirements filter vendor pools. The signal to watch is Jakarta infrastructure zone establishment announcements as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Jakarta Infrastructure Zone Establishment | OJK data localization compliance unlocks Indonesian banking contract pipelines. |
| SOC 2 Type II Certification Investment | Singapore IMDA licensing filters vendor pools toward audited security controls. |
| API-First Platform Integration | SAP S/4HANA connector development extends implementation cycles into multi-year contracts. |
| Telecom-Affiliated Channel Partnership | Infrastructure ownership leverages existing carrier relationships in Philippines and Thailand. |
| AI-Powered Real-Time Translation Development | Bahasa Indonesia-English-Thai multilingual capabilities capture regional headquarters demand. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vendor licensing disclosures, regulatory filing databases, and enterprise procurement documentation across the analysis window. Primary interviews engaged cloud service provider executives, ASEAN banking IT procurement officers, telecom infrastructure planners, and compliance audit specialists. Secondary sources include Singapore IMDA licensing registers, Indonesia OJK data localization guidance, Thailand PDPA implementation circulars, Philippines DICT cloud-first policy directives, and hyperscaler regional capex disclosures. Bottom-up seat deployment estimates triangulate against top-down market value reconstruction.
Segmentation dimensions modeled span service type, deployment architecture, end-user scale, and industry vertical across the projection horizon. Deployment model analysis weights hybrid cloud configurations against public cloud seat volume. Service type disaggregation separates video conferencing growth trajectories from VoIP commoditization patterns. CAGRs derive from elasticity-adjusted adoption curves and regulatory mandate acceleration effects. Forecast inputs include OJK infrastructure zone establishment timelines and PDPA disclosure template harmonization rates.
Material uncertainties — submarine cable disruption events, cybersecurity decree revisions, and subscription fatigue fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and enterprise migration timeline stability. Revision becomes warranted when Jakarta infrastructure zone capacity constraints cross utilization thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Cloud UC Calling Market
Unified Communications
Unified Communication Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
Ucaas in the Manufacturing Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
Unified Monitoring Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Ucaas in Banking Market
Unified Communications
Business Cloud Voip and UC Services Market