
 Asia-Pacific Automated Liquid Handling Market | 2026-2036
Asia-Pacific Automated Liquid Handling Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automated Liquid Handling Market Outlook
The capability gap between high-throughput workstation specialists and benchtop pipette vendors is unwinding as mid-tier players invest in modular robotics. Hamilton Company leverages its precision syringe-drive technology to dominate ultra-low-volume applications in genomics workflows. Tecan Group Ltd. sustains competitive position through application-specific software ecosystems that reduce protocol development time for pharmaceutical clients. Beckman Coulter, Inc. anchors its Asia-Pacific presence with localized service infrastructure and compliance support for clinical laboratories navigating CDSCO device registration pathways.
Automated liquid handling encompasses electromechanical systems that transfer microliter-to-milliliter volumes with positional accuracy below one millimeter, integrating pipetting heads, deck controllers, and scheduling software to execute reproducible protocols in multi-well formats. These systems eliminate manual pipetting variability in high-complexity assays such as CRISPR library preparation and ELISA automation. Liquid handling workstations command the deepest margin pools due to integration complexity and recurring consumables revenue, while automated plate robots represent the fastest-expanding category as contract research organizations scale compound screening throughput. Academic research institutions remain price-sensitive adopters, driving distributor-channel competition for entry-level multichannel pipettes across India and Southeast Asia.
Japan's PMDA medical device quality management standards and China's NMPA in vitro diagnostic instrument registration rules shape product development timelines and localization requirements for vendors serving clinical end users. India's CDSCO import licensing framework for automated laboratory equipment adds compliance layers that favor direct sales models over reseller networks for high-value installations. METI's Japan Bioeconomy Strategy funding mechanisms are accelerating domestic biopharma capacity expansion, tightening lead times for workstation deliveries. Stakeholders must weigh regulatory divergence against platform standardization bets as country-specific validation protocols proliferate across the region.
Market Dynamics
China's dual carbon goals and tightening GB standards on laboratory energy efficiency are compelling manufacturers to redesign instrument architectures, while CRO expansion across Shanghai and Suzhou concentrates demand for modular, high-throughput systems.
Growth Catalysts
- Biopharma CRO expansion:Contract research organizations in Shanghai and Suzhou are scaling compound screening throughput, driving workstation procurement across genomics and proteomics workflows.
- CDSCO pathway streamlining:India's revised import licensing framework for automated laboratory equipment reduces approval timelines for clinical diagnostic installations.
- Precision medicine protocols:CRISPR library preparation and next-generation sequencing sample prep are standardizing on automated liquid handling to eliminate manual pipetting variability.
Market Restraints
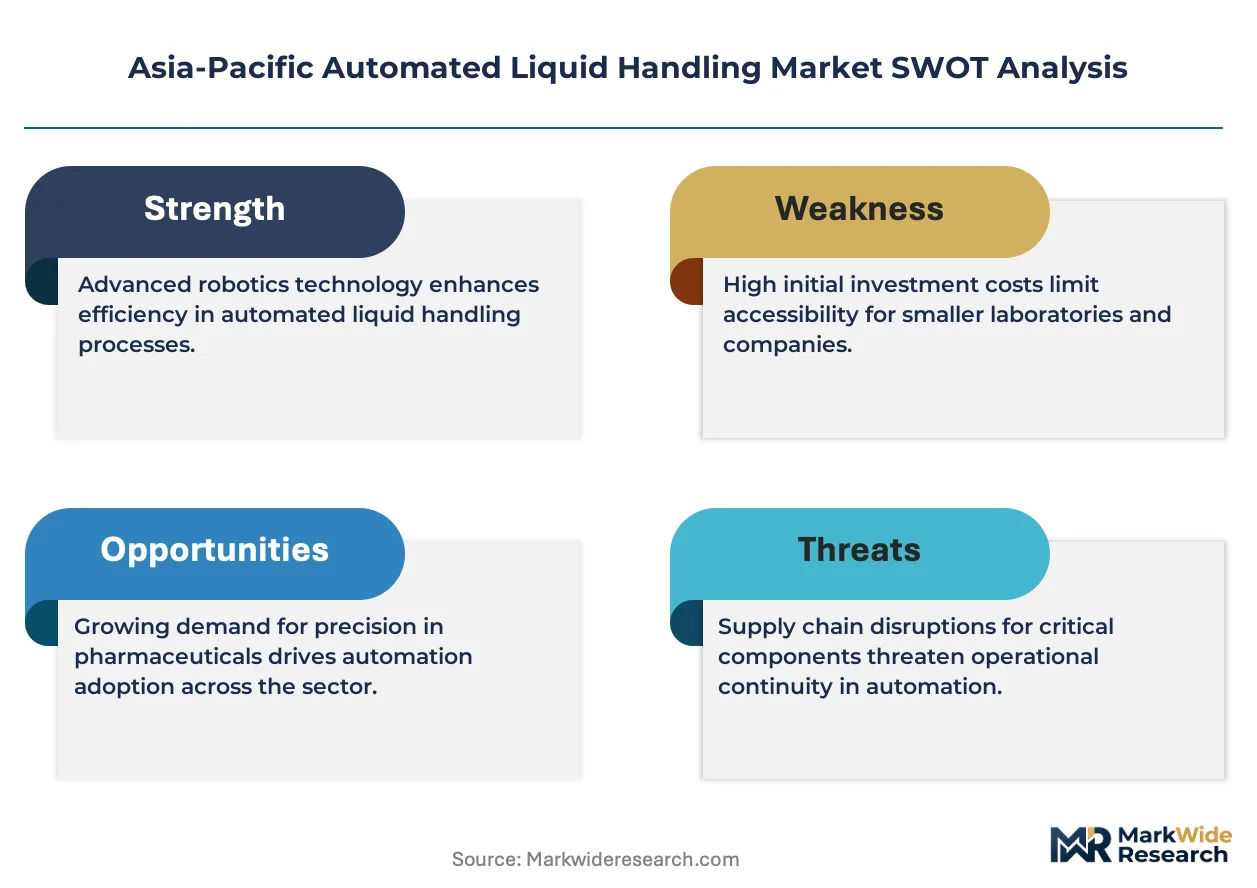
- Precision component supply concentration:Syringe-drive motors and optical position sensors concentrate among Japanese and German component suppliers, exposing lead time risks.
- NMPA registration complexity:China's in vitro diagnostic instrument registration rules require extensive clinical validation studies that extend product launch timelines by 18-24 months.
- Academic price sensitivity:Research institutions across India and Southeast Asia prioritize entry-level multichannel pipettes over integrated workstations, compressing average selling prices.
Strategic Opportunities
- Vietnam biotech corridor emergence:Ho Chi Minh City and Hanoi are attracting CMO investment, creating first-mover advantage for workstation vendors establishing localized service infrastructure.
- METI Bioeconomy Strategy funding:Japan's domestic biopharma capacity expansion subsidies accelerate capital equipment depreciation, tightening delivery lead times for qualified suppliers.
- Cloud-native protocol software:Browser-based scheduling and remote diagnostics integration are displacing on-premise license models, opening recurring revenue streams for platform vendors.
Industry Challenges
- Cross-border service technician certification:PMDA medical device quality management standards require Japan-specific training credentials that complicate regional workforce deployment.
- Legacy LIMS integration complexity:Pharmaceutical clients demand seamless data exchange with existing laboratory information management systems, extending implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automated Liquid Handling Market |
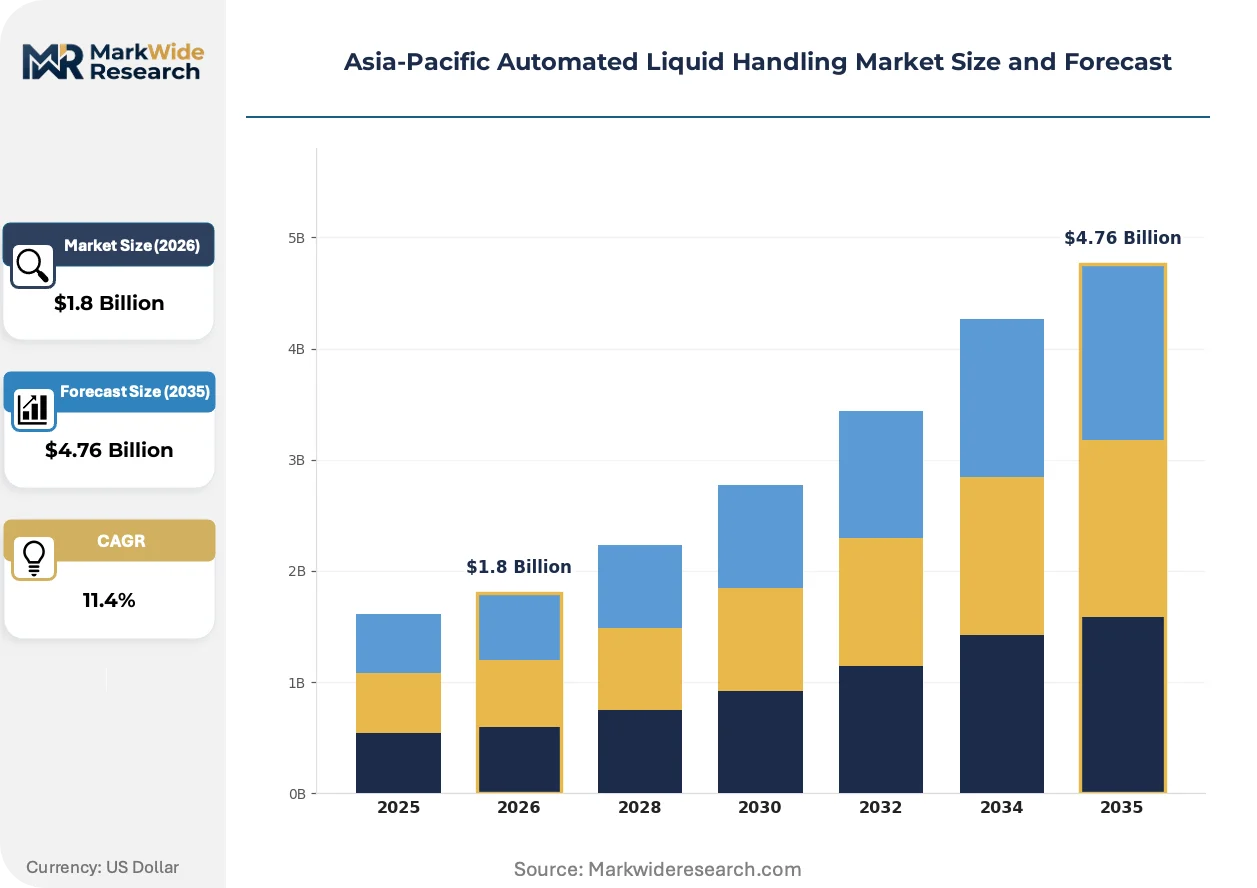
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
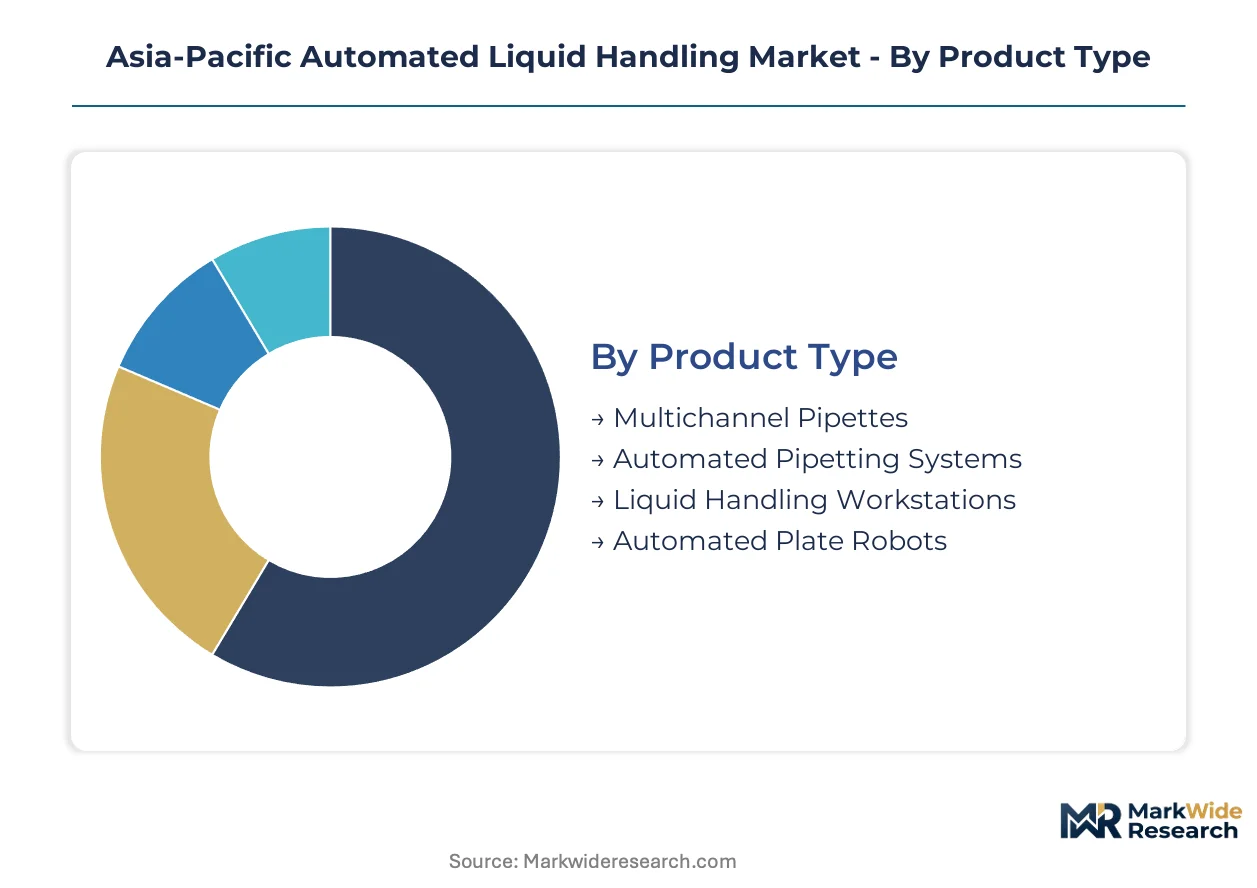
| Segmentation | Product Type: Multichannel Pipettes, Automated Pipetting Systems, Liquid Handling Workstations, Automated Plate Robots End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutions, Clinical Laboratories Delivery Mode: Online, Direct Sales, Distributors, Resellers Application: Drug Discovery, Genomics, Proteomics, Tissue Culture |
| Companies Covered | Agilent Technologies, Inc., Thermo Fisher Scientific Inc., Hamilton Company, PerkinElmer Inc., Beckman Coulter, Inc., Eppendorf AG, Tecan Group Ltd., Gilson Incorporated, METTLER TOLEDO, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automated Liquid Handling Market Strategic Shifts
Digital microfluidics and acoustic droplet ejection are compressing minimum transferable volumes while software-defined protocol architectures are decoupling hardware from application-specific workflows.
Acoustic liquid handling technology is miniaturizing transfer volumes to nanoliter ranges without physical contact, eliminating cross-contamination risks in high-density screening applications. Genomics core facilities and CRISPR service providers are adopting these systems to process 10,000+ samples daily with positional accuracy below 0.1 millimeters. This capability is miniaturizing reagent consumption and enabling assay miniaturization that was previously impractical with traditional pipetting mechanics.
PMDA medical device quality management standards and China's GB standards on laboratory energy efficiency are mandating traceable calibration records and standby power limits that reshape product development roadmaps. Manufacturers must maintain dual validation protocols for clinical and research-grade instruments, fragmenting firmware architectures. Clinical laboratories navigating CDSCO device registration pathways face the steepest compliance burden, favoring vendors with pre-submitted master files.
After-sales service unbundling is separating maintenance contracts from instrument sales, with CROs and large pharmaceutical buyers negotiating multi-site enterprise service agreements directly with manufacturer technical teams. Distributor-channel partners are losing high-value installation and validation revenue to direct sales organizations. This shift is most visible in China's biotech corridor, where compound screening facilities demand 4-hour response time guarantees that reseller networks cannot provision.
Asia-Pacific Automated Liquid Handling Market Segmentation
Automated liquid handling procurement patterns diverge sharply across product tiers and customer types. Channel strategy must align with end-user sophistication, as CROs demand direct technical engagement while academic buyers route through distributor networks.
Product Type:
Multichannel pipettes and entry-level systems flow through distributor channels serving price-sensitive academic buyers, while integrated workstations and plate robots move through direct sales teams with embedded field applications scientists.
- Liquid Handling Workstations:These electromechanical platforms integrate pipetting heads, deck controllers, and scheduling software for multi-well format protocols. Demand concentrates in Shanghai and Suzhou biotech corridors where CROs scale compound screening throughput. Hamilton Company and Tecan Group Ltd. dominate this tier through precision syringe-drive technology and application-specific software ecosystems.
- Automated Plate Robots:Robotic arms with specialized end-effectors transfer microplates between workstations, enabling unattended operation across 24-hour screening cycles. Contract research organizations in China's biotech corridor are adopting these systems fastest as METI Bioeconomy Strategy funding accelerates regional capacity expansion.
- Automated Pipetting Systems:Benchtop units with programmable liquid transfer protocols serve mid-scale genomics workflows.
- Multichannel Pipettes:Handheld electronic devices with 8-12 channel heads remain the entry point for budget-constrained laboratories.
By volume, multichannel pipettes lead. By growth pace, automated plate robots are expanding most quickly.
End User:
Customer maturity determines pricing tolerance and service expectations, with pharmaceutical buyers accepting premium positioning for validated protocols while academic institutions compress margins through competitive bidding.
- Pharmaceutical Companies:Multinational drug developers require 21 CFR Part 11-compliant software and seamless LIMS integration for high-throughput screening. These buyers negotiate enterprise service agreements directly with manufacturer technical teams, bypassing distributor markups.
- Clinical Laboratories:Diagnostic facilities across India navigate CDSCO device registration pathways, favoring vendors with pre-submitted master files and localized compliance support. Beckman Coulter, Inc. anchors its regional presence through this infrastructure.
- Biotechnology Firms:Venture-backed developers prioritize modular architectures that scale with pipeline progression.
- Academic Research Institutions:University core facilities across India and Southeast Asia prioritize entry-level multichannel pipettes over integrated workstations.
Pharmaceutical companies generate the highest revenue per installation. Clinical laboratories are climbing the fastest as NMPA and CDSCO pathway streamlining accelerates diagnostic automation.
Delivery Mode:
Sales channel selection reflects instrument complexity and buyer sophistication, with high-value installations requiring technical validation support that reseller networks cannot provision.
- Direct Sales:Manufacturer-employed account executives and field applications scientists manage complex workstation deployments. This channel captures compound screening facilities in China's biotech corridor demanding 4-hour response time guarantees.
- Distributors:Regional partners with inventory and basic technical support serve academic and small biotechnology accounts across India and Southeast Asia.
- Online:E-commerce platforms with configurators and consumables replenishment serve repeat buyers of established models.
- Resellers:Independent agents without manufacturer certification handle legacy system trade-ins and refurbished equipment.
Direct sales commands the highest average transaction value. Online channels are gaining share fastest among consumables replenishment and entry-level system buyers.
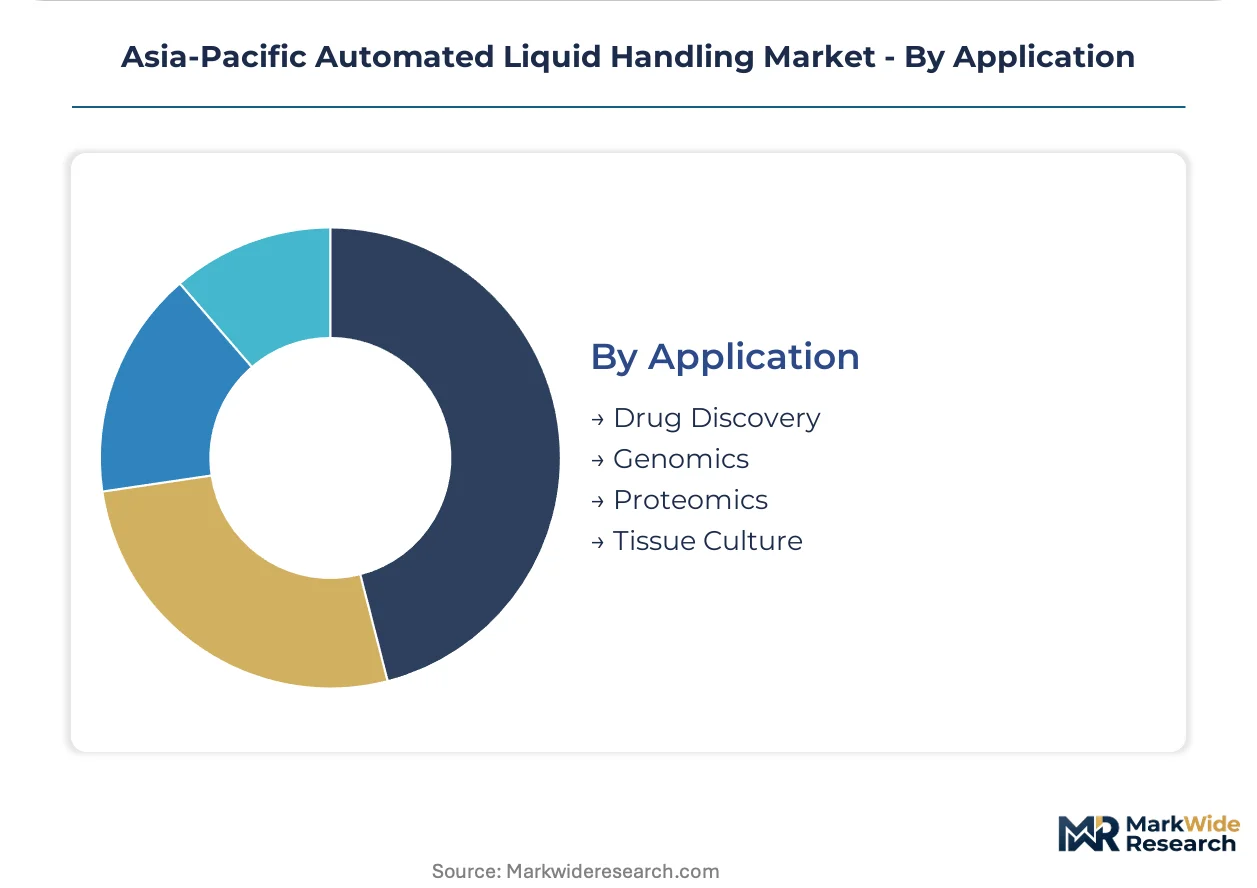
Application:
Workflow complexity dictates system specification, with genomics and drug discovery requiring nanoliter precision while tissue culture applications prioritize sterility maintenance over volume accuracy.
- Genomics:Next-generation sequencing sample prep and CRISPR library preparation demand ultra-low-volume precision below one millimeter positional accuracy. Acoustic droplet ejection technology is miniaturizing transfer volumes to nanoliter ranges without physical contact.
- Drug Discovery:High-density screening applications process 10,000-plus samples daily, driving acoustic liquid handling adoption to eliminate cross-contamination risks. CROs in Shanghai and Suzhou concentrate demand for these capabilities.
- Proteomics:Mass spectrometry sample prep requires reproducible protein digestion and peptide cleanup protocols.
- Tissue Culture:Media exchange and passaging workflows prioritize sterility maintenance and gentle handling over precision metrics.
Drug discovery generates the deepest instrument margins. Genomics is expanding most quickly as precision medicine protocols standardize on automated sample preparation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's precision instrument corridor while India operates at steeper discount tiers, creating a two-speed procurement landscape across the Asia-Pacific automated liquid handling market.
China
Shanghai and Suzhou anchor biotech corridor expansion where CROs scale compound screening throughput. NMPA in vitro diagnostic instrument registration rules mandate 18-24 month clinical validation timelines that fragment product launch cycles. Domestic manufacturers redesign instrument architectures to meet tightening GB standards on laboratory energy efficiency.
Japan
METI Bioeconomy Strategy subsidies accelerate domestic biopharma capacity expansion and tighten workstation delivery lead times. PMDA medical device quality management standards require Japan-specific technician credentials that complicate regional workforce deployment. Kanto region precision manufacturers supply syringe-drive motors and optical position sensors to regional vendors.
India
CDSCO import licensing framework revisions reduce approval timelines for clinical diagnostic installations. Academic institutions across Maharashtra and Karnataka prioritize entry-level multichannel pipettes through distributor channels. Pharmaceutical manufacturers in Hyderabad and Ahmedabad negotiate enterprise service agreements directly with manufacturer technical teams.
South Korea
MFDS medical device quality standards shape validation protocols for clinical-grade liquid handling systems. Seoul Capital Area biotech clusters demand 21 CFR Part 11-compliant software for high-throughput screening workflows. Domestic CROs in Songdo International Business District scale automated plate robot procurement for 24-hour unattended operation.
Vietnam
Ho Chi Minh City and Hanoi attract contract manufacturing organization investment, creating first-mover positioning for workstation vendors establishing localized service infrastructure. The country's national pharmaceutical regulator develops harmonized import standards for automated laboratory equipment. Emerging biotech facilities in Thu Duc City prioritize modular architectures that scale with pipeline progression.
Asia-Pacific Automated Liquid Handling Market Competitive Environment
Concentration sits with precision electromechanical specialists and application-specific software providers that anchor the workstation tier. The vendor base stratifies across three functional tiers: high-throughput workstation specialists, benchtop pipette generalists, and emerging modular robotics players. Competitive positioning hardens around M&A activity targeting software-defined protocol architectures and direct sales capacity expansion in China's biotech corridor.
Among precision instrument specialists, Hamilton Company and Tecan Group Ltd. occupy positions within the ultra-low-volume application tier, while Beckman Coulter, Inc. anchors clinical laboratory service infrastructure. These three exemplify divergent strategic archetypes: Hamilton Company represents syringe-drive precision technology, Tecan Group Ltd. sits within application-specific software ecosystems, and Beckman Coulter, Inc. embodies localized compliance support models. Each occupies a distinct competitive position without overlapping core capability claims.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| Thermo Fisher Scientific Inc. |
| Hamilton Company |
| PerkinElmer Inc. |
| Beckman Coulter, Inc. |
| Eppendorf AG |
| Tecan Group Ltd. |
| Gilson Incorporated |
| METTLER TOLEDO |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at precision electromechanical component foundries in Japan and Germany sets price floors across the Asia-Pacific automated liquid handling market, concentrating margin capture among workstation specialists while compressing entry-level pipette tiers. This scale dynamic tightens as CRO procurement volumes in Shanghai and Suzhou accelerate demand for configured-to-order systems with embedded validation support.
Pricing Analysis
The customization-premium spread separates liquid handling workstations priced for pharmaceutical enterprise agreements from distributor-channel multichannel pipettes serving academic budgets. Pricing stratifies across premium, standard, and economy tiers driven by certification grade—PMDA clinical validation versus research-grade firmware—and after-sales service bundling. Cost compression in the academic tier intensifies because Indian and Southeast Asian institutions prioritize entry-level systems through competitive bidding. Pharmaceutical buyers in China and Japan exhibit lowest price sensitivity, accepting premium positioning for 21 CFR Part 11-compliant software and direct technical engagement.
Supply Chain Analysis
Inbound logistics costs from Yokohama and Hamburg ports constrain inventory positioning for syringe-drive motors and optical position sensors, extending replenishment cycles for workstation manufacturers. Precision component supply concentrates in Japan, Germany, and South Korea, drawing from rare-earth magnet feedstocks and specialized bearing alloys. Single-source vulnerability sits with Japanese suppliers of sub-micron linear encoders. Distribution runs through direct sales teams for high-value installations and regional distributors for academic and small biotechnology accounts across India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific automated liquid handling market reads as a service-attach opportunity where cloud-native protocol software and remote diagnostics integration are expanding faster than hardware replacement cycles. Enterprise service agreements with 4-hour response guarantees now capture margin pools that previously accrued to distributor partners.
For Market Incumbents: Secure field applications scientist capacity in China's biotech corridor before METI Bioeconomy Strategy subsidies tighten regional delivery lead times further. Deepen backward integration into precision syringe-drive manufacturing to offset Japanese component supplier concentration. Defend against modular robotics entrants by accelerating firmware architectures that decouple hardware from application-specific workflows. For New Entrants and Emerging Players: Cloud-native scheduling software without on-premise license dependencies represents the most penetrable service layer where Tecan and Hamilton maintain legacy codebases. Target Vietnam's emerging biotech corridor in Ho Chi Minh City and Hanoi with modular architectures that scale from venture-backed biotechnology firms to contract manufacturing organizations. Lead with browser-based protocol development tools that reduce implementation cycles for laboratories navigating CDSCO and NMPA validation pathways. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors application-specific software providers over hardware generalists as acoustic droplet ejection and digital microfluidics reshape volume precision standards. Five-to-ten year viability hinges on recurring revenue ratios from consumables and software subscriptions rather than instrument replacement cycles. Watch for inflection when CRO procurement committees mandate API-first LIMS integration as a baseline vendor qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Protocol Platform Launch | Browser-based scheduling displaces on-premise licenses, opening recurring revenue streams for platform vendors. |
| Direct Service Infrastructure Expansion | Localized technical teams in Shanghai and Suzhou capture enterprise agreements bypassing distributor markups. |
| Acoustic Liquid Handling Technology Licensing | Nanoliter-range droplet ejection eliminates cross-contamination in high-density CRISPR screening workflows. |
| Regulatory Master File Pre-Submission | Pre-submitted CDSCO and NMPA documentation accelerates clinical laboratory procurement decisions. |
| Consumables Supply Agreement | Captive tips, plates, and reagent reservoirs lock in recurring revenue per installed workstation base. |
Study Parameters
Operator-level perspectives from CRO automation directors, clinical laboratory managers, biomedical procurement officers, and field service technicians anchored the qualitative base for this study. Primary interviews combined with secondary validation from NMPA registration filings, CDSCO import licensing records, METI subsidy disbursement reports, and SEC 10-K instrument revenue disclosures. Bottom-up triangulation across product tier shipment estimates and top-down cross-checks against biopharma capital expenditure surveys calibrated market sizing.
Sensitivity analysis tested volume and value outputs across the projection horizon against alternative regulatory pathway timelines and component supply disruption scenarios. Segmentation dimensions modeled include product type, end user sophistication, delivery mode, and application workflow complexity. CAGRs derived from logistic diffusion curves fitted to historical automation penetration rates in genomics and drug discovery laboratories, with cross-validation against precision medicine protocol adoption trajectories.
Forecasts assume regulatory continuity in NMPA in vitro diagnostic instrument registration, CDSCO import licensing, and PMDA medical device quality management standards; material policy shifts would require re-modeling. Specific risk factors include syringe-drive motor supply concentration, cross-border technician certification fragmentation, and legacy LIMS integration complexity extending pharmaceutical implementation cycles. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Automated Sample Storage Systems Market
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
Asia-Pacific Data Center Automation Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
Modular Laboratory Automation Market
Automation
Global Automated Liquid Handlers Market
Automation
Distributed Control System Market
Automation
Data Center Automation Market
Automation
Global Warehouse Execution System Market
Automation
Database Automation Market
Automation
Middle East and Africa Workforce Management Market
Automation
Network Automation Market
Automation
CNC Controller Market
Automation
Automated Cell Block Systems Market
Automation
Distribution Automation Solutions Market
Automation
Global Direct Mail Automation Software Market