
 Website Monitoring Software Market | 2026-2036
Website Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Website Monitoring Software Market Outlook
Modular bundling of uptime, performance, and security capabilities into unified observability suites is shifting buyer procurement patterns away from standalone point tools. Datadog leverages its cloud-native platform architecture to anchor multi-product contracts across enterprise DevOps teams. SolarWinds competes through specialized network-performance heritage that extends into hybrid infrastructure monitoring. New Relic differentiates via full-stack visibility positioning that occupies the mid-market digital transformation segment.
Website monitoring software encompasses tools that track server response times, page-load latency, transaction completion rates, and synthetic user journeys to ensure digital service reliability. These platforms employ distributed probe networks, real-browser testing, and API endpoint polling to detect outages before end-user impact. Cloud-based solutions now lead deployment preferences as IT service providers demand elastic scalability without capital infrastructure. Security monitoring represents the fastest-growing product type as ransomware exposure and compliance mandates intensify scrutiny of certificate expiry, DNS hijacking, and third-party script injection.
FCC net-neutrality frameworks and SEC cybersecurity disclosure rules shape how US enterprises justify monitoring investments to audit committees. GDPR breach-notification timelines and EU AI Act risk-classification requirements compel European buyers toward automated alerting with documented response protocols. Stakeholders must weigh whether to consolidate around platform vendors or preserve best-of-breed flexibility as observability data volumes expand.
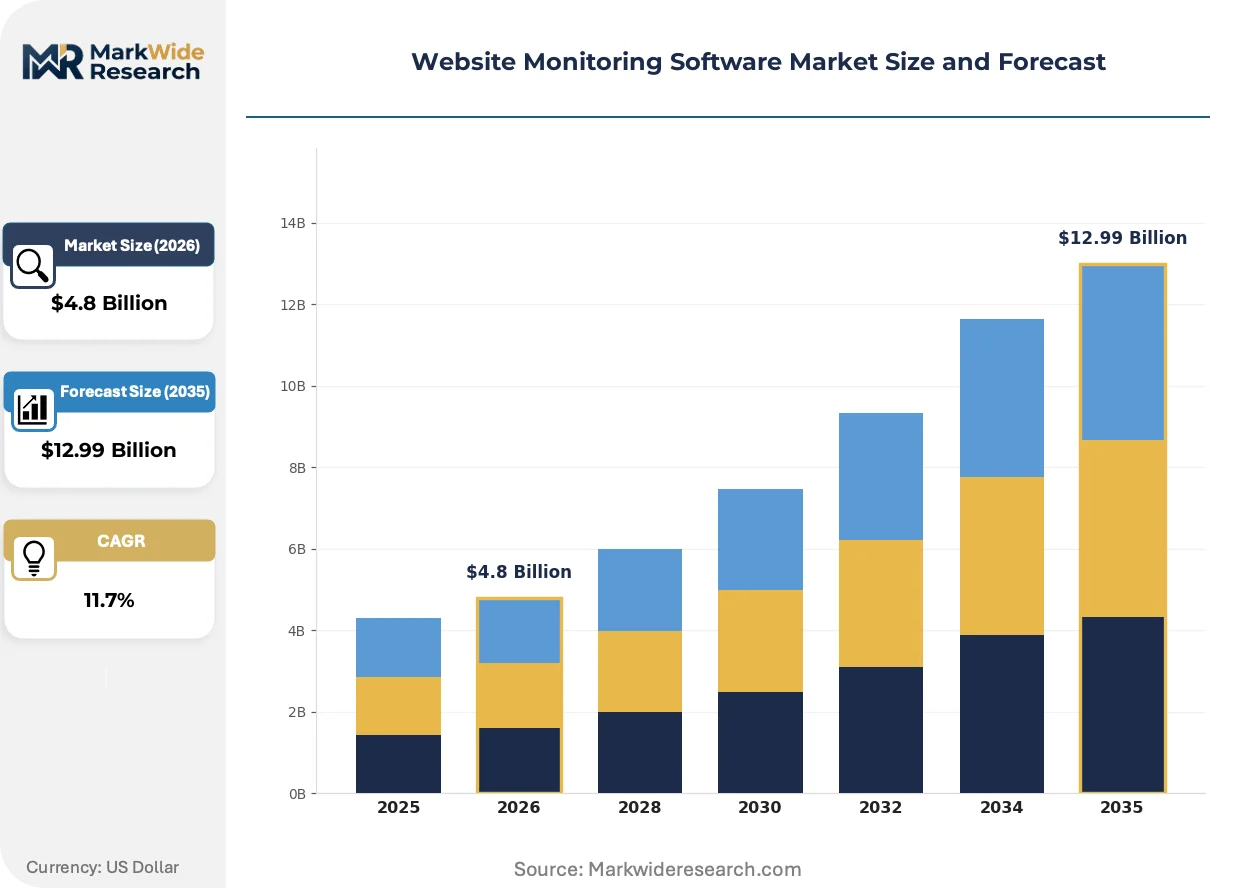
Market Dynamics
Unified observability platforms are consolidating formerly discrete monitoring functions, forcing vendors to bundle synthetic testing, real-user analytics, and security scanning into single procurement contracts rather than standalone point solutions.
Growth Catalysts
- EU AI Act risk-classification mandates:European enterprises must document automated decision-system reliability, driving demand for continuous performance validation and audit-ready incident logs.
- SaaS-based IT service providers:Cloud-native MSPs require elastic probe networks that scale with customer growth without infrastructure capital, accelerating subscription-based monitoring adoption.
- Certificate lifecycle automation:TLS expiry monitoring prevents service outages from expired credentials, with DevOps teams prioritizing proactive alerting over reactive incident response.
Market Restraints
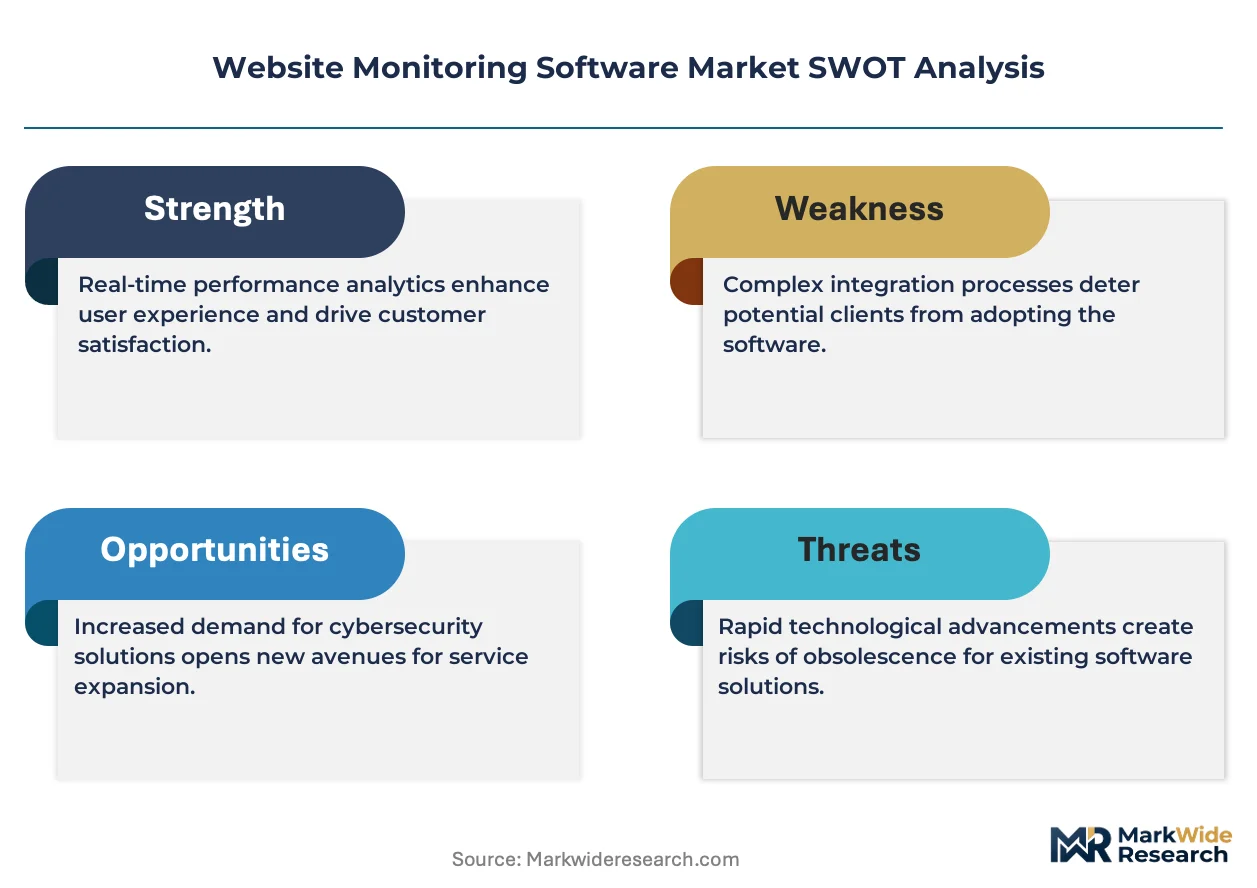
- Open-source telemetry stack proliferation:Prometheus, Grafana, and Jaeger combinations reduce willingness to pay for commercial uptime monitoring among cost-conscious engineering teams.
- Data sovereignty requirements:GDPR Article 44 cross-border transfer restrictions complicate cloud-hosted probe network deployment for European buyers evaluating US-based vendors.
- Alert fatigue saturation:Excessive notification volume from poorly tuned thresholds degrades operational response effectiveness and increases churn risk among mid-market accounts.
Strategic Opportunities
- Manufacturing Mittelstand digitization:Germany's mid-sized industrial firms are deploying customer-facing portals requiring 99.9% SLA guarantees, creating greenfield demand for transaction monitoring.
- API-first observability convergence:Combining synthetic API testing with OpenTelemetry tracing addresses microservices debugging workflows that span multiple vendor tools today.
- SEC cybersecurity disclosure alignment:US public companies facing incident reporting mandates need documented response protocols that integrated monitoring platforms can automate.
Industry Challenges
- Legacy mainframe integration complexity:Financial services institutions struggle to extend cloud-native monitoring tools to core banking systems that still process critical transactions.
- Observability engineer talent scarcity:Organizations lack personnel capable of configuring distributed tracing, SLO-based alerting, and custom dashboard development at required velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Website Monitoring Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uptime Monitoring, Performance Monitoring, Security Monitoring, User Experience Monitoring Solution: Cloud-Based, On-Premise, Hybrid, Open Source End User: Small Enterprises, Medium Enterprises, Large Enterprises, IT Service Providers Deployment: Public Cloud, Private Cloud, Dedicated Server, SaaS |
| Companies Covered | Dynatrace, Datadog, New Relic, SolarWinds, Site24x7, Pingdom, Cloudflare, Akamai Technologies, Cisco ThousandEyes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Website Monitoring Software Market Strategic Shifts
Observability data pipelines are fragmenting across edge, cloud, and on-premise environments, requiring new architectural approaches to correlation, storage cost optimization, and real-time analysis.
Real-browser synthetic monitoring is modularizing transaction testing workflows. E-commerce platforms and fintech applications now script complex checkout journeys across Chrome, Firefox, and Safari engines simultaneously. Retail DevOps teams are consolidating previously separate uptime, performance, and conversion-funnel tools into unified suites that reduce mean-time-to-detection.
GDPR breach-notification timelines are compressing incident response windows. Article 33 mandates 72-hour disclosure requirements that pressure European enterprises toward automated alert escalation with pre-documented remediation playbooks. German automotive suppliers and French insurance groups are prioritizing platforms with native EU data residency and audit-trail generation.
Enterprise buying committees are consolidating vendor relationships around platform breadth rather than point-tool depth. Mid-market technology companies that previously procured separate solutions for infrastructure metrics, log aggregation, and user experience monitoring now favor single-vendor contracts with modular pricing. This pattern is most pronounced among Series C-stage software companies in the United States seeking procurement simplification.
Website Monitoring Software Market Segmentation
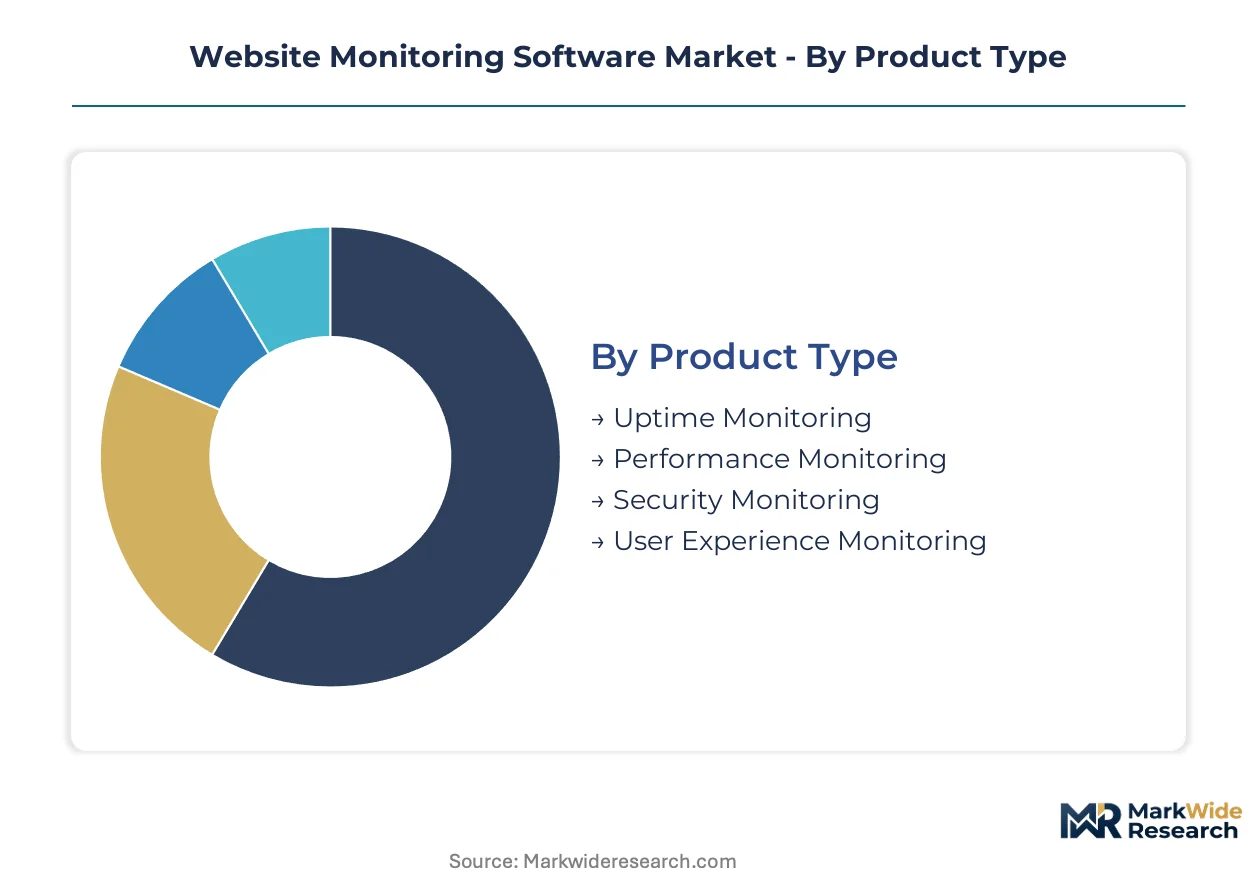
Website monitoring software segments diverge sharply between legacy infrastructure buyers and cloud-native adopters. Procurement patterns reflect whether enterprises prioritize capital control or elastic scalability. Vendor positioning must align with these divergent technical requirements and budget cycles.
Product Type:
Volume deployment clusters around basic uptime verification, while premium pricing attaches to security-integrated suites.
- Uptime Monitoring:Core availability tracking through distributed probe networks pinging endpoints at configurable intervals. German automotive suppliers and French insurance groups deploy this as foundational infrastructure for SLA compliance with 99.9% guarantees. Mature deployment sits with Uptime Monitoring.
- Performance Monitoring: Synthetic transaction testing and real-browser emulation capture page-load latency, render times, and resource waterfall analysis. SaaS-based IT service providers in the United States demand this for customer-facing application optimization, driven by conversion-rate sensitivity in e-commerce and fintech verticals. Newer deployment is concentrated in Performance Monitoring.
- Security Monitoring:TLS certificate lifecycle tracking, DNS integrity verification, and third-party script injection detection. European enterprises under GDPR and EU AI Act mandates prioritize automated alerting with audit-trail documentation for breach-notification compliance.
- User Experience Monitoring:Real-user analytics capturing session replays, frustration indicators, and journey abandonment patterns. Retail DevOps teams consolidate this with conversion-funnel tools to reduce mean-time-to-detection for revenue-impacting issues.
Security Monitoring is climbing the fastest as ransomware exposure and compliance mandates intensify scrutiny of credential expiry and supply-chain attacks.
Solution:
Deployment architecture splits between capital-intensive on-premise control and operational-expense cloud flexibility.
- Cloud-Based:Fully managed probe networks with elastic scaling, multi-tenant dashboards, and API-first integrations. SaaS-based IT service providers represent the core demand cluster, requiring infrastructure-free scaling that matches customer growth curves without data-center investment.
- On-Premise:Self-hosted monitoring stacks with complete data sovereignty and custom probe deployment. Financial services institutions in Germany and Switzerland maintain this architecture for core banking system integration where regulatory audit requirements prohibit third-party data handling.
- Hybrid:Split architectures placing sensitive transaction monitoring on-premise while leveraging cloud probes for external availability checks. Manufacturing Mittelstand firms adopt this pattern as they digitize customer portals without exposing industrial control networks.
- Open Source:Self-assembled telemetry stacks combining Prometheus, Grafana, and Jaeger for cost-conscious engineering teams. Mid-market technology companies with Series C funding constraints prioritize this for infrastructure observability while deferring commercial monitoring spend.
Hybrid solutions dominate procurement discussions where data residency requirements conflict with elastic scaling demands.
End User:
Enterprise size correlates inversely with procurement cycle length and directly with platform consolidation appetite.
- Small Enterprises:Point-tool procurement with monthly subscription flexibility and minimal configuration overhead. These buyers prioritize immediate deployment over feature depth, often selecting freemium tiers with upgrade paths.
- Medium Enterprises:Modular suite adoption consolidating previously separate uptime, performance, and log aggregation tools. United States-based Series C software companies exhibit pronounced preference for single-vendor contracts with usage-based pricing.
- Large Enterprises:Platform-wide observability mandates spanning infrastructure metrics, distributed tracing, and security monitoring. Procurement committees evaluate vendor breadth against existing DevOps toolchain investments.
- IT Service Providers:Multi-tenant monitoring platforms with customer-isolated dashboards and white-label reporting capabilities. Cloud-native MSPs require elastic probe networks that scale without infrastructure capital, accelerating subscription-based adoption across managed customer bases.
IT Service Providers are expanding most quickly as outsourced infrastructure management concentrates monitoring demand among specialized providers.
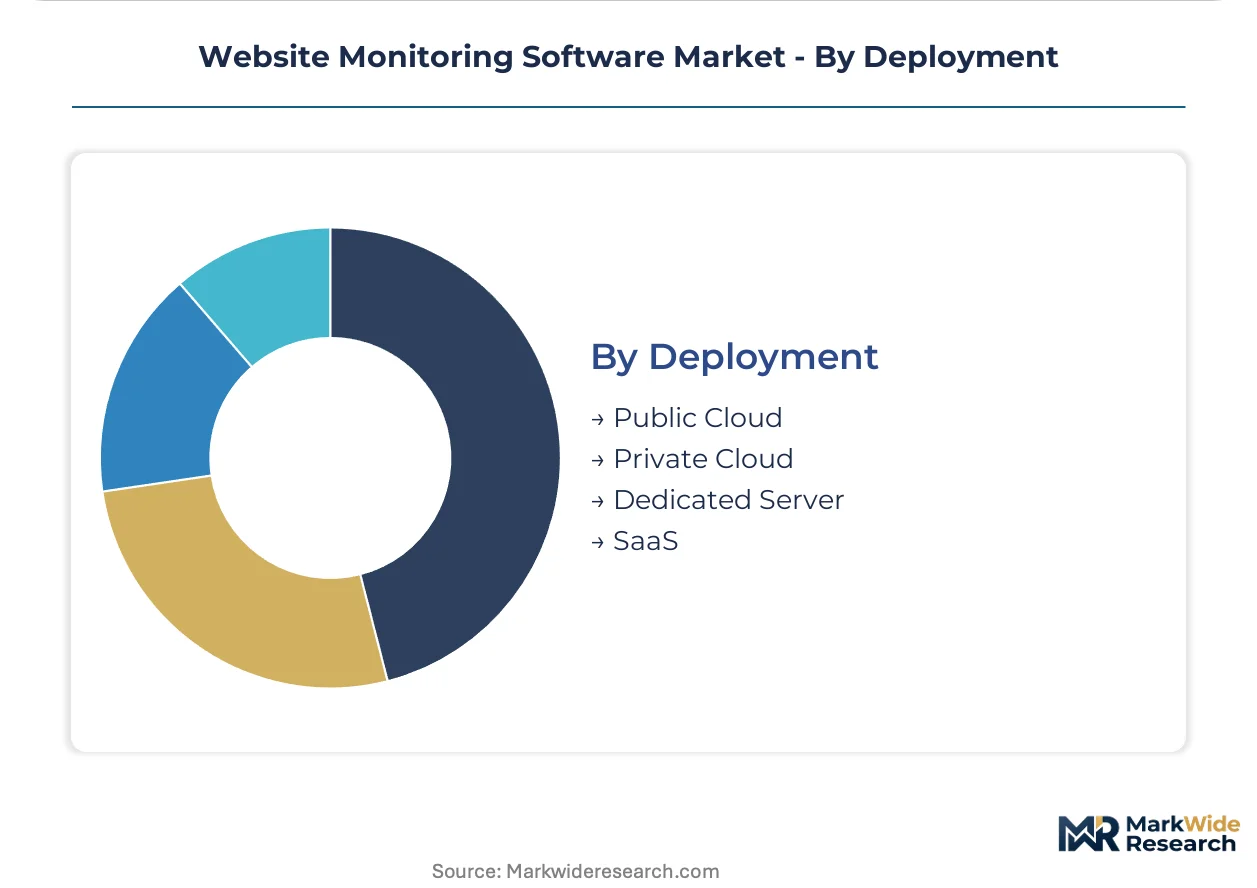
Deployment:
Infrastructure location decisions reflect data sovereignty requirements and latency sensitivity for probe placement.
- Public Cloud:Shared infrastructure with regional availability zones and automatic failover. European buyers evaluate US-based vendors against GDPR Article 44 cross-border transfer restrictions, complicating probe network deployment.
- Private Cloud:Dedicated virtualized environments with isolated compute and storage resources. German automotive suppliers and French insurance groups prioritize native EU data residency for audit-trail generation and breach-notification compliance.
- Dedicated Server:Single-tenant physical or virtual machines with guaranteed resource allocation. Financial services institutions deploy this for payment processing monitoring where regulatory mandates prohibit multi-tenant infrastructure.
- SaaS:Fully managed software delivery with browser-based configuration and automatic updates. DevOps teams prioritize this for rapid deployment without operational overhead, particularly in agile development environments.
SaaS deployment shows steepest expansion trajectory as IT service providers and mid-market enterprises prioritize operational simplicity over infrastructure control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of cloud-native SaaS headquarters creates gravitational pull for website monitoring procurement, with tax-advantaged zones in Texas and Washington State accelerating secondary cluster formation.
United States
SaaS-based IT service providers in Austin and Seattle drive elastic probe network demand as they scale multi-tenant customer bases. SEC cybersecurity disclosure rules compel public companies toward automated incident response documentation. Series C-stage software companies in San Francisco consolidate vendor relationships around platform breadth rather than point-tool depth.
Germany
Mittelstand manufacturing firms digitizing customer-facing portals require 99.9% SLA guarantees for transaction monitoring. GDPR Article 44 cross-border transfer restrictions pressure buyers toward native EU data residency. Automotive suppliers in Stuttgart and insurance groups in Munich prioritize platforms with audit-trail generation for breach-notification compliance.
United Kingdom
London-based fintech applications demand real-browser synthetic monitoring across Chrome, Firefox, and Safari engines simultaneously. Financial Conduct Authority operational resilience requirements mandate documented response protocols for digital service disruptions. DevOps teams in the City consolidate previously separate uptime, performance, and conversion-funnel tools into unified suites.
Japan
Tokyo enterprise buyers emphasize hybrid architectures placing sensitive transaction monitoring on-premise while leveraging cloud probes for external availability. METI digital transformation subsidies accelerate manufacturing digitization requiring customer portal reliability. Osaka-based industrial firms adopt split deployment patterns to protect industrial control networks from exposure.
India
Bangalore cloud-native MSPs require infrastructure-free scaling that matches customer growth curves without data-center capital investment. TRAI data localization consultations influence procurement decisions for probe network deployment. Mumbai financial services institutions evaluate SaaS solutions against RBI cybersecurity framework requirements for payment processing monitoring.
Website Monitoring Software Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Cloud infrastructure incumbents leverage existing customer relationships to attach monitoring modules, while independent vendors fight for best-of-breed positioning in synthetic testing and real-user analytics. Three archetypes dominate: platform consolidators bundling observability stacks, network-heritage specialists extending into hybrid infrastructure, and cloud-native challengers anchoring DevOps-centric contracts. Competitive moves center on M&A for telemetry data capabilities and API-first integration partnerships that embed monitoring into CI/CD pipelines.
Within the platform consolidator tier, Datadog and Dynatrace exemplify cloud-native architectures that anchor multi-product enterprise contracts. SolarWinds occupies a position among network-heritage specialists extending monitoring capabilities into hybrid infrastructure environments. New Relic sits within the full-stack visibility segment targeting mid-market digital transformation initiatives. These three companies represent divergent strategic postures rather than direct feature parity, with procurement committees evaluating breadth against existing toolchain investments.
| Leading Market Players |
|---|
| Dynatrace |
| Datadog |
| New Relic |
| SolarWinds |
| Site24x7 |
| Pingdom |
| Cloudflare |
| Akamai Technologies |
| Cisco ThousandEyes |
| Others |
Value Chain & Pricing Dynamics
Cloud-native observability architectures are displacing on-premise probe infrastructure, compressing deployment costs for SaaS-based IT service providers while concentrating supply leverage among hyperscale data-center operators in Northern Virginia, Frankfurt, and Singapore. This technology shift simultaneously reduces capital barriers for mid-market buyers and tightens vendor margins as elastic scaling becomes table stakes.
Pricing Analysis
Short lead-time deployment commands premium positioning in the Website Monitoring Software Market, with buyers paying elevated rates for same-day provisioning versus standard 30-day implementation cycles. Three-tier pricing structure across premium, standard, and economy levels segments by probe network density, retention period, and API call volume. Cost compression in the economy tier is intensifying because open-source telemetry stacks reduce willingness to pay among engineering-led procurement. SaaS-based IT service providers exhibit highest price sensitivity due to thin margin structures, while financial services institutions accept premium positioning for dedicated infrastructure and audit-trail compliance.
Supply Chain Analysis
Freight costs for dedicated server hardware and probe appliance shipments from Taiwan, China, and Germany influence total cost of ownership for hybrid deployment buyers. Raw material dependencies center on semiconductor components for edge probe devices, submarine cable capacity for transcontinental data transit, and renewable energy contracts for data-center power. Single-source vulnerability concentrates in Taiwan's advanced foundry capacity for network processing silicon. Distribution runs through direct vendor sales for enterprise accounts and cloud marketplaces for self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Observability engineer talent scarcity props pricing power for vendors with managed service capabilities, as buyers lack internal capacity to configure distributed tracing and SLO-based alerting at required velocity.
For Market Incumbents: Deploy certification investment as the priority lever. Pursue ISO 27001 and SOC 2 Type II attestations to differentiate against open-source alternatives threatening mid-market accounts. Anchor multi-product contracts through API-first integration partnerships that embed monitoring into CI/CD pipelines, reducing churn risk from alert fatigue saturation. For New Entrants and Emerging Players: Synthetic API testing convergence with OpenTelemetry tracing offers a technology-first wedge into microservices debugging workflows. Target Germany's Mittelstand manufacturing base digitizing customer-facing portals, where 99.9% SLA guarantees create greenfield demand absent incumbent relationships. Lead with usage-based pricing and rapid deployment to bypass procurement committees. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidators seeking telemetry data capabilities to complete observability stacks. Five-to-ten-year viability hinges on differentiation against hyperscaler monitoring modules. Signal to watch: Series C-stage software companies consolidating vendor relationships around single-vendor contracts, indicating platform preference inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified observability suites reduce mean-time-to-detection for retail DevOps teams consolidating previously separate tools. |
| Acquisition of Specialist Firm | Telemetry data capabilities address fragmentation across edge, cloud, and on-premise correlation requirements. |
| Geographic Expansion | Native EU data residency satisfies GDPR Article 44 restrictions for German automotive suppliers and French insurance groups. |
| Strategic Partnership | CI/CD pipeline embedding creates switching costs that defend against open-source Prometheus and Grafana combinations. |
| Product Launch | Certificate lifecycle automation prevents TLS expiry outages that DevOps teams prioritize over reactive incident response. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and DevOps team leads combined with SEC filings, hyperscaler capex disclosures, and cloud marketplace transaction data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators to validate volume and value estimates.
Granularity-level modeling operated at deployment architecture, organization size, vertical industry, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from segment-specific adoption curves weighted against infrastructure investment cycles and compliance mandate timelines. Forecast inputs incorporated IT service provider scaling patterns and Mittelstand digitization velocity.
Several conditions sit outside the modeled scope, including unannounced M&A activity, abrupt regulatory enforcement shifts, and hyperscaler entry into adjacent monitoring segments. Forecasts reflect documented assumptions about open-source competitive pressure and talent availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Certification Authority Market
Security Software
Next-Generation Intrusion Prevention System (NGIPS) Market
Security Software
Web Content Filtering Market
Security Software
Global Secure Access Service Edge Market
Security Software
Global Secure Mobile Communications Software Market
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
Network Camera Market
Security Software
Cloud Intrusion Protection Software Market
Security Software
Privileged Identity Management Market
Security Software
Vsaas Market
Security Software
Data Privacy Software Market
Security Software
Global Data Protection As a Service (Dpaas) Market
Security Software
Global Automatic Number Plate Recognition (ANPR) System Market
Security Software
Global Dynamic Application Security Testing Market
Security Software
Private Virtual Communications for Police Network Market
Security Software
Hardware Encryption Market