
 Ucaas in Banking Market | 2026-2036
Ucaas in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Ucaas in Banking Market Analytics
The EU Digital Operational Resilience Act is recalibrating the cost-of-entry calculus for cloud communications vendors serving European financial institutions. Cisco Systems Inc. leverages its Webex platform and security certifications to anchor institutional deployments across regulated banking environments. Microsoft Corporation sustains competitive pressure through deep Teams integration with Office 365 workloads already entrenched in bank IT estates. Zoom Video Communications, Inc. differentiates via video-first architecture that supports virtual wealth advisory and branchless banking models.
Unified Communications as a Service for banking delivers cloud-hosted voice, video, messaging, and contact center functions through subscription models, typically operating over encrypted SIP trunking with sub-150ms latency requirements for real-time trading floor coordination. The primary purpose is replacing capital-intensive on-premise PBX estates with elastic, API-extendable communication infrastructure that scales with branch networks and remote workforces. Hosted services and collaboration tools capture the dominant share of current banking expenditure as institutions prioritize omnichannel customer engagement and internal workforce mobility. Hybrid cloud deployment is expanding fastest among mid-tier banks seeking regulatory data sovereignty without full infrastructure ownership, while public cloud remains the margin pool for global systemically important banks with established cloud governance frameworks.
The Federal Reserve's operational resilience guidance, the EU Digital Operational Resilience Act, and PCI-DSS compliance requirements collectively shape product standards by mandating encrypted recording retention, geographic data residency, and real-time failover capabilities. HIPAA and SEC recordkeeping rules extend these obligations to banks with insurance subsidiaries or broker-dealer operations, narrowing the vendor field to providers with multi-framework certifications. Stakeholders must monitor how AI-driven analytics integration reshapes procurement criteria as regulators scrutinize algorithmic decision-making in customer-facing communications channels.
Market Dynamics
Cloud-native voice and video platforms are displacing legacy PBX estates across retail banking networks, with regulatory mandates for operational continuity accelerating procurement cycles for encrypted, API-extendable communication infrastructure.
Growth Catalysts
- EU Digital Operational Resilience Act:Financial institutions across Germany, France, and Italy must re-architect communication systems for failover compliance, creating immediate replacement demand for cloud-hosted voice infrastructure with geographic redundancy.
- Branch digitization acceleration:Regional banks in the United States are deploying virtual advisor platforms and video-enabled teller systems to reduce physical footprint while maintaining customer engagement depth.
- Hybrid cloud adoption:Mid-tier banks favor deployment models combining public cloud elasticity with private infrastructure control, enabling regulatory data sovereignty without full capital ownership of communication hardware.
Market Restraints
- Multi-framework certification costs:Vendors must maintain simultaneous compliance with PCI-DSS, HIPAA, and SEC recordkeeping rules, narrowing the qualified supplier base and extending sales cycles.
- Latency sensitivity in trading environments:Sub-150ms requirements for real-time trading floor coordination restrict viable deployment architectures and limit vendor options for capital markets segments.
- Encrypted recording retention mandates:Federal Reserve operational resilience guidance requires long-term storage of all customer-facing communications, driving substantial ongoing storage expenditure.
Strategic Opportunities
- Wealth advisory virtualization:Video-first platforms enable branchless private banking models, allowing institutions to serve high-net-worth clients without geographic proximity to physical locations.
- AI-driven analytics integration:Natural language processing layered over recorded communications extracts compliance intelligence and customer sentiment, creating new subscription revenue streams for platform vendors.
- API ecosystem expansion:Open banking frameworks in the United Kingdom and Australia mandate interoperable communication channels, rewarding vendors with robust developer toolkits and pre-built CRM connectors.
Industry Challenges
- SIP trunking security architecture:Banks must engineer encrypted session border controllers and real-time threat detection into voice networks, requiring scarce cybersecurity engineering talent.
- Legacy PBX migration complexity:Parallel operation of on-premise estate and cloud platform during transition periods demands dual skill sets and extended technical support contracts.
- Algorithmic decision scrutiny:Regulators are examining AI-powered routing and sentiment analysis in customer channels, creating compliance uncertainty for institutions deploying advanced automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ucaas in Banking Market |
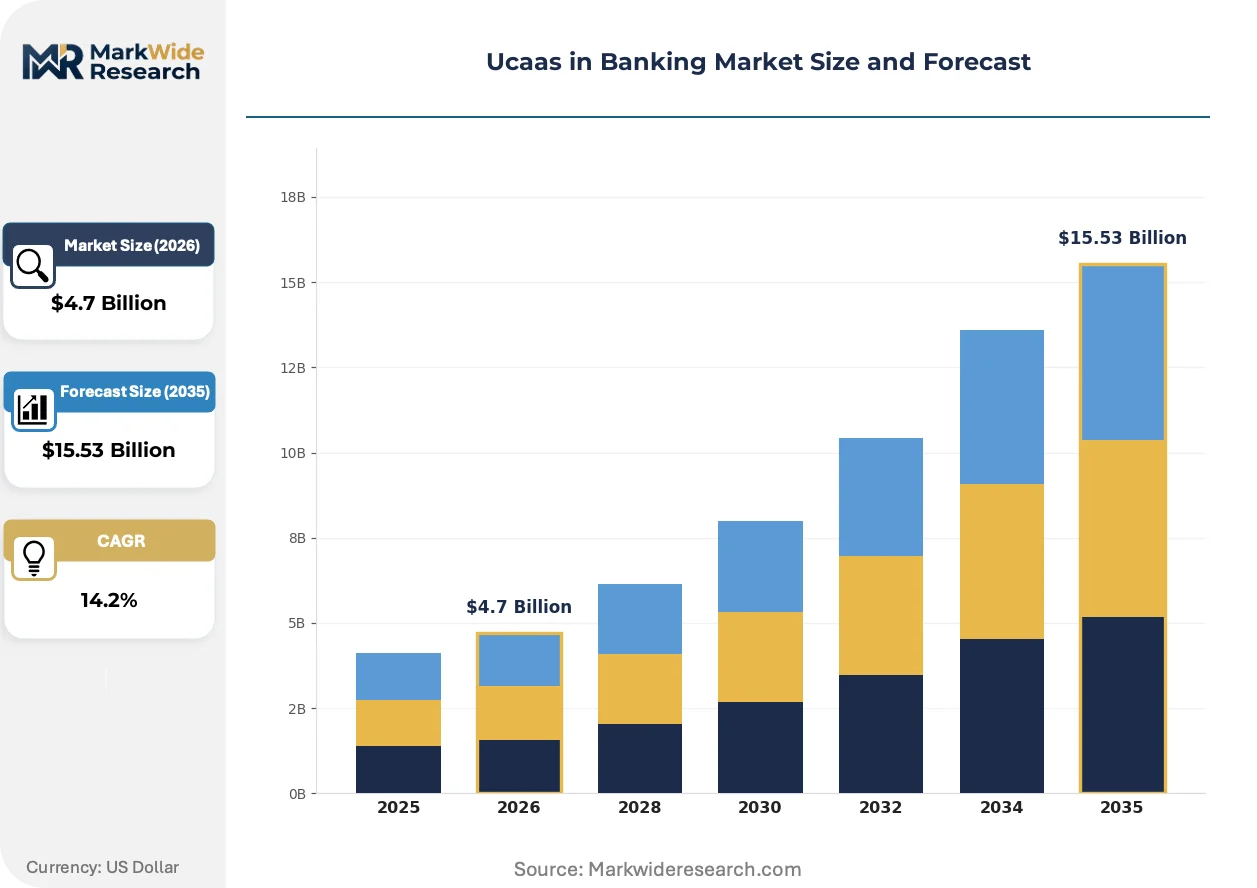
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hosted Services, Managed Services, Collaboration Tools, Communication APIs Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-premise End User: Retail Banks, Investment Firms, Credit Unions, Savings Institutions Technology: VoIP, SIP Trunking, Video Conferencing, AI-Driven Analytics |
| Companies Covered | RingCentral, Inc., 8X8 Inc., Cisco Systems Inc., Microsoft Corporation, Zoom Video Communications, Inc., Sangoma, Avaya, Vonage, Nextiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ucaas in Banking Market Evolving Landscape
Artificial intelligence and embedded compliance automation are redefining how banks evaluate communication platform vendors, with procurement criteria shifting from feature checklists to demonstrated regulatory adaptability and API extensibility.
Conversational AI with real-time transcription and sentiment analysis is automating compliance documentation and quality assurance in customer service channels. Tier-one banks in North America are deploying these tools across retail contact centers to reduce manual review overhead. The technology is automating previously labor-intensive supervision workflows while generating structured data for regulatory examination.
The EU Digital Operational Resilience Act mandates geographic redundancy and real-time failover capabilities for all critical communication infrastructure serving European financial institutions. Vendors must architect multi-region deployments with automated disaster recovery testing to maintain certification eligibility. German and French banks are prioritizing providers with pre-validated compliance frameworks over feature-rich alternatives.
Subscription-based consumption models are displacing perpetual licensing for core banking communication infrastructure. Regional banks in the United States favor per-seat pricing with elastic scaling to match branch network fluctuations. This shift concentrates vendor relationships with platform providers capable of delivering unified voice, video, and contact center functions through single contracts.
Ucaas in Banking Market Segmentation
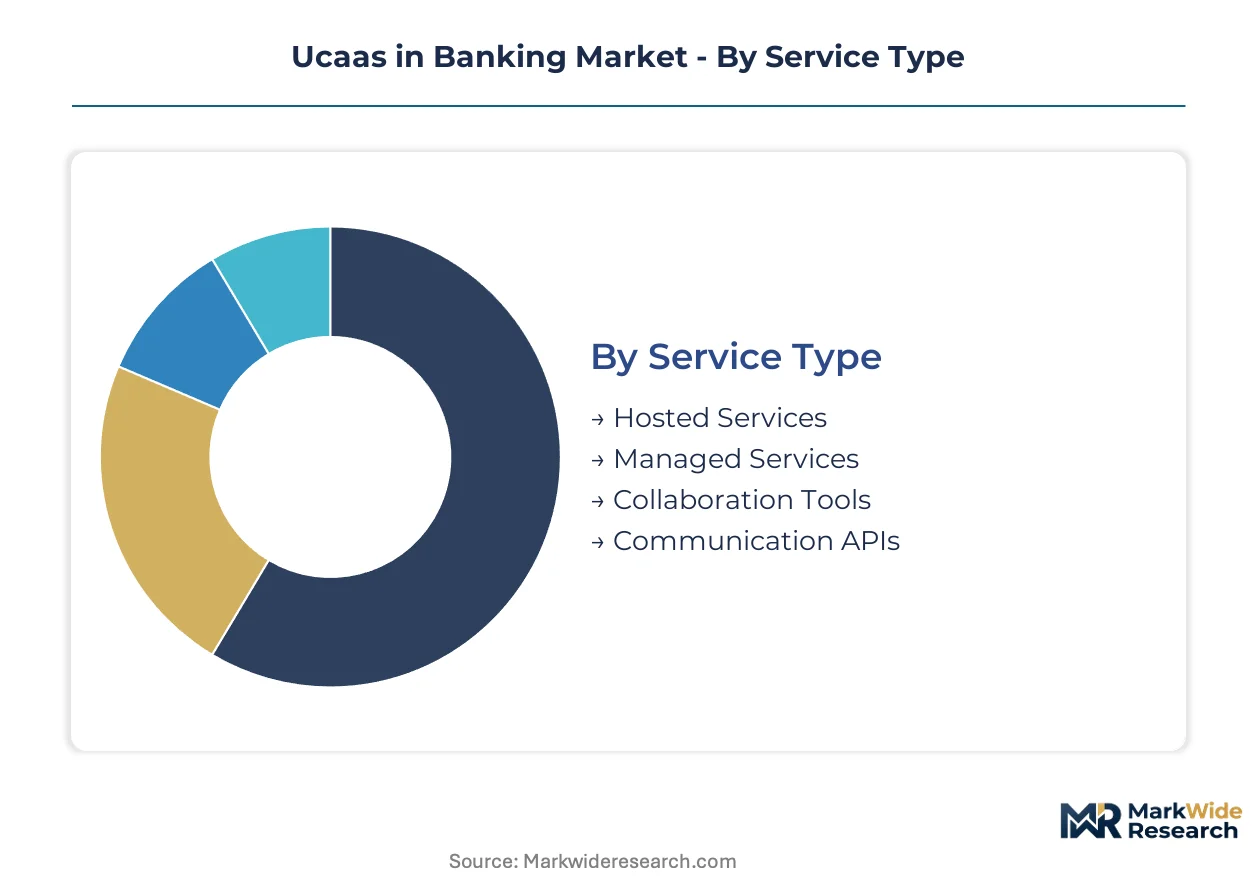
Segmentation in UCaaS banking procurement reveals how institutions balance regulatory mandates against operational flexibility. Each dimension—service delivery, infrastructure ownership, institutional type, and underlying technology—creates distinct vendor qualification pathways and cost structures.
Service Type:
Customization intensity varies sharply across this category, from standardized API layers to bespoke managed service arrangements.
- Hosted Services:Cloud-delivered voice and video infrastructure operated by third-party providers under SLA-governed contracts. Regional banks in the United States concentrate demand here as they retire legacy PBX estates without building internal cloud operations teams. The Federal Reserve's operational resilience guidance accelerates procurement for encrypted, geographically redundant hosted platforms.
- Collaboration Tools:Integrated messaging, file sharing, and meeting platforms extending core communication infrastructure. Investment firms with distributed trading desks drive adoption, requiring sub-150ms latency for real-time coordination across multiple time zones. Integration with existing Office 365 or Google Workspace estates shapes vendor selection criteria.
- Managed Services:Fully outsourced communication operations including monitoring, patching, and compliance documentation. European institutions facing EU Digital Operational Resilience Act mandates favor this model to transfer continuity accountability.
- Communication APIs:Programmable interfaces embedding voice, SMS, and video into proprietary banking applications. Fintech partnerships and mobile-first retail banks represent primary demand concentration.
Leading the category by volume: Hosted Services. Growing fastest: Communication APIs.
Deployment:
Capital deployment patterns track institutional size and regulatory jurisdiction, with mid-tier banks seeking middle-ground solutions between full cloud and full ownership.
- Hybrid Cloud:Workload distribution across public cloud elasticity and private infrastructure for sensitive data. Mid-tier banks in Germany and France prioritize this model to satisfy EU data sovereignty requirements without absorbing full data center capital costs. The architecture permits customer-facing functions on public cloud while retaining transaction records in controlled private environments.
- Public Cloud:Fully outsourced infrastructure with multi-tenant resource sharing. Global systemically important banks with mature cloud governance frameworks dominate this segment, leveraging established relationships with hyperscale providers.
- Private Cloud:Single-tenant dedicated infrastructure either on-premise or in exclusive hosted environments. Swiss private banks and Luxembourg wealth managers favor this model for client confidentiality assurance.
- On-premise:Legacy estate retention with minimal cloud integration. Smaller savings institutions with limited IT modernization budgets maintain this posture, though attrition accelerates.
Hybrid Cloud claims the largest current deployment base. Public Cloud exhibits the steepest expansion trajectory among institutions completing digital transformation programs.
End User:
Institutional type determines feature prioritization, from retail branch networks to trading floor coordination requirements.
- Retail Banks:Branch networks and contact centers serving mass-market consumers. United States regional banks are replacing teller systems with video-enabled remote advisor platforms to reduce physical footprint while maintaining engagement depth. Omnichannel integration with mobile banking apps drives platform selection.
- Investment Firms:Broker-dealers and asset managers with intensive real-time communication needs. SEC recordkeeping rules and trading floor latency requirements restrict viable vendor options to providers with financial services specialization and certified compliance frameworks.
- Credit Unions:Member-owned cooperative institutions with constrained IT budgets. Per-seat subscription pricing with elastic scaling matches their fluctuating branch network sizes and seasonal membership patterns.
- Savings Institutions:Deposit-focused banks with conservative technology postures. Gradual migration from legacy PBX systems proceeds alongside core banking modernization timelines.
Retail Banks anchor category volume. Investment Firms command premium pricing tiers and specialized vendor relationships.
Technology:
Underlying protocol and intelligence layers differentiate commodity connectivity from value-added platform capabilities.
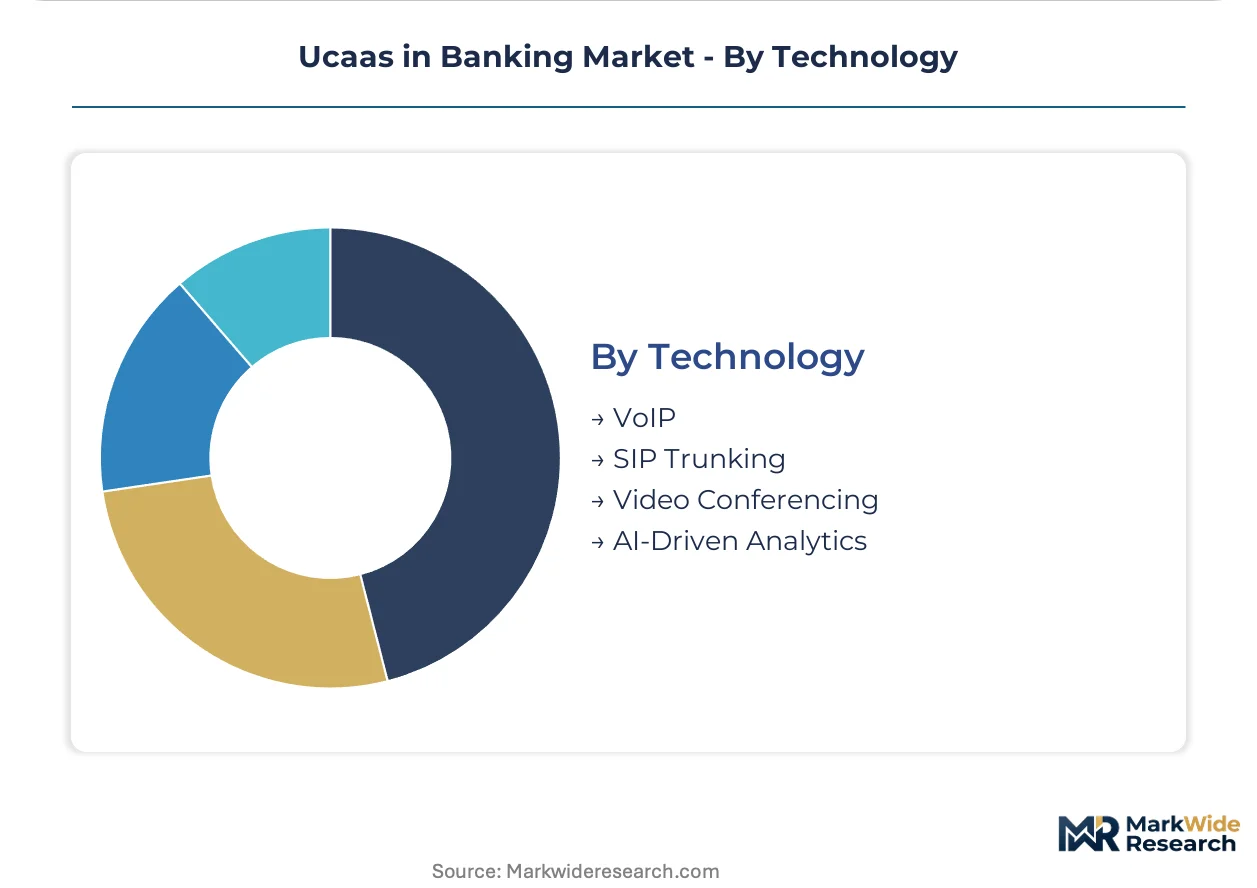
- AI-Driven Analytics:Natural language processing and sentiment analysis layered over recorded communications. Tier-one North American banks deploy these tools across retail contact centers to automate compliance documentation and generate structured supervisory data. Regulator scrutiny of algorithmic decision-making in customer channels creates procurement uncertainty despite operational efficiency gains.
- SIP Trunking:Session Initiation Protocol connectivity replacing traditional PSTN voice circuits. Encrypted session border controllers and real-time threat detection requirements demand scarce cybersecurity engineering talent for implementation.
- VoIP:Voice over Internet Protocol delivering telephony over data networks. Mature technology with widespread adoption across all institution sizes, now baseline rather than differentiating.
- Video Conferencing:Synchronous visual communication supporting virtual wealth advisory and branchless banking models. High-net-worth client service without geographic proximity dependence drives private banking adoption.
VoIP and SIP Trunking constitute the established technology base. AI-Driven Analytics is gaining share fastest as institutions seek automated compliance extraction and customer intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level tax incentives for financial technology operations in the United States are concentrating cloud communications procurement among regional banking headquarters clusters.
United States
Regional banks accelerate branch digitization and deploy video-enabled remote advisor platforms to reduce physical footprint. The Federal Reserve's operational resilience guidance mandates encrypted recording retention and geographic redundancy for customer-facing communications. Charlotte, North Carolina and Dallas, Texas anchor procurement concentration as major regional bank headquarters re-architect legacy PBX estates.
Germany
Mid-tier banks favor hybrid cloud deployment to satisfy data sovereignty requirements without absorbing full data center capital costs. The EU Digital Operational Resilience Act forces re-architecture of communication infrastructure for real-time failover compliance. Frankfurt's financial district drives vendor qualification pathways as institutions prioritize pre-validated compliance frameworks.
United Kingdom
Open banking frameworks mandate interoperable communication channels, rewarding vendors with robust developer toolkits. The Financial Conduct Authority scrutinizes algorithmic decision-making in customer-facing channels. London's fintech corridor concentrates API ecosystem expansion as mobile-first retail banks embed programmable voice and video into proprietary applications.
France
Wealth advisory virtualization enables branchless private banking models for high-net-worth clients without geographic proximity. GDPR and EU Digital Operational Resilience Act requirements narrow qualified supplier bases. Parisian private banks and Luxembourg wealth managers drive demand for single-tenant dedicated infrastructure assuring client confidentiality.
Japan
Investment firms with distributed trading desks require sub-150ms latency for real-time coordination across multiple time zones. METI guidelines shape cybersecurity engineering standards for encrypted session border controllers. Tokyo's capital markets district concentrates specialized vendor relationships for broker-dealer operations facing SEC recordkeeping obligations.
Ucaas in Banking Market Competitive Landscape
United States-based platform providers anchor the consolidated tier; European specialists hold compliance-certification advantages in regulated jurisdictions. The vendor base concentrates around three strategic archetypes: hyperscale cloud integrators with entrenched enterprise productivity suites, video-first specialists supporting virtual advisory models, and legacy telecom vendors transitioning subscription revenue streams. Dominant competitive moves include M&A activity targeting API ecosystem capabilities and strategic partnerships with core banking software providers.
Within the hyperscale tier, Microsoft Corporation and Cisco Systems Inc. exemplify platform providers leveraging existing IT estate penetration to anchor institutional deployments. Zoom Video Communications, Inc. occupies a distinct position among video-first architects enabling branchless banking and virtual wealth advisory models. These three entities represent the competitive concentration around which mid-tier specialists and regional service providers orbit.
| Leading Market Players |
|---|
| RingCentral, Inc. |
| 8X8 Inc. |
| Cisco Systems Inc. |
| Microsoft Corporation |
| Zoom Video Communications, Inc. |
| Sangoma |
| Avaya |
| Vonage |
| Nextiva |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up UCaaS specialists anchor supply consolidation across North American banking corridors, concentrating pricing power with vendors holding multi-framework certifications while compressing margins for undifferentiated hosted voice providers.
Pricing Analysis
Short lead-time deployments command premium positioning as regional banks accelerate branch digitization timelines under Federal Reserve operational resilience deadlines. Three-tier pricing structure across enterprise, mid-market, and entry-level tiers stratifies by certification depth and geographic redundancy guarantees. Pricing pressure stems from hyperscaler bundling of communication tools with existing productivity suites, eroding standalone vendor margins. Credit unions and community banks exhibit highest price sensitivity, while global systemically important banks prioritize compliance assurance over cost.
Supply Chain Analysis
Encrypted session border controller supply rests on Israeli, American, and British cybersecurity engineering talent pools with financial services specialization. Hyperscale data center capacity, submarine cable infrastructure, and specialized SIP trunking hardware constitute critical input dependencies. Single-source vulnerability concentrates in certified compliance documentation services required for EU Digital Operational Resilience Act adherence. Distribution runs through direct enterprise sales teams and core banking software vendor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-framework certification bottlenecks constrain qualified vendor supply, propping pricing discipline for certified providers while excluding speculative entrants from regulated procurement channels.
For Market Incumbents: Anchor institutional relationships through pre-validated compliance frameworks covering PCI-DSS, HIPAA, and SEC recordkeeping simultaneously. Deepen vertical integration into AI-driven analytics layers to capture subscription revenue from automated compliance documentation. Defend against hyperscaler bundling by emphasizing sub-150ms latency guarantees for trading floor segments. For New Entrants and Emerging Players: The mid-tier hybrid cloud gap between hyperscale public deployments and legacy on-premise retention offers white-space expansion across German and French banking markets. Target API ecosystem partnerships with mobile-first retail banks in United Kingdom open banking corridors. Pursue communication-embedded fintech integrations as the fastest-penetrable entry vector. For Investors and Strategic Acquirers: Distressed-cycle entries favor managed service specialists with established EU Digital Operational Resilience Act compliance frameworks in Frankfurt and Paris clusters. Long-term viability centers on vendors demonstrating regulatory adaptability across multiple jurisdictions rather than feature velocity. Watch AI-powered routing scrutiny by the Financial Conduct Authority as an inflection indicator for compliance automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Framework Certification Investment | PCI-DSS, HIPAA, and SEC compliance unlocks regulated banking procurement channels. |
| AI Analytics Layer Integration | Natural language processing over recorded communications generates recurring compliance revenue streams. |
| Core Banking Software Partnership | Pre-built CRM connectors accelerate deployment velocity for regional bank digitization programs. |
| Hybrid Cloud Architecture Development | Mid-tier German and French banks prioritize data sovereignty without full infrastructure ownership. |
| API Ecosystem Expansion | Open banking mandates in United Kingdom and Australia reward programmable communication embedding. |
Research Methodology
Independent corroboration across chief technology officers at regional banks, compliance officers facing Federal Reserve guidance, and UCaaS platform engineers underwrites the qualitative findings. Primary interviews with IT procurement leads, contact center operations directors, and cybersecurity architects combined with secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory bulletins. Bottom-up deployment sizing and top-down market triangulation cross-check volume estimates.
Comparable historical reference periods anchored the forecast window to pre-pandemic baseline infrastructure spending and post-DORA acceleration phases across the analysis window. Segmentation modeling incorporated service delivery mode, deployment architecture, institutional type, and underlying technology protocol. CAGRs derived from elasticity-adjusted adoption curves and regulatory mandate implementation timelines, with latency-sensitive trading floor requirements and encrypted retention mandates as industry-specific inputs.
Underlying measurement precision varies by segment; hosted services and public cloud deployments carry tighter precision than emerging AI analytics categories. Forecasts reflect assumptions about regulatory enforcement consistency and certification maintenance costs. Ongoing watch centers on Federal Reserve operational resilience guidance evolution and EU AI Act algorithmic decision scrutiny in customer channels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
United States SMS and MMS Market
Unified Communications
Business Cloud Voip and UC Services Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
Unified Communication Market
Unified Communications
High Definition HD Voice Market
Unified Communications
Ucaas in the Manufacturing Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Cloud UC Calling Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market