
 High Definition HD Voice Market | 2026-2036
High Definition HD Voice Market Size, Share, and Industry Trends Forecast 2026-2036
High Definition HD Voice Market Foresight
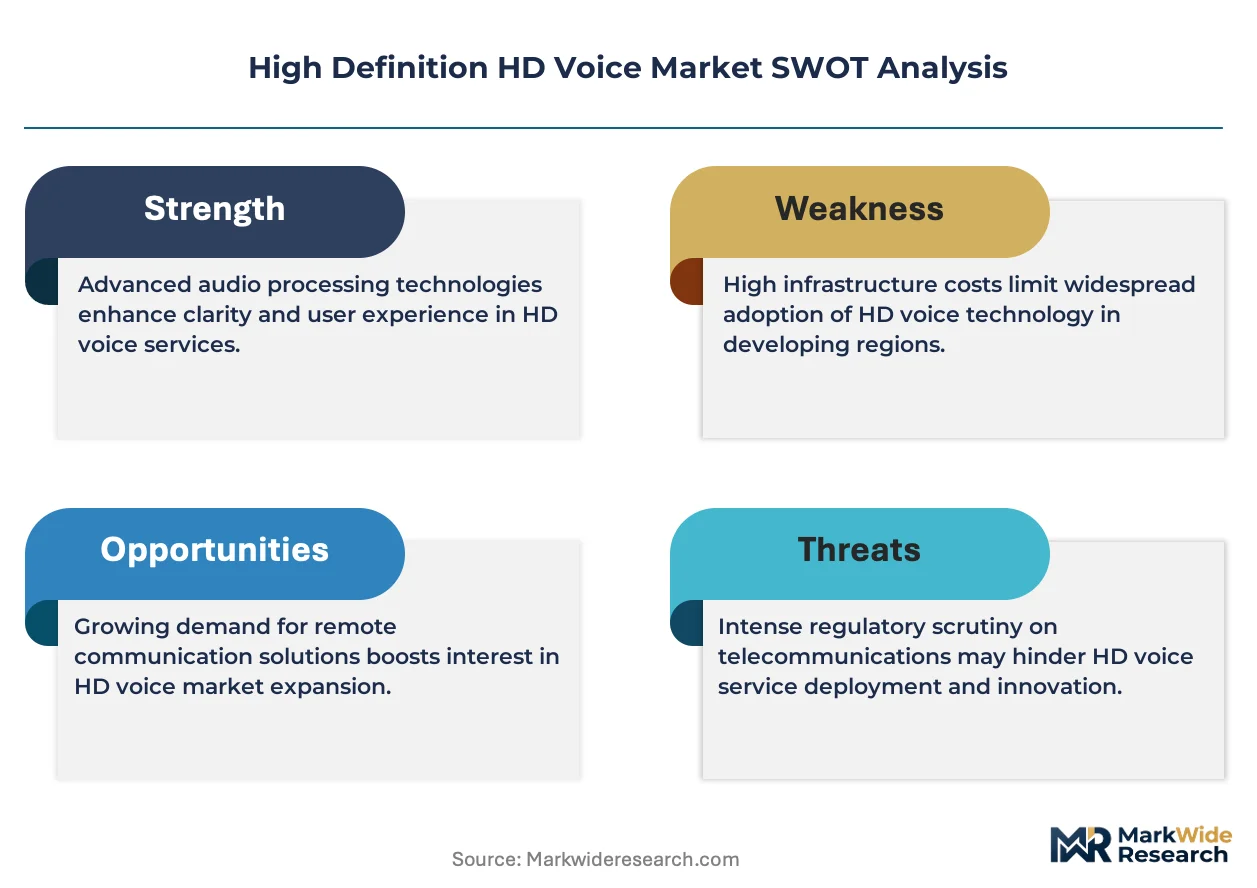
Platform licensing is fragmenting across VoIP and unified communications ecosystems as vendors compete for enterprise switching cycles. Cisco Systems dominates enterprise-grade HD voice infrastructure through its WebEx and Unified Communications portfolios. Nokia Networks anchors mobile network deployments with AMR-WB codec integration across carrier-grade infrastructure. Orange S.A. leverages its European fiber backbone to extend wideband voice services to business customers in France and neighboring markets.
High Definition HD Voice refers to telephony systems transmitting audio across a wider frequency range than traditional narrowband calls, typically spanning 50 Hz to 7 kHz or higher using codecs such as AMR-WB or EVS rather than the legacy 300–3.4 kHz band. Its primary commercial purpose is to deliver intelligibility gains for remote collaboration, customer service, and telemedicine where conversational clarity reduces fatigue and error rates. Cloud-based deployment leads among enterprise adopters seeking scalable subscription models without premise hardware refresh cycles. VoIP product types capture the largest revenue pool as SIP trunking displaces TDM circuits, while WebRTC technology segments are expanding fastest through browser-embedded conferencing requiring no client installation.
The FCC mandates IP-transition timelines that compel US carriers to retire copper PSTN facilities, directly accelerating HD voice substitution. ETSI and 3GPP standards in Europe enforce wideband codec interoperability across national roaming agreements, shaping vendor certification requirements. Stakeholders must monitor codec royalty structures and spectrum auction conditions that determine whether mobile operators prioritize VoLTE capacity expansion or delay HD voice feature rollout.
Market Dynamics
The FCC's IP-transition mandates are dismantling copper PSTN infrastructure, forcing carriers to accelerate wideband codec deployment across enterprise and consumer networks while ETSI interoperability standards reshape vendor certification requirements.
Growth Catalysts
- VoLTE Network Expansion:Mobile operators in Germany and France are prioritizing AMR-WB codec activation across 4G and 5G cores, driving subscriber migration from narrowband voice.
- Enterprise Cloud Migration:SIP trunking adoption in financial services and healthcare verticals is displacing TDM circuits, creating immediate demand for wideband audio endpoints.
- ETSI Wideband Mandates:European roaming agreements now enforce EVS codec interoperability, compelling infrastructure vendors to certify cross-border compatibility.
Market Restraints
- Codec Royalty Stacking:Patent pools for AMR-WB and EVS impose per-unit licensing costs that compress margins on low-ARPU consumer plans.
- Legacy Endpoint Inertia:Narrowband handset installed bases in Eastern European markets delay network-wide wideband activation despite core readiness.
- Spectrum Auction Timing:Mobile operators in India and Brazil defer VoLTE capacity investments when 5G spectrum costs consume capital budgets.
Strategic Opportunities
- Telemedicine Audio Standards:Remote diagnostic workflows in rural India and Southeast Asia require intelligibility thresholds that wideband codecs satisfy.
- WebRTC Browser Convergence:Embedded conferencing without client installation is opening SMB segments previously blocked by IT deployment friction.
- FCC Copper Retirement Deadlines:US carrier infrastructure replacement cycles create vendor switching windows for cloud-native platform providers.
Industry Challenges
- Interoperability Certification Backlogs:Multi-vendor testing for EVS fallback compatibility extends product launch timelines by six to nine months.
- Legacy PBX Integration Complexity:Hybrid TDM-IP environments in German manufacturing require gateway architectures that degrade end-to-end wideband quality.
- Specialized Audio Engineering Talent:Acoustic design and codec optimization expertise concentrates in Finnish and Swedish vendor R&D centers, creating recruitment bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Definition HD Voice Market |
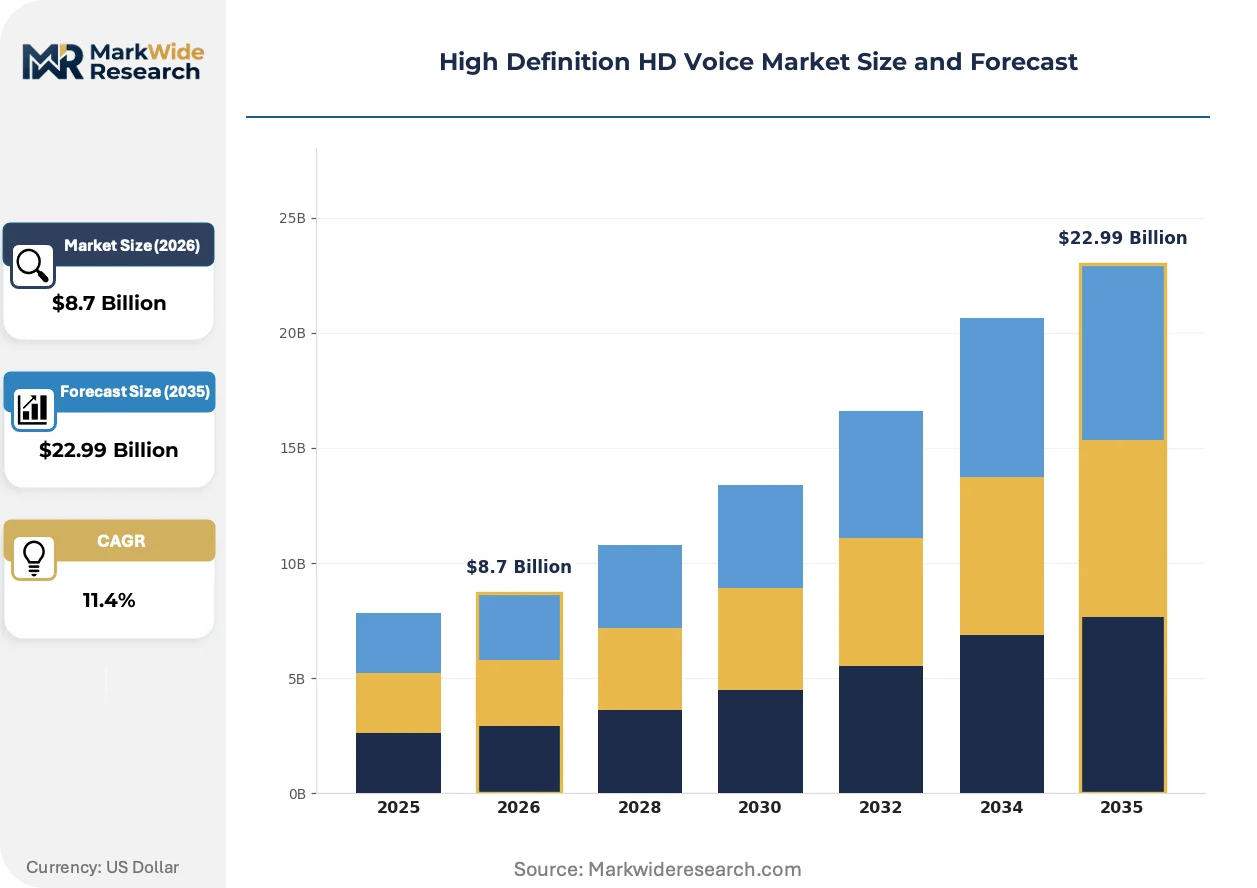
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VoIP, PSTN, Mobile, Unified Communications End User: Telecom Operators, Enterprises, Individuals, Call Centers Technology: Codec, SIP, WebRTC, MPLS Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Telefonaktiebolaget LM Ericsson, AT&T Inc, Verizon Communication Inc, Cisco Systems Inc, Deutsche Telekom AG, Orange S.A., Nokia Networks, Alcatel-Lucent Enterprise, Avaya Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Definition HD Voice Market Shifts & Advancements
Codec architecture is fragmenting across cloud-native and edge-deployed instances, with deployment topology becoming the primary differentiator in enterprise RFPs. Three developments are compressing competitive timelines.
Enhanced Voice Services (EVS) is hybridizing mobile and fixed-network quality expectations by delivering full-band audio across variable bitrates. Tier-one carriers in South Korea and Japan are mandating EVS as the default voice codec for 5G standalone cores. This convergence is collapsing the historical performance gap between cellular and enterprise VoIP, forcing infrastructure vendors to unify their codec roadmaps.
The FCC's 2024 copper retirement order is accelerating PSTN substitution timelines, with state-level public utility commissions now enforcing facility decommissioning schedules. Rural incumbent local exchange carriers face stranded asset risks as subscriber counts fall below economic maintenance thresholds. Wholesale voice providers are responding by pre-positioning session border controllers in secondary US markets to capture switching traffic.
Enterprise procurement of voice infrastructure is consolidating around subscription-based consumption models that bundle endpoint management with usage pricing. System integrators in France and the Netherlands are displacing direct vendor relationships by offering multi-carrier SIP trunk aggregation. This channel shift is most pronounced in mid-market professional services firms seeking to outsource telephony operations without capital commitment.
High Definition HD Voice Market Segmentation
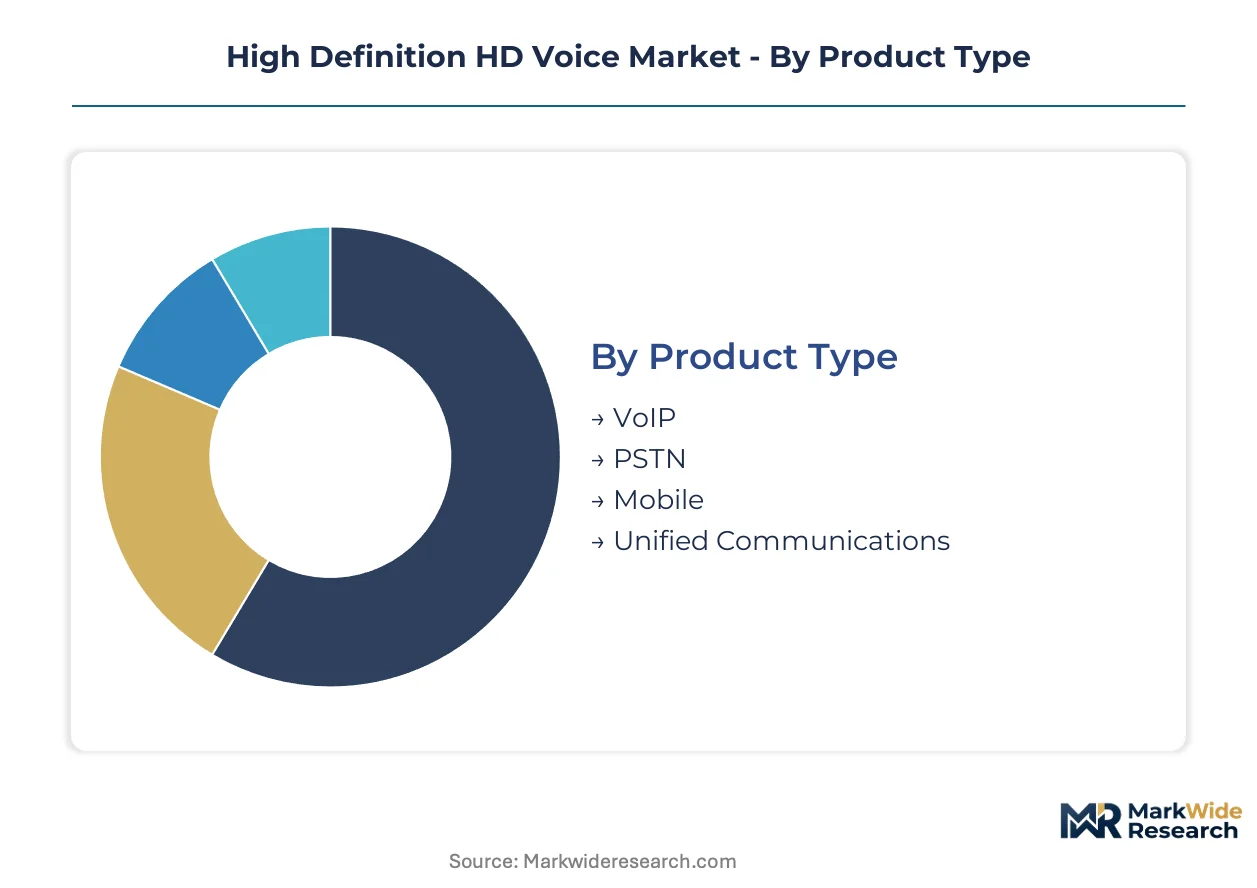
HD voice market segmentation reveals distinct service intensity profiles across deployment modes and end-user categories. Technical architecture choices directly determine recurring support obligations, codec licensing exposure, and infrastructure refresh cycles.
Product Type:
After-sales service intensity varies sharply across product categories, with premise-based systems demanding field engineering support while cloud alternatives shift burden to vendor operations centers.
- VoIP:Session Initiation Protocol trunking dominates enterprise infrastructure replacement, with SIP interoperability testing consuming substantial vendor certification resources. Financial services firms in Germany and the United States are displacing TDM circuits fastest, though hybrid gateway architectures in manufacturing environments degrade end-to-end wideband quality.
- Unified Communications:Integrated voice-video-messaging platforms bundle HD voice as a standard feature rather than premium add-on, collapsing standalone codec licensing as a revenue line. Enterprise procurement in France and the Netherlands is consolidating around subscription consumption models that outsource telephony operations entirely.
- Mobile:VoLTE network cores require carrier-grade codec activation across 4G and 5G infrastructure, with per-unit licensing costs compressing margins on consumer plans.
- PSTN:Legacy copper infrastructure retirement is accelerating substitution timelines, though narrowband handset installed bases in Eastern European markets delay network-wide activation.
VoIP holds the largest share; momentum sits with Unified Communications.
End User:
Cost tier stratification separates enterprise buyers seeking SLA-guaranteed quality from consumer segments tolerating best-effort service levels.
- Enterprises:Healthcare and financial services verticals mandate intelligibility thresholds for compliance documentation, with cloud migration displacing capital-intensive premise hardware. SIP trunk aggregation by system integrators is displacing direct vendor relationships in mid-market professional services firms.
- Telecom Operators:Mobile carriers in South Korea and Japan are mandating EVS as default voice codec for 5G standalone cores, collapsing historical performance gaps between cellular and fixed networks. Spectrum auction timing in India and Brazil defers VoLTE capacity investments when 5G spectrum costs consume capital budgets.
- Call Centers:Remote diagnostic workflows in rural India and Southeast Asia require wideband codec deployment for conversational clarity that reduces error rates.
- Individuals:Consumer adoption concentrates where carrier marketing emphasizes perceptible quality differentiation, with Deutsche Telekom driving widespread wideband audio adoption across German consumer segments.
Enterprises command premium pricing; call centers are expanding most quickly.
Technology:
Volume concentration in codec licensing creates patent pool dependency, while transport protocols compete on interoperability certification speed.
- Codec:AMR-WB and EVS patent pools impose per-unit licensing costs, with ETSI and 3GPP standards enforcing wideband interoperability across European roaming agreements. Multi-vendor testing for EVS fallback compatibility extends product launch timelines.
- WebRTC:Browser-embedded conferencing eliminates client installation friction, opening SMB segments previously blocked by IT deployment overhead.
- SIP:Session border controller pre-positioning in secondary US markets is capturing switching traffic from rural incumbent local exchange carriers.
- MPLS:Private network transport maintains quality-of-service guarantees for enterprise voice, though SD-WAN substitution is eroding dedicated circuit demand.
Codec holds the largest share; WebRTC shows steepest expansion trajectory.
Deployment:
Customer type determines control preference, with regulated industries demanding data sovereignty while growth-stage firms prioritize scalability.
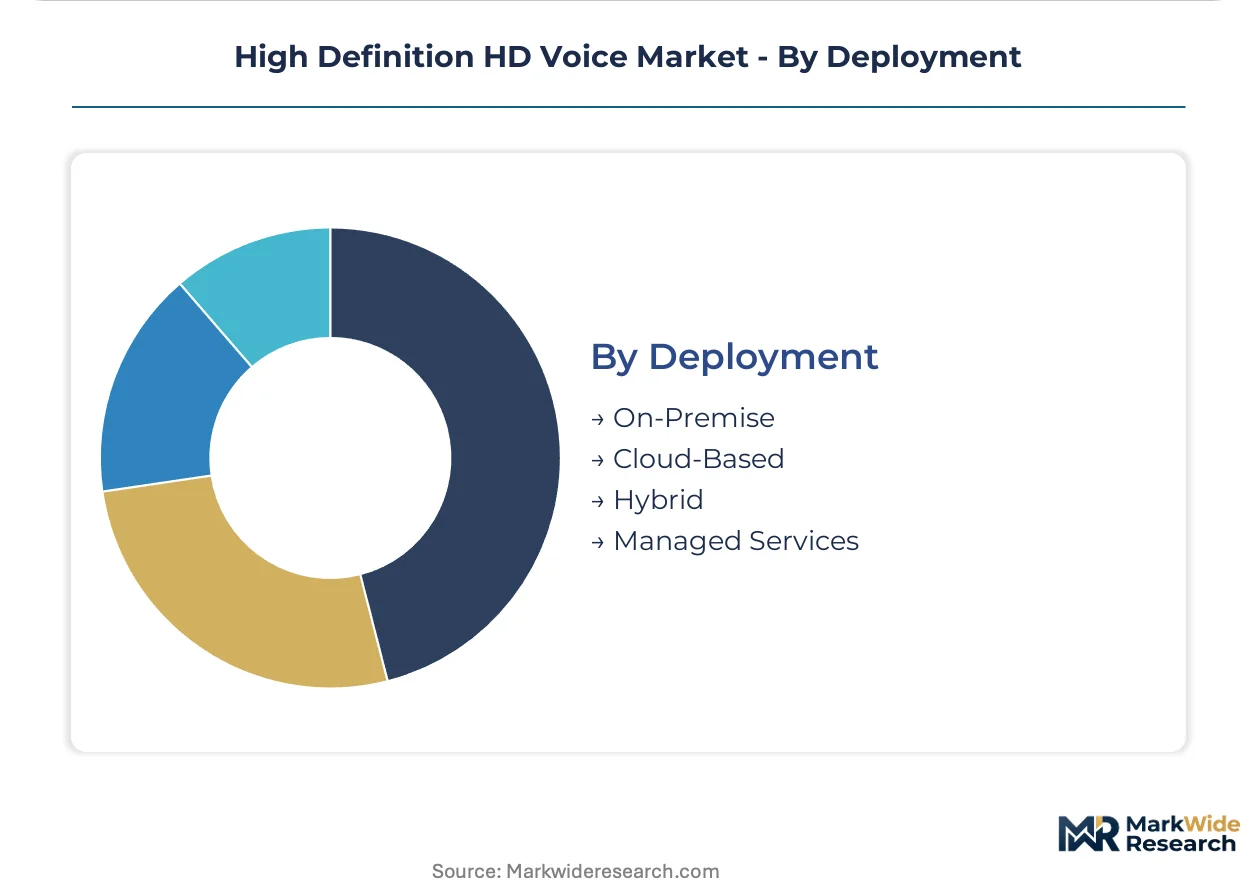
- Cloud-Based:Subscription models bundle endpoint management with usage pricing, eliminating capital commitment for mid-market adopters. FCC copper retirement deadlines are creating vendor switching windows for cloud-native platform providers.
- Hybrid:TDM-IP gateway architectures in German manufacturing preserve legacy investment while enabling incremental wideband migration, though codec transcoding degrades end-to-end quality.
- On-Premise:Financial institutions and government agencies maintain physical infrastructure for compliance audit trails, sustaining demand for certified integrators.
- Managed Services:Outsourced operations transfer codec optimization and interoperability certification burden to specialized providers, concentrating acoustic engineering talent recruitment in Finnish and Swedish R&D centers.
Cloud-Based holds the largest share; Managed Services is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish and Swedish R&D centers concentrate acoustic engineering talent for codec optimization, while carrier infrastructure deployment clusters in German industrial regions and South Korean metropolitan networks. Regulatory mandates in the United States and European Union are accelerating copper retirement and interoperability standards respectively.
United States
Enterprise cloud migration and FCC copper retirement deadlines drive infrastructure replacement cycles. The FCC's 2024 order compels state-level public utility commissions to enforce facility decommissioning schedules. Rural incumbent local exchange carriers in secondary Midwest markets face stranded asset risks as wholesale voice providers pre-position session border controllers to capture switching traffic.
Germany
Deutsche Telekom's wideband audio adoption spans consumer and business segments with manufacturing verticals demanding hybrid TDM-IP gateway architectures. ETSI standards enforce EVS codec interoperability across national roaming agreements. Industrial clusters in Bavaria and Baden-Württemberg preserve legacy PBX investments while enabling incremental wideband migration through certified integrators.
South Korea
Tier-one carriers mandate EVS as the default voice codec for 5G standalone cores, collapsing performance gaps between cellular and fixed networks. The country's spectrum allocation frameworks prioritize VoLTE capacity expansion. Seoul metropolitan network operators anchor mobile infrastructure deployment with carrier-grade codec activation across 4G and 5G infrastructure.
France
Orange S.A. leverages its European fiber backbone to extend wideband voice services to business customers domestically and in neighboring markets. GDPR compliance requirements shape data sovereignty preferences for regulated industries. System integrators in the Paris region and Netherlands border zones displace direct vendor relationships through multi-carrier SIP trunk aggregation.
India
Telemedicine audio standards for remote diagnostic workflows in rural regions require wideband codec deployment for conversational clarity. TRAI regulations govern spectrum auction timing that defers VoLTE capacity investments when 5G spectrum costs consume capital budgets. Karnataka and Maharashtra technology corridors concentrate system integration capabilities for SMB WebRTC adoption.
High Definition HD Voice Market Competitive Landscape
Infrastructure vendors and telecom operators split the market between enterprise-grade platform provision and carrier network deployment. Consolidation pressures concentrate around codec licensing pools and interoperability certification requirements. Three archetypes dominate: European telecom incumbents with fiber backbone assets, North American enterprise communications platforms, and Nordic network infrastructure specialists. Competitive moves center on strategic partnerships for cross-border roaming agreements and portfolio diversification into cloud-native subscription models.
Among European telecom incumbents, Deutsche Telekom AG and Orange S.A. exemplify carrier-led wideband adoption strategies. Within the network infrastructure tier, Telefonaktiebolaget LM Ericsson and Nokia Networks occupy positions shaped by AMR-WB and EVS codec integration mandates. At the enterprise platform end, Cisco Systems Inc anchors vendor switching windows created by FCC copper retirement deadlines. These named entities represent distinct geographic and functional archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Telefonaktiebolaget LM Ericsson |
| AT&T Inc |
| Verizon Communication Inc |
| Cisco Systems Inc |
| Deutsche Telekom AG |
| Orange S.A. |
| Nokia Networks |
| Alcatel-Lucent Enterprise |
| Avaya Inc |
| Others |
Supply & Pricing Matrix
Helsinki-Tampere corridor codec engineering clusters concentrate acoustic optimization talent that feeds directly into vendor licensing power and downstream platform pricing. AMR-WB and EVS patent pool structures transmit this upstream concentration into per-unit cost stacking across mobile operator consumer plans and enterprise VoIP deployments.
Pricing Analysis
FCC copper retirement mandates dictate the pricing tier structure across US carrier infrastructure replacement cycles. Three-tier pricing structure across premium SLA-guaranteed enterprise, standard mid-market subscription, and economy best-effort consumer levels separates buyers by quality certification and support intensity. Price differentiation hinges on codec licensing tiers and geographic deployment complexity. Cost compression in economy consumer segments is intensifying because per-unit royalty burdens compress margins on low-ARPU plans. Enterprise healthcare and financial services verticals exhibit least price sensitivity due to compliance documentation requirements.
Supply Chain Analysis
Silicon wafer fabrication for DSP chipsets and acoustic membrane components draws from Taiwan, South Korea, and Germany. Codec algorithm development rests on Finnish and Swedish R&D center concentration. Supply chain vulnerability centers on single-source dependency for EVS patent pool administration and certification testing capacity. Distribution runs through carrier-direct procurement for mobile infrastructure and systems integrator aggregation for enterprise SIP trunking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HD voice market expansion represents a high-growth disruption as FCC IP-transition mandates and ETSI wideband interoperability standards simultaneously dismantle legacy PSTN economics and enforce codec upgrade cycles across carrier and enterprise networks.
For Market Incumbents: Harden codec roadmap unification around EVS as the converged mobile-fixed standard to preempt quality arbitrage between cellular and enterprise VoIP. Secure backward integration into session border controller manufacturing to capture wholesale switching traffic from rural ILEC decommissioning. Fortify certification testing capacity to compress six-to-nine-month interoperability backlogs that delay product launches.
For New Entrants and Emerging Players: Build out WebRTC-native conferencing platforms targeting SMB segments blocked by IT deployment friction in Karnataka and Maharashtra technology corridors. Penetrate telemedicine audio standards adoption in rural India where diagnostic clarity requirements exceed narrowband capability. Lead with browser-embedded deployment eliminating client installation overhead.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native subscription platform providers bundling endpoint management with usage pricing. Long-term viability over the coming decade favors vendors with carrier-grade certification relationships and cross-border roaming agreement access. Monitor TRAI spectrum auction timing in India and Anatel proceedings in Brazil as inflection signals for VoLTE capacity investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| EVS Codec Mandate Adoption | Orange S.A. and Deutsche Telekom enforce full-band audio as default 5G standard. |
| Cloud-Native Platform Migration | Subscription models displace premise hardware refresh cycles for mid-market adopters. |
| Session Border Controller Pre-Positioning | Wholesale voice providers capture switching traffic from FCC-mandated copper retirement. |
| WebRTC Browser Convergence | Embedded conferencing eliminates IT deployment friction for SMB telemedicine adoption. |
| Multi-Carrier SIP Trunk Aggregation | Systems integrators in France and Netherlands displace direct vendor relationships. |
Research Methodology
Operator-level perspectives from carrier network planners, enterprise IT procurement officers, codec engineering leads, and systems integration specialists anchored the qualitative base. Primary interviews triangulated against FCC docket filings, ETSI standardization records, 3GPP release documentation, and carrier infrastructure capex disclosures. Bottom-up deployment volume estimates across VoIP, unified communications, and mobile segments reconciled with top-down market sizing from patent pool royalty filings.
Scenario-bracketing framed optimistic, baseline, and conservative paths across the projection horizon. Segmentation dimensions modeled include product architecture, end-user vertical, codec technology, and deployment topology. CAGRs derived from subscriber migration curves, enterprise switching cycle timing, and infrastructure replacement elasticity. Forecast inputs incorporated VoLTE activation rates, copper retirement compliance deadlines, and spectrum auction outcome probabilities.
Stress conditions across codec royalty rate adjustments, 5G standalone core deployment delays, and Eastern European narrowband handset replacement inertia were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of carrier infrastructure procurement announcements and patent pool licensing term updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Ucaas in Banking Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Business Cloud Voip and UC Services Market
Unified Communications
Cloud UC Calling Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Unified Communication Market
Unified Communications
Unified Monitoring Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
Global Mobile Voip Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
United States SMS and MMS Market