
 Mobile Unified Communications and Collaboration (Ucandc) Solution Market | 2026-2036
Mobile Unified Communications and Collaboration (Ucandc) Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Unified Communications and Collaboration (Ucandc) Solution Market Foresight
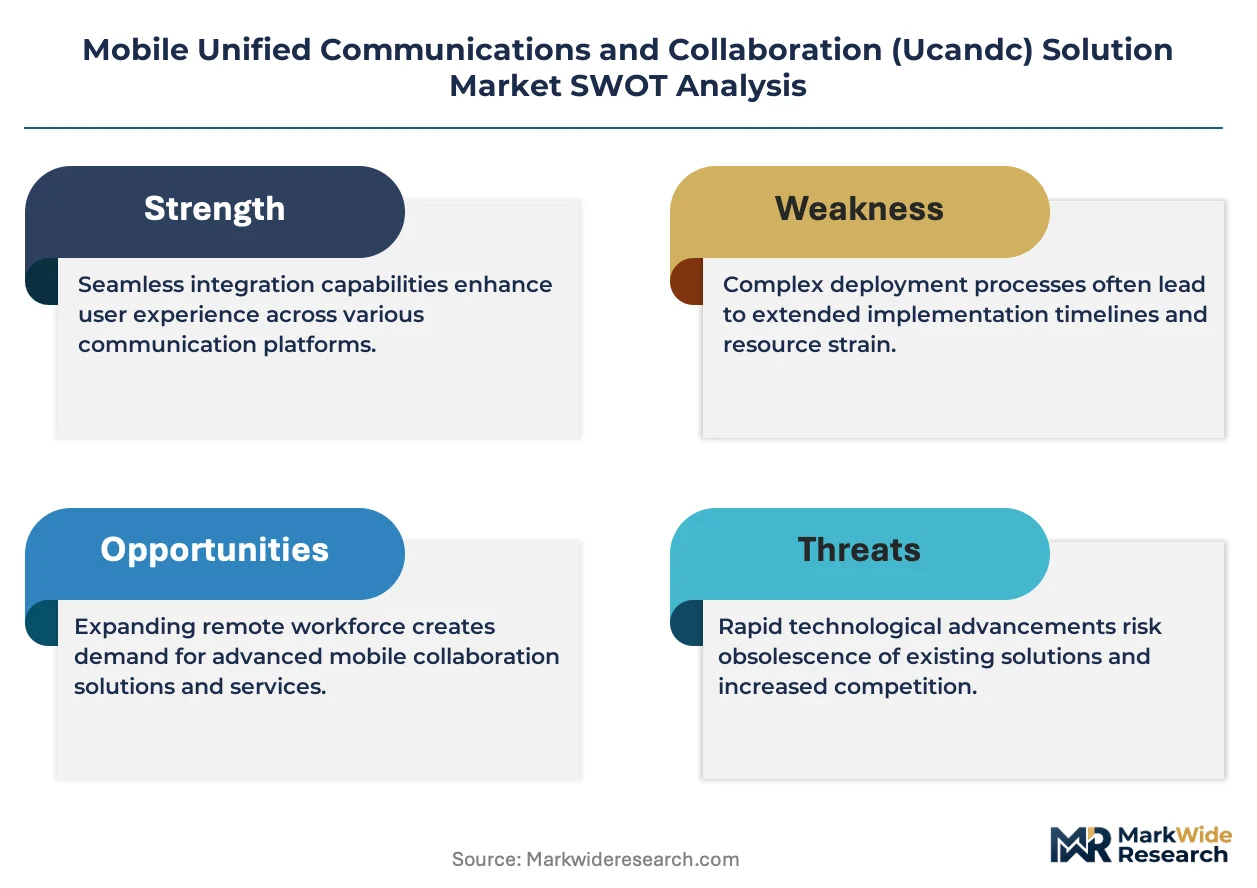
ISO/IEC 27001 certification is redrawing competitive boundaries in mobile UCC, as enterprise buyers increasingly require audited information security management systems for vendor shortlists. Microsoft leverages its Azure cloud backbone to anchor government and healthcare contracts with FedRAMP-authorized deployments. Cisco Systems competes through Webex's end-to-end encryption architecture and dedicated hardware endpoints that sustain premium positioning in regulated industries. Zoom Video Communications navigates enterprise scrutiny by extending its zero-trust security framework across mobile clients, differentiating on rapid compliance adaptation.
Mobile Unified Communications and Collaboration solutions integrate real-time messaging, voice, video conferencing, and file sharing into unified platforms accessible from smartphones and tablets, typically requiring AES-256 encryption, sub-150ms latency for voice, and API-based connectivity to enterprise directories. Their primary purpose is to extend workplace productivity tools beyond fixed endpoints, enabling seamless team coordination for distributed and field-based workforces. Cloud Solutions within the Product Type dimension now capture the dominant margin pool as recurring SaaS models displace perpetual licensing, while Hybrid deployment models are growing fastest among enterprises with legacy PBX investments seeking phased cloud migration. The End User segment shows Government buyers tightening vendor qualification requirements around supply chain provenance, whereas SME demand concentrates on bundled managed services with minimal IT overhead.
FCC net neutrality rulings and NIST cybersecurity frameworks shape US market access requirements for mobile UCC providers serving federal contractors, while GDPR and the EU AI Act impose data localization and algorithmic accountability standards on European deployments. HIPAA in the United States further constrains healthcare mobile UCC architectures through mandatory audit trails and business associate agreement structures. Stakeholders must monitor how fragmented national encryption and data sovereignty regulations will fragment product roadmaps and force region-specific engineering investments.
Market Dynamics
Federal telework mandates and defense sector secure mobility requirements in the United States are compressing enterprise procurement cycles, while GDPR and the EU AI Act force parallel certification tracks that fragment vendor engineering roadmaps.
Growth Catalysts
- HIPAA audit trail mandates:Healthcare providers in the United States are accelerating mobile UCC deployments to enable secure clinician collaboration at the point of care, creating sustained demand for FedRAMP-authorized platforms.
- Field-based workforce coordination:Distributed teams across construction, logistics, and emergency services require sub-150ms latency voice capabilities that legacy PBX systems cannot deliver.
- Germany:The country's national data protection regulator is enforcing GDPR data localization requirements that favor European-hosted cloud infrastructure, redirecting vendor capital toward Frankfurt and Amsterdam data centers.
Market Restraints
- Legacy PBX sunk costs:Enterprises with substantial on-premise telephony investments face high switching costs that delay full cloud migration and compress SaaS pricing power.
- Encryption standard fragmentation:National data sovereignty laws in China, Russia, and India mandate country-specific cryptographic modules that force redundant product development.
- Specialized security talent scarcity:Shortages of engineers with both mobile platform expertise and FedRAMP certification experience elongate implementation timelines.
Strategic Opportunities
- India's SME segment:Bundled managed services with minimal IT overhead are capturing price-sensitive buyers previously excluded from enterprise-grade mobile UCC.
- 5G network slicing convergence:Integration with quality-of-service guaranteed mobile networks is enabling guaranteed latency for mission-critical voice applications in public safety.
- EU AI Act algorithmic transparency:Early compliance with automated decision-making disclosure requirements is creating vendor differentiation in European public sector tenders.
Industry Challenges
- ISO/IEC 27001 certification timelines:The 12-18 month audit cycle for information security management systems delays vendor entry into regulated industry shortlists.
- Interoperability with legacy directory services:API-based connectivity to aging enterprise identity systems requires custom integration work that erodes SaaS margin structures.
- Supply chain provenance documentation:Government buyers are tightening vendor qualification requirements that demand extensive hardware component sourcing disclosure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Unified Communications and Collaboration (Ucandc) Solution Market |
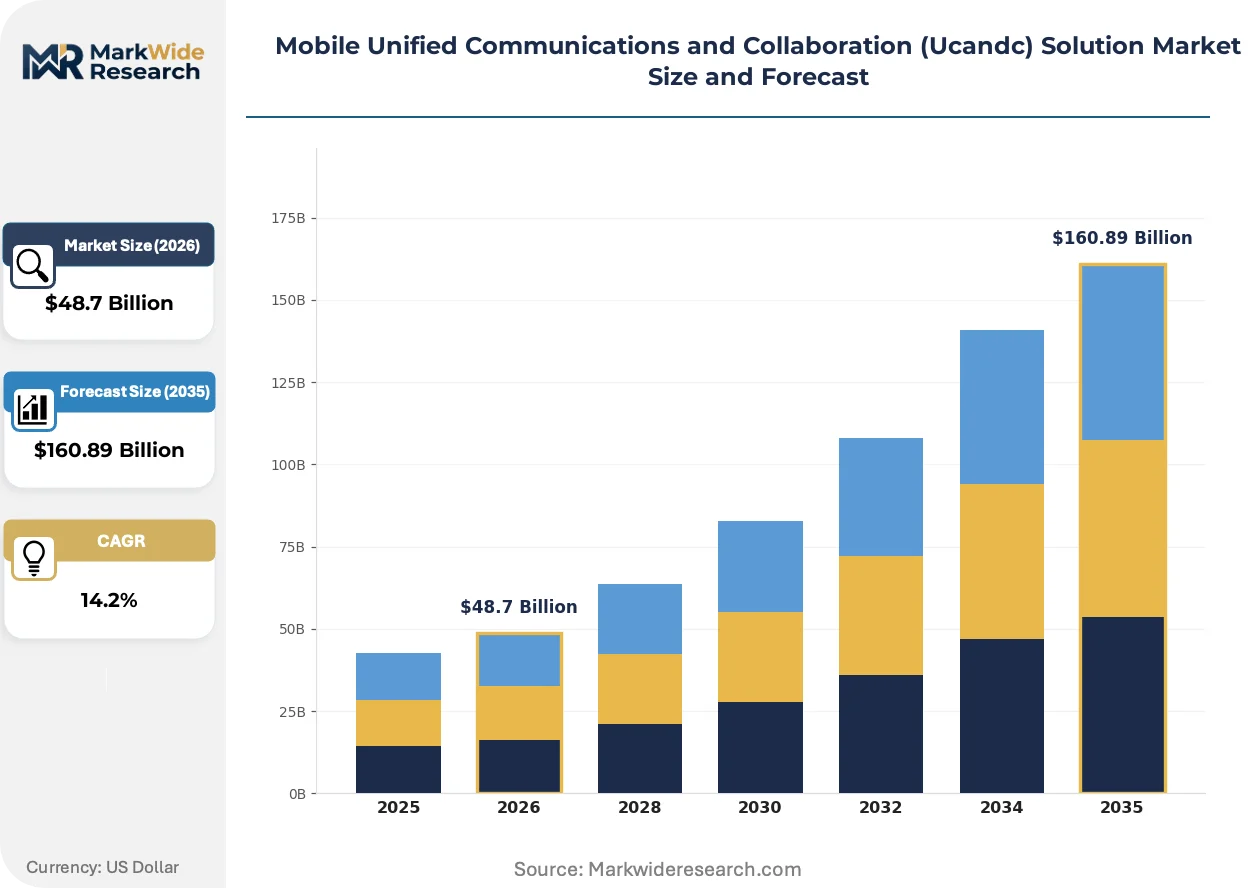
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Integrated Systems, Cloud Solutions Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Enterprises, SMEs, Government, Education Integration Level: API Integration, Standalone, Third-Party Apps, Custom Solutions |
| Companies Covered | Microsof Corporation, Cisco Systems, IBM Corporation, Zoom Video Communications, Avaya, Google, Verizon Communications, RingCentral, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Unified Communications and Collaboration (Ucandc) Solution Market Shifts & Advancements
Edge computing architectures and zero-trust security frameworks are converging to redefine mobile UCC deployment patterns, compressing the traditional perimeter-based security model.
Embedded secure elements within smartphone hardware security modules are miniaturizing the trust boundary for mobile UCC clients. Defense contractors and classified government users are adopting these chip-level protections fastest. This architecture is miniaturizing the attack surface that vendors must certify, reducing FedRAMP authorization scope and accelerating deployment timelines.
The EU AI Act's risk classification system for biometric identification and emotion recognition is forcing algorithmic transparency disclosures in European mobile UCC deployments. Vendors must now document automated decision-making in features like meeting transcription and sentiment analysis. Healthcare and public sector buyers in France and Germany are prioritizing suppliers with pre-submitted conformity assessments.
Enterprise buying committees are compressing vendor evaluation cycles from 18 months to 6-9 months through pre-certified procurement frameworks. State and local governments in the United States are adopting cooperative purchasing agreements that aggregate demand and lock in pricing. This pattern is most visible in California and Texas, where multi-agency contracts favor incumbent cloud providers with existing FedRAMP authorizations.
Mobile Unified Communications and Collaboration (Ucandc) Solution Market Segmentation
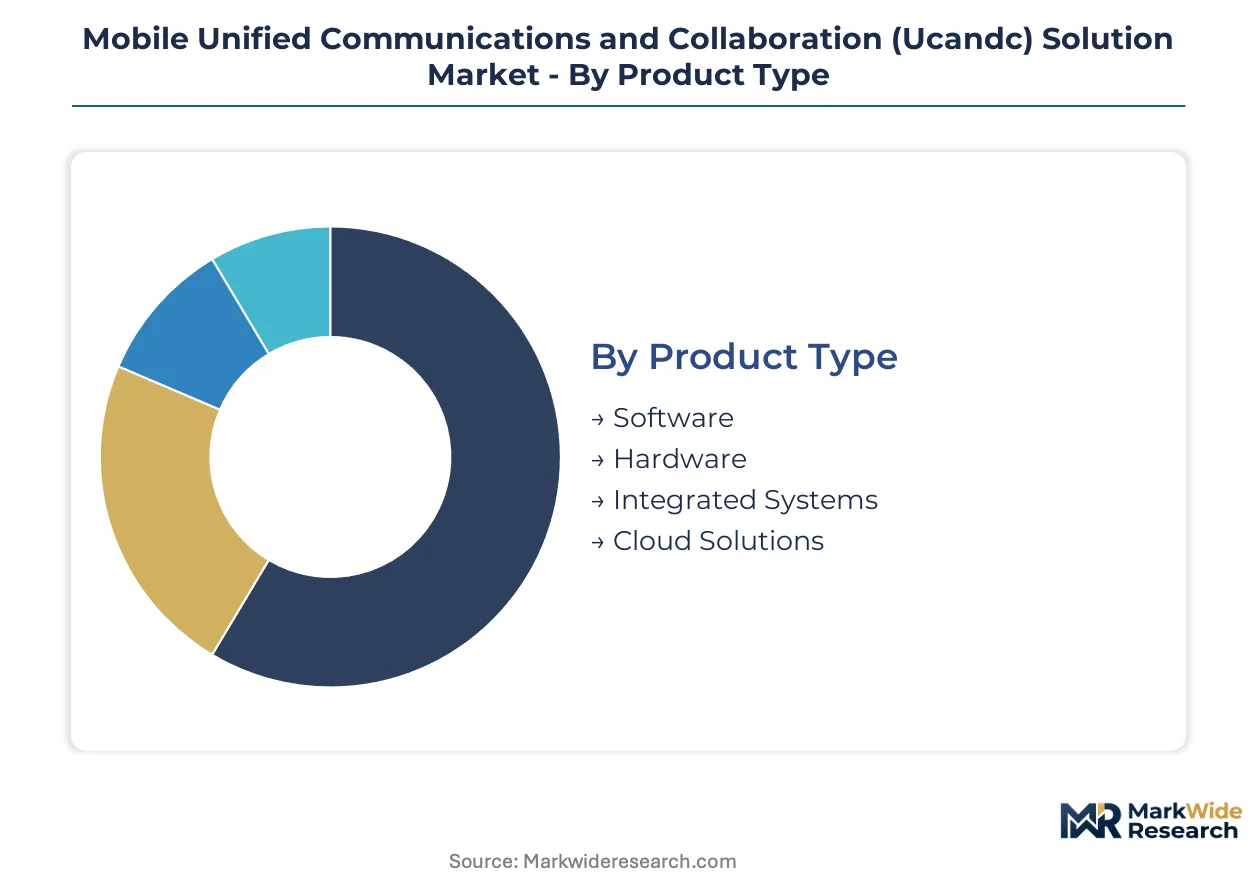
Mobile UCC procurement patterns diverge sharply across product architectures and deployment models, with regulatory compliance requirements acting as the primary filter for vendor selection. Buyers in regulated industries prioritize certified security frameworks over feature breadth, creating tiered demand pools that reshape competitive positioning.
Product Type:
FedRAMP authorization and ISO/IEC 27001 certification availability determine which product types penetrate government and healthcare shortlists.
- Software:Modular applications delivering voice, video, and messaging through downloadable clients with AES-256 encryption. Demand concentrates among SMEs seeking minimal capital expenditure with rapid deployment cycles.
- Cloud Solutions:Recurring SaaS platforms with API-based directory connectivity and sub-150ms latency guarantees. Healthcare providers in the United States favor these for HIPAA-compliant clinician collaboration at the point of care.
- Hardware:Dedicated endpoints with embedded secure elements and hardware security modules. Defense contractors prioritize these for classified communications requiring chip-level trust boundaries.
- Integrated Systems:Bundled software-hardware combinations with unified management consoles. Enterprises with legacy PBX investments use these for phased cloud migration paths.
Established volume favors Software; emerging adoption favors Cloud Solutions.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premise investments from operational expenditure models favored by budget-constrained buyers.
- Cloud-Based:Fully hosted infrastructure with vendor-managed security updates and automatic scaling. United States federal agencies accelerate procurement of FedRAMP-authorized cloud deployments under telework mandates.
- Hybrid:Split architectures preserving on-premise PBX core while extending cloud voice services to mobile endpoints. European enterprises with GDPR data localization requirements favor these for phased transitions.
- On-Premises:Self-managed infrastructure with direct control over encryption keys and audit trails. Financial services firms in Germany maintain these for BaFin compliance with transaction recording requirements.
- Managed Services:Outsourced operations with bundled support, monitoring, and compliance management. India's SME segment captures price-sensitive buyers through minimal IT overhead offerings.
Hybrid deployments are climbing the fastest as enterprises balance sunk legacy costs against cloud agility demands.
End User:
Customer type dictates security certification depth, with government buyers imposing the most stringent supply chain provenance requirements.
- Government:Federal, state, and local agencies requiring FedRAMP authorization, NIST cybersecurity framework alignment, and hardware component sourcing disclosure. Defense sector secure mobility requirements compress procurement cycles for authorized vendors.
- Enterprises:Large organizations with distributed workforces and field-based coordination needs. Construction and logistics sectors demand sub-150ms latency voice for mission-critical dispatch operations.
- SMEs:Small and medium enterprises prioritizing bundled functionality with limited internal IT resources. Managed service bundles capture this segment through predictable operational expenditure models.
- Education:K-12 and higher education institutions requiring FERPA-compliant student data protection alongside parent-teacher communication tools. State cooperative purchasing agreements aggregate demand in California and Texas.
Government buyers enforce the steepest compliance barriers; SME demand expands most quickly through service bundling.
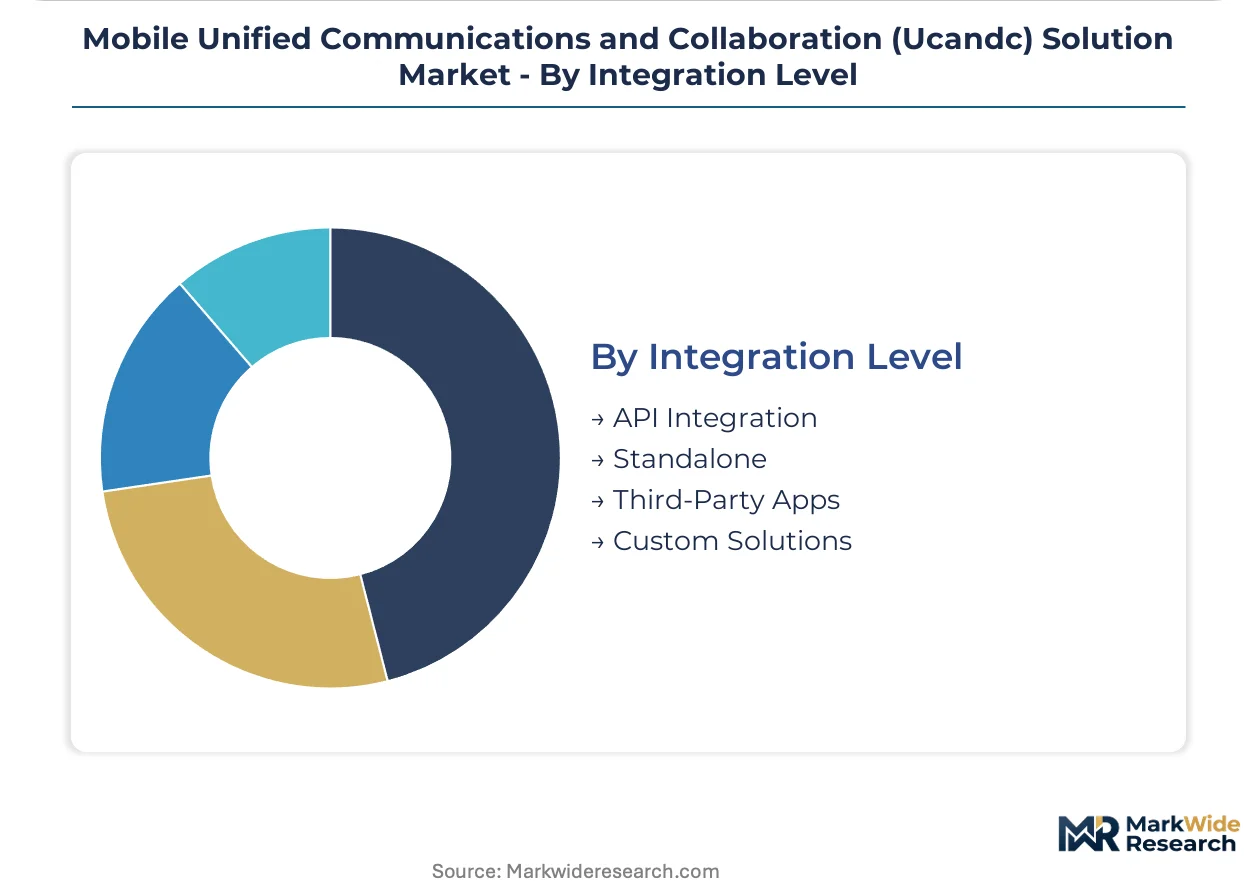
Integration Level:
Application maturity determines whether buyers accept vendor-native ecosystems or demand open connectivity to existing enterprise infrastructure.
- API Integration:Programmable interfaces connecting mobile UCC to ERP, CRM, and identity management systems. Enterprises with substantial Microsoft Azure or Google Workspace investments prioritize these for unified directory services.
- Third-Party Apps:Pre-built connectors to Salesforce, ServiceNow, and Slack enabling workflow embedding. Professional services firms use these to embed communication into client matter management.
- Standalone:Self-contained platforms without external system dependencies. Smaller professional practices favor these for simplified administration and reduced attack surface.
- Custom Solutions:Bespoke development for specialized regulatory or operational requirements. Healthcare systems with unique EHR integration needs commission these for clinician workflow alignment.
API Integration commands premium pricing; Third-Party Apps gain share fastest through ecosystem network effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal telework mandates and defense sector secure mobility requirements in the United States compress enterprise procurement cycles, while GDPR and the EU AI Act force parallel certification tracks across European deployments. Healthcare providers in multiple jurisdictions accelerate mobile UCC adoption to enable secure clinician collaboration at the point of care.
United States
FCC net neutrality rulings and NIST cybersecurity frameworks shape market access requirements for mobile UCC providers serving federal contractors. HIPAA audit trail mandates constrain healthcare architectures through mandatory business associate agreement structures. California and Texas state cooperative purchasing agreements aggregate multi-agency demand and lock in pricing for incumbent cloud providers.
Germany
BaFin compliance requirements for transaction recording drive financial services firms toward on-premise deployments with direct encryption key control. The national data protection regulator enforces GDPR data localization requirements that favor European-hosted cloud infrastructure. Frankfurt and Amsterdam data centers capture redirected vendor capital from enterprises seeking compliant hosting.
India
TRAI regulations and the PLI scheme for electronics manufacturing create policy tailwinds for domestic mobile UCC adoption. Bundled managed services with minimal IT overhead capture price-sensitive SME buyers previously excluded from enterprise-grade solutions. Maharashtra and Karnataka technology corridors concentrate implementation demand from IT services exporters.
United Kingdom
Post-Brexit data adequacy arrangements with the EU reshape cloud hosting decisions for enterprises serving continental customers. The Information Commissioner's Office enforces GDPR-aligned standards through domestic UK-GDPR frameworks. London financial services clusters sustain demand for low-latency voice capabilities that legacy PBX systems cannot deliver.
Japan
METI industrial digitization programs accelerate mobile UCC deployment among manufacturing exporters coordinating distributed supply chains. JIS standards for information security management systems align with ISO/IEC 27001 certification requirements. Tokyo and Osaka metropolitan areas concentrate enterprise demand from conglomerates with field-based workforce coordination needs.
Mobile Unified Communications and Collaboration (Ucandc) Solution Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and deployment model breadth. The vendor base clusters around three strategic tiers: hyperscale cloud providers with FedRAMP authorization, telecommunications carriers with network-integrated service bundles, and specialized software vendors with vertical-specific compliance expertise. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through localized data center investments.
Within the hyperscale tier, Microsoft Corporation and Cisco Systems occupy positions defined by cloud backbone scale and hardware-software integration depth. Zoom Video Communications exemplifies rapid compliance adaptation as a competitive anchor. Huawei Technologies represents network equipment specialists pursuing carrier-integrated service models. Each archetype faces distinct certification timelines and regional market access constraints.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Cisco Systems |
| IBM Corporation |
| Zoom Video Communications |
| Avaya |
| Verizon Communications |
| RingCentral |
| Huawei Technologies |
| Others |
Supply & Pricing Matrix
Hyperscale cloud capacity utilization above 75% in Microsoft Azure and Amazon Web Services data centers compresses unit economics for SaaS delivery, concentrating pricing power among FedRAMP-authorized vendors while raising cost floors for uncertified competitors seeking ISO/IEC 27001 compliance. This scale dynamic simultaneously anchors supply chain decisions around Frankfurt, Amsterdam, and US East Coast hosting regions where certification density justifies capital allocation.
Pricing Analysis
Certification level (FedRAMP-authorized versus ISO/IEC 27001-only) creates the primary spread between premium and standard tiers, with government buyers absorbing 40-60% price premiums for audited security management systems. Cloud Solutions dominate through subscription SaaS models displacing perpetual licensing, while Healthcare providers show lowest price sensitivity due to HIPAA audit trail mandates. Cost compression in SME segments intensifies as India's bundled managed services capture price-sensitive buyers with minimal IT overhead, eroding margin structures for undifferentiated software vendors.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Rotterdam and Hamburg elevate inbound logistics costs for hardware security modules and embedded secure elements sourced from Taiwan and South Korea. Semiconductor fabrication for smartphone trust anchors concentrates in Taiwan, South Korea, and Japan, with single-source vulnerability in advanced node production. Distribution runs through systems integrators and carrier-integrated service bundles, with defense contractors bypassing standard channels for direct procurement of classified-grade hardware endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile UCC sits in early-cycle expansion as federal telework mandates and 5G network slicing convergence accelerate enterprise displacement of legacy PBX infrastructure. Penetration among field-based workforces in construction, logistics, and emergency services remains below 35%, creating sustained adoption tailwinds.
For Market Incumbents: Compound certification depth through accelerated FedRAMP authorization timelines and ISO/IEC 27001 audit pre-positioning to lock out emerging competitors. Threats from carrier-integrated specialists like Huawei Technologies demand defensive capacity expansion in European data centers to satisfy GDPR localization requirements. Vertical integration into hardware security module sourcing secures supply continuity against Taiwan Strait disruption risks. For New Entrants and Emerging Players: FedRAMP Fast Track authorization for cloud service providers offers the fastest path to government shortlist eligibility, bypassing 12-18 month standard timelines. India's SME segment presents the most penetrable white space, where bundled managed services with minimal IT overhead capture price-sensitive buyers excluded from enterprise-grade platforms. Go-to-market positioning should emphasize cooperative purchasing agreement eligibility in California and Texas state frameworks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Cloud Solutions providers with HIPAA-compliant healthcare deployments, offering superior cash flow predictability over hardware-centric vendors. Acquisition targets should screen for pre-submitted EU AI Act conformity assessments and existing Frankfurt or Amsterdam hosting infrastructure. The signal to watch is defense sector procurement cycle compression, which accelerates valuation multiples for FedRAMP-authorized vendors with chip-level trust boundary capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-based connectivity to Microsoft Azure and Google Workspace directories captures enterprise buyers with existing cloud investments. |
| Geographic Expansion | Frankfurt and Amsterdam data center deployments satisfy GDPR data localization requirements for European healthcare tenders. |
| Strategic Partnership | Systems integrator alliances accelerate FedRAMP authorization timelines and compress implementation cycles for government buyers. |
| Product Launch | Zero-trust security framework extensions across mobile clients differentiate vendors under enterprise compliance scrutiny. |
| Acquisition of Specialist Firm | Vertical compliance expertise in HIPAA audit trail architectures deepens penetration among US healthcare providers. |
Research Methodology
The analysis maps Cloud Solutions, Software, Hardware, and Integrated Systems product architectures, each validated through chief technology officers, IT procurement officers, platform engineers, and channel partners across primary interviews. Secondary validation draws from SEC filings, hyperscaler capex disclosures, FedRAMP authorization databases, and GPO contract repositories. Bottom-up deployment model sizing triangulates against top-down enterprise mobility spend estimates.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, deployment model, end user category, and integration complexity level. CAGR derivation incorporates 5G network slicing adoption curves, federal telework mandate compliance deadlines, and EU AI Act implementation timelines as industry-specific forecast inputs.
Underlying assumptions cover sustained federal telework policy continuity and stable GDPR enforcement intensity, with deviation risk concentrated in encryption standard fragmentation across China, Russia, and India. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
United States SMS and MMS Market
Unified Communications
Ucaas in Banking Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Unified Communication Market
Unified Communications
High Definition HD Voice Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Unified Monitoring Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Cloud UC Calling Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Business Cloud Voip and UC Services Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market