
 Global IP Telephony and Ucaas Market | 2026-2036
Global IP Telephony and Ucaas Market Size, Share, and Industry Trends Forecast 2026-2036
Global IP Telephony and Ucaas Market Foresight
Subscription-based software-defined voice routing is shifting how enterprises procure communication infrastructure. Cisco Systems leverages its installed base of networking hardware to anchor hybrid deployment contracts across Fortune 500 accounts. Microsoft competes through deep integration of Teams telephony with Azure cloud services, while Zoom differentiates by simplifying video-first UCaaS provisioning for mid-market buyers.
IP telephony and UCaaS encompass packet-switched voice transmission, session initiation protocol signaling, and cloud-hosted unified communication platforms delivering voice, video, messaging, and contact center functions over internet protocol networks with quality-of-service prioritization. Cloud-based deployment leads segment value as organizations retire legacy PBX systems, while contact center solutions within the solution/offering dimension capture expanding margin pools from AI-assisted agent workflows. Team communication applications sustain faster growth than legacy customer support use cases as distributed workforce norms institutionalize persistent chat and channel-based collaboration.
FCC net neutrality rulings and HIPAA encryption standards in the US, alongside GDPR and the EU AI Act in Europe, collectively shape product architecture by mandating end-to-end encryption, geographic data localization, and algorithmic transparency in AI-powered call analytics. India's TRAI VoIP guidelines and BIS cloud security standards further constrain how multinational vendors design multi-tenant infrastructure for regulated industries. Stakeholders must weigh regulatory fragmentation against platform consolidation bets when selecting long-term UCaaS partners.
Market Dynamics
Subscription-based software-defined voice routing is compressing enterprise procurement cycles and collapsing the distinction between on-premises PBX maintenance and cloud-native consumption. Healthcare providers now drive outsized contract velocity as telemedicine protocols harden into permanent clinical workflows.
Growth Catalysts
- India's cloud-first mandates:Government directives accelerating SME digitization are pulling hosted voice adoption forward in the world's second-largest telecommunications market. TRAI VoIP guidelines provide regulatory scaffolding for multi-tenant infrastructure deployment.
- EU AI Act compliance architecture:Algorithmic transparency requirements for AI-powered call analytics are creating upgrade cycles among European enterprises. Vendors embedding explainable AI into contact center workflows capture premium positioning.
- Session border controller virtualization:Software-based SBC deployment is collapsing hardware refresh cycles and enabling elastic capacity scaling. Mid-market buyers bypass capital-intensive premises equipment through consumption-based models.
Market Restraints
- GDPR data residency friction:Geographic localization mandates fragment multi-tenant architecture economics. Vendors must replicate infrastructure across sovereign zones, elevating operational complexity.
- Legacy PSTN interconnection costs:TDM-to-IP gateway maintenance and carrier settlement structures impose residual cost burdens. Hybrid deployments retain expensive circuit-switched tail dependencies.
- Skilled SIP engineering scarcity:Packet-level troubleshooting and QoS optimization expertise concentrates among veteran practitioners. Workforce gaps constrain implementation velocity for complex multi-site rollouts.
Strategic Opportunities
- AI-assisted agent augmentation:Real-time transcription and sentiment analysis convergence is opening margin pools beyond commoditized voice transport. Contact center buyers prioritize workflow intelligence over minutes-based pricing.
- Indonesia's SME digitization gap:Underpenetrated mid-market segments present first-mover advantages for simplified UCaaS provisioning. Local data center partnerships satisfy emerging sovereignty expectations.
- HIPAA encryption tailwinds:US healthcare providers face intensifying audit scrutiny for patient communication channels. End-to-end encrypted mobile softphone deployments are displacing pager and fax remnants.
Industry Challenges
- Multi-vendor interoperability testing:SIP trunking compatibility verification across heterogeneous endpoint ecosystems consumes pre-deployment engineering resources. Certification delays compress implementation windows.
- E911 location accuracy mandates:FCC requirements for precise caller geolocation in mobile and remote worker scenarios impose architectural retrofit burdens. Dynamic location routing complexity escalates with distributed workforce scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IP Telephony and Ucaas Market |
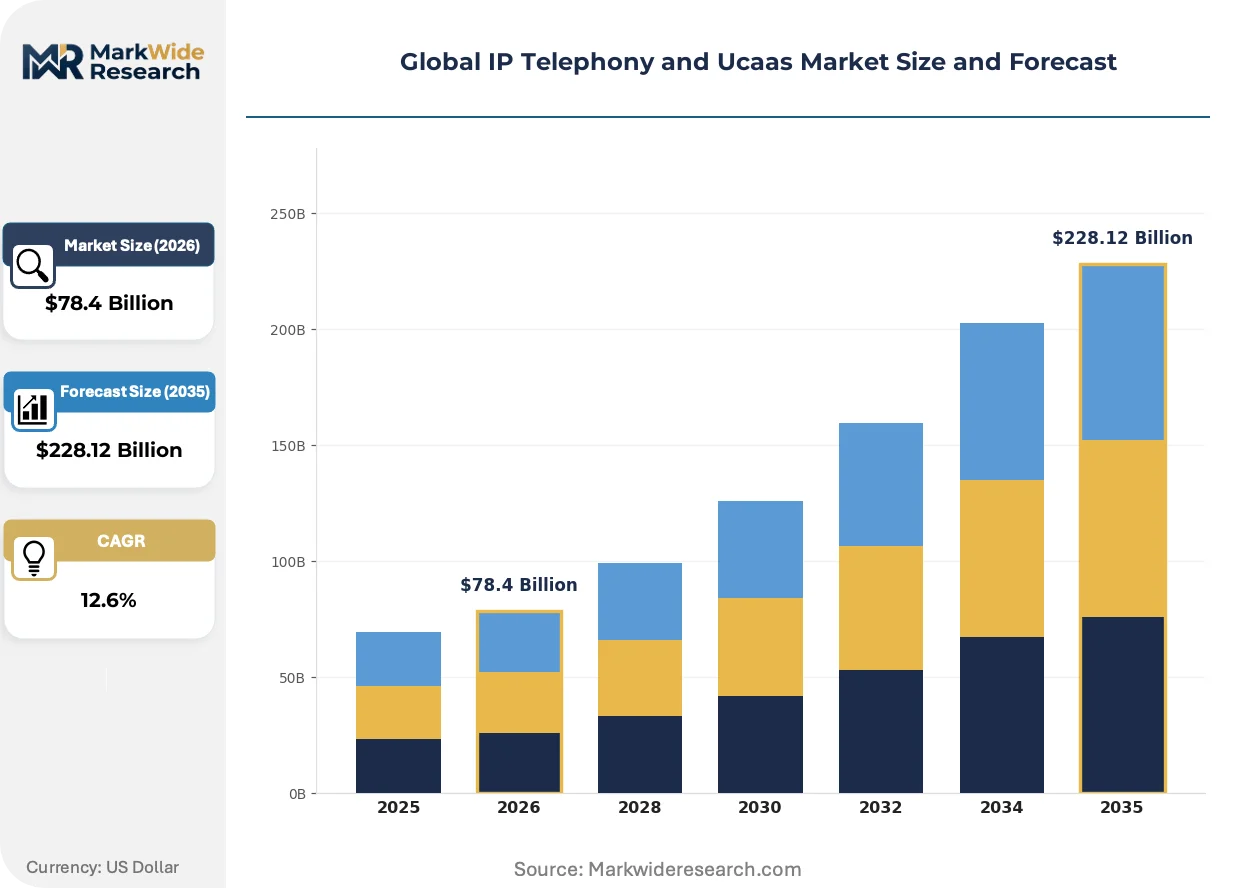
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $228.12 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution/Offering: VoIP Phones, Video Conferencing, Contact Center, Collaboration Tools Application: Customer Support, Team Communication, Remote Work, Sales Enablement, Training End User Industry: Technology Firms, Financial Services, Education Providers, Government Agencies |
| Companies Covered | RingCentral, 8x8, Cisco Systems, Vonage, Microsoft, Zoom, Verizon Communications, Orange Business Solutions, Sangoma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IP Telephony and Ucaas Market Shifts & Advancements
Artificial intelligence inference at the network edge is compressing latency for real-time communication augmentation. Regulatory fragmentation across data sovereignty zones is forcing modular platform architecture. Buyer expectations now fuse video-first design patterns with legacy voice reliability standards.
WebRTC browser-native media engines are consolidating real-time communication stack complexity into standardized JavaScript APIs. Healthcare providers and financial services firms adopt WebRTC-embedded customer engagement portals to bypass plugin dependencies and mobile app friction. This consolidation is collapsing the distinction between unified communications and embedded communications-platform-as-a-service.
GDPR and the EU AI Act are mandating algorithmic audit trails for emotion recognition and biometric inference in call analytics. Vendors must engineer transparency dashboards and consent management workflows into AI-assisted agent tools. European contact center operators now prioritize explainability over raw predictive accuracy in vendor selection.
Channel-based team collaboration is displacing email-centric workflows as the primary internal communication modality. Technology and professional services verticals lead this behavioral pivot, with persistent chat threading replacing meeting-heavy coordination. Germany's Mittelstand manufacturing sector exhibits fastest adoption velocity as engineering teams coordinate across distributed production sites.
Global IP Telephony and Ucaas Market Segmentation
Segmentation in IP telephony and UCaaS reveals divergent capital requirements and margin profiles across deployment architectures, solution types, and end-use contexts. Buyers prioritize cloud elasticity, AI-augmented workflows, or sovereign control depending on regulatory exposure and workforce distribution.
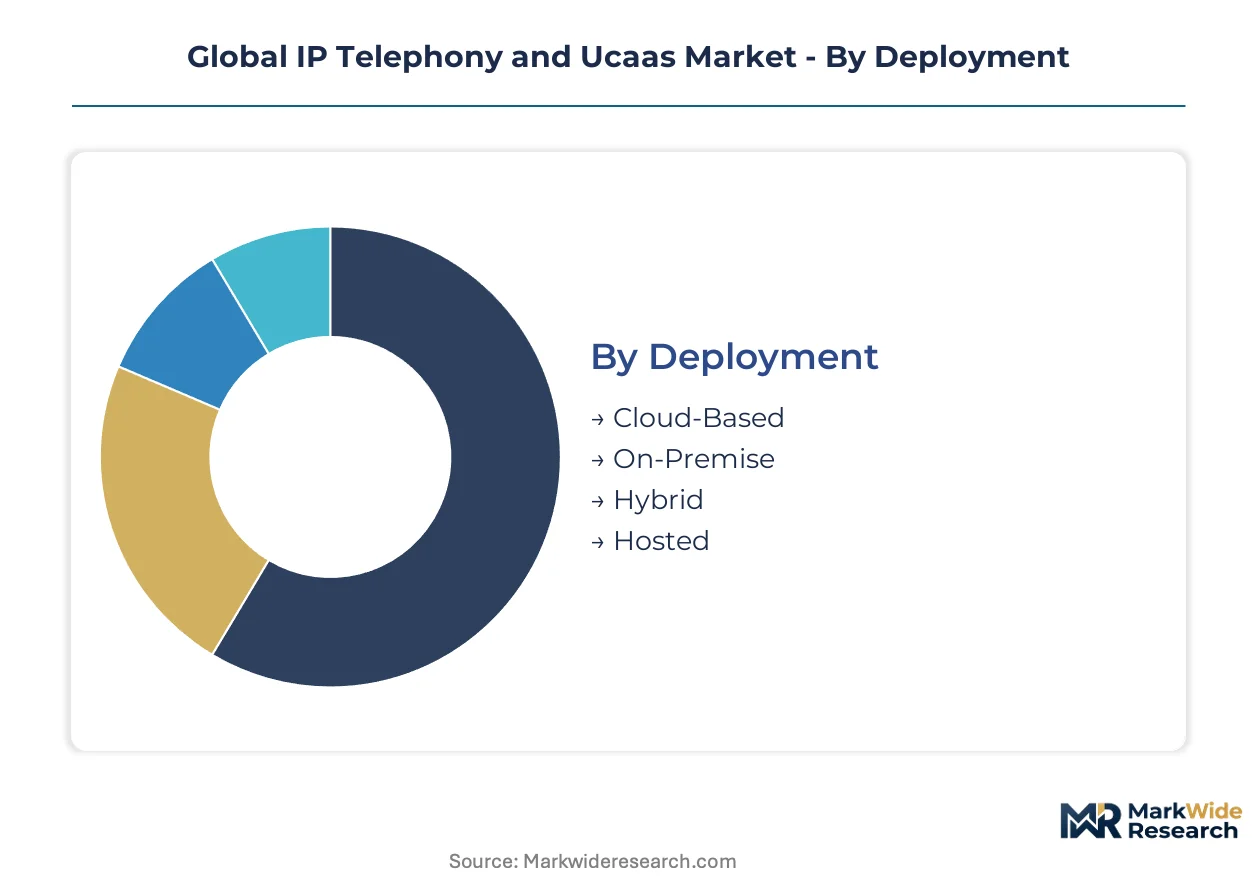
Deployment:
Capital intensity varies sharply across deployment models, with on-premise infrastructure demanding the heaviest upfront hardware investment while cloud-native alternatives shift expenditure to recurring operational budgets.
- Cloud-Based:Multi-tenant infrastructure delivers elastic capacity scaling through software-defined provisioning. Healthcare providers in the United States and government agencies in India drive contract velocity as HIPAA encryption requirements and cloud-first procurement mandates accelerate legacy PBX displacement.
- On-Premise:Dedicated hardware deployments retain appeal for organizations with stringent data sovereignty requirements or specialized session border controller configurations. Financial services firms in Germany and defense contractors across NATO member states maintain capital-intensive premises equipment to satisfy air-gapped security protocols.
- Hybrid:Mixed architectures preserve existing PSTN gateway investments while selectively cloud-enabling specific user cohorts or geographic sites.
- Hosted:Single-tenant managed services deliver operational outsourcing without full cloud-native elasticity, serving mid-market buyers with limited internal SIP engineering capacity.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as enterprises stage multi-year migration roadmaps.
Solution/Offering:
Margin concentration follows AI integration depth, with contact center and collaboration tools commanding premium pricing against commoditized voice transport endpoints.
- Contact Center:AI-assisted agent workflows embed real-time transcription, sentiment analysis, and predictive routing into customer engagement platforms. European enterprises prioritize explainable AI dashboards to satisfy EU AI Act algorithmic transparency mandates, while US healthcare providers demand HIPAA-compliant encryption for patient interaction channels.
- Collaboration Tools:Persistent chat threading and channel-based coordination replace email-centric workflows in distributed technology firms. Germany's Mittelstand manufacturing sector exhibits fastest adoption velocity as engineering teams synchronize across dispersed production facilities.
- VoIP Phones:Desktop and mobile softphone endpoints deliver packet-switched voice transmission with quality-of-service prioritization.
- Video Conferencing:WebRTC-native browser engines collapse plugin dependencies for customer-facing engagement portals.
Revenue pools concentrate in Contact Center solutions. Collaboration Tools are gaining share fastest as hybrid workforce norms institutionalize asynchronous coordination.
Application:
Procurement urgency correlates with workforce distribution, with remote work and team communication use cases accelerating faster than legacy customer support implementations.
- Remote Work:Distributed workforce enablement demands mobile softphone deployments, dynamic E911 location routing, and zero-trust network access integration. FCC geolocation accuracy mandates in the United States impose architectural retrofit burdens as employers scale remote agent populations across state boundaries.
- Team Communication:Persistent chat and channel-based coordination displace meeting-heavy workflows in technology and professional services verticals. Engineering teams at India's software exporters and Japan's precision manufacturers adopt these modalities to synchronize across time zones.
- Customer Support:Voice-centric service desk operations retain volume leadership but face margin compression from commoditized transport pricing.
- Sales Enablement:CRM-integrated communication stacks prioritize call recording compliance and conversation intelligence for revenue operations.
- Training:Scalable webinar and virtual classroom provisioning serves corporate learning management system integrations.
Deployment volume clusters in Customer Support applications. Remote Work configurations are climbing the fastest as distributed workforce policies harden into permanent organizational structures.
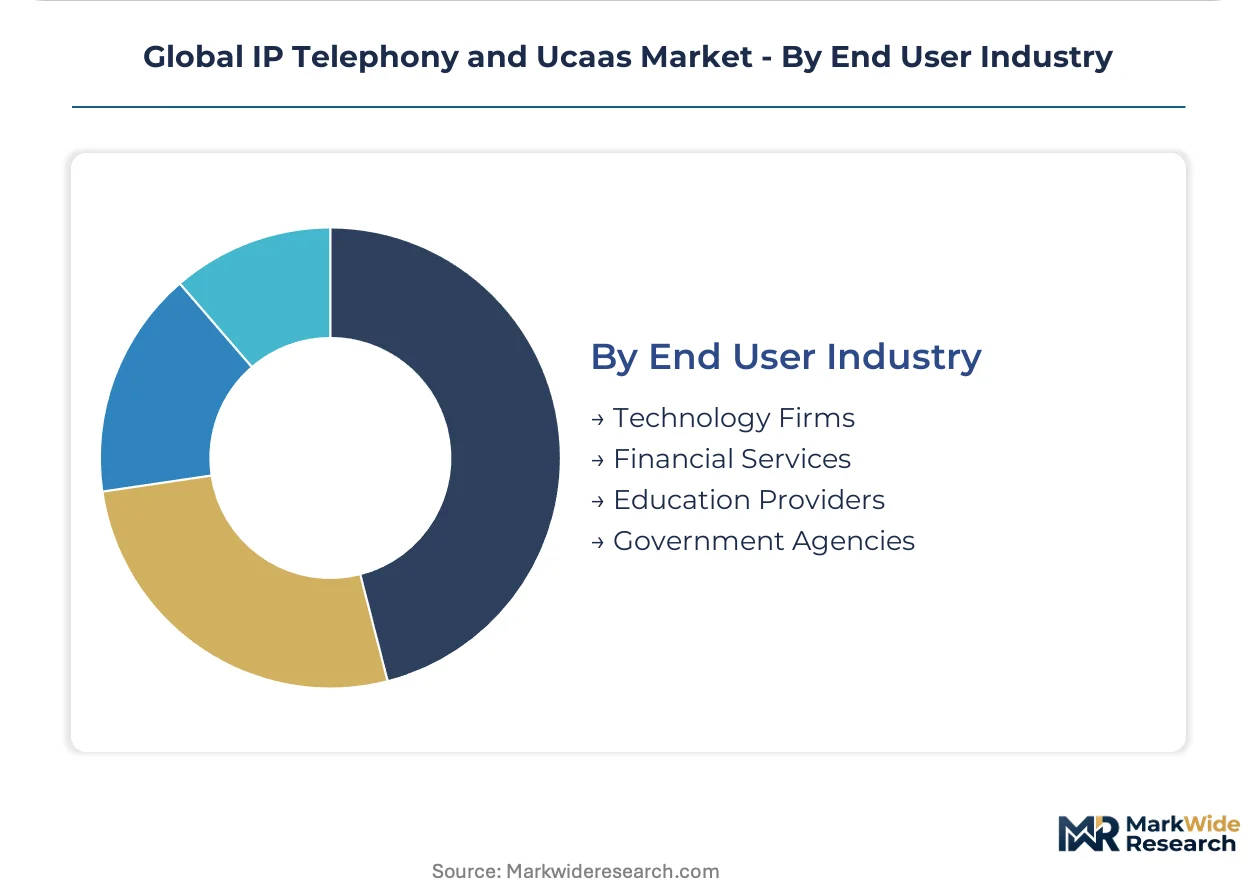
End User Industry:
Regulatory density and digital maturity create divergent buyer profiles across vertical segments, with financial services and government agencies imposing the most stringent compliance architectures.
- Financial Services:Banks, insurers, and asset managers demand end-to-end encryption, call recording retention, and MiFID II-compliant communication surveillance. GDPR data residency requirements in Europe and SEC recordkeeping rules in the United States fragment multi-tenant infrastructure designs, elevating operational complexity for vendors serving cross-border institutions.
- Government Agencies:Sovereign cloud mandates and classified information handling protocols favor on-premise or nationally hosted deployments. India's cloud-first directives and TRAI VoIP guidelines accelerate procurement reform, while NATO defense establishments maintain air-gapped session border controller configurations.
- Technology Firms:Early adopters of WebRTC-native stacks and AI-augmented collaboration tools drive feature velocity roadmaps.
- Education Providers:Scalable virtual classroom and administrative communication provisioning serves K-12 and higher education digitization initiatives.
Contract value concentrates in Financial Services deployments. Technology Firms are expanding most quickly as product-led growth companies embed communications-platform-as-a-service into customer-facing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's SME digitization accelerates faster than Germany's Mittelstand manufacturing adoption, yet both markets now drive substantial contract velocity for cloud-hosted voice infrastructure. Regulatory fragmentation across data sovereignty zones forces vendors to engineer modular platform architectures. Urban technology corridors concentrate procurement authority while government cloud mandates reshape national deployment patterns.
United States
Healthcare providers and financial services firms dominate enterprise procurement as HIPAA encryption requirements and SEC recordkeeping rules harden compliance architectures. FCC net neutrality rulings and E911 geolocation accuracy mandates impose architectural retrofit burdens for distributed workforce scale. Silicon Valley technology clusters and New York financial services corridors anchor contract value concentration.
Germany
Mittelstand manufacturing engineering teams drive fastest adoption velocity for channel-based collaboration tools across dispersed production facilities. GDPR data residency requirements fragment multi-tenant infrastructure economics and elevate operational complexity for cross-border institutions. Bavaria and Baden-Württemberg industrial corridors concentrate sovereign cloud procurement authority.
India
Government cloud-first directives and SME digitization programs accelerate hosted voice adoption in the world's second-largest telecommunications market. TRAI VoIP guidelines and BIS cloud security standards constrain multinational vendor infrastructure design for regulated industries. Bangalore and Hyderabad technology corridors anchor software exporter demand for persistent chat coordination across time zones.
United Kingdom
Financial services surveillance requirements and MiFID II-compliant communication retention shape buyer specifications for encrypted call recording platforms. Post-Brexit data localization expectations intersect with GDPR continuity obligations to complicate multi-tenant architecture decisions. London's fintech corridor and Edinburgh asset management clusters concentrate premium-tier contract negotiations.
Japan
Precision manufacturing engineering teams adopt channel-based collaboration modalities to synchronize production coordination across distributed facilities. METI industrial digitization frameworks and JIS standards shape procurement specifications for hybrid deployment architectures. Tokyo-Osaka industrial corridors anchor enterprise voice modernization cycles.
Global IP Telephony and Ucaas Market Competitive Landscape
Top-tier vendors anchor hybrid-cloud infrastructure contracts across Fortune 500 accounts, while mid-market specialists compete through simplified provisioning models. The vendor base stratifies across networking hardware incumbents, cloud-native platform operators, and carrier-affiliated service providers. Strategic archetypes include installed-base leverage players, ecosystem integration specialists, and vertical-focused compliance enablers. Dominant competitive moves center on AI-assisted workflow embedding and geographic data center expansion to satisfy sovereignty requirements.
Among cloud-native platform operators, RingCentral and 8x8 occupy positions exemplifying consumption-based provisioning models for mid-market buyers lacking internal SIP engineering capacity. Cisco Systems represents the installed-base leverage archetype through hybrid deployment anchoring. These three companies illustrate the competitive tension between hardware-rooted migration pathways and software-native consumption economics.
| Leading Market Players |
|---|
| RingCentral |
| 8x8 |
| Cisco Systems |
| Vonage |
| Microsoft |
| Zoom |
| Verizon Communications |
| Orange Business Solutions |
| Sangoma |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up UCaaS specialists anchor pricing discipline through recurring revenue consolidation, while sovereign-backed cloud infrastructure investments in India and the EU reshape both supply deployment patterns and subscription tier structures across enterprise buyer segments.
Pricing Analysis
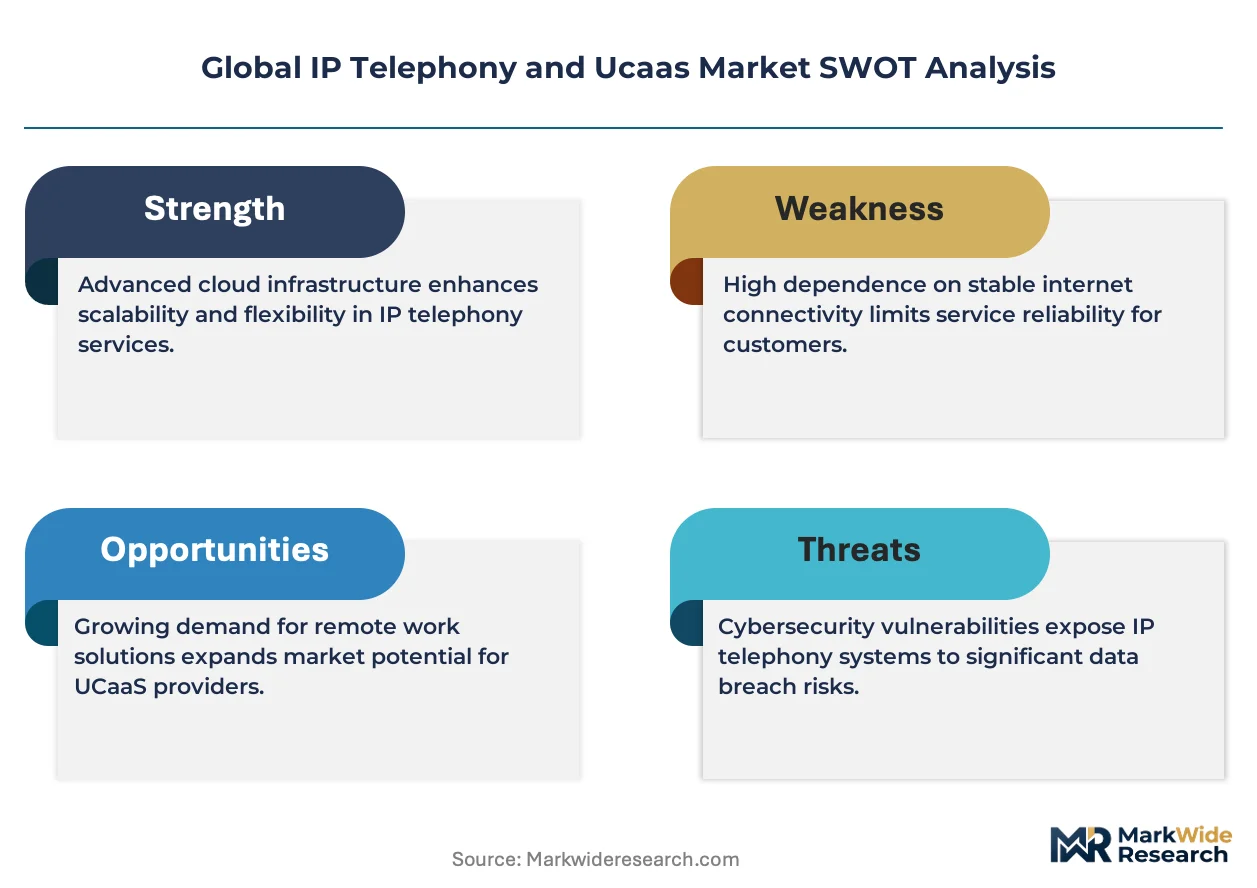
Capacity additions in India's data center corridors are reshaping price floors for cloud-hosted voice infrastructure. Three-tier pricing structure across premium, standard, and economy levels dominates enterprise procurement, with differentiation driven by HIPAA encryption certification and AI-assisted workflow depth. Cost compression in the mid-market tier is intensifying because TRAI VoIP guidelines accelerate multi-tenant infrastructure deployment. Healthcare providers exhibit lowest price sensitivity due to compliance mandates, while India's SME segment drives volume through consumption-based models.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries producing session border controller chipsets. Hardware assembly concentrates in China, Mexico, and Vietnam, while cloud infrastructure provisioning draws from hyperscaler data center networks across the United States, Germany, and India. Supply chain risk centers on tariff exposure for premises-based IP phone shipments. Distribution runs through carrier-affiliated service providers and direct SaaS platforms serving mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global IP Telephony and UCaaS Market operates as a regulatory compounder, with the EU AI Act's algorithmic transparency mandates driving systematic upgrade cycles across European contact center deployments.
For Market Incumbents: To counter cloud-native platform erosion, Cisco Systems and Microsoft must deepen backward integration into sovereign data center infrastructure across Germany and India. Certification investment in GDPR-compliant AI explainability dashboards captures premium positioning. Channel control through carrier partnerships defends installed-base renewal rates against mid-market specialists. For New Entrants and Emerging Players: Enter via Indonesia's underpenetrated SME manufacturing segment, where local data center partnerships satisfy emerging sovereignty expectations. Simplified WebRTC-native provisioning without legacy PBX migration complexity offers the most penetrable wedge. Direct-to-end-user SaaS platforms bypass incumbent distribution chokepoints. For Investors and Strategic Acquirers: Cloud-native platform operators are the most active acquirer in this space, consolidating AI-assisted workflow specialists to augment contact center margins. Long-term viability hinges on geographic data center footprint expansion. Watch FCC E911 mandate enforcement velocity as an inflection indicator for remote-work infrastructure retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Data Center Expansion | GDPR and EU AI Act compliance architecture in Germany and India anchors premium-tier contract capture. |
| AI-Assisted Workflow Integration | Real-time transcription and sentiment analysis convergence opens margin pools beyond commoditized voice transport. |
| Carrier Partnership Deepening | Verizon and Orange Business Solutions distribution networks accelerate enterprise penetration against direct-sales rivals. |
| WebRTC-Native Platform Launch | Browser-native media engines collapse plugin dependencies for healthcare and financial services customer portals. |
| Vertical Compliance Certification | HIPAA encryption and MiFID II surveillance capabilities differentiate procurement specifications in US healthcare and UK fintech. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged CTOs at technology firms, IT procurement officers at healthcare systems, platform engineers at cloud-native vendors, and channel partners serving India's SME segment. Secondary validation drew from FCC filings, TRAI regulatory notices, SEC 10-K hyperscaler disclosures, and EU AI Act implementation guidance. Bottom-up deployment volume estimates triangulated against top-down addressable market sizing.
Segment-weighting applied deployment model, organization size, vertical industry, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from fitted growth curves incorporating AI adoption velocity, cloud-first mandate implementation timelines, and legacy PBX replacement cycles. Model inputs included E911 compliance retrofit demand and WebRTC browser penetration rates.
Inputs from carrier partnership disclosures and hyperscaler capex announcements were available through the study window; gaps in private SME procurement data introduce uncertainty bands around India growth trajectories. Forecasts reflect assumptions about regulatory enforcement consistency and workforce distribution permanence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Unified Monitoring Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
Ucaas in Banking Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
United States SMS and MMS Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
Cloud UC Calling Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Ucaas in the Manufacturing Market
Unified Communications
Unified Communication Market
Unified Communications
High Definition HD Voice Market