
 Global Mobile Unified Communications and Collaboration Market | 2026-2036
Global Mobile Unified Communications and Collaboration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Unified Communications and Collaboration Market Foresight
Cloud infrastructure investment in North American hyperscale facilities is shifting toward edge-compatible architectures that support low-latency mobile UC&C workloads. Microsoft Corporation leverages its Azure global footprint to sustain platform availability across distributed enterprise environments. Cisco Systems anchors its competitive position through deep integration of security stacks with mobile voice and video endpoints. Zoom Video Communications differentiates via simplified user experience design that reduces IT support overhead for hybrid work deployments.
Mobile unified communications and collaboration encompasses real-time messaging, VoIP voice calling, video conferencing, presence indication, and file synchronization delivered through native applications on iOS, Android, and progressive web platforms with end-to-end encryption and API extensibility. The technology serves distributed enterprises requiring seamless workforce connectivity without tethering employees to fixed desktop environments. Cloud-based deployment mode leads current revenue contribution as organizations retire legacy PBX infrastructure, while hybrid architectures capture growing interest from financial services firms navigating data residency requirements. Video conferencing solution type commands premium pricing due to bandwidth and compute intensity, whereas messaging and file sharing segments operate at scale-driven margin structures.
FCC net neutrality rulings in the United States shape how mobile carriers prioritize UC&C traffic across cellular networks, while GDPR and the EU AI Act impose strict constraints on cross-border data flows and automated decision-making within European deployments. Japan's METI guidelines on telework infrastructure standards influence enterprise procurement criteria for mobile collaboration tools. Stakeholders must monitor evolving spectrum allocation policies and sovereign cloud certification programs as determinants of platform accessibility and competitive positioning.
Market Dynamics
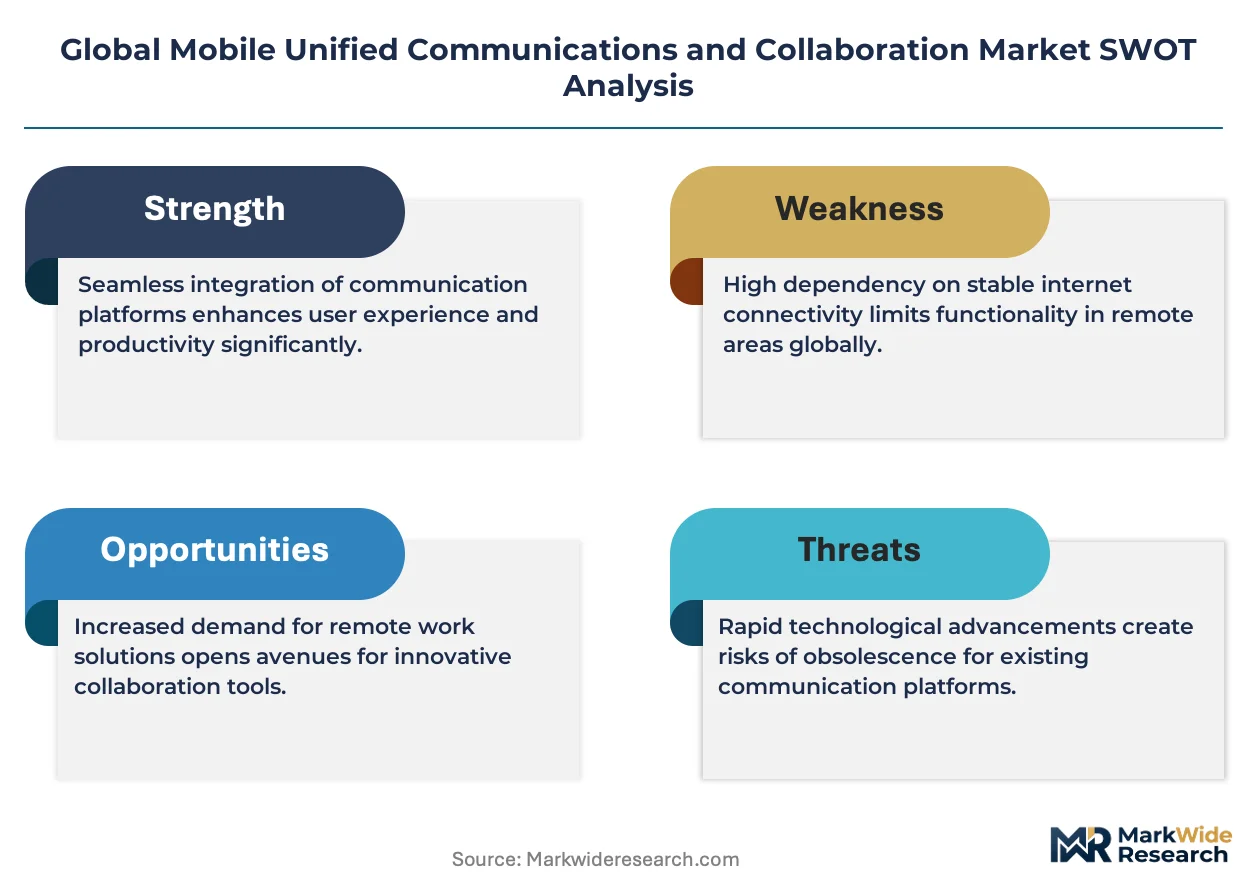
Enterprise migration from on-premises PBX systems to cloud-native mobile collaboration platforms is compressing deployment timelines and forcing incumbent vendors to re-architect delivery models around API-first extensibility.
Growth Catalysts
- Healthcare delivery networks:Clinical staff require secure, HIPAA-compliant mobile messaging and voice coordination across dispersed care facilities. Hospital systems in the United States are standardizing on integrated platforms that unify nurse call systems with physician mobile endpoints.
- EU AI Act compliance deadlines:European enterprises face mandatory algorithmic transparency requirements for automated decision-making in workforce management tools. This accelerates replacement of legacy systems lacking audit trails and explainable AI documentation.
- Edge computing infrastructure:Hyperscale providers are deploying micro-datacenters within 50 kilometers of major metropolitan zones. This topology reduces latency for real-time video and voice workloads on mobile devices.
Market Restraints
- Semiconductor supply concentration:Advanced baseband processors for enterprise-grade mobile endpoints depend on fabrication capacity concentrated in Taiwan and South Korea. Geopolitical friction threatens component availability.
- GDPR cross-border data friction:European data residency requirements block seamless failover of UC&C workloads to non-EU cloud regions. This fragments platform architectures and raises operational complexity.
- Legacy PBX sunk costs:Financial services firms in Japan maintain substantial capital investment in METI-certified on-premises voice infrastructure. Replacement cycles extend due to depreciation schedules and compliance re-certification costs.
Strategic Opportunities
- German sovereign cloud certification:The country's GAIA-X framework creates procurement preference for EU-controlled data infrastructure. Vendors achieving compliance gain preferential access to automotive and industrial enterprise accounts.
- Convergence of UC&C with IoT field service:Integration of mobile collaboration platforms with connected equipment telemetry enables real-time technician dispatch and remote expert guidance. This application is expanding in Japanese manufacturing and German utilities.
- India's PLI scheme for electronics manufacturing:Production-linked incentives attract assembly of enterprise mobile devices and networking equipment within the country. This reduces landed cost for domestic UC&C deployments and supports government procurement mandates.
Industry Challenges
- End-to-end encryption key management:Enterprise IT teams lack specialized cryptography expertise to implement zero-trust architectures across distributed mobile endpoints. Skills scarcity extends deployment timelines and elevates security audit failures.
- Multi-vendor integration complexity:Hybrid environments combining Microsoft Teams, Cisco Webex, and Zoom require custom API middleware. This interoperability tax consumes 15-25% of annual IT collaboration budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Unified Communications and Collaboration Market |
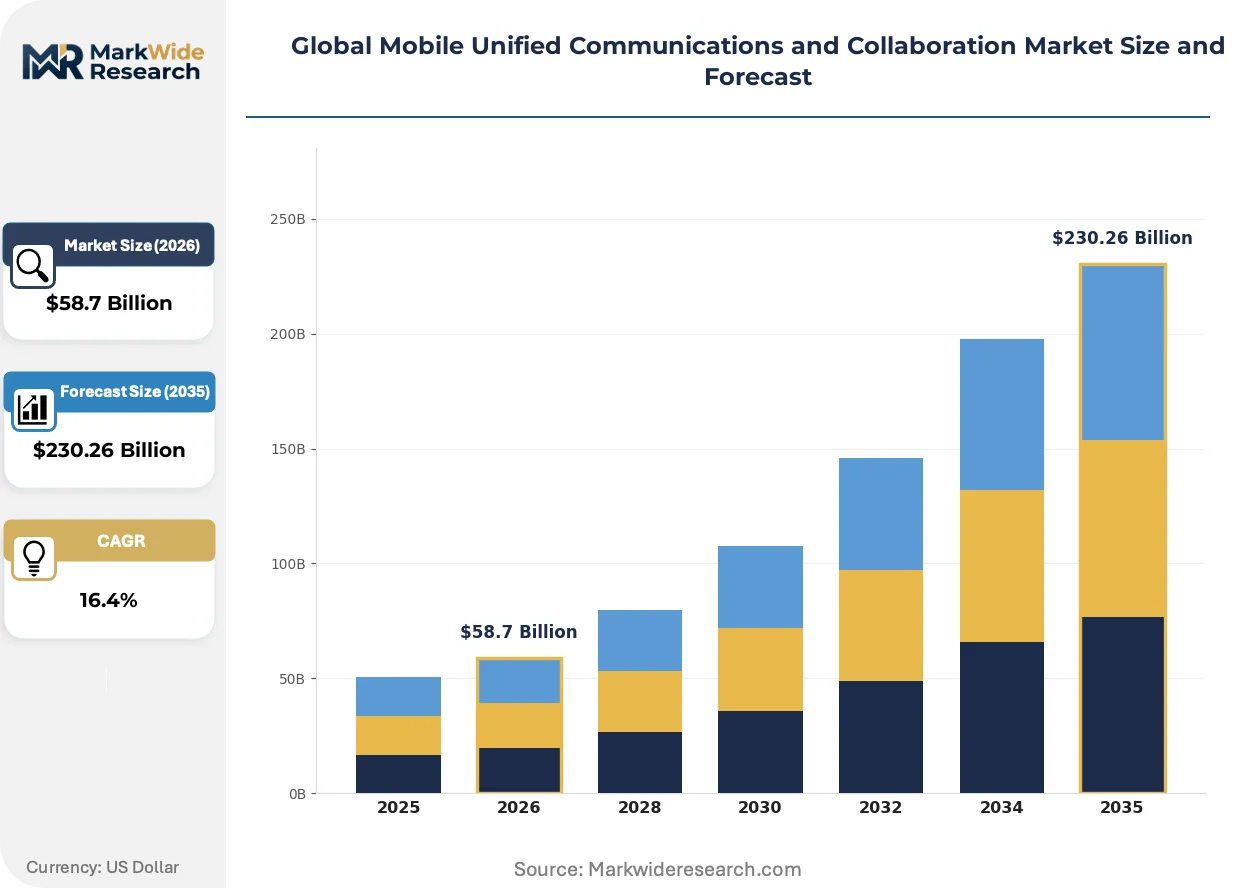
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $230.26 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Messaging, Voice Calling, Video Conferencing, Presence Management, File Sharing, Task Management Deployment Mode: Cloud-Based, On-Premise, Hybrid, Multi-Cloud End User Industry: Information Technology, Financial Services, Education, Government, Telecommunications Device Compatibility: Smartphones, Tablets, Laptops, Desktop Computers, Wearables |
| Companies Covered | Cisco Systems, Microsoft Corporation, Avaya Inc., IBM Corporation, Zoom Video Communications, RingCentral Inc., Huawei Technologies, NEC Corporation, Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Unified Communications and Collaboration Market Shifts & Advancements
Artificial intelligence inference at the device level is redefining performance requirements for mobile UC&C hardware. Vendors are racing to optimize power consumption while preserving real-time transcription and translation capabilities.
On-device neural processing units are expanding into enterprise mobile endpoints to enable real-time speech-to-text and speaker identification without cloud round-trips. Field service technicians in German automotive plants are adopting these capabilities for hands-free documentation. This edge-AI architecture is expanding into mid-tier device segments previously limited to cloud-dependent processing.
Japan's METI telework infrastructure standards now mandate interoperability certification for mobile collaboration platforms used in government procurement. Vendors must demonstrate SIP trunking compatibility and disaster recovery failover protocols. Domestic system integrators are consolidating around certified platforms, compressing vendor selection cycles for public sector deployments.
Enterprise buyers are unbundling UC&C procurement from bundled telecommunications contracts. Large manufacturers in the United States now source mobile collaboration software separately from carrier voice and data plans. This disintermediation shifts pricing power toward platform vendors and pressures traditional telecom resellers to develop managed services capabilities.
Global Mobile Unified Communications and Collaboration Market Segmentation
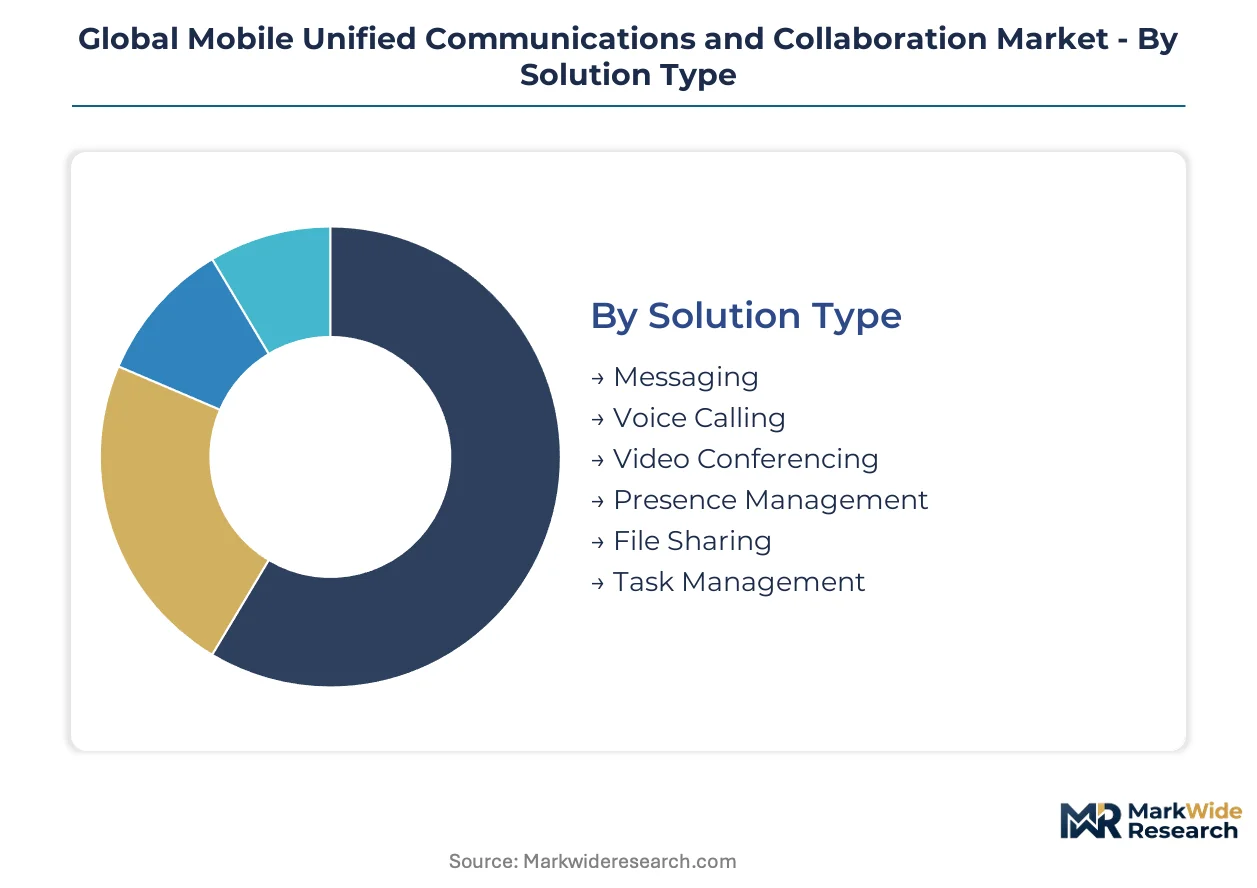
Mobile UC&C procurement patterns diverge sharply across solution architectures, deployment topologies, and workforce device ecosystems. Understanding these fault lines enables vendors to align R&D investment with segments commanding pricing power versus those scaling through volume.
Solution Type:
Video conferencing commands premium pricing due to bandwidth intensity and compute requirements, while messaging and file sharing operate on scale-driven margin structures.
- Video Conferencing:High-definition real-time video with spatial audio and virtual background rendering consumes substantial cloud GPU resources. Healthcare delivery networks in the United States prioritize this modality for telemedicine consultations requiring diagnostic visual fidelity.
- Messaging:Asynchronous text communication with end-to-end encryption and ephemeral content controls. Financial services firms in Germany favor this segment for trader compliance under MiFID II documentation requirements.
- Voice Calling:VoIP audio with noise cancellation and call recording capabilities.
- Presence Management:Real-time availability status and calendar integration across endpoints.
- File Sharing:Synchronized document repositories with version control and co-authoring.
- Task Management:Workstream coordination with assignment tracking and deadline notifications.
Today's leader: Video conferencing. Tomorrow's challenger: Messaging.
Deployment Mode:
Cloud-based architectures dominate current revenue as organizations retire legacy PBX infrastructure, though hybrid configurations gain traction among regulated industries.
- Cloud-Based:Fully managed SaaS delivery with automatic updates and elastic capacity scaling. Japanese enterprises adopting METI telework standards favor this mode for rapid deployment without capital expenditure.
- Hybrid:Split architecture keeping sensitive voice data on-premises while routing collaboration tools through public cloud. German automotive manufacturers select this approach to satisfy GAIA-X data sovereignty certification.
- On-Premise:Self-hosted infrastructure with direct hardware control.
- Multi-Cloud:Workload distribution across AWS, Azure, and GCP to mitigate vendor lock-in.
Cloud-based deployments hold current volume leadership. Hybrid architectures are climbing the fastest as sovereign data requirements harden.
End User Industry:
Regulatory intensity and workforce mobility patterns create divergent procurement specifications across verticals.
- Healthcare:HIPAA-compliant platforms with clinical workflow integration and nurse call system unification. Hospital systems in the United States standardize on these solutions for physician-mobile endpoint coordination.
- Financial Services:Archival and surveillance capabilities meeting SEC and FINRA retention mandates. Trading floors in Frankfurt and Tokyo demand sub-50 millisecond latency for time-sensitive communications.
- Information Technology:API-first platforms supporting DevOps toolchain integration.
- Education:Scalable licensing for semester-based enrollment fluctuations.
- Government:FedRAMP or equivalent security certification requirements.
Healthcare anchors current premium spending. Financial services represent the steepest expansion trajectory as algorithmic trading floors mobilize.
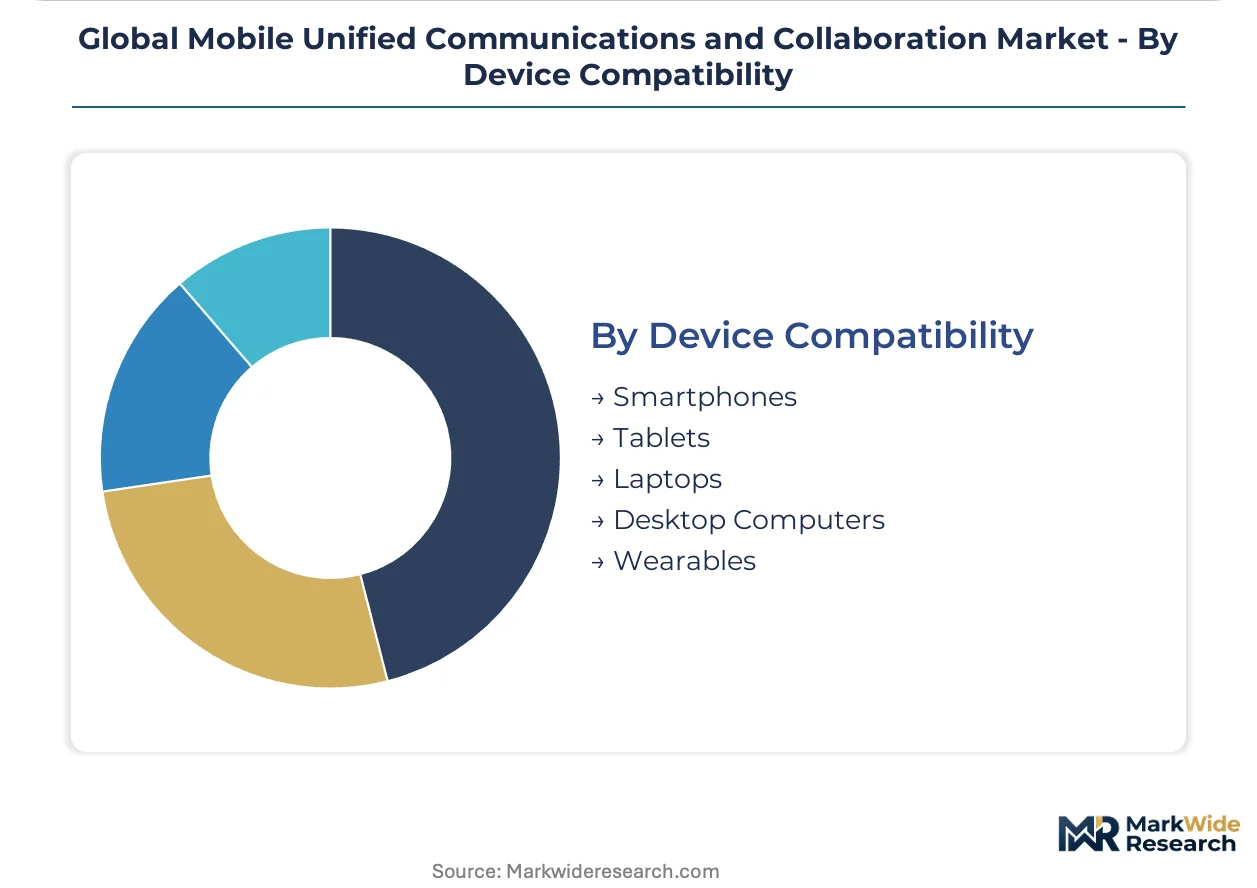
Device Compatibility:
Enterprise endpoint strategies increasingly favor smartphone-centric deployments while maintaining fallback coverage across form factors.
- Smartphones:Native iOS and Android applications with biometric authentication and encrypted local storage. Field service technicians in German utilities rely on these for IoT-integrated dispatch and remote expert guidance.
- Wearables:Smartwatch and AR glass interfaces enabling hands-free operation. Japanese manufacturing plants deploy these for assembly line workers requiring voice-activated documentation.
- Tablets:Larger-screen devices for presentation and annotation workflows.
- Laptops:Full-featured desktop-class clients with peripheral integration.
- Desktop Computers:Stationary endpoints for contact center and administrative roles.
Smartphones dominate installed base. Wearables are gaining share fastest as industrial safety protocols evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan demonstrate contrasting procurement patterns for mobile UC&C infrastructure, with German automotive manufacturers prioritizing sovereign cloud compliance while Japanese enterprises emphasize METI-certified interoperability standards.
United States
Healthcare delivery networks and financial services firms drive enterprise mobile UC&C investment. FCC net neutrality rulings shape how carriers prioritize real-time collaboration traffic across cellular networks. Hospital systems in Texas and California standardize on integrated platforms unifying nurse call systems with physician mobile endpoints.
Germany
Automotive manufacturers and industrial enterprises anchor demand for GAIA-X certified sovereign cloud deployments. The EU AI Act and GDPR impose strict constraints on cross-border data flows and automated workforce management tools. Manufacturing clusters in Bavaria and Baden-Württemberg select hybrid architectures to satisfy data residency requirements.
Japan
Enterprise mobility upgrades and government procurement mandates accelerate platform adoption. METI telework infrastructure standards require SIP trunking compatibility and disaster recovery failover certification. System integrators in Tokyo and Osaka consolidate around certified platforms for public sector deployments.
India
Domestic electronics manufacturing incentives and government procurement mandates expand market opportunity. The PLI scheme for electronics manufacturing attracts assembly of enterprise mobile devices and networking equipment. Technology hubs in Karnataka and Telangana reduce landed costs for domestic UC&C deployments.
United Kingdom
Financial services compliance requirements and hybrid work standardization sustain platform investment. GDPR cross-border data friction blocks seamless workload failover to non-EU cloud regions. Trading floors in London navigate fragmented architectures while meeting FCA archival mandates.
Global Mobile Unified Communications and Collaboration Market Competitive Landscape
United States-based hyperscale cloud providers anchor one tier; European and Asian telecommunications specialists hold differentiated positions in carrier-integrated deployments. The market exhibits tiered concentration with platform vendors commanding pricing power over infrastructure components. Three archetypes dominate: cloud-native SaaS providers, legacy equipment manufacturers pivoting to subscription models, and telecommunications carriers bundling collaboration services. Strategic moves center on API-first extensibility investments and sovereign cloud certification achievements.
Among United States-based platform vendors, Microsoft Corporation and Cisco Systems exemplify contrasting approaches to enterprise mobility. Microsoft leverages its Azure global footprint to sustain platform availability across distributed environments. Cisco anchors competitive positioning through security stack integration with mobile voice and video endpoints. Zoom Video Communications occupies a position emphasizing simplified user experience design that reduces IT support overhead.
| Leading Market Players |
|---|
| Cisco Systems |
| Microsoft Corporation |
| Avaya Inc. |
| IBM Corporation |
| Zoom Video Communications |
| RingCentral Inc. |
| Huawei Technologies |
| NEC Corporation |
| Ericsson |
| Others |
Supply & Pricing Matrix
Captive cloud infrastructure ownership by hyperscale providers anchors supply positioning and pricing power across mobile UC&C deployments. Microsoft and Cisco maintain in-house control over global data center footprints and security stack integration, insulating premium tiers from commodity pressure while forcing smaller vendors toward outsourced edge hosting.
Pricing Analysis
Capacity additions in India's domestic electronics manufacturing zones are reshaping price floors for enterprise mobile endpoints. Three-tier pricing structure across premium, standard, and economy levels dominates SaaS delivery, with HIPAA certification and GAIA-X sovereign cloud compliance commanding substantial premiums. Cost compression in standard-tier messaging services is intensifying because India's PLI scheme attracts assembly competition. Mid-market healthcare networks in the United States exhibit highest price sensitivity, while German automotive manufacturers prioritize certification over cost.
Supply Chain Analysis
Advanced baseband processor supply rests on Taiwanese and South Korean fabrication capacity concentrated in TSMC and Samsung foundries. Cloud GPU resources for video conferencing draw from NVIDIA and AMD allocations, while enterprise mobile endpoints source displays from Chinese and Vietnamese panel manufacturers. Single-source vulnerability in sub-7nm semiconductor nodes threatens component availability during geopolitical friction. Distribution runs through carrier-integrated resellers and direct hyperscaler marketplaces, with unbundling trends shifting volume toward platform-native procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile UC&C has matured into a late-cycle quality market where procurement favors platforms with proven sovereign cloud certification and vertical workflow integration. Healthcare delivery networks now mandate HIPAA-compliant clinical collaboration as baseline specification, disqualifying uncertified entrants from hospital system RFPs.
For Market Incumbents: Lock in GAIA-X and METI certification moats before compliance windows narrow. Acquire specialized clinical workflow integrators to deepen vertical penetration against API-first challengers. Prioritize edge micro-datacenter expansion in Germany and Japan to defend latency advantages for real-time video workloads.
For New Entrants and Emerging Players: Direct-to-developer API marketplaces offer the fastest route to embedded collaboration without carrier distribution dependencies. Target Indian domestic manufacturing ecosystems where PLI incentives reduce endpoint landed costs. Pursue white-label integration with Japanese system integrators consolidating around METI-certified platforms.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-vendor integration complexity consumes 15-25% of enterprise IT collaboration budgets. Five-to-ten year viability favors platforms with demonstrated sovereign cloud compliance and healthcare vertical penetration. Watch for FCC spectrum allocation rulings and EU AI Act enforcement actions as inflection triggers for platform accessibility and competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Microsoft Teams and Cisco Webex interoperability reduces middleware tax for hybrid deployments. |
| Strategic Partnership | Carrier-agnostic unbundling agreements with Verizon and Deutsche Telekom expand direct enterprise access. |
| Acquisition of Specialist Firm | Clinical workflow integrators with nurse call system expertise command premium valuations from hospital networks. |
| Geographic Expansion | GAIA-X certified edge nodes in Bavaria unlock automotive procurement previously blocked by data residency requirements. |
| Product Launch | On-device NPU-enabled transcription differentiates mid-tier endpoints for German field service technicians. |
Research Methodology
Direct dialogue with CIOs at hospital systems, IT procurement officers at German automotive manufacturers, platform engineers at hyperscale cloud providers, and integration specialists at Japanese system integrators grounded qualitative findings. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, METI certification registries, and EU AI Act implementation guidance. Bottom-up and top-down triangulation cross-checked endpoint shipment estimates against SaaS subscription revenue recognition patterns.
Bottom-up modeling aggregated deployment mode, solution type, end-user industry, and device compatibility dimensions across the analysis window. CAGRs derived from segment-level growth rate reconciliation with macroeconomic mobility infrastructure investment indicators. Forecast inputs incorporated FCC spectrum allocation timelines, GAIA-X certification progression, and India's PLI scheme capacity buildout schedules without year-specific anchoring.
The model assumes a particular technology adoption path; alternative pathways for on-device neural processing unit inference would alter the outlook if edge-AI latency advantages fail to materialize at scale. Forecasts reflect assumptions about sovereign cloud certification penetration and healthcare vertical standardization that regulatory enforcement actions or carrier pricing restructuring could revise. A small set of triggers—EU AI Act audit outcomes, Taiwan semiconductor export restrictions, and METI interoperability standard updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
United States SMS and MMS Market
Unified Communications
High Definition HD Voice Market
Unified Communications
Cloud UC Calling Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
Unified Monitoring Market
Unified Communications
Unified Communication Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Ucaas in the Manufacturing Market
Unified Communications
Business Cloud Voip and UC Services Market