
 Ucaas in the Manufacturing Market | 2026-2036
Ucaas in the Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Ucaas in the Manufacturing Market Analytics
Market Context
Enterprise-grade SLAs with sub-50ms latency guarantees is rotating demand toward specialized UcaaS architectures purpose-built for industrial environments. Cisco Systems, Inc. leverages its Webex platform's edge-computing integrations to serve high-availability manufacturing workflows. Microsoft Corporation anchors its Teams deployments through Azure Industrial IoT partnerships that bundle voice with machine-data analytics. Zoom competes on simplified provisioning models that reduce IT overhead for mid-sized assembly plants.
Technical Definition and Segments
UcaaS in manufacturing delivers voice, video, messaging, and contact-center functions through cloud-hosted infrastructure with API connectivity to SCADA and MES systems, typically requiring 99.999% uptime and OPC-UA protocol compatibility for shop-floor integration. The primary purpose is to unify distributed production teams, suppliers, and field service engineers under a single communication layer that interoperates with operational technology stacks. VoIP and video conferencing segments dominate current spending as OEMs replace legacy PBX systems, while hybrid cloud deployment is capturing the fastest growth by balancing data residency requirements with cloud elasticity. Managed services command the deepest margin pools because manufacturers outsource voice quality monitoring, security patching, and ERP-CRM integration to specialized providers.
Regulatory Frame and Outlook
NIST, the EU's Cybersecurity Act, and Germany's BSI IT-Grundschutz standards collectively mandate encrypted communications, access logging, and supply-chain risk documentation that elevate compliance costs for UcaaS vendors serving manufacturing. These frameworks shape demand by disqualifying providers lacking ISO 27001 certification or sovereign cloud options, particularly for defense and pharmaceutical subcontractors. Stakeholders must monitor how emerging operational-technology cybersecurity regulations in the United States and European Union will redefine the boundary between information-technology and shop-floor network architectures.
Market Dynamics
Factory digitization programs in Germany's industrial corridor are embedding unified communications into operational technology environments, forcing UCaaS architectures to converge with SCADA and MES systems at the network edge.
Growth Catalysts
- BSI IT-Grundschutz certification requirements:German manufacturers now mandate encrypted communications with sovereign cloud options, disqualifying non-compliant vendors and concentrating procurement among certified providers serving automotive and pharmaceutical subcontractors.
- Tier-1 automotive supplier cloud migration:Accelerating replacement of legacy PBX systems with voice-video bundles that integrate directly into production line monitoring dashboards and supplier collaboration portals.
- Edge-computing latency thresholds:Sub-50ms SLA guarantees for high-availability workflows are rotating demand toward specialized industrial UCaaS platforms with local gateway deployments.
Market Restraints
- Data sovereignty compliance costs:The EU's Cybersecurity Act and evolving data localization rules require multi-region infrastructure duplication, elevating operational overhead for vendors serving cross-border manufacturing networks.
- Legacy OT-IT integration complexity:OPC-UA protocol compatibility requirements and 99.999% uptime guarantees create technical barriers that extend sales cycles and inflate implementation costs for mid-sized assembly plants.
- Concentrated vendor certification scarcity:ISO 27001 certification and sovereign cloud capabilities remain concentrated among established providers, limiting price competition for defense and pharmaceutical manufacturing contracts.
Strategic Opportunities
- Underpenetrated industrial corridor expansion:Factory digitization programs in Baden-Württemberg and Bavaria present white-space demand for managed services bundling voice quality monitoring with ERP-CRM integration.
- Hybrid cloud deployment acceleration:Balancing data residency requirements with cloud elasticity is capturing the fastest growth segment as manufacturers seek flexible architectures that satisfy both IT and OT security teams.
- Contact-center convergence with machine analytics:Bundling voice services with Azure Industrial IoT partnerships creates new margin pools by unifying field service engineer dispatch with predictive maintenance alerts.
Industry Challenges
- OT cybersecurity skill scarcity:Manufacturers face acute shortages of engineers capable of configuring API connectivity between UCaaS platforms and SCADA systems without creating attack vectors.
- Regulatory boundary ambiguity:Emerging operational-technology cybersecurity regulations in the United States and European Union are redefining network architecture standards faster than vendors can certify compliance.
- Interoperability certification timelines:Extended validation periods for MES system integrations delay revenue recognition and strain vendor cash flow during competitive procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ucaas in the Manufacturing Market |
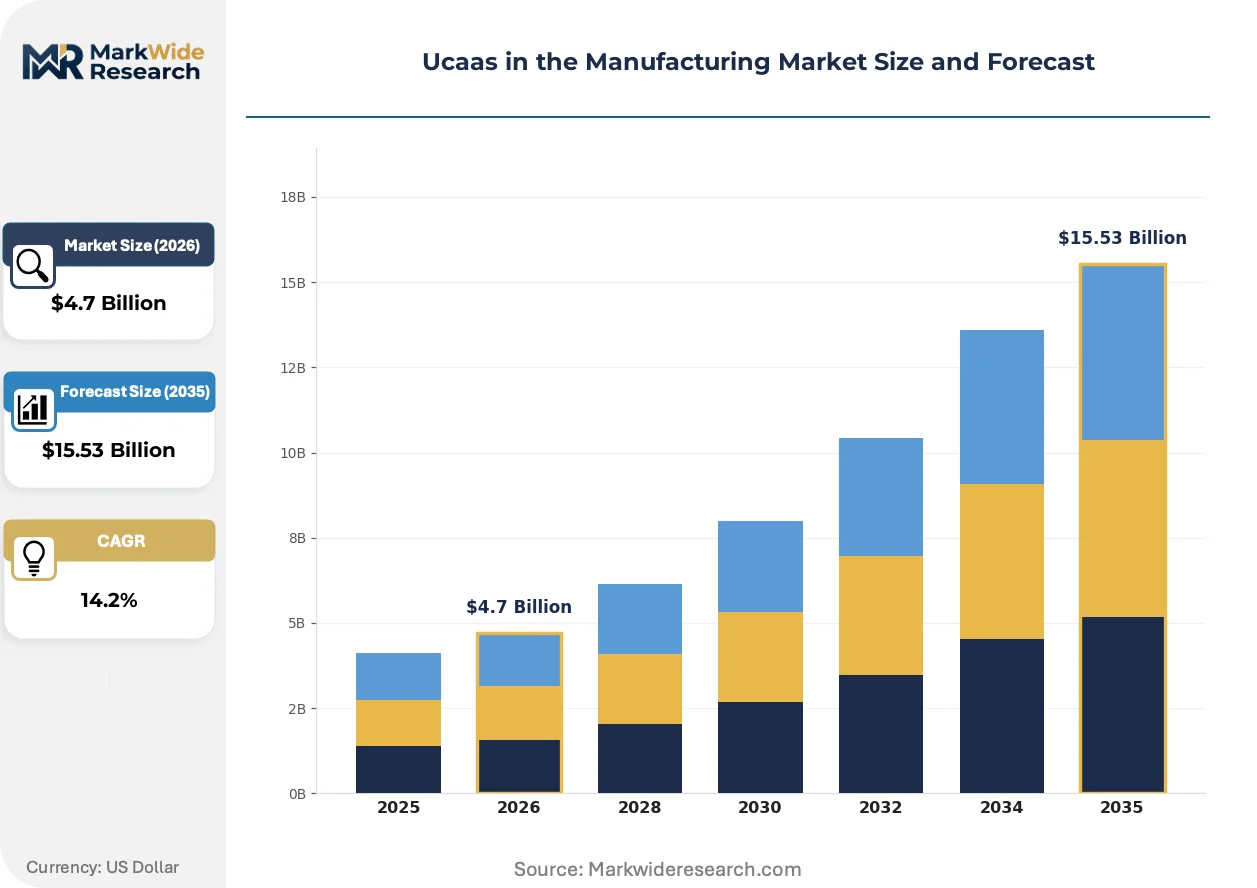
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VoIP, Video Conferencing, Team Collaboration, Contact Center Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: OEMs, Tier-1 Suppliers, Assembly Plants, Distribution Centers Service Type: Managed Services, Support Services, Custom Solutions, Integration Services |
| Companies Covered | Cisco Systems, Inc., Microsoft Corporation, Avaya Inc., 8x8, Inc., Tata Communications Limited, Sangoma, Zoom, RingCentral, Nextiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ucaas in the Manufacturing Market Evolving Landscape
Edge-native UCaaS architectures are displacing centralized cloud models as latency-sensitive manufacturing workflows demand local processing. Regulatory frameworks are hardening procurement criteria around encryption and access logging. Buyer behavior is pivoting toward outcome-based service contracts that bundle communication infrastructure with operational uptime guarantees.
Containerized microservices at the network edge are displacing monolithic cloud deployments in high-availability manufacturing environments. Automotive OEMs in Stuttgart and Wolfsburg are adopting these architectures fastest, driven by production line monitoring requirements that cannot tolerate WAN latency. This shift is compressing margins for pure-cloud providers while rewarding vendors with industrial edge computing partnerships.
The EU's Cybersecurity Act and Germany's BSI standards now mandate supply-chain risk documentation and encrypted communications with comprehensive access logging. These requirements are disqualifying uncertified providers from defense and pharmaceutical subcontractor contracts. Tier-1 automotive suppliers are responding by embedding compliance verification into RFP scoring matrices, privileging vendors with pre-certified sovereign cloud options.
Manufacturing procurement teams are consolidating vendor relationships around integrated platform contracts that tie communication service fees to operational uptime metrics. Traditional per-seat licensing models are losing ground to bundled offerings that include voice quality monitoring, security patching, and MES integration support. This pattern is most visible in Germany's industrial corridor, where factory digitization programs demand single-vendor accountability across IT and OT domains.
Ucaas in the Manufacturing Market Segmentation
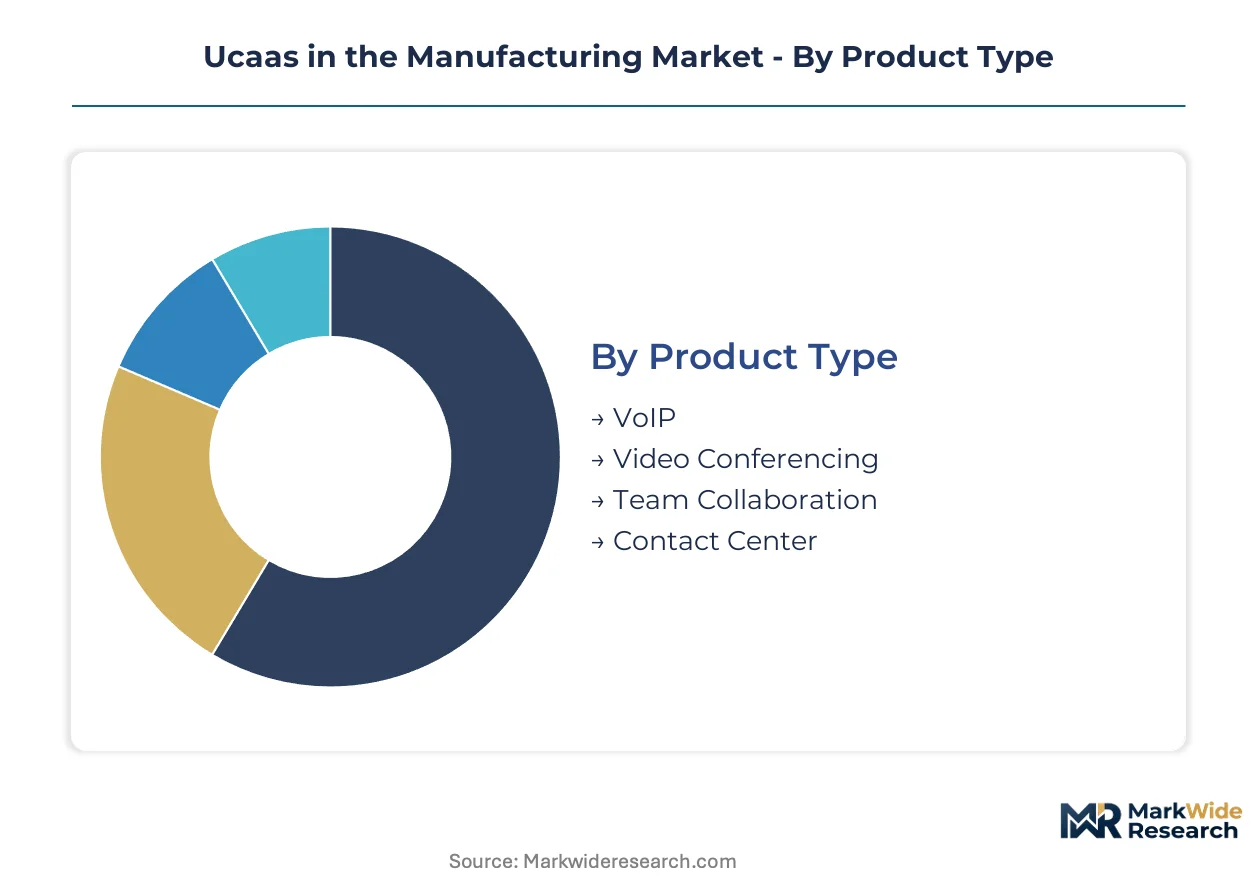
Segmentation in manufacturing UCaaS reveals how procurement criteria diverge between IT-centric and OT-integrated environments. Each dimension captures distinct technical requirements, compliance obligations, and vendor selection patterns that shape competitive positioning across automotive, pharmaceutical, and industrial equipment verticals.
Product Type:
Channel mix varies sharply by product complexity, with VoIP and video conferencing flowing through established telecom distributors while contact center solutions require direct vendor engagement for MES integration.
- VoIP:Cloud-hosted voice services replacing legacy PBX infrastructure in assembly plants and distribution centers. Demand concentrates in Germany's automotive corridor where factory digitization programs mandate encrypted communications with sub-50ms latency guarantees.
- Video Conferencing:High-definition meeting platforms with edge-computing integrations for supplier collaboration and remote quality inspections. Tier-1 automotive suppliers in Stuttgart and Wolfsburg are accelerating adoption of bundles that integrate directly into production line monitoring dashboards.
- Team Collaboration:Persistent messaging and file-sharing workspaces with API connectivity to ERP systems.
- Contact Center:Omnichannel customer engagement platforms bundling voice with predictive maintenance alert routing.
VoIP dominates installed base. Contact Center is where expansion concentrates.
Deployment:
Cost tier structure separates premium sovereign cloud deployments from economy-grade public cloud offerings, with hybrid architectures commanding mid-market positioning.
- Public Cloud:Multi-tenant infrastructure delivering elastic capacity for mid-sized assembly plants without dedicated IT security teams. OEMs in cost-sensitive segments favor this model despite data residency limitations.
- Hybrid Cloud:Architectures balancing local gateway processing with cloud elasticity to satisfy both IT and OT security requirements. German manufacturers responding to BSI IT-Grundschutz mandates are driving fastest adoption in Baden-Württemberg and Bavaria.
- Private Cloud:Single-tenant environments with dedicated infrastructure for defense and pharmaceutical subcontractors.
- On-Premises:Legacy voice systems retained in facilities with extreme latency sensitivity or air-gapped security requirements.
Public Cloud holds majority share. Hybrid Cloud is climbing the fastest as regulatory pressure intensifies.
End User:
Application intensity scales with supply chain position, from OEMs demanding full platform integration to distribution centers requiring basic voice-video bundles.
- OEMs:Original equipment manufacturers requiring unified communications platforms with SCADA and MES interoperability for multi-site production coordination. Volkswagen, BMW, and Mercedes-Benz operations anchor demand in Germany's industrial corridor.
- Tier-1 Suppliers:Component manufacturers such as Bosch and Continental accelerating cloud migration to replace legacy PBX systems with integrated supplier collaboration portals.
- Assembly Plants:Discrete manufacturing facilities prioritizing shop-floor voice quality and OPC-UA protocol compatibility.
- Distribution Centers:Logistics hubs emphasizing mobile workforce enablement and warehouse management system integration.
Tier-1 Suppliers represent the deepest procurement activity. Assembly Plants offer the steepest expansion trajectory for specialized industrial UCaaS vendors.
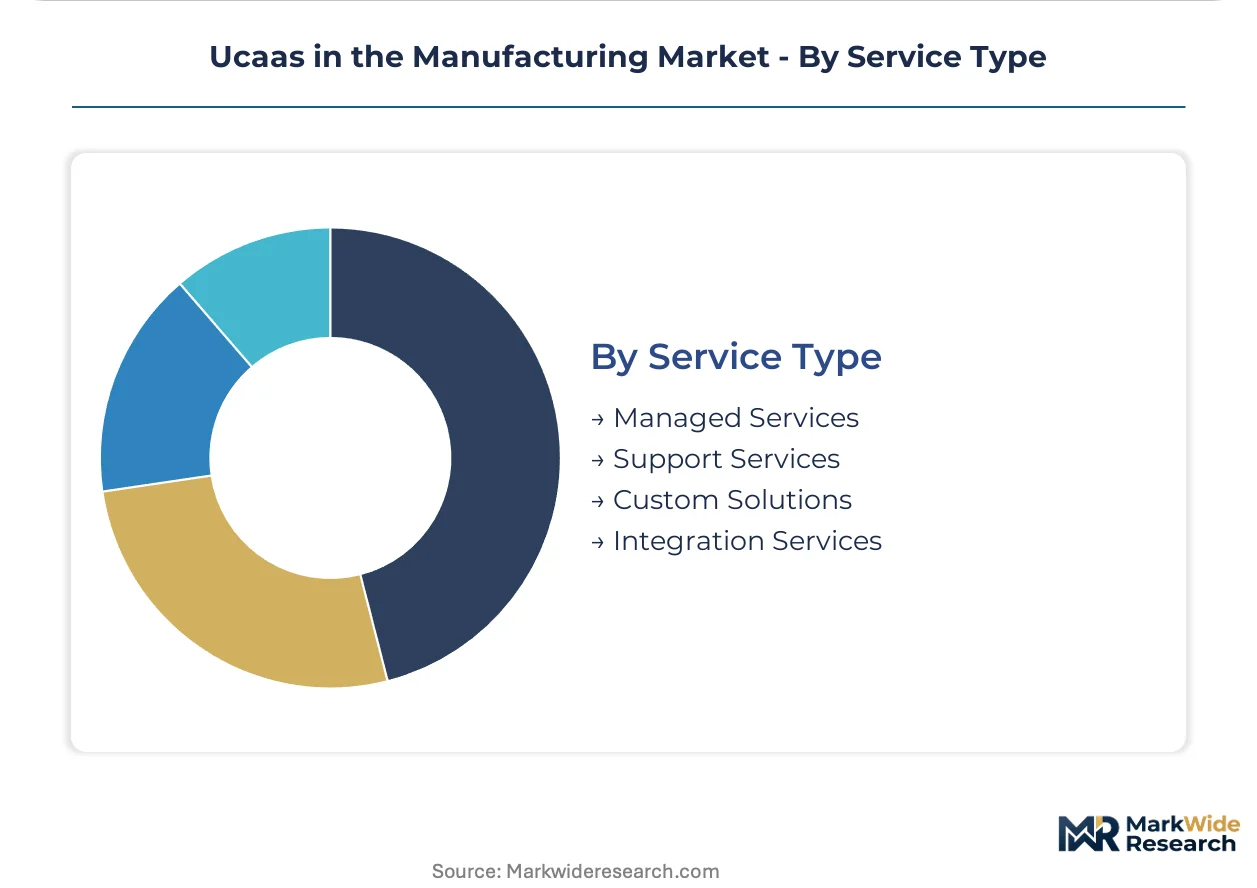
Service Type:
Margin concentration favors recurring revenue models, with managed services capturing premium pricing through outcome-based contracts tied to operational uptime.
- Managed Services:Outsourced voice quality monitoring, security patching, and ERP-CRM integration delivered under SLA-backed contracts. German manufacturers are consolidating vendor relationships around these bundled offerings to achieve single-vendor accountability across IT and OT domains.
- Integration Services:Custom API development and MES system connectivity projects for high-complexity deployments. Extended validation periods for these engagements delay revenue recognition but yield multi-year relationships.
- Support Services:Break-fix and technical assistance contracts for standardized implementations.
- Custom Solutions:Bespoke development for unique operational technology environments or specialized compliance requirements.
Managed Services dominates margin pools. Integration Services is gaining share fastest as OT-IT convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UCaaS infrastructure for manufacturing clusters most densely where automotive and pharmaceutical OEMs have invested in operational technology convergence. Sovereign cloud requirements and BSI IT-Grundschutz certification are reshaping vendor eligibility across industrial corridors.
United States
NIST cybersecurity frameworks and emerging OT security regulations are elevating procurement standards for defense and pharmaceutical subcontractors. The Department of Defense's CMMC requirements now flow down to manufacturing communication infrastructure. Detroit's automotive engineering centers and Houston's petrochemical complexes are driving demand for edge-native UCaaS with sub-50ms latency guarantees.
Germany
BSI IT-Grundschutz mandates now require encrypted communications with comprehensive access logging for automotive and pharmaceutical supply chains. Factory digitization programs in Baden-Württemberg and Bavaria are embedding unified communications directly into SCADA and MES environments. Stuttgart and Wolfsburg anchor the deepest procurement activity for hybrid cloud deployments balancing data residency with cloud elasticity.
China
MIIT industrial internet initiatives are accelerating cloud-based collaboration platform adoption among state-owned automotive and electronics manufacturers. GB standards for operational technology cybersecurity are creating compliance barriers for foreign UCaaS providers. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate demand for voice-video bundles integrated with production line monitoring systems.
Japan
METI's Society 5.0 roadmap is funding smart factory deployments that require API connectivity between UCaaS platforms and legacy MES systems. JIS standards for industrial communication security are elevating certification requirements for foreign vendors. The Chubu region around Nagoya and Kansi's Osaka-Kobe manufacturing corridor represent the most active procurement zones for managed services bundling voice quality monitoring with predictive maintenance.
India
PLI scheme incentives for automotive and electronics manufacturing are expanding factory footprints that require scalable communication infrastructure. TRAI data localization consultations are creating uncertainty for multi-tenant cloud deployments. Maharashtra's Pune-Nashik automotive belt and Tamil Nadu's Chennai-Sriperumbudur electronics corridor are driving fastest growth for mid-sized assembly plant UCaaS migrations.
Ucaas in the Manufacturing Market Competitive Landscape
Concentration sits with diversified technology conglomerates that can bundle UCaaS with adjacent infrastructure software. The vendor base stratifies across three tiers: hyperscale cloud platforms with industrial IoT partnerships, specialized telecommunications providers with sovereign cloud certifications, and mid-market SaaS vendors competing on simplified provisioning. M&A activity targets edge-computing specialists and OT cybersecurity boutiques, while strategic partnerships with SCADA and MES vendors dominate competitive positioning.
Within the diversified technology tier, Cisco Systems, Inc. and Microsoft Corporation exemplify platform breadth that spans enterprise networking through operational technology integration. RingCentral occupies a position among pure-play UCaaS specialists competing on mid-market accessibility. These anchors demonstrate how vendor selection increasingly hinges on pre-existing industrial automation relationships rather than communication features alone.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Microsoft Corporation |
| Avaya Inc. |
| 8x8, Inc. |
| Tata Communications Limited |
| Sangoma |
| Zoom |
| RingCentral |
| Nextiva |
| Others |
Value Network & Pricing Analysis
Capacity utilization at sovereign cloud data centers in Germany and the Netherlands shapes both supply concentration and price floors for industrial UCaaS, as BSI IT-Grundschutz certification requirements restrict viable vendor pools and elevate minimum viable pricing tiers for automotive and pharmaceutical subcontractors.
Pricing Analysis
BSI IT-Grundschutz and the EU Cybersecurity Act dictate the pricing tier structure across the German manufacturing corridor. Three-tier pricing separates sovereign cloud deployments from hybrid architectures and public cloud offerings, with ISO 27001 certification and OPC-UA protocol compatibility serving as the primary price differentiation drivers. Cost compression in mid-market public cloud tiers is intensifying because Zoom and RingCentral compete for assembly plant contracts on simplified provisioning models. Tier-1 automotive suppliers exhibit the least price sensitivity, prioritizing sub-50ms SLA guarantees and MES integration support over per-seat cost.
Supply Chain Analysis
Subsea cable chokepoints through the English Channel and North Sea transit underwrite latency performance for edge-native UCaaS architectures serving Stuttgart and Wolfsburg manufacturing clusters. Supply concentrates in Germany, the United States, and Ireland for sovereign cloud infrastructure, with critical dependencies on specialized edge gateway hardware, encrypted VoIP chipsets, and API middleware for SCADA interoperability. Single-source vulnerability in certified sovereign cloud capacity creates procurement bottlenecks for defense subcontractors. Distribution runs through direct vendor engagement for complex MES-integrated deployments, while standardized VoIP flows through telecom distributors serving mid-sized assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory digitization programs across Germany's industrial corridor signal early-cycle expansion, with penetration of OT-integrated UCaaS still below saturation even among Tier-1 automotive suppliers.
For Market Incumbents: Fortify sovereign cloud capacity in Baden-Württemberg and Bavaria to preempt emerging specialist vendors from capturing pharmaceutical subcontractor contracts. Deepen backward integration into edge gateway manufacturing to reduce dependency on single-source hardware suppliers and defend margin position against pure-cloud competitors. For New Entrants and Emerging Players: Managed services bundling voice quality monitoring with predictive maintenance alert routing represents the most penetrable white-space, as Cisco and Microsoft under-serve mid-sized assembly plants with complex OT-IT integration requirements. Target India's Pune-Nashik automotive belt through channel partnerships with local system integrators familiar with TRAI data localization consultations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors OT cybersecurity boutiques with pre-certified API connectivity to Siemens and Rockwell MES systems. Long-term viability hinges on regulatory moats deepening around BSI and NIST frameworks. Watch for inflection when emerging OT cybersecurity regulations in the United States and European Union redefine network architecture certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Gateway Partnership | Local processing partnerships with Siemens reduce latency for Stuttgart automotive OEMs. |
| Sovereign Cloud Certification | BSI IT-Grundschutz pre-qualification unlocks defense and pharmaceutical subcontractor procurement. |
| MES Integration Development | Native SCADA connectivity differentiates offerings for Tier-1 supplier cloud migrations. |
| Managed Services Bundling | Outcome-based contracts tying fees to operational uptime capture premium manufacturing accounts. |
| OT Cybersecurity Acquisition | Specialist firms with API security expertise address acute skill scarcity in manufacturing IT departments. |
Research Methodology
A spread of perspectives from plant engineers, OT cybersecurity leads, UCaaS procurement officers, and MES integration specialists converged on the working assumptions through structured primary interviews validated against secondary sources including SEC filings from Cisco and Microsoft, BSI certification registries, and German automotive production databases. Bottom-up sizing of individual factory deployments triangulated against top-down estimates from industrial cloud spending disclosures.
Segmentation dimensions modeled include deployment architecture, product type complexity, end-user supply chain position, and service delivery model across the projection horizon. CAGRs were derived from growth rate convergence analysis applied to adoption curves in Germany's industrial corridor, with forecast inputs incorporating BSI certification timeline data and Tier-1 supplier cloud migration announcements.
Underlying assumptions cover sustained factory digitization investment, stable BSI IT-Grundschutz requirements, and manageable OT-IT integration complexity, with deviation risk concentrated in accelerated NIST cybersecurity framework revisions and sovereign cloud capacity constraints. Practitioners should keep alternative scenarios live as emerging OT cybersecurity regulations in the United States and European Union evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
Business Cloud Voip and UC Services Market
Unified Communications
Ucaas in Banking Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
High Definition HD Voice Market
Unified Communications
Unified Communication Market
Unified Communications
United States SMS and MMS Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Cloud UC Calling Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Unified Monitoring Market