
 Enterprise AR Software Market | 2026-2036
Enterprise AR Software Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise AR Software Market Foresight
ISO/IEC 27001 certification for enterprise data security is reorganizing vendor qualification protocols for industrial AR deployments. Microsoft sustains cloud-edge hybrid architectures across manufacturing and healthcare accounts. PTC specializes in CAD-anchored AR authoring tools for factory-floor maintenance workflows. TeamViewer controls remote assistance connectivity layers that bridge field technicians with centralized expertise pools.
Enterprise AR software overlays digital information—spatial instructions, 3D schematics, real-time telemetry—onto physical environments through head-mounted displays, handheld devices, or projection systems, with sub-20 millisecond latency thresholds required for synchronous remote collaboration. Its primary commercial purpose is to reduce operational errors, compress training cycles, and enable expert access without geographic relocation. Cloud-based deployment captures the fastest expansion as manufacturers abandon capital-heavy server installations for scalable SaaS consumption models. Maintenance solutions within the solution category carry the deepest margin pools due to recurring subscription attach rates and integration complexity with legacy asset management systems.
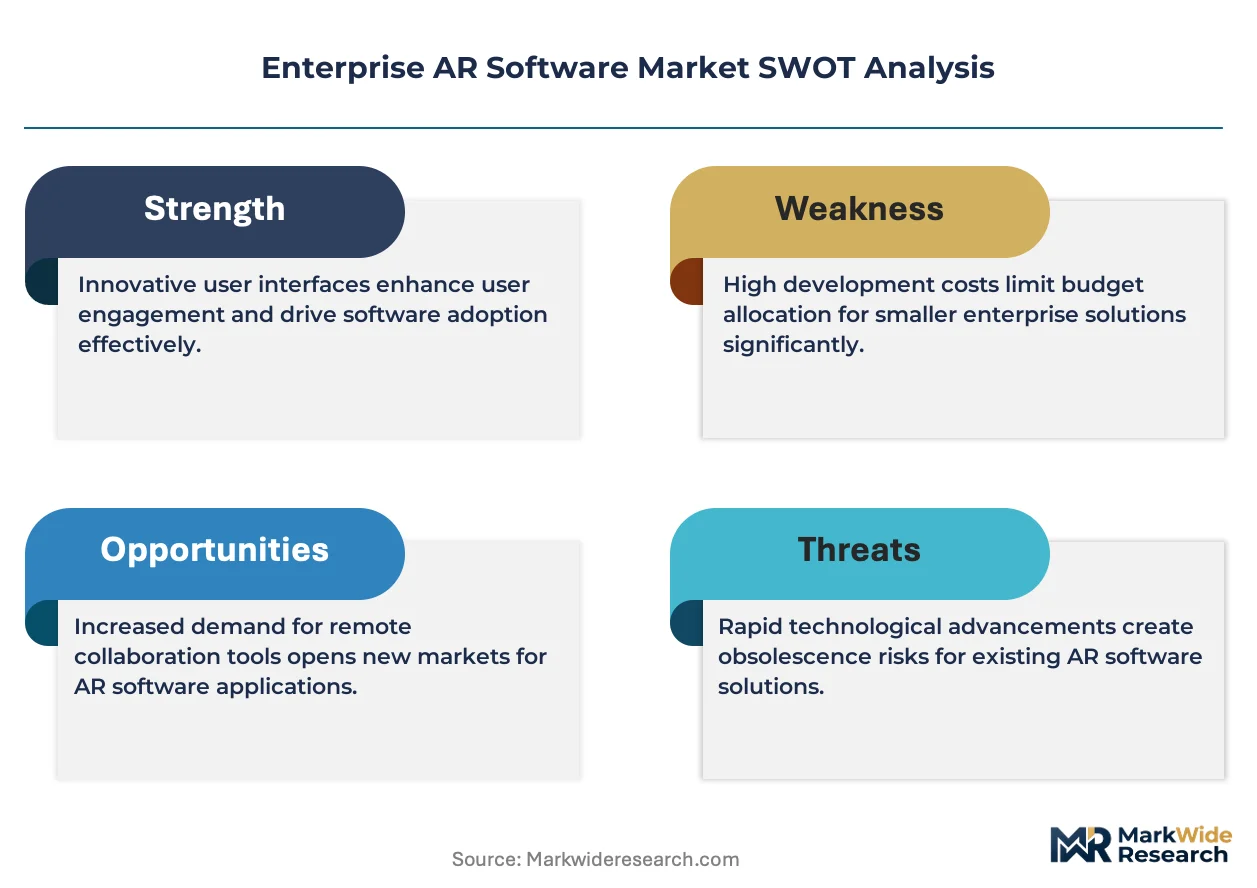
FDA scrutiny of AR-guided surgical visualization tools in the United States shapes validation requirements for healthcare end users, while EU AI Act provisions on transparency and human oversight constrain algorithmic decision layers in European industrial AR applications. Germany's KBA enforces functional safety standards for AR interfaces used in automotive assembly verification. Stakeholders must weigh regulatory compliance investment against platform interoperability gains when selecting deployment architectures.
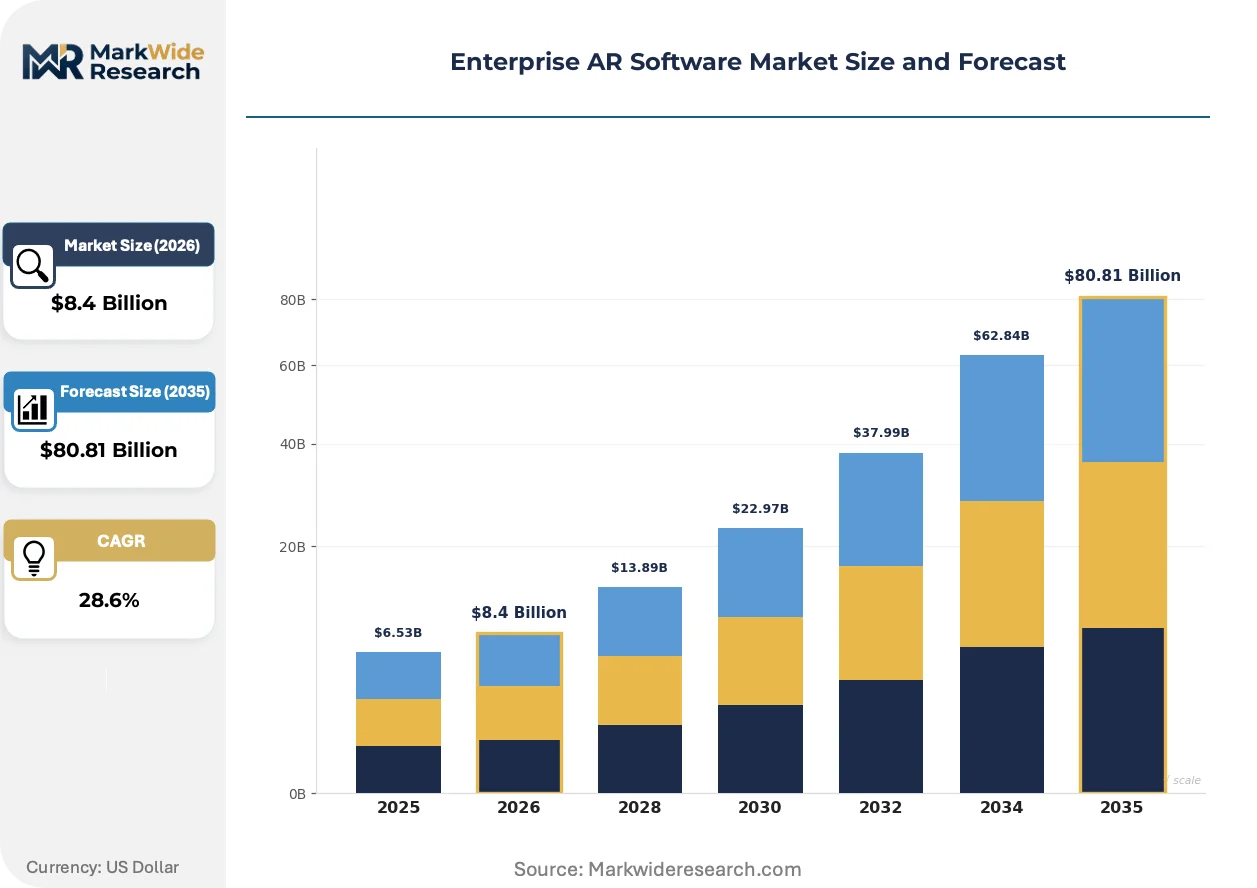
Market Dynamics
Cloud-edge hybrid architectures are compressing deployment timelines as manufacturers abandon capital-intensive server farms for consumption-based SaaS models with sub-20 millisecond latency guarantees.
Growth Catalysts
- ISO/IEC 27001 certification protocols:Enterprise data security mandates are accelerating vendor qualification cycles for industrial AR deployments in regulated manufacturing environments.
- 5G network latency thresholds:Telecommunications infrastructure improvements in Germany, Japan, and the United States enable synchronous remote collaboration previously impossible over 4G.
- Workforce training mandates:Industrial digitization budgets in China and the United States prioritize AR-guided skill transfer to address technician shortages.
Market Restraints
- Optical component supply concentration:Waveguide and micro-display manufacturing clusters in East Asia create single-source vulnerability for head-mounted display producers.
- EU AI Act algorithmic transparency requirements:Human oversight provisions constrain automated decision layers in European industrial AR applications, extending validation timelines.
- Legacy asset management integration costs:Enterprise resource planning retrofitting for AR telemetry ingestion demands specialized middleware expenditure.
Strategic Opportunities
- Healthcare surgical visualization:FDA premarket notification pathways for AR-guided operative tools create first-mover advantage in United States academic medical centers.
- India manufacturing automation:PLI scheme incentives for electronics and automotive production are unlocking greenfield AR deployment budgets.
- Digital twin convergence:Real-time physics simulation layered with spatial AR instruction enables predictive maintenance in German automotive assembly.
Industry Challenges
- Spatial computing talent scarcity:Computer vision and 3D engine expertise concentrates among gaming industry veterans, forcing cross-sector compensation wars.
- KBA functional safety certification:German automotive assembly verification standards require 18-24 month validation cycles for AR interface modifications.
- Multi-platform content fragmentation:Proprietary authoring tools from competing ecosystems force enterprises into costly parallel development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise AR Software Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $80.81 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Healthcare, Retail, Education, Manufacturing Solution: Training, Maintenance, Marketing, Remote Assistance Technology: Marker-Based, Marker-Less, Projection-Based, Superimposition |
| Companies Covered | Microsoft, PTC, Unity Technologies, Google, Apple, TeamViewer, Scope AR, Librestream Technologies, Magic Leap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise AR Software Market Shifts & Advancements
Spatial computing hardware is shedding weight and power consumption while software stacks consolidate around open interoperability standards, compressing the gap between pilot deployment and scaled production.
Waveguide optical engines are miniaturizing from bulky helmet-mounted systems to eyeglass-compatible form factors. Automotive quality inspectors in Stuttgart and Wolfsburg are piloting 45-gram displays for eight-hour assembly verification shifts. Component miniaturization is eliminating the ergonomic barrier that previously restricted AR to short-duration maintenance tasks.
Germany's KBA functional safety standards for human-machine interfaces are mandating fail-safe visualization protocols in automotive AR applications. Tier-1 suppliers must demonstrate redundancy in spatial overlay systems before production line authorization. European industrial AR vendors are restructuring software architectures to isolate safety-critical rendering paths from general-purpose content layers.
Subscription consumption models are displacing perpetual licensing in manufacturing software procurement. German and Japanese industrial buyers now prioritize SaaS AR platforms with usage-based telemetry pricing over capitalized on-premises installations. Cloud delivery preference is most pronounced among mid-cap automotive suppliers seeking to avoid data center construction.
Enterprise AR Software Market Segmentation
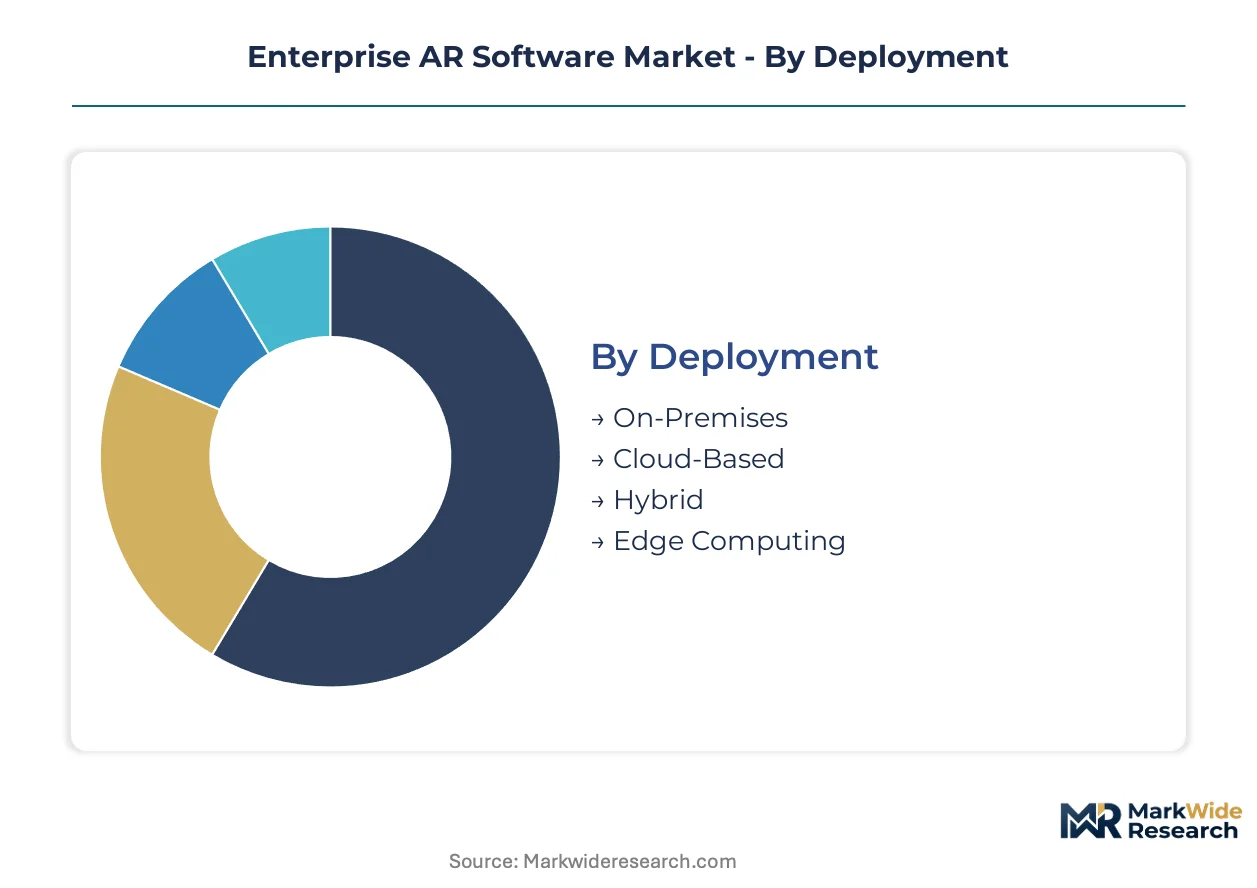
Enterprise AR software segments diverge sharply in margin structure and procurement channel. Cloud delivery routes favor subscription economics, while on-premises installations concentrate in defense and regulated healthcare environments with stringent data sovereignty requirements.
Deployment:
Channel mix splits between capital-intensive perpetual licenses and consumption-based SaaS models with telemetry metering.
- Cloud-Based:Scalable infrastructure eliminates server farm construction for mid-cap manufacturers. German automotive suppliers and Japanese electronics assemblers prioritize this route to compress deployment timelines and shift IT expenditure from CapEx to OpEx.
- Hybrid:Combines cloud orchestration with edge nodes for sub-20 millisecond latency in safety-critical applications. German KBA functional safety mandates for automotive assembly verification drive hybrid adoption where rendering paths must isolate safety-critical layers.
- On-Premises:Defense contractors and FDA-regulated surgical centers mandate air-gapped installations with ISO/IEC 27001-certified data containment.
- Edge Computing:Localized processing for remote field sites with intermittent connectivity; mining and offshore energy operations in Australia and Brazil deploy this architecture.
On-Premises dominates installed base. Cloud-Based is where expansion concentrates.
End User:
Cost tier stratification separates high-margin regulated applications from volume-driven retail deployments.
- Manufacturing:AR-guided assembly and predictive maintenance command premium pricing due to ERP integration complexity and recurring subscription attach rates. Stuttgart and Wolfsburg automotive clusters represent concentrated demand for eight-hour-shift eyewear compatibility.
- Healthcare:FDA premarket notification pathways for surgical visualization create first-mover advantages in United States academic medical centers. EU MDR compliance adds validation overhead for European hospital procurement.
- Retail:Virtual try-on and spatial merchandising operate on thinner margins with volume-based SaaS tiers.
- Education:Institutional procurement cycles and budget constraints favor lower-cost marker-based solutions over enterprise-grade spatial computing platforms.
Manufacturing captures the deepest margin pools. Healthcare is climbing the fastest as regulatory pathways mature.
Solution:
Application maturity determines whether segments command implementation services or pure software licensing.
- Maintenance:Integration with legacy asset management systems requires specialized middleware, creating sticky revenue through multi-year service contracts. German industrial buyers prioritize this category for technician shortage mitigation.
- Remote Assistance:5G latency improvements enable synchronous expert access without geographic relocation. Field service operations in United States utilities and Japanese precision manufacturing deploy this for distributed workforce leverage.
- Training:AR-guided skill transfer compresses onboarding cycles in China and United States manufacturing hubs facing demographic workforce pressure.
- Marketing:Brand activation and product visualization carry shorter sales cycles but lower renewal rates compared to operational solutions.
Maintenance commands the highest lifetime value. Remote Assistance is gaining share fastest as telecommunications infrastructure improves.
Technology:
Supply concentration in optical components creates divergent sourcing strategies across technical approaches.
- Marker-Less:Computer vision and SLAM-based spatial mapping eliminate physical fiducial dependencies. Advanced manufacturing quality inspection in Germany and Japan demands this capability for unconstrained workspace flexibility.
- Superimposition:Real-time 3D model overlay onto physical assets enables predictive maintenance visualization. Automotive digital twin convergence in Stuttgart assembly plants leverages this for physics-synchronized spatial instruction.
- Marker-Based:Lower computational requirements suit cost-constrained education and retail deployments with controlled lighting environments.
- Projection-Based:Shared spatial displays for collaborative assembly tasks; Boeing and Airbus manufacturing facilities pilot this for multi-viewer instruction without individual head-mounted hardware.
Marker-Based retains the largest installed footprint. Marker-Less is where vendor R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial digitization subsidies and workforce modernization mandates are accelerating AR software procurement across concentrated manufacturing clusters. National regulators are embedding functional safety and data sovereignty requirements into deployment protocols, reshaping vendor qualification criteria.
United States
Defense contractors and academic medical centers drive demand for air-gapped on-premises installations with stringent data containment requirements. FDA premarket notification pathways for AR-guided surgical visualization tools establish validation benchmarks that ripple through industrial applications. Detroit automotive clusters and Houston energy operations deploy remote assistance platforms for distributed field service leverage.
Germany
KBA functional safety mandates for automotive assembly verification enforce 18-24 month validation cycles for AR interface modifications. Stuttgart and Wolfsburg manufacturing hubs pilot 45-gram eyewear displays for eight-hour quality inspection shifts. EU AI Act transparency provisions constrain algorithmic decision layers in industrial AR applications, extending compliance timelines.
China
MIIT industrial internet initiatives channel state funding toward smart factory AR deployments in electronics and automotive sectors. Workforce training mandates address technician shortages in Yangtze River Delta manufacturing corridors. Shenzhen and Shanghai industrial parks prioritize marker-less spatial mapping for unconstrained workspace flexibility.
Japan
METI productivity enhancement programs subsidize AR-guided assembly in precision manufacturing and automotive supply chains. JIS standards for human-machine interfaces influence software architecture decisions across domestic vendors. Nagoya and Osaka industrial clusters adopt cloud-edge hybrid models to compress deployment timelines.
India
PLI scheme incentives for electronics and automotive production unlock greenfield AR deployment budgets among contract manufacturers. BIS certification requirements for industrial software procurement reshape vendor selection protocols. Karnataka and Tamil Nadu automotive corridors pilot remote assistance platforms for technician skill transfer.
Enterprise AR Software Market Competitive Landscape
Player mix skews toward cloud-native platform specialists with hybrid architecture capabilities. Market structure concentrates around three tiers: hyperscale cloud providers with edge computing infrastructure, CAD-anchored industrial software incumbents, and remote assistance connectivity specialists. Competitive positioning hardens through M&A activity targeting spatial computing talent pools and strategic partnerships with telecommunications carriers for 5G latency guarantees.
Within the cloud-platform tier, Microsoft exemplifies hybrid architecture deployment across manufacturing and healthcare accounts. PTC occupies a position among CAD-anchored authoring tool specialists serving factory-floor maintenance workflows. TeamViewer represents the remote assistance connectivity archetype bridging field technicians with centralized expertise pools.
| Leading Market Players |
|---|
| Microsoft |
| PTC |
| Unity Technologies |
| Apple |
| TeamViewer |
| Scope AR |
| Librestream Technologies |
| Magic Leap |
| Others |
Supply & Pricing Matrix
ISO/IEC 27001 certification gates both vendor qualification and price stratification in enterprise AR software, forcing buyers to pay premiums for audited data containment while suppliers absorb compliance overhead to access regulated manufacturing accounts in Germany and the United States.
Pricing Analysis
Certification level creates the primary spread between ISO/IEC 27001-audited SaaS tiers and uncertified alternatives. Pricing stratifies across premium, standard, and economy tiers based on ERP integration complexity and after-sales service bundling. Cost compression in the mid-market tier is intensifying because Japanese and German automotive suppliers demand usage-based telemetry pricing without perpetual license commitments. Small-to-mid contract manufacturers in India exhibit the highest price sensitivity, while FDA-regulated surgical centers in the United States accept substantial premiums for air-gapped on-premises installations.
Supply Chain Analysis
Just-in-time procurement dominates optical component sourcing for waveguide and micro-display assemblies, though Tier-1 AR hardware vendors maintain strategic stockpiles of East Asian-sourced MEMS chips to buffer against single-source vulnerability. Supply concentrates in Taiwan, South Korea, and Japan for display engines, with China controlling rare-earth magnet feeds for head-mounted actuator systems. Distribution runs through hyperscale cloud provider marketplaces and direct enterprise sales teams serving Stuttgart and Detroit manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spatial computing talent scarcity—particularly computer vision engineers and 3D engine specialists—constrains platform development velocity and inflates compensation costs across vendor ecosystems, compressing margins for pure-play software specialists.
For Market Incumbents: Fortify hybrid architecture roadmaps with edge-node redundancy to satisfy German KBA functional safety mandates while locking in multi-year SaaS commitments from mid-cap automotive suppliers. Acquire specialist computer vision teams to defend against hyperscaler talent raids, and accelerate ISO/IEC 27001 certification across all product tiers to preempt compliance-driven procurement disqualification.
For New Entrants and Emerging Players: Lead with marker-less spatial mapping solutions targeting greenfield electronics manufacturers in India under PLI scheme incentives, where legacy ERP integration burdens are minimal and procurement protocols favor innovation over incumbent relationships. Position remote assistance platforms for Brazilian and Australian mining operations with intermittent connectivity, leveraging edge-computing architectures that established vendors have neglected.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native AR platforms as SaaS delivery displaces on-premises infrastructure, improving cash conversion cycles and reducing customer acquisition payback periods. Target acquisition archetypes include CAD-anchored authoring tool specialists with sticky factory-floor maintenance workflows and remote assistance connectivity layers with 5G carrier partnerships. Watch 5G network latency threshold improvements in industrial corridors as the signal for synchronous collaboration adoption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP-anchored AR authoring tools from PTC deepen factory-floor workflow stickiness in Stuttgart automotive clusters. |
| Strategic Partnership | 5G latency guarantees from Deutsche Telekom and Verizon enable synchronous remote assistance previously impossible over 4G. |
| Acquisition of Specialist Firm | Computer vision talent pools in gaming industry veterans compress development timelines for marker-less spatial mapping. |
| Geographic Expansion | PLI scheme incentives in Karnataka and Tamil Nadu unlock greenfield deployment budgets among Indian contract manufacturers. |
| Product Launch | FDA premarket notification pathways for surgical visualization create first-mover advantage in United States academic medical centers. |
Research Methodology
Operator-level perspectives from plant engineers, IT procurement officers, platform integration specialists, and maintenance directors anchored the qualitative base for this analysis. Primary interviews with German automotive quality inspectors, Japanese precision manufacturing technicians, and United States hospital biomedical engineers combined with secondary validation from SEC filings of hyperscale cloud providers, hyperscaler capex disclosures, 5G infrastructure deployment databases, and FDA premarket notification records. Bottom-up segment sizing triangulated against top-down industrial digitization budget estimates across the analysis window.
Sensitivity analysis tested forecast robustness across deployment model adoption curves, 5G network latency improvement trajectories, and regulatory validation timeline extensions. The analytical framework modeled segmentation across deployment architecture, end-user vertical, solution category, and technology approach throughout the forecast period. CAGRs derived from installation base growth rates, subscription attach rate expansion, and cloud consumption elasticity parameters, with cross-validation against industrial software spending patterns and telecommunications infrastructure investment cycles.
Underlying assumptions cover sustained 5G latency threshold improvements, stable ISO/IEC 27001 audit capacity, and continued PLI scheme funding in India, with deviation risk concentrated in optical component supply disruptions and EU AI Act enforcement intensity. Revision becomes warranted when 5G millisecond latency guarantees fail to materialize in targeted industrial corridors or when KBA validation timelines extend beyond current baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Telepresence Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market