
 Omni Channel Messaging Software Market | 2026-2036
Omni Channel Messaging Software Market Size, Share, and Industry Trends Forecast 2026-2036
Omni Channel Messaging Software Market Analytics
Developer talent scarcity in conversational AI and real-time message orchestration is bifurcating the competitive landscape into well-capitalized platform builders and narrow-point solution vendors. Twilio leverages its communications API infrastructure to anchor enterprise-grade messaging pipelines. Salesforce sustains dominance through native CRM integration that locks customer data gravity into its messaging layer. HubSpot competes by bundling messaging automation with inbound marketing workflows for mid-market SaaS buyers.
Omni channel messaging software unifies outbound and inbound customer communications across SMS, email, push notifications, WhatsApp, and live chat through a single orchestration layer with message sequencing logic and channel preference routing. The system processes delivery receipts, read confirmations, and response latency under 200 milliseconds to maintain conversation continuity across asynchronous channels. Cloud-based deployment leads structural adoption because elastic infrastructure absorbs traffic spikes from seasonal campaigns without capital commitment. AI-driven technology segments capture expanding margin pools as natural language processing enables automated sentiment triage and response generation. API-centric architectures dominate developer-led procurement, while web-based interfaces retain strength among marketing operations teams lacking dedicated engineering resources.
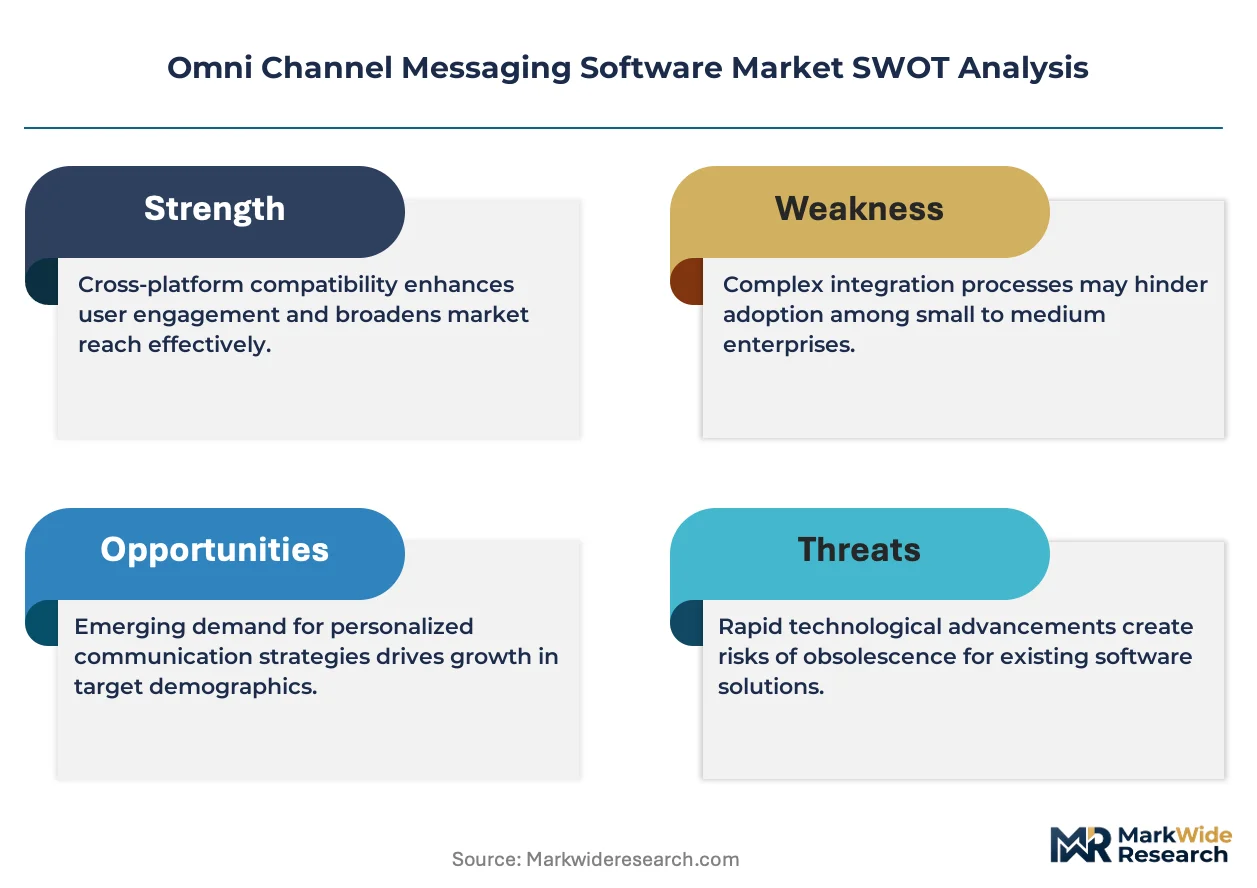
The EU AI Act, GDPR, and HIPAA constrain how vendors process message content containing personal health information or automated decision logic. The Federal Communications Commission's TCPA enforcement in the United States imposes per-violation penalties that shape product design around explicit opt-in capture and consent timestamping. Stakeholders must monitor regulatory divergence between European algorithmic transparency mandates and American sector-specific privacy fragmentation.
Market Dynamics
Enterprise demand for sub-200 millisecond message orchestration latency is compressing vendor margins and forcing infrastructure consolidation around edge-computing deployments. Real-time sentiment analysis pipelines now require GPU clusters co-located with carrier gateways, reshaping how platform economics scale across traffic spikes.
Growth Catalysts
- GDPR Article 7 Consent Frameworks:European retailers must maintain auditable opt-in trails across every touchpoint, creating mandatory procurement of timestamped consent management layers.
- Conversational AI Talent Scarcity:The shortage of engineers skilled in transformer-based response generation is concentrating procurement decisions toward API-first platforms with pre-trained models.
- Healthcare Patient Engagement Mandates:HIPAA-covered entities in the United States require encrypted asynchronous messaging for appointment adherence, expanding compliant channel orchestration budgets.
Market Restraints
- Cloud Infrastructure Cost Volatility:GPU instance pricing from hyperscale providers fluctuates 40% seasonally, eroding margin predictability for AI-powered response generation features.
- Carrier Gateway Concentration:SMS termination routes through three dominant aggregator networks create single-point-of-failure exposure for time-critical transactional messaging.
- TCPA Per-Violation Penalties:The FCC's $1,500 statutory damages per unauthorized message force conservative opt-in flows that suppress conversion rates in high-velocity sales campaigns.
Strategic Opportunities
- India's Unified Payments Interface Integration:Messaging platforms embedding UPI payment confirmations capture transaction fee revenue streams from merchant onboarding in the world's fastest-growing digital payments market.
- EU AI Act Explainability Mandates:Automated message routing decisions must expose decision logic to auditors, creating premium pricing tiers for interpretable AI pipeline architectures.
- 5G Rich Communication Services:The convergence of carrier-native RCS with existing WhatsApp Business API channels enables branded interactive messaging without third-party app dependency.
Industry Challenges
- Legacy CRM Data Migration Complexity:Enterprises running on-premise Siebel or SAP systems face 18-24 month integration timelines to unify customer identity graphs with cloud messaging layers.
- Real-Time NLP Model Drift:Sarcasm detection accuracy degrades 15% quarterly without continuous retraining, requiring dedicated MLOps headcount that mid-market buyers cannot sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omni Channel Messaging Software Market |
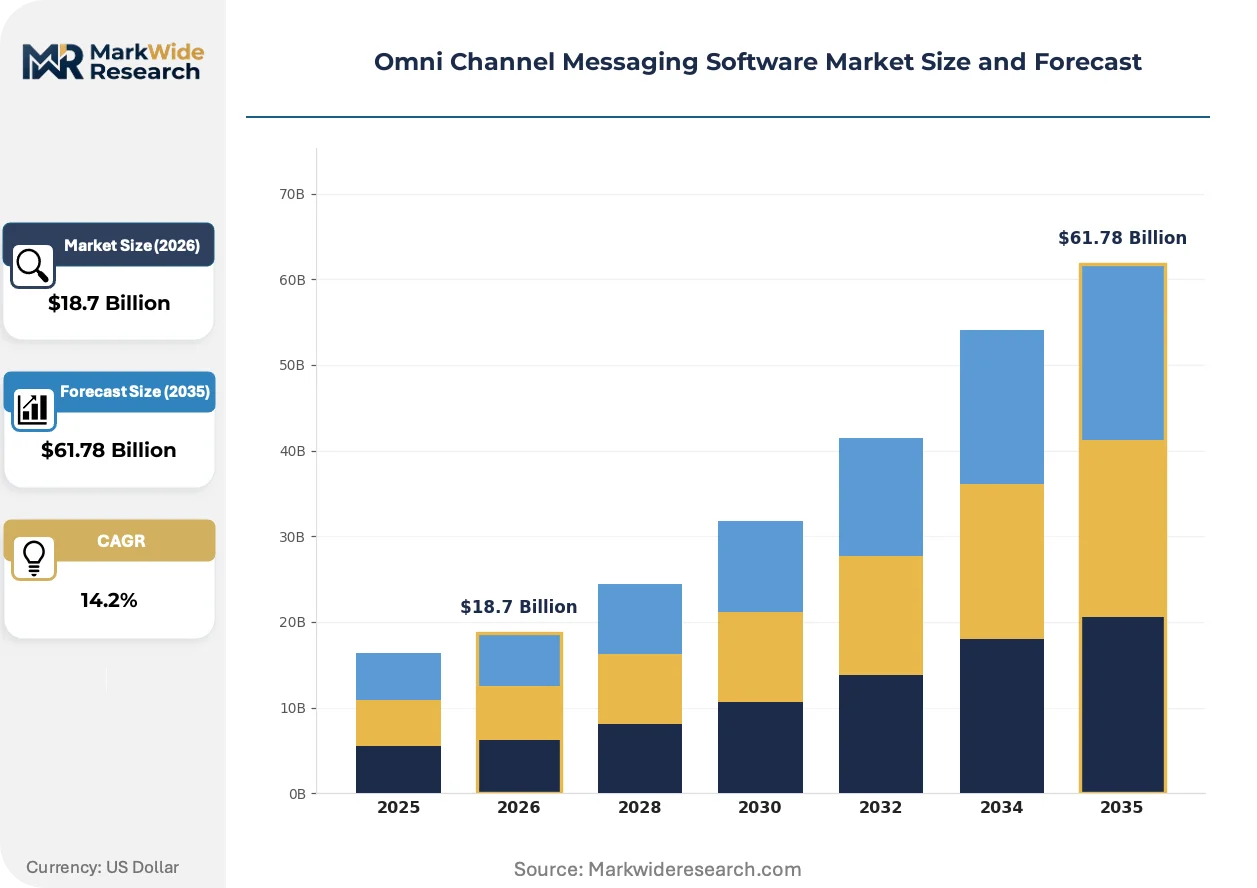
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Multi-tenant Customer Type: Enterprise, SMEs, Startups, Public Sector Technology: AI-driven, Web-based, Mobile-enabled, API-centric Use Case: Customer Support, Marketing Automation, Sales Engagement, Feedback Collection |
| Companies Covered | Insider One, Klaviyo, HubSpot, Twilio, Infobip, Salesforce, ActiveCampaign, Freshworks, Adobe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omni Channel Messaging Software Market Evolving Landscape
Edge-deployed inference engines are displacing centralized cloud processing for latency-sensitive message routing decisions. This architectural shift compresses infrastructure costs while enabling compliance with data residency requirements that prohibit cross-border content analysis.
Transformer-based response generation is miniaturizing. Lightweight fine-tuned models running on commodity CPU clusters now match cloud API quality for routine customer service queries. Mid-market SaaS vendors in Germany and the Netherlands are adopting these compressed architectures to avoid per-token inference fees from hyperscale providers. The technology is miniaturizing the economic barrier between enterprise-grade automation and budget-constrained implementations.
The EU AI Act's risk classification system for automated decision-making is forcing architectural redesigns of message prioritization engines. High-risk deployments involving credit or health content must maintain human-in-the-loop override capabilities. Financial services messaging workflows across France, Italy, and Spain are most affected, with banks rebuilding routing logic to expose algorithmic weights for regulatory inspection.
Subscription-based platform pricing is displacing usage-based SMS volume billing among enterprise procurement teams. Chief marketing officers in the United States and United Kingdom now demand predictable annual costs regardless of seasonal campaign intensity. This preference shift compresses revenue visibility for vendors historically dependent on Black Friday and holiday traffic spikes for annual margin targets.
Omni Channel Messaging Software Market Segmentation
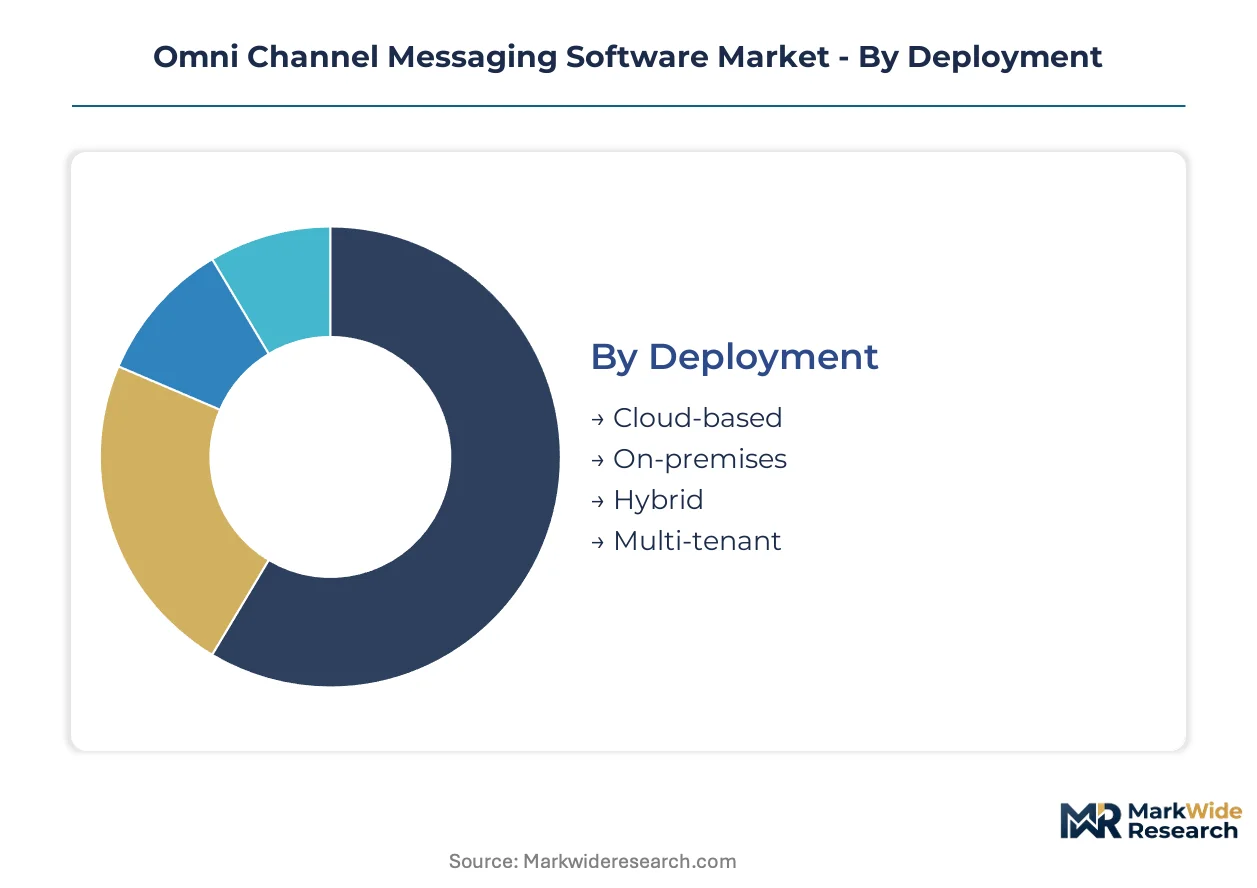
Segmentation in omni channel messaging software reveals how procurement priorities diverge across infrastructure maturity, compliance burden, and technical staffing levels. Buyers select deployment modes and technology stacks based on regulatory jurisdiction, data residency mandates, and in-house engineering capacity.
Deployment:
GDPR Article 44 cross-border transfer restrictions and HIPAA encryption requirements create divergent infrastructure procurement patterns across European healthcare networks and American financial services.
- Cloud-based:Elastic compute pools absorb Black Friday traffic spikes without capital commitment. German retailers and Dutch logistics operators favor EU-sovereign cloud instances to satisfy GDPR data localization mandates while maintaining sub-200 millisecond latency.
- On-premises:Air-gapped installations serve HIPAA-covered hospital systems in Texas and Illinois requiring encrypted message archives on controlled hardware. Capital expenditure thresholds and 24-month depreciation cycles limit adoption to organizations exceeding 10,000 employees.
- Hybrid:Split architectures route PII through on-site gateways while pushing anonymized analytics to public cloud. French banks deploy this model to satisfy CNIL audit requirements for algorithmic decision transparency.
- Multi-tenant:Shared infrastructure partitions tenant data through containerized isolation. Indian fintech startups leverage multi-tenant deployments to achieve TRAI compliance cost structures without dedicated DevOps headcount.
Established volume favors Cloud-based; emerging adoption favors Hybrid.
Customer Type:
Procurement scale determines whether buyers prioritize API flexibility or pre-configured workflow templates.
- Enterprise:Fortune 500 manufacturers in Michigan and Ohio demand custom SLA terms, dedicated account engineering, and ISO 27001 certification documentation. Annual contract values support vendor investment in bespoke integration layers for SAP and Oracle systems.
- SMEs:Mid-market SaaS vendors in North Carolina and Colorado select bundled platforms combining messaging automation with CRM and email marketing. Subscription pricing caps below $50,000 annually constrain customization scope.
- Startups:Venture-backed companies in Bangalore and São Paulo prioritize per-message pricing with no minimum commitments. Rapid scaling requirements favor serverless architectures over provisioned capacity.
- Public Sector:Municipal governments in California and federal agencies in Virginia mandate FedRAMP authorization and FedRAMP-equivalent state-level certifications. Procurement cycles extend 18-36 months through RFP processes.
Revenue concentration sits with Enterprise; steepest expansion trajectory belongs to Startups.
Technology:
Engineering talent availability shapes whether buyers build on pre-trained models or configure no-code interfaces.
- AI-driven:Transformer-based sentiment analysis and response generation require GPU clusters and MLOps specialization. Healthcare providers in Massachusetts and Pennsylvania deploy these systems for patient triage automation under FDA software-as-medical-device guidance.
- Web-based:Browser-accessible dashboards serve marketing operations teams without dedicated developers. British ecommerce retailers and Australian hospitality chains favor drag-and-drop campaign builders.
- Mobile-enabled:Native iOS and Android SDKs support field service technicians and delivery coordinators. Logistics operators in Singapore and Dubai prioritize offline message queuing for connectivity gaps.
- API-centric:REST and GraphQL endpoints enable developer-led integration into existing tech stacks. Technology companies in Stockholm and Tel Aviv embed messaging into proprietary applications.
Margin pools concentrate in AI-driven; deployment velocity favors API-centric.
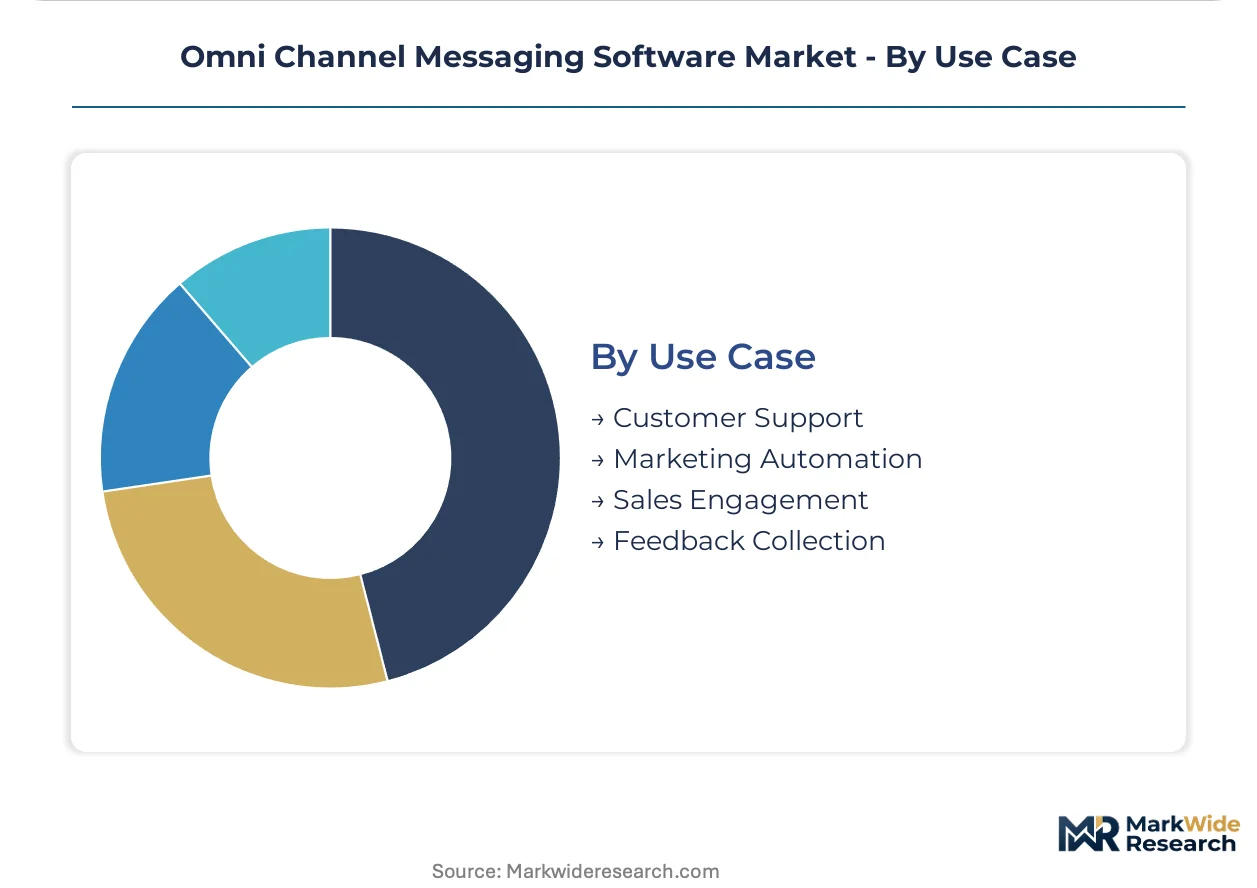
Use Case:
Functional application determines channel mix, latency tolerance, and compliance architecture.
- Customer Support:Conversational AI handles routine queries while human agents manage escalations. Telecom operators in Spain and Italy maintain 24/7 Spanish and Italian language coverage through hybrid automation.
- Marketing Automation:Cross-channel sequencing coordinates SMS, email, and push notifications around purchase journeys. Retail brands in the United Kingdom face strict GDPR consent validation for promotional messaging.
- Sales Engagement:Real-time lead routing and cadence management integrate with Salesforce and HubSpot. TCPA compliance constraints in the United States suppress cold outreach conversion rates.
- Feedback Collection:Post-interaction surveys trigger through WhatsApp Business API and RCS. Hospitality groups in Thailand and Indonesia capture guest satisfaction metrics within 30 minutes of checkout.
Budget allocation tilts toward Customer Support; innovation investment flows to Marketing Automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC enforcement of TCPA statutes in the United States shapes product architecture across the industry, while GDPR Article 44 and the EU AI Act force divergent compliance investments in European markets. National procurement patterns reflect cloud infrastructure maturity, carrier gateway density, and regulatory fragmentation.
United States
Enterprise SaaS procurement and venture capital availability drive platform consolidation. FCC TCPA penalties reaching $1,500 per unauthorized message force conservative opt-in flows. Michigan and Ohio manufacturers demand custom SLA terms and dedicated account engineering for SAP integration.
Germany
GDPR data localization mandates and EU AI Act algorithmic transparency requirements dominate vendor selection. Retailers in Berlin and Hamburg favor EU-sovereign cloud instances with sub-200 millisecond latency. The country's national data protection authority enforces strict cross-border transfer protocols.
India
Unified Payments Interface integration creates transaction fee revenue opportunities for messaging platforms. TRAI compliance structures shape cost-efficient multi-tenant deployments. Bangalore and São Paulo venture-backed startups prioritize per-message pricing with serverless architectures.
United Kingdom
Cross-channel marketing automation budgets concentrate in London and Southeast retail clusters. GDPR consent validation requirements suppress promotional messaging conversion rates. British ecommerce operators favor web-based drag-and-drop campaign builders over API-centric solutions.
France
CNIL audit requirements for algorithmic decision transparency drive hybrid deployment adoption. Banks in Paris and Lyon rebuild message routing logic to expose decision weights. Financial services messaging workflows face mandatory human-in-the-loop override capabilities.
Omni Channel Messaging Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the vendor landscape. Well-capitalized platform builders with communications API infrastructure anchor enterprise-grade pipelines, while narrow-point solution vendors compete on bundled pricing for mid-market buyers. The market structure reveals three strategic archetypes: API-first infrastructure providers, CRM-native messaging layers, and marketing automation bundlers. Dominant competitive moves include M&A to capture conversational AI talent and strategic partnerships to embed payment confirmations into messaging flows.
Within the API-first infrastructure tier, Twilio and Infobip occupy positions as scale-driven platform builders with global carrier gateway relationships. Salesforce and HubSpot exemplify the CRM-native archetype, leveraging customer data gravity to lock messaging layers into broader enterprise software ecosystems. Adobe represents the marketing automation bundler position, competing through workflow integration rather than standalone messaging infrastructure.
| Leading Market Players |
|---|
| Insider One |
| Klaviyo |
| HubSpot |
| Twilio |
| Infobip |
| Salesforce |
| ActiveCampaign |
| Freshworks |
| Adobe |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with hyperscale cloud providers lock in GPU cluster access and flatten seasonal cost volatility for AI-powered response generation features. European healthcare networks and American financial services buyers negotiate these arrangements to secure sub-200 millisecond latency guarantees while insulating against spot-market price swings in compute infrastructure.
Pricing Analysis
Annual contract spreads between German EU-sovereign cloud deployments and American standard-tier instances reflect data residency premium capture. Subscription-based SaaS pricing now dominates enterprise procurement, displacing per-message SMS volume billing as chief marketing officers demand predictable costs regardless of seasonal campaign intensity. Price differentiation hinges on GDPR Article 44 compliance certification and dedicated account engineering availability. Mid-market SaaS vendors in North Carolina and Colorado exhibit highest price sensitivity due to subscription caps below fifty thousand dollars annually, while Fortune 500 manufacturers in Michigan and Ohio absorb premium tiers for custom SLA terms.
Supply Chain Analysis
Container availability constraints across Pacific trade lanes elevate inbound logistics costs for GPU hardware destined to European edge-computing deployments. Taiwan, South Korea, and the United States concentrate advanced semiconductor fabrication for NLP inference accelerators. Taiwan Semiconductor Manufacturing Company and Samsung Foundry output feeds transformer-based model training pipelines. Single-source vulnerability around NVIDIA GPU allocation creates procurement risk for vendors scaling sentiment analysis infrastructure. Distribution runs through direct hyperscale partnerships and regional systems integrators with carrier gateway relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Fortune 500 procurement teams with dedicated cloud infrastructure engineering, fragmenting pricing leverage across mid-market vendors unable to negotiate volume commitments. This consolidation forces platform providers toward tiered service architectures.
For Market Incumbents: Consolidate conversational AI talent through targeted acquisition of transformer-based response generation specialists in Tel Aviv and Stockholm. Lock SAP and Oracle integration layers through dedicated account engineering investments in Michigan and Ohio manufacturing corridors. Defend against API-first challengers by embedding payment confirmation workflows into proprietary messaging pipelines, capturing transaction fee revenue streams from merchant onboarding. For New Entrants and Emerging Players: Lead with lightweight fine-tuned models running on commodity CPU clusters to undercut hyperscale inference fees for mid-market SaaS buyers in Germany and the Netherlands. Target India's Unified Payments Interface integration white space where TRAI compliance structures favor cost-efficient multi-tenant deployments. Pursue serverless architecture positioning with per-message pricing and no minimum commitments for venture-backed startups in Bangalore. For Investors and Strategic Acquirers: Capital is best deployed toward narrow-point solution vendors with pre-trained conversational AI models and established carrier gateway relationships in underserved geographies. Long-term viability favors platforms embedding interpretable AI pipeline architectures to capture EU AI Act explainability mandate premiums. Watch for inflection signals around 5G Rich Communication Services carrier adoption rates in France, Italy, and Spain.| Strategic Initiative | Industry Significance |
|---|---|
| Conversational AI Talent Acquisition | Transformer-based response generation specialists in Tel Aviv and Stockholm command premium valuations due to scarcity. |
| EU-Sovereign Cloud Deployment | GDPR Article 44 data localization mandates in Germany and France require EU-resident infrastructure investment. |
| UPI Payment Integration | Unified Payments Interface embedding in India captures transaction fee revenue from merchant onboarding workflows. |
| 5G RCS Channel Expansion | Rich Communication Services convergence with WhatsApp Business API reduces third-party app dependency for branded messaging. |
| Edge Computing Infrastructure | GPU clusters co-located with carrier gateways compress sub-200 millisecond latency for real-time sentiment triage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief technology officers, IT procurement officers, platform engineers, and channel partners at enterprise SaaS vendors, healthcare systems, and financial services institutions. Secondary validation drew from SEC filings, hyperscaler capex disclosures, carrier gateway tariff schedules, and GDPR enforcement action databases. Bottom-up deployment model analysis triangulated against top-down market sizing across cloud infrastructure spend categories.
Across the analysis window, projections incorporate deployment mode segmentation by cloud-based, on-premises, hybrid, and multi-tenant architectures; customer type tiering across enterprise, SME, startup, and public sector buyers; and technology stack differentiation between AI-driven, web-based, mobile-enabled, and API-centric platforms. CAGRs were derived from elasticity modeling of seasonal campaign traffic spikes and compliance-driven procurement acceleration. Industry-specific inputs include GPU instance pricing volatility curves and TCPA enforcement action frequency trends.
Forecasts assume regulatory continuity in FCC TCPA enforcement, GDPR Article 7 consent frameworks, and EU AI Act risk classification implementation; material policy shifts would require re-modeling of opt-in flow conversion rates and algorithmic transparency investment levels. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
Unified Communication Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Business Cloud Voip and UC Services Market
Unified Communications
High Definition HD Voice Market
Unified Communications
Unified Monitoring Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
Ucaas in Banking Market
Unified Communications
Ucaas in the Manufacturing Market
Unified Communications
United States SMS and MMS Market