
 United States SMS and MMS Market | 2026-2036
United States SMS and MMS Market Size, Share, and Industry Trends Forecast 2026-2036
United States SMS and MMS Market Analytics
The United States SMS and MMS landscape is pivoting on a widening gap between premium authenticated messaging tiers and commodity bulk channels that lack delivery guarantees or compliance tooling. Twilio leverages its programmable communications infrastructure to anchor enterprise-grade API workflows across major verticals. Sinch competes through direct carrier relationships that sustain higher throughput rates for transactional traffic. Bandwidth differentiates by controlling its own IP voice and messaging network, which positions it favorably for regulated industries requiring audit trails.
SMS and MMS constitute text-based mobile messaging protocols where SMS delivers up to 160 characters of plain text per message while MMS extends capacity to roughly 1,600 characters plus embedded multimedia, operating over cellular signaling channels and IP data bearers for commercial customer communication. Cloud-based deployment dominates structural investment as enterprises abandon on-premises messaging gateways in favor of elastic infrastructure that scales with campaign volume. A2P messaging captures the deepest margin pools because application-to-person traffic commands per-message premiums and carries stricter authentication requirements than person-to-person flows. Transactional messages lead volume share among service types due to their utility in banking alerts and two-factor authentication, though promotional messages face compression from opt-in consent enforcement.
The FCC governs sender identity and anti-spam enforcement through TCPA rules and STIR/SHAKEN call authentication extensions that increasingly apply to messaging ecosystems, while HIPAA constrains how healthcare entities deploy SMS for patient communication by mandating encryption and access controls. The CTIA publishes messaging best practices that carriers enforce through tiered filtering, effectively creating market access barriers for non-compliant senders. Stakeholders must monitor whether the FCC expands robotext rules to mandate explicit opt-in documentation, as this would force infrastructure upgrades across the entire vendor base.
Market Dynamics
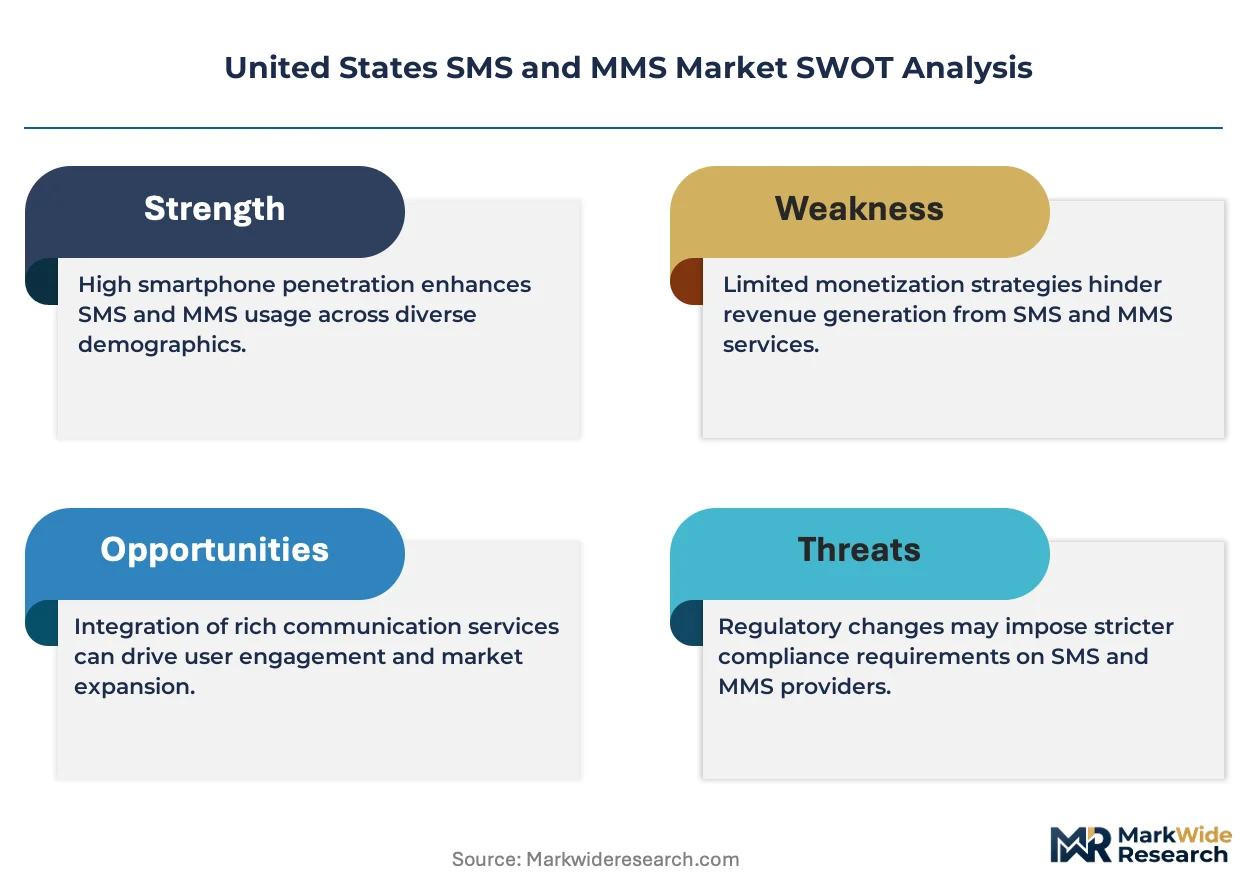
The United States SMS and MMS market is being fundamentally restructured by the FCC's STIR/SHAKEN framework extending into messaging authentication, which is bifurcating the vendor landscape between verified premium tiers and unauthenticated bulk channels that face escalating carrier filtering.
Growth Catalysts
- Healthcare automation:Enterprise hospital systems are deploying automated appointment workflows via SMS to reduce no-show rates and streamline patient engagement across multi-facility networks.
- FCC sender verification mandates:The STIR/SHAKEN framework is creating compliance-driven demand for authenticated messaging infrastructure that commands premium pricing from regulated senders.
- California and New York corridor concentration:Technology and financial services clusters in these metropolitan areas are generating disproportionate transactional message volume for two-factor authentication and fraud alerts.
Market Restraints
- Carrier tiered filtering economics:Major wireless carriers impose throughput penalties and delivery uncertainty on non-compliant senders, raising effective costs for commodity A2P traffic.
- Input cost volatility in IP transit:Messaging API providers face margin pressure from fluctuating data bearer costs and interconnection fees with tier-one mobile network operators.
- Substitution by encrypted messaging apps:WhatsApp Business and Apple Business Chat are capturing promotional and customer service traffic that previously flowed through SMS/MMS channels.
Strategic Opportunities
- HIPAA-compliant healthcare messaging:The HIPAA encryption mandate is opening specialized infrastructure contracts for vendors that can demonstrate audit trails and access controls for patient communications.
- Rich Communication Services convergence:RCS Business Messaging is converging with carrier networks to enable verified branded interactions with multimedia capabilities that surpass SMS limitations.
- Midwestern healthcare system expansion:Underserved hospital networks in Ohio, Michigan, and Illinois present whitespace for automated patient engagement deployments.
Industry Challenges
- TCPA opt-in documentation complexity:Evolving consent requirements demand costly infrastructure upgrades for explicit opt-in capture and retention across multi-touchpoint customer journeys.
- Legacy system integration friction:Enterprise IT departments struggle to embed modern messaging APIs into decades-old patient management and core banking platforms without workflow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States SMS and MMS Market |
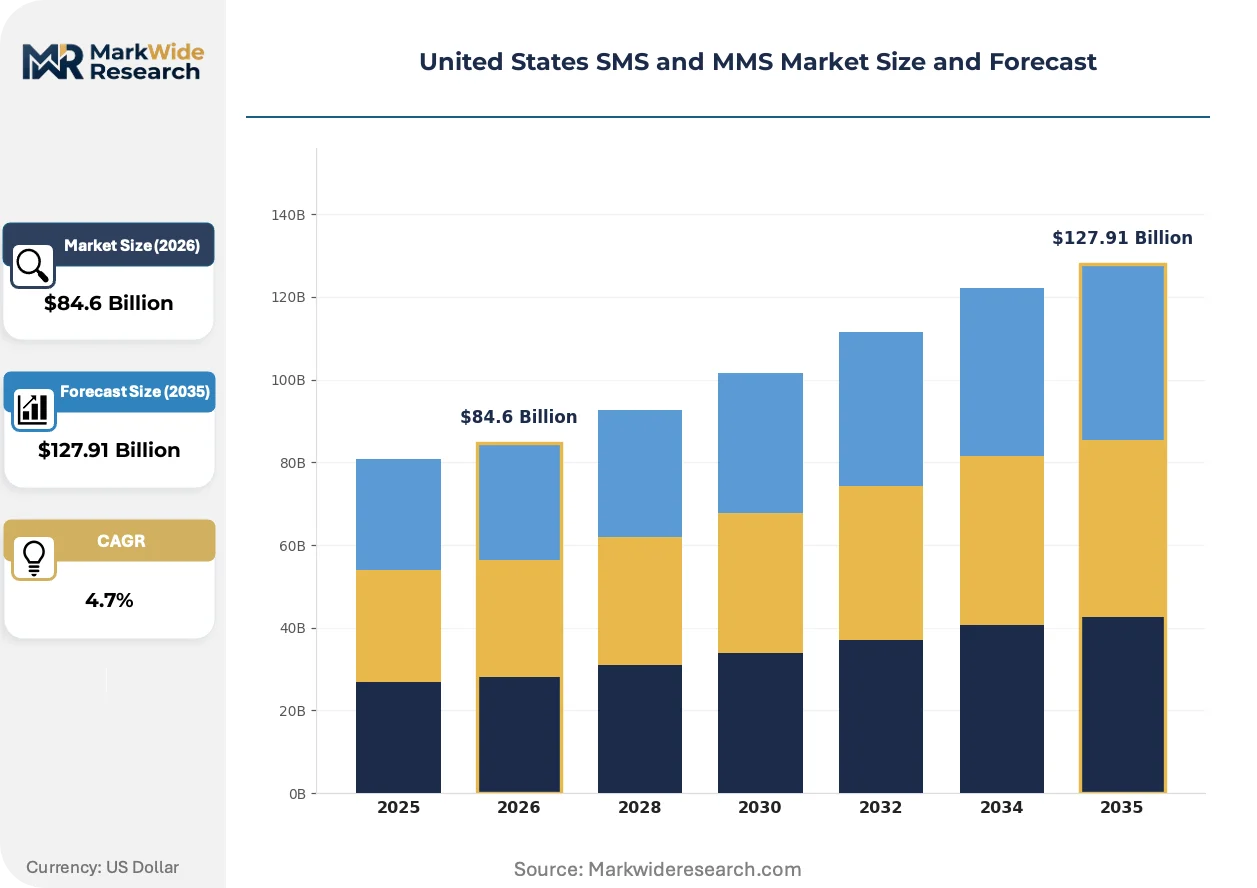
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $127.91 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Promotional Messages, Transactional Messages, OTP Services, Alerts End User: BFSI, E-commerce, Healthcare, Retail Technology: Cloud-Based, On-Premises, API Integration, A2P Messaging Application: Customer Engagement, Marketing Campaigns, Notifications, Feedback Collection |
| Companies Covered | Vonage, Infobip, Twilio, Attentive, ActiveCampaign, Sinch, Telnyx, MessageBird, Bandwidth, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States SMS and MMS Market Evolving Landscape
Artificial intelligence and machine learning are reshaping message routing optimization and spam detection, while carrier-native rich messaging protocols threaten to displace traditional SMS for high-value customer interactions.
Conversational AI is converging with programmable messaging infrastructure to enable dynamic two-way interactions that escalate beyond static alerts. Retail banks and insurance carriers are deploying these systems for claims processing and payment reminders. The technology is converging with existing CRM platforms to compress implementation timelines from months to weeks.
The FCC's robotext rulemaking proceedings are tightening consent documentation requirements for commercial messaging. This regulatory pressure is forcing infrastructure vendors to build explicit opt-in capture systems with timestamp verification. Healthcare and financial services verticals are responding fastest due to overlapping HIPAA and TCPA compliance obligations.
Enterprise procurement of messaging services is consolidating around outcome-based contracts tied to verified delivery rates rather than raw message volume. Marketing technology departments are displacing traditional IT-led vendor selection with direct platform relationships. This shift is most visible in California's technology corridor where agile deployment cycles dominate vendor evaluation criteria.
United States SMS and MMS Market Segmentation
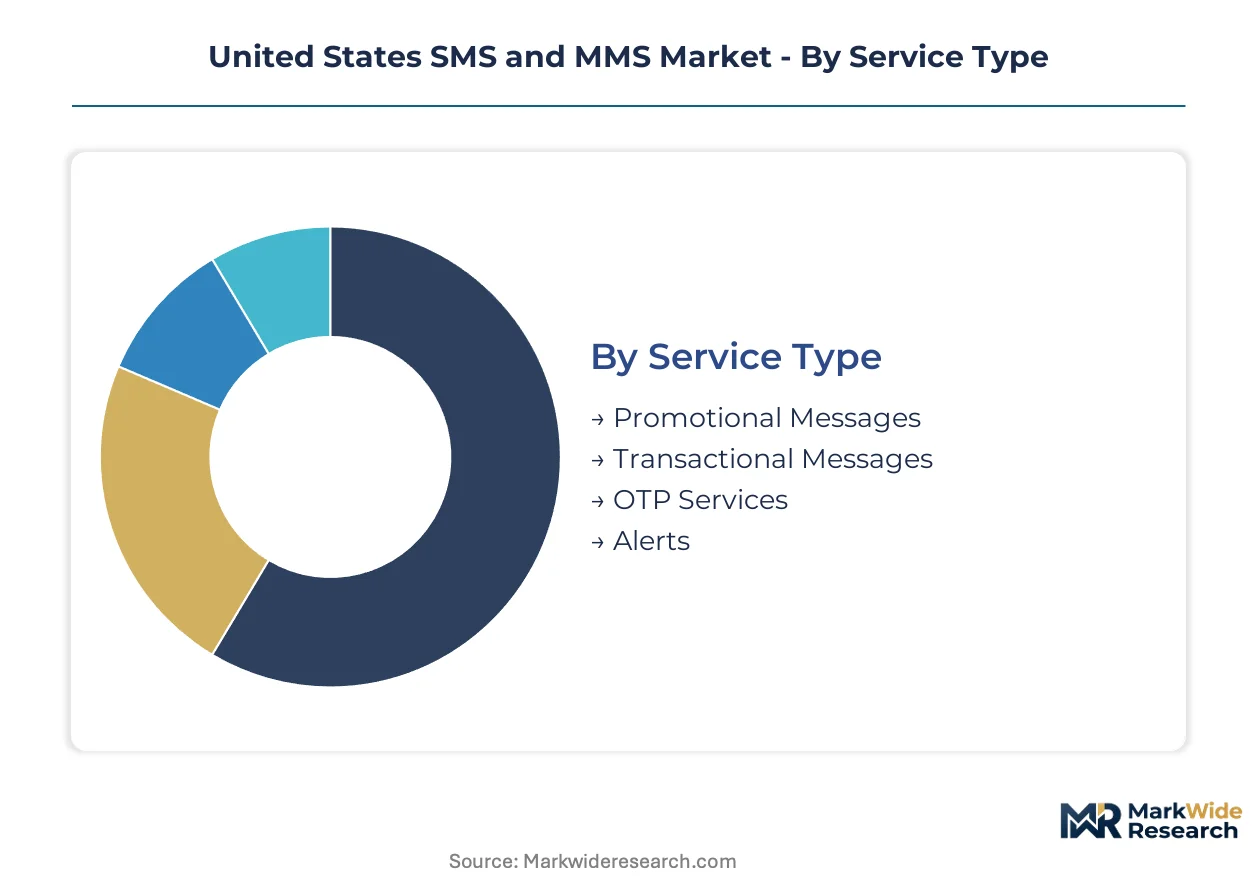
Segmentation in the United States SMS and MMS market reveals how infrastructure investments, regulatory exposure, and customer engagement intensity vary across service tiers and deployment models. Understanding these divisions helps vendors align pricing architecture with delivery guarantees and compliance tooling.
Service Type:
Capital intensity escalates sharply with message authentication requirements, separating premium verified tiers from commodity bulk channels that face carrier filtering penalties.
- Transactional Messages:Banking alerts, payment confirmations, and shipping notifications require guaranteed delivery SLAs and STIR/SHAKEN-compliant authentication infrastructure. Demand concentrates in California's fintech corridor and New York's financial hub where two-factor authentication volumes drive API consumption.
- OTP Services:Time-sensitive one-time password flows mandate sub-second latency and carrier-grade throughput agreements. Healthcare systems in Texas and Florida are expanding automated patient verification workflows, tightening infrastructure requirements for latency-sensitive routing.
- Promotional Messages:Marketing broadcasts face escalating TCPA consent documentation burdens and carrier throttling.
- Alerts:Emergency and service disruption notifications require government-grade reliability tiers with failover redundancy.
Transactional messages absorb the bulk of installed capacity; OTP services are expanding most quickly.
End User:
Compliance overhead varies dramatically by vertical, with HIPAA and TCPA obligations creating specialized infrastructure requirements that reshape vendor selection criteria.
- Healthcare:Hospital systems deploy automated appointment workflows and patient engagement platforms under HIPAA encryption mandates. Midwestern networks in Ohio and Michigan represent whitespace for infrastructure expansion as systems modernize legacy patient management platforms.
- BFSI:Retail banks and insurance carriers drive dense transactional volume for fraud alerts and claims processing. The vertical demands audit trails and STIR/SHAKEN verification that command premium API pricing.
- E-commerce:Order confirmations and delivery notifications prioritize cost-efficient throughput over authentication depth.
- Retail:Promotional campaigns face compression from opt-in consent enforcement and substitution by Apple Business Chat.
BFSI dominates current infrastructure deployment; healthcare is climbing the fastest as hospital networks automate patient touchpoints.
Technology:
Deployment architecture determines scalability economics and regulatory auditability, with cloud migration accelerating as enterprises abandon fixed-capacity gateway investments.
- Cloud-Based:Elastic infrastructure scales with campaign volume and integrates conversational AI for dynamic two-way interactions. California technology corridor enterprises favor consumption-based pricing tied to verified delivery rates rather than raw message commits.
- A2P Messaging:Application-to-person flows command per-message premiums and stricter authentication requirements than P2P traffic. The segment captures the deepest margin pools as carriers impose tiered filtering on non-compliant senders.
- API Integration:Programmable interfaces compress implementation timelines from months to weeks when converged with existing CRM platforms.
- On-Premises:Legacy gateway installations persist in regulated entities requiring physical data sovereignty controls.
Cloud-based deployment holds the majority of new investment; A2P messaging is gaining share fastest as carriers bifurcate verified and unauthenticated tiers.
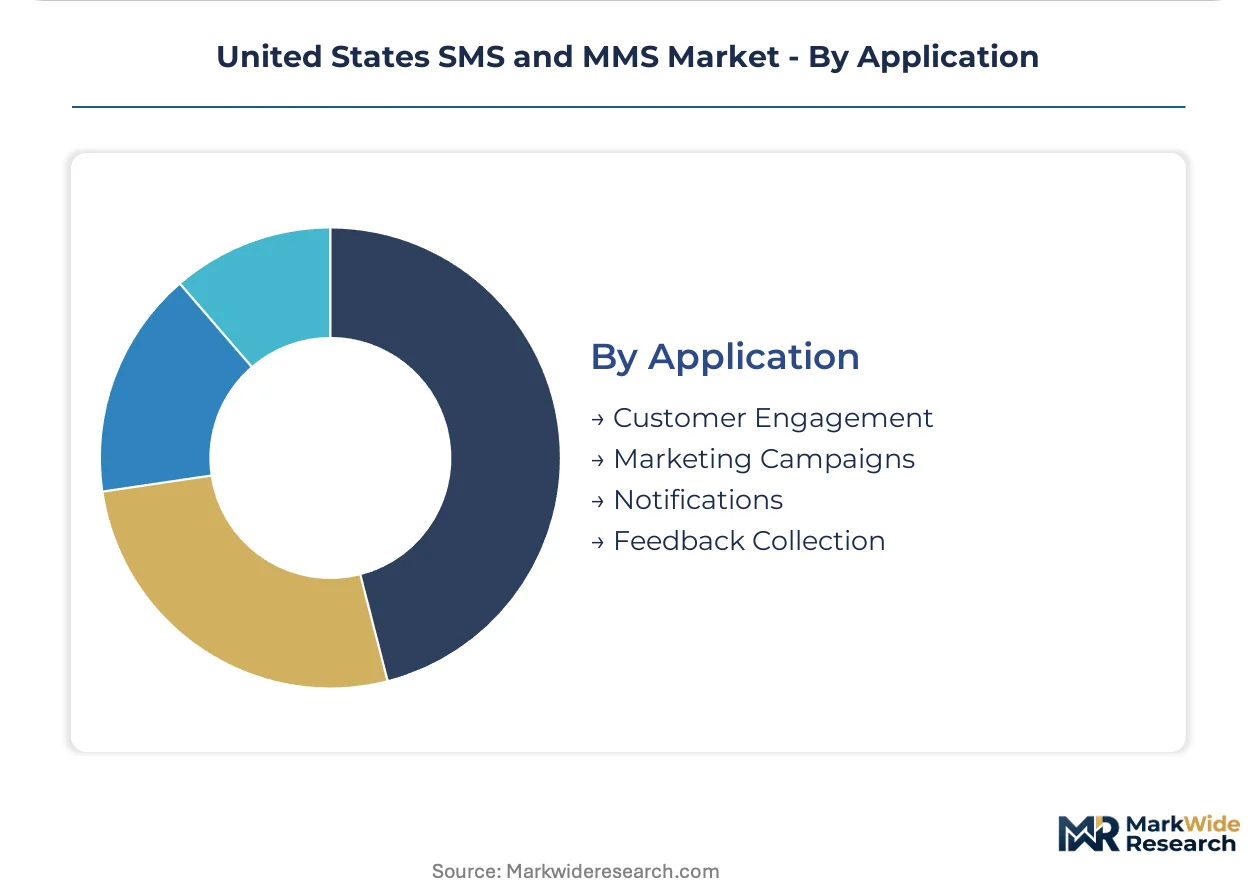
Application:
Customer interaction depth shapes infrastructure requirements, with static alerts giving way to dynamic conversational flows that demand AI-enabled routing optimization.
- Customer Engagement:Two-way conversational platforms integrate with CRM systems to enable dynamic escalation beyond static alerts. Retail banks deploy these systems for payment reminders and claims status inquiries.
- Notifications:One-way service alerts require guaranteed delivery but minimal interactivity, suiting cost-optimized routing.
- Marketing Campaigns:Promotional broadcasts face margin compression from consent enforcement and encrypted messaging substitution.
- Feedback Collection:Survey and rating flows represent emerging use cases with moderate authentication requirements.
Customer engagement applications command the largest infrastructure commitments; feedback collection is expanding most rapidly as enterprises close loop on service interactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's technology corridor and the New York metropolitan financial hub concentrate the densest transactional message volumes for two-factor authentication and fraud alerts. The FCC's STIR/SHAKEN framework applies nationwide, reshaping sender verification requirements state by state. Regional variations in healthcare automation and financial services density create distinct infrastructure demand patterns across sub-regional markets.
California
Silicon Valley technology enterprises and San Francisco fintech clusters drive premium API consumption for verified messaging infrastructure. The California Consumer Privacy Act imposes data handling constraints that overlap with HIPAA encryption mandates for healthcare systems. Los Angeles healthcare networks are expanding automated patient appointment workflows to reduce no-show rates across multi-facility systems.
New York Metro
Wall Street financial institutions generate dense transactional traffic for payment confirmations and security alerts requiring STIR/SHAKEN-compliant authentication. New York State's Department of Financial Services cybersecurity regulations reinforce carrier-grade throughput requirements for latency-sensitive routing. Manhattan insurance carriers and Brooklyn-based retail banks are deploying conversational AI for claims processing and payment reminders.
Texas
Houston medical center complexes and Dallas-Fort Worth healthcare systems are expanding automated patient verification workflows for appointment scheduling. Texas Medical Board regulations align with HIPAA encryption mandates for SMS-based patient communication. Austin's technology corridor is emerging as a secondary hub for fintech messaging API consumption.
Florida
Miami healthcare networks and Tampa Bay hospital systems are modernizing legacy patient management platforms with automated engagement tools. Florida's Agency for Health Care Administration enforces data security standards that complement federal HIPAA requirements. Orlando's insurance carrier concentration is driving demand for audit-trail-compliant messaging infrastructure.
Midwest Corridor
Ohio, Michigan, and Illinois hospital networks represent whitespace for automated patient engagement deployments as systems modernize legacy infrastructure. State-level health information exchange regulations in Illinois and Michigan reinforce encryption requirements for patient communication. Cleveland Clinic and Detroit health systems are piloting conversational AI for dynamic two-way patient interactions.
United States SMS and MMS Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light platform designers across the United States SMS and MMS ecosystem. Carrier-direct operators with owned network assets face API-first developers with programmable communications stacks. Three strategic archetypes dominate: vertically integrated network owners, pure-play API platforms, and carrier-aggregator hybrids. Consolidation pressure is driving strategic partnerships between healthcare compliance specialists and conversational AI developers.
Within the API-platform tier, Twilio and Sinch exemplify divergent approaches to enterprise-grade messaging infrastructure. Twilio anchors programmable communications workflows across regulated verticals. Sinch occupies a position emphasizing direct carrier relationships for transactional throughput. Bandwidth represents the vertically integrated archetype through its captive IP voice and messaging network, positioning favorably for HIPAA-compliant healthcare contracts requiring audit trails.
| Leading Market Players |
|---|
| Vonage |
| Infobip |
| Twilio |
| Attentive |
| ActiveCampaign |
| Sinch |
| Telnyx |
| MessageBird |
| Bandwidth |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up API platforms have consolidated carrier relationships and authentication infrastructure, tightening pricing discipline while feeding margin pressure back into interconnection fee negotiations with tier-one mobile network operators.
Pricing Analysis
Outcome-based pricing tied to verified delivery rates anchors enterprise contracts, with STIR/SHAKEN-compliant authentication tiers commanding premiums over commodity bulk channels. Price differentiation rests on throughput guarantees and HIPAA audit-trail capabilities, not raw message volume. Cost compression in unauthenticated A2P tiers is intensifying because carrier filtering raises effective delivery costs for non-compliant senders. E-commerce and retail promotional buyers exhibit highest price sensitivity; healthcare systems and BFSI entities prioritize compliance over unit cost.
Supply Chain Analysis
Returns and remediation flows for failed message delivery create reverse-logistics complexity as carriers bounce non-compliant traffic back to originating platforms for re-routing or customer notification. Infrastructure concentration centers on the United States, with secondary dependencies on Ireland and Singapore for data sovereignty and latency optimization. Raw material inputs draw from IP transit bandwidth, carrier interconnection agreements, and cloud compute capacity. Single-source vulnerability sits with tier-one mobile network operator gateway access. Distribution runs through API-first platforms and direct carrier relationships to enterprise IT and marketing technology departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over IP voice and messaging networks to escape carrier interconnection fee pressure and capture HIPAA-compliant healthcare contracts.
For Market Incumbents: Lock in carrier-direct relationships and STIR/SHAKEN authentication infrastructure to defend against encrypted messaging substitution by WhatsApp Business and Apple Business Chat. Deepen backward integration into owned network assets to reduce exposure to tier-one mobile network operator pricing power. For New Entrants and Emerging Players: Launch via HIPAA-compliant healthcare specialization targeting Midwestern hospital networks in Ohio, Michigan, and Illinois where legacy system modernization creates whitespace. Penetrate conversational AI integration layers for retail banks seeking claims processing automation, avoiding saturated promotional messaging tiers. For Investors and Strategic Acquirers: FCC robotext rulemaking proceedings mandating explicit opt-in documentation are the leading indicator that infrastructure vendors with timestamp verification capabilities will command acquisition premiums. Long-term viability favors vertically integrated network owners over asset-light API platforms. Target carriers with owned IP infrastructure and demonstrated healthcare compliance tooling.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Network Acquisition | Captive IP infrastructure reduces interconnection fees and enables HIPAA audit trails for healthcare contracts. |
| STIR/SHAKEN Infrastructure Buildout | Authentication tier separation creates pricing power with regulated BFSI and healthcare senders under FCC mandates. |
| Conversational AI Platform Integration | Dynamic two-way patient and customer interactions compress implementation timelines from months to weeks. |
| HIPAA Compliance Certification Investment | Encryption and access control capabilities open specialized infrastructure contracts with hospital systems. |
| Midwestern Healthcare System Partnership | Ohio, Michigan, and Illinois networks represent whitespace for automated patient engagement deployments. |
Research Methodology
Document review covered FCC rulemaking proceedings, CTIA messaging best practices, carrier tariff filings, and HIPAA guidance documents, complemented by interviews with platform engineering directors, healthcare IT procurement managers, carrier interconnection specialists, and regulatory compliance officers. Secondary sources included SEC 10-K disclosures from publicly traded communications infrastructure providers, CTIA annual reports, and CMS Medicare messaging utilization data. Bottom-up message volume estimates triangulated against top-down carrier revenue disclosures.
Segment-level projections across service type, end user vertical, deployment technology, and application use case fed into an analytical framework spanning the projection horizon. CAGRs derived from regression analysis against historical A2P messaging growth patterns, adjusted for STIR/SHAKEN compliance adoption curves and healthcare automation penetration rates. Model inputs included carrier filtering intensity indices and conversational AI deployment velocity by vertical.
The model assumes a particular technology adoption path; alternative pathways for RCS Business Messaging convergence would alter the outlook if carrier-native rich messaging protocols displace traditional SMS faster than projected. Practitioners should monitor FCC robotext rulemaking finalization and carrier tiered filtering enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Ucaas in Banking Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Business Cloud Voip and UC Services Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Unified Communication Market
Unified Communications
Unified Monitoring Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
Cloud UC Calling Market