
 Cloud UC Calling Market | 2026-2036
Cloud UC Calling Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud UC Calling Market Insights
North American data center expansion is reshaping how cloud UC infrastructure deploys at the edge. Microsoft leverages its Azure global footprint to anchor enterprise-grade calling reliability across distributed workloads. Cisco competes through deep integration of security protocols with voice infrastructure, while RingCentral specializes in multi-tenant architectures for mid-market customers.
Cloud UC Calling delivers real-time voice, video, and messaging services through IP-based infrastructure with session initiation protocol signaling and guaranteed mean opinion score thresholds above 3.6 for toll-quality voice. Hosted solutions dominate current revenue as enterprises outsource telephony management to avoid capital-intensive PBX refresh cycles. Public cloud deployment leads volume adoption, though private cloud configurations capture premium margins in financial services and government verticals where data residency controls apply.
FCC regulations govern emergency service obligations and number portability for IP-based voice providers, while GDPR in Europe imposes strict constraints on call metadata retention and cross-border data flows. HIPAA compliance requirements shape product roadmaps for healthcare-focused UC deployments, particularly around encryption standards and access audit trails. Stakeholders must weigh regulatory fragmentation against platform consolidation pressures when selecting multi-region deployment architectures.
Market Dynamics
Enterprise migration from on-premises PBX infrastructure to cloud-native voice architectures is compressing refresh cycles and redistributing vendor power toward platform consolidators with integrated security stacks.
Growth Catalysts
- Healthcare telemedicine expansion:HIPAA-compliant cloud voice deployments are accelerating across hospital networks and ambulatory care chains as remote patient coordination becomes standard care delivery.
- FCC emergency calling mandates:Enhanced 911 requirements for IP-based voice services are forcing legacy system replacements and driving compliant cloud migration among mid-market enterprises.
- Session border controller virtualization:Software-defined SBC deployment is reducing voice infrastructure capital requirements and enabling faster geographic expansion for service providers.
Market Restraints
- Submarine cable concentration:Transatlantic and transpacific fiber routes through limited landing points create single-point-of-failure risks for real-time voice quality across intercontinental deployments.
- GDPR metadata retention constraints:European call record storage limitations complicate cross-border unified communications architectures and increase compliance engineering costs.
- Legacy PRI circuit obligations:Remaining TDM interconnect requirements in regulated industries delay full cloud migration and sustain hybrid complexity costs.
Strategic Opportunities
- India enterprise digitization:TRAI's cloud communication liberalization is opening addressable market expansion for hosted voice providers serving the country's mid-market manufacturing and services sectors.
- AI-powered real-time transcription:Convergence of natural language processing with voice streams is creating new compliance and accessibility service tiers for financial services and legal verticals.
- Edge computing voice processing:Distributed micro-datacenter deployment is enabling sub-50ms latency guarantees for manufacturing floor communications and industrial IoT integration.
Industry Challenges
- SIP security engineering scarcity:Deep expertise in session initiation protocol threat mitigation and toll fraud prevention remains concentrated among limited specialist talent pools.
- Multi-vendor interoperability certification:Complex vendor-specific implementation variants delay enterprise deployment timelines and increase integration testing overhead.
- Hybrid environment management complexity:Sustained coexistence of cloud and premises-based systems demands specialized operational tooling that many IT organizations lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud UC Calling Market |
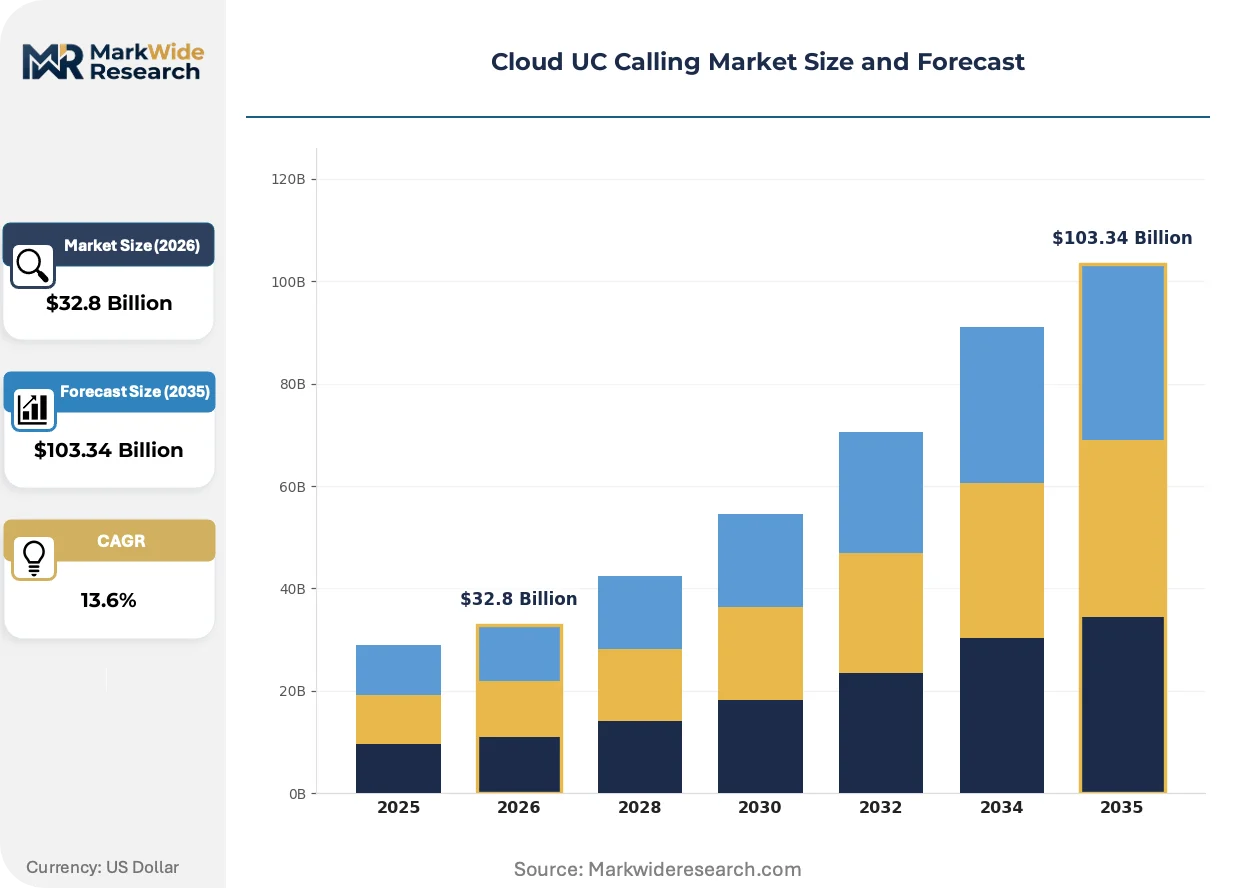
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $103.34 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Hosted Solutions, On-Premises Solutions, Hybrid Solutions, Platform-as-a-Service Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Virtual Private Cloud Use Case: Video Conferencing, Instant Messaging, Team Collaboration, Contact Center Solutions End User: Enterprises, SMBs, Education Sector, Healthcare Providers |
| Companies Covered | Microsoft, Cisco, Zoom, RingCentral, 8x8, Avaya, Mitel, Dialpad, Nextiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud UC Calling Market Trends and Innovations
Voice infrastructure is decoupling from dedicated hardware, with software-defined signaling and containerized media processing enabling elastic capacity scaling that matches enterprise communication volatility.
WebRTC is virtualizing browser-based real-time communications without plugin dependencies. Financial services contact centers are adopting it for client-facing video authentication. This architecture is virtualizing the traditional desktop phone endpoint and collapsing deployment timelines from weeks to hours.
GDPR's cross-border data transfer mechanisms are tightening call routing compliance requirements. European enterprises must now document lawful bases for transcontinental voice metadata flows. German and French healthcare providers are responding by demanding in-region media processing guarantees from their UCaaS contracts.
Enterprise buyers are unbundling managed services from core platform subscriptions. Mid-market procurement teams now source voice analytics, compliance archiving, and E911 management as separate best-of-breed components. This pattern is most pronounced among United States professional services firms with 500-5,000 employees seeking vendor diversification.
Cloud UC Calling Market Segmentation
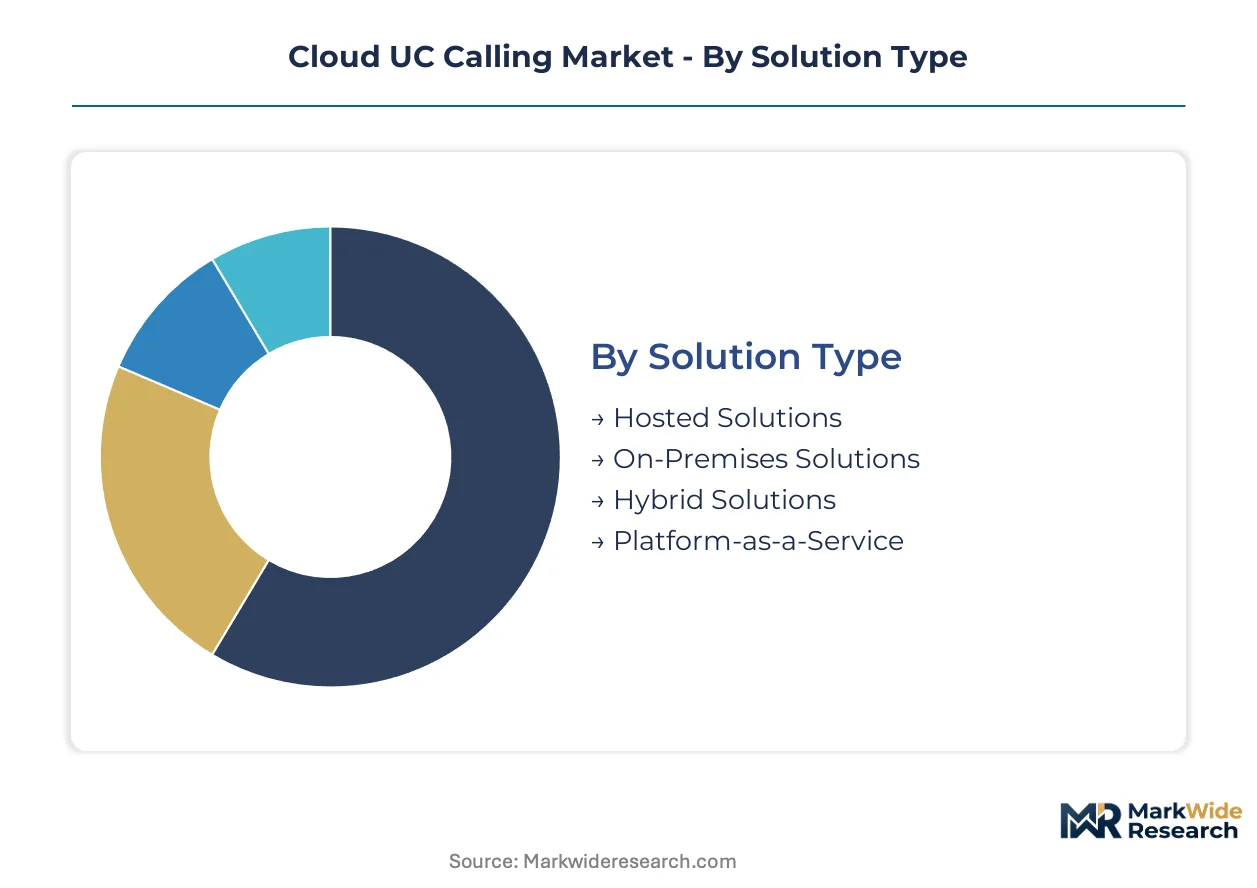
Cloud UC Calling segmentation reveals how voice infrastructure investment splits between legacy migration paths and cloud-native architectures. Procurement patterns vary sharply by organization size, regulatory exposure, and collaboration intensity requirements.
Solution Type:
Mature outsourcing models coexist with emerging platform abstractions as enterprises navigate capital efficiency against control requirements.
- Hosted Solutions:Third-party telephony management delivered over IP infrastructure eliminates PBX refresh capital cycles. Demand concentrates among United States mid-market enterprises seeking predictable operating expenditure models without internal voice engineering teams.
- On-Premises Solutions:Customer-managed voice infrastructure retains dedicated hardware for signaling and media processing. Financial services and government verticals in Germany and France favor this model for data residency compliance and direct control over encryption key management.
- Hybrid Solutions:Split architectures maintain legacy PRI interconnects while routing internal traffic through cloud SIP trunks. Healthcare systems leverage this pattern to preserve emergency calling reliability during gradual cloud transitions.
- Platform-as-a-Service:API-first voice infrastructure enables developers to embed calling capabilities into custom applications. Indian software vendors and United States SaaS builders are adopting this for embedded communications in vertical workflows.
Hosted Solutions handles the majority of throughput; Platform-as-a-Service is the fastest mover on share.
Deployment Model:
Cost tier differentiation separates commodity consumption from premium isolation guarantees in regulated verticals.
- Public Cloud:Shared infrastructure delivers elastic capacity scaling across Microsoft's Azure, Amazon Web Services, and Google Cloud Platform footprints. United States technology and professional services firms dominate consumption for distributed workforce enablement.
- Private Cloud:Single-tenant voice infrastructure deployed in dedicated data centers or customer facilities. Swiss banking consortiums and Japanese automotive suppliers specify this for call metadata sovereignty and audit trail isolation.
- Multi-Cloud:Orchestrated workloads spanning multiple hyperscaler environments with automated failover. Australian federal contractors and Canadian healthcare networks adopt this to avoid single-provider concentration risk.
- Virtual Private Cloud:Logically isolated network segments within public cloud fabrics with dedicated IP addressing and security policies. United Kingdom legal services firms and South Korean manufacturing conglomerates favor this for client confidentiality compliance.
Public Cloud absorbs the volume base; Private Cloud commands the margin premium.
Use Case:
Application intensity varies by collaboration modality, with synchronous video demanding disproportionate bandwidth engineering.
- Video Conferencing:High-definition real-time video with screen sharing and recording capabilities. United States pharmaceutical sales organizations and Brazilian financial advisory networks drive demand for regulatory-compliant client-facing visual authentication.
- Instant Messaging:Persistent chat with file sharing, threading, and enterprise search across conversation history. Technology sector deployment in India and Israel emphasizes integration with DevOps toolchain workflows.
- Team Collaboration:Integrated workspaces combining messaging, voice, video, and document co-editing. German engineering firms and United States architecture practices adopt this for cross-functional project coordination.
- Contact Center Solutions:Omnichannel customer engagement with automated call distribution, IVR, and workforce optimization. Indian business process outsourcing providers and Philippine customer service operations scale this for voice-agent productivity measurement.
Team Collaboration anchors daily user engagement; Contact Center Solutions generates the highest per-seat revenue.
End User:
Customer type determines feature complexity tolerance and compliance certification requirements.
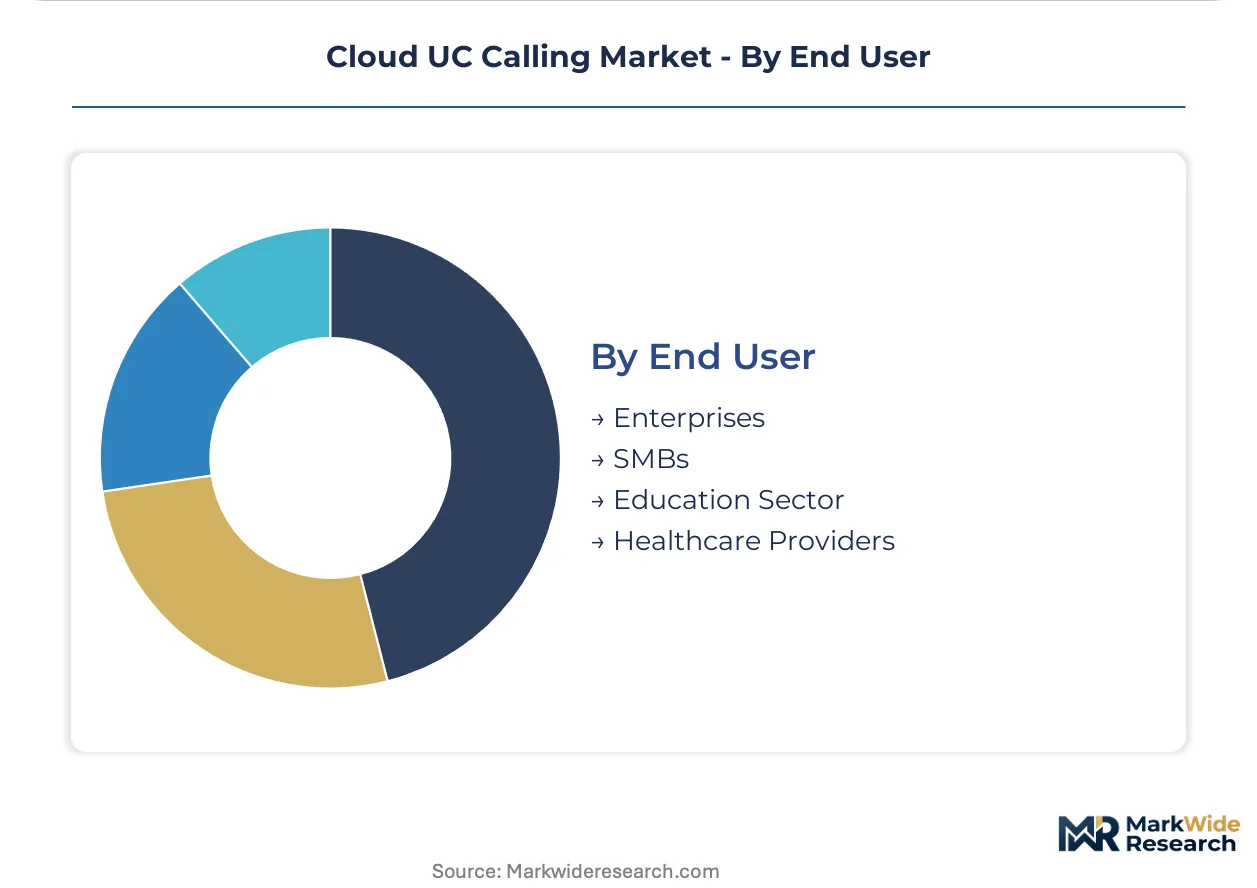
- Enterprises:Organizations with 1,000-plus employees requiring global dial plans, advanced analytics, and custom integration. United States Fortune 500 manufacturers and European automotive OEMs drive demand for multi-region redundancy and SLA-backed uptime guarantees.
- SMBs:Small and medium businesses with 10-999 employees prioritizing rapid deployment and minimal IT overhead. Australian retail chains and Mexican professional services firms favor pre-configured templates and bundled mobile applications.
- Education Sector:K-12 districts and higher education institutions with seasonal enrollment volatility and accessibility mandates. United States public university systems specify this for lecture capture integration and ADA-compliant transcription services.
- Healthcare Providers:Hospitals, clinics, and telemedicine platforms with HIPAA, GDPR, or equivalent patient data protections. German hospital networks and United States ambulatory surgery centers demand Business Associate Agreements and encrypted call recording retention.
Enterprises contribute the revenue concentration; Healthcare Providers show the steepest compliance-driven upgrade cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler data center buildouts concentrate voice infrastructure investment in three primary markets. United States cloud UC deployment leads absolute spending. European regulatory fragmentation shapes multi-region architecture decisions. Indian enterprise digitization opens new subscriber growth corridors.
United States
Fortune 500 manufacturers and professional services firms drive hosted voice migration to eliminate PBX capital cycles. FCC Enhanced 911 mandates force legacy system replacements among mid-market enterprises. Seattle and Northern Virginia hyperscaler clusters anchor Azure and AWS voice infrastructure for distributed workforce enablement.
Germany
Automotive OEMs and engineering conglomerates demand private cloud configurations for call metadata sovereignty. GDPR cross-border transfer constraints complicate transcontinental voice architectures for multinational enterprises. Munich and Stuttgart industrial belts favor on-premises solutions with direct encryption key management.
United Kingdom
London legal services firms and financial advisory networks adopt virtual private cloud segments for client confidentiality compliance. Post-Brexit data residency requirements reshape call routing documentation for European operations. The Greater Southeast technology corridor concentrates API-first voice platform development for embedded communications.
India
Mid-market manufacturing and business process outsourcing providers scale contact center solutions for voice-agent productivity measurement. TRAI cloud communication liberalization removes licensing barriers for hosted voice providers. Bengaluru and Hyderabad software clusters drive Platform-as-a-Service adoption for vertical workflow integration.
Japan
Automotive suppliers and precision manufacturers specify private cloud deployments for audit trail isolation. METI digital transformation incentives accelerate enterprise migration from legacy TDM infrastructure. The Nagoya industrial corridor maintains hybrid architectures to preserve emergency calling reliability during gradual cloud transitions.
Cloud UC Calling Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in signaling and security layers. The vendor base separates between hyperscaler-anchored suites and best-of-breed point solutions. Three archetypes dominate: cloud-native multi-tenant providers, legacy equipment vendors transitioning to subscription models, and API-first developers embedding voice into vertical applications. Consolidation pressures favor M&A activity among mid-scale hosted providers, while strategic partnerships between carriers and software vendors reshape distribution economics.
Within the platform integrator tier, Microsoft and Cisco exemplify divergent architectural philosophies—Azure-anchored ecosystem breadth versus security-integrated infrastructure depth. RingCentral occupies a position representing cloud-native specialization for mid-market multi-tenancy. These three anchors illustrate how scale, vertical integration depth, and API accessibility define competitive positioning without requiring uniform strategic moves across the category.
| Leading Market Players |
|---|
| Microsoft |
| Cisco |
| Zoom |
| RingCentral |
| 8x8 |
| Avaya |
| Mitel |
| Dialpad |
| Nextiva |
| Others |
Pricing and Supply Chain Analysis
Transatlantic submarine cable routes anchor freight cost dynamics for voice infrastructure hardware, concentrating supply-side pricing power among hyperscaler regions while downstream buyers face tiered differentiation based on compliance certification and deployment latency requirements.
Pricing Analysis
FCC emergency calling mandates dictate the pricing tier structure across the Cloud UC Calling landscape, separating premium HIPAA-compliant configurations from standard enterprise subscriptions and economy-tier SMB packages. Price differentiation rests on encryption grade certification and geographic media processing guarantees, with German healthcare buyers paying substantial premiums for in-region data residency. Cost compression in mid-market hosted solutions is intensifying because Microsoft and Cisco are bundling voice into broader productivity suites. SMB procurement teams show highest price sensitivity, while financial services firms with regulatory exposure demonstrate lowest elasticity.
Supply Chain Analysis
Export control restrictions on advanced encryption chipsets limit component flows from United States and allied suppliers to certain overseas assembly points. Hardware concentration centers on Taiwan for session border controller silicon, South Korea for memory modules, and China for commodity networking gear. Raw material dependencies span rare earth elements for magnetic components, high-purity copper for cable infrastructure, and specialized polymers for fiber optic sheathing. Single-source vulnerability around Taiwanese semiconductor fabrication creates systemic risk for voice processing hardware. Distribution runs through hyperscaler-direct procurement for enterprise deployments and carrier-aggregator channels for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud UC Calling is approaching a platform-economics inflection where WebRTC standardization and API-first architectures are collapsing traditional vendor lock-in, rewarding ecosystem orchestrators over point-solution specialists.
For Market Incumbents: Harden session border controller virtualization roadmaps against software-defined entrants threatening margin compression in core voice infrastructure. Deepen Azure and AWS partnership tiers to secure hyperscaler co-sell positioning. Invest in AI-powered transcription certifications for financial services compliance archiving before specialist NLP vendors capture that attach revenue. For New Entrants and Emerging Players: Establish a beachhead in Indian mid-market manufacturing where TRAI liberalization has removed licensing barriers and incumbent presence remains thin. Target healthcare telemedicine platforms seeking embedded voice APIs for remote patient coordination workflows. Pursue vertical-specific compliance certifications as primary go-to-market differentiation rather than competing on raw price. For Investors and Strategic Acquirers: API-first voice infrastructure developers with healthcare or financial services compliance moorings represent the most defensible acquisition profile for sustained value creation. Long-term viability hinges on platform consolidation economics favoring multi-tenant architectures with developer ecosystem density. Watch for FCC rulemaking on AI-generated voice disclosure as an inflection signal for regulatory-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft's Azure ecosystem bundling collapses standalone voice vendor margins through productivity suite anchoring. |
| Acquisition of Specialist Firm | AI transcription vendors with HIPAA certifications command premium valuations from platform consolidators seeking compliance differentiation. |
| Geographic Expansion | Indian enterprise digitization under TRAI liberalization opens subscriber growth corridors for hosted voice providers. |
| Strategic Partnership | Carrier-software vendor alliances reshape distribution economics for mid-market segments bypassing traditional reseller channels. |
| Product Launch | Edge computing voice processing with sub-50ms latency guarantees targets manufacturing floor communications and industrial IoT integration. |
Research Methodology
A standing panel of UCaaS procurement officers, voice infrastructure engineers, carrier network architects, and compliance audit specialists provided ongoing calibration across primary interview rounds and secondary validation. FCC rulemaking dockets, TRAI consultation papers, hyperscaler capex disclosures, and healthcare system RFP databases anchored bottom-up triangulation against top-down market sizing.
Scenario-bracketing around regulatory enforcement intensity and enterprise migration velocity shaped analytical outputs across the projection horizon. Segmentation dimensions modeled encompassed solution type, deployment architecture, organization size tier, vertical regulatory exposure, and regional adoption pattern. CAGRs derived from install base erosion rates for legacy PBX systems correlated against cloud seat expansion curves, with session border controller virtualization timelines and WebRTC penetration assumptions as industry-specific inputs.
Stress conditions across FCC mandate implementation timing, submarine cable disruption frequency, and GDPR cross-border enforcement consistency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enterprise refresh cycle compression and healthcare telemedicine standardization. Material shifts in encryption export control regimes or hyperscaler data center buildout pauses would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Business Cloud Voip and UC Services Market
Unified Communications
Ucaas in the Manufacturing Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
United States SMS and MMS Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
Unified Monitoring Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Ucaas in Banking Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Unified Communication Market