
 Unified Communications As a Service (Ucaas) Market | 2026-2036
Unified Communications As a Service (Ucaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Unified Communications As a Service (Ucaas) Market Analysis
Platform licensing revenue is rewriting profitability calculus across the UCaaS value chain, pulling margin pools away from perpetual hardware sales toward recurring software subscriptions. Microsoft Corporation leverages its Entra identity fabric and Teams Phone integration to anchor enterprise retention across verticals. Cisco Systems Inc. competes through Webex's security certifications and dedicated hardware endpoints that sustain premium positioning in regulated industries. Zoom Video Communications Inc. specializes in video-first architecture that dominates mid-market land-and-expand motions.
Unified Communications as a Service denotes a cloud delivery model integrating voice, video, messaging, and collaboration tools through IP-based infrastructure with guaranteed service-level agreements for uptime and latency. The architecture eliminates capital expenditure on private branch exchanges while centralizing administration through web-native dashboards. Public cloud deployment leads volume due to elastic scaling and rapid provisioning, though hybrid cloud configurations capture expanding margin pools as enterprises retain on-premises session border controllers for compliance-sensitive workloads. Voice services constitute the mature revenue base, while collaboration tools represent the fastest-growing segment as vendors embed AI-assisted transcription and workflow automation.
FCC net neutrality rulings in the United States shape interconnection agreements and quality-of-service prioritization for VoIP traffic traversing carrier networks. GDPR and the EU AI Act impose data localization and algorithmic transparency mandates that restrict cross-border processing of meeting recordings and biometric analytics. HIPAA compliance requirements govern how UCaaS providers architect Business Associate Agreements for healthcare clients. Stakeholders must evaluate whether their vendor's sovereign cloud footprint aligns with emerging sector-specific residency obligations before committing to multi-year contracts.
Market Dynamics
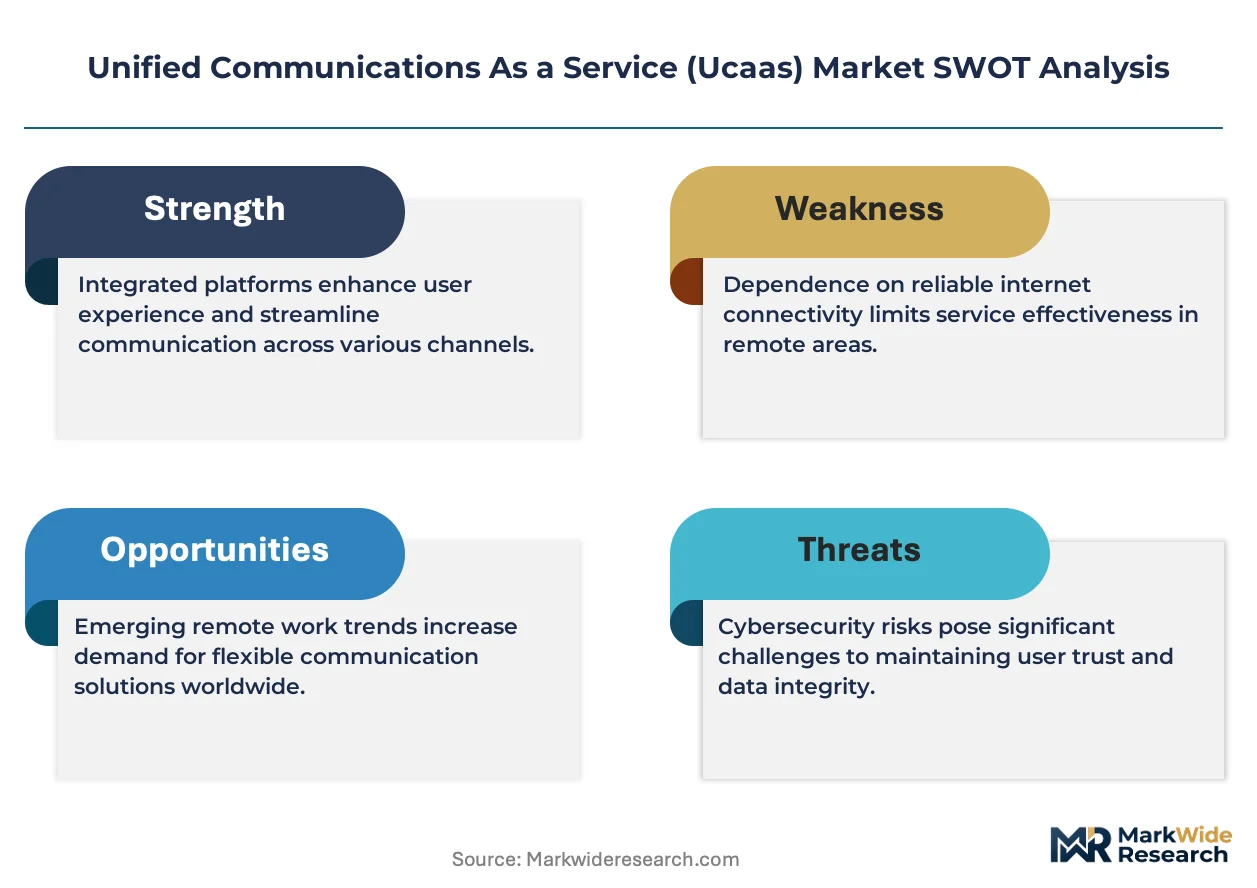
The UCaaS market is compressing around data sovereignty mandates as GDPR and the EU AI Act force vendors to rebuild infrastructure for jurisdictional isolation rather than global consolidation.
Growth Catalysts
- Healthcare telemedicine workflows:HIPAA-covered entities are consolidating voice, video, and EHR-integrated messaging onto single cloud platforms to eliminate vendor fragmentation in patient care coordination.
- German Mittelstand hybrid deployments:Mid-sized manufacturers are procuring UCaaS with local session border controllers to satisfy works council data residency requirements while retaining cloud elasticity.
- FCC net neutrality enforcement:Quality-of-service prioritization rulings are legitimizing carrier-grade SLAs for VoIP traffic, reducing enterprise hesitation about voice reliability over public internet.
Market Restraints
- Submarine cable concentration:Transatlantic latency for real-time video depends on a handful of landing stations in Virginia and Cornwall, creating single-point vulnerability for sovereign cloud routing.
- Legacy PBX sunk costs:Enterprises with recent on-premises investments face accounting friction in accelerating depreciation to justify cloud migration timelines.
- Biometric data processing restrictions:GDPR Article 9 limitations on voiceprint authentication are forcing vendors to disable features in EU instances that remain standard elsewhere.
Strategic Opportunities
- AI-assisted transcription convergence:Meeting analytics engines are merging with workflow automation platforms, creating stickiness through CRM and project management integration rather than standalone communication.
- Indian BPO sector expansion:Domestic outsourcing providers are upgrading from basic VoIP to full collaboration suites as TRAI regulations ease international cloud interconnect.
- CSRD disclosure requirements:EU corporate sustainability reporting is mandating scope 3 emissions tracking that favors UCaaS vendors with certified carbon-neutral data centers.
Industry Challenges
- Session border controller certification backlog:National security agencies in France and Germany are queuing hardware approvals for encrypted voice gateways, delaying hybrid deployments by quarters.
- Interoperability testing complexity:Enterprises maintaining Cisco, Microsoft, and Zoom environments simultaneously face integration debt from divergent API implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unified Communications As a Service (Ucaas) Market |
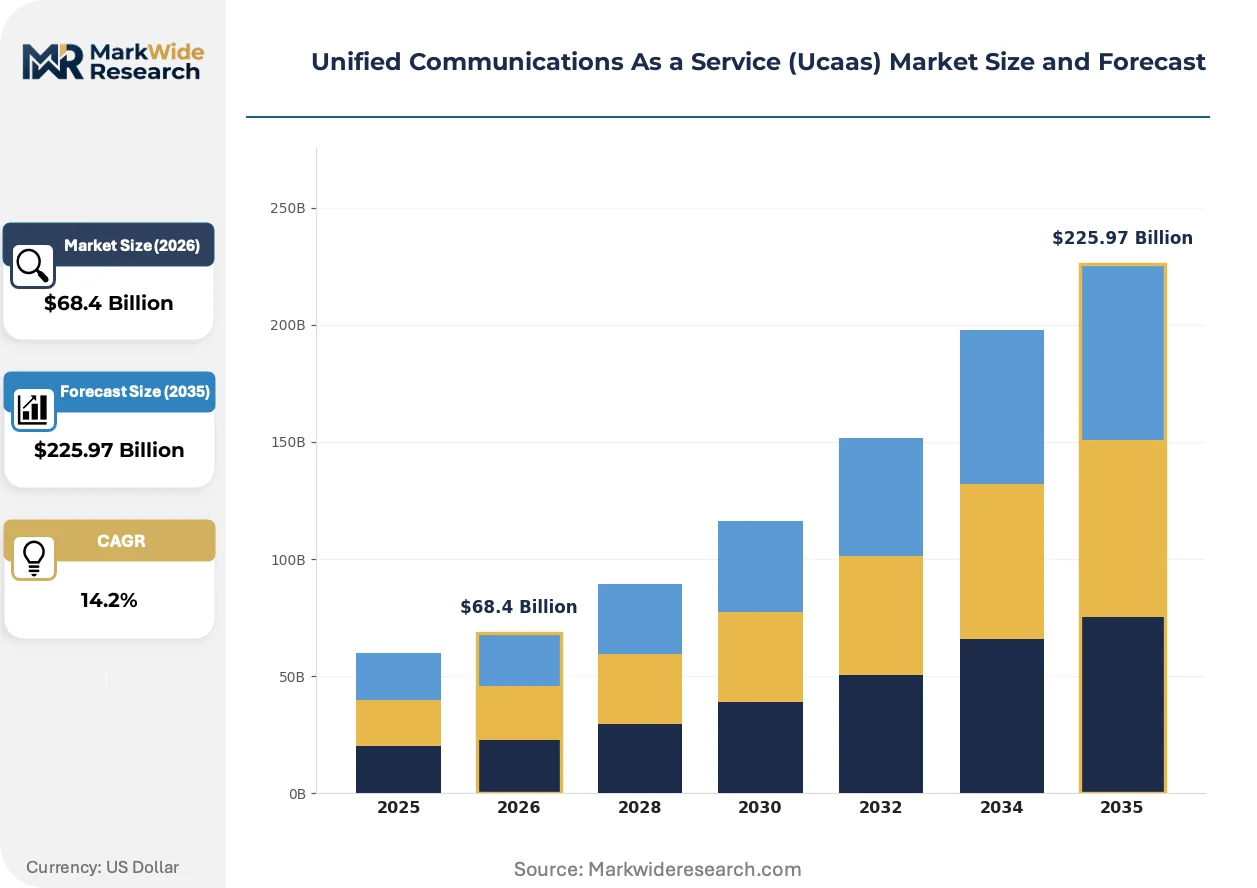
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $225.97 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: SMEs, Large Enterprises, Government, Educational Institutions Service Type: Voice Services, Video Conferencing, Messaging, Collaboration Tools Technology: VoIP, WebRTC, SIP, UC Clients |
| Companies Covered | Cisco Systems Inc., Microsoft Corporation, RingCentral Inc., 8x8 Inc., Zoom Video Communications Inc., Avaya Inc., IBM Corporation, Oracle Corporation, Verizon Communications Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unified Communications As a Service (Ucaas) Market Emerging Trajectories
Artificial intelligence is embedding into communication workflows at the infrastructure layer, shifting competitive differentiation from connectivity quality to predictive automation and ambient intelligence.
Edge-resident media processing is migrating from centralized cloud transcoding to on-premises AI accelerators. Financial services firms with sub-10-millisecond latency requirements are deploying GPU-equipped appliances in branch offices. This architecture is compressing bandwidth costs while enabling real-time compliance monitoring that previously required post-call batch analysis.
The EU AI Act's risk classification system is forcing vendors to document algorithmic decision-making in biometric emotion detection and speaker identification features. Providers must now maintain separate model versions for EU and non-EU deployments. Healthcare and legal verticals are demanding audit trails that satisfy both GDPR data minimization and sector-specific retention mandates.
Consumption-based licensing is displacing per-seat subscriptions in contact center deployments. Enterprise buyers are negotiating metered billing tied to actual interaction minutes rather than named user counts. This shift is most advanced in North American retail and logistics operations where seasonal staffing volatility makes fixed commitments economically untenable.
Unified Communications As a Service (Ucaas) Market Segmentation
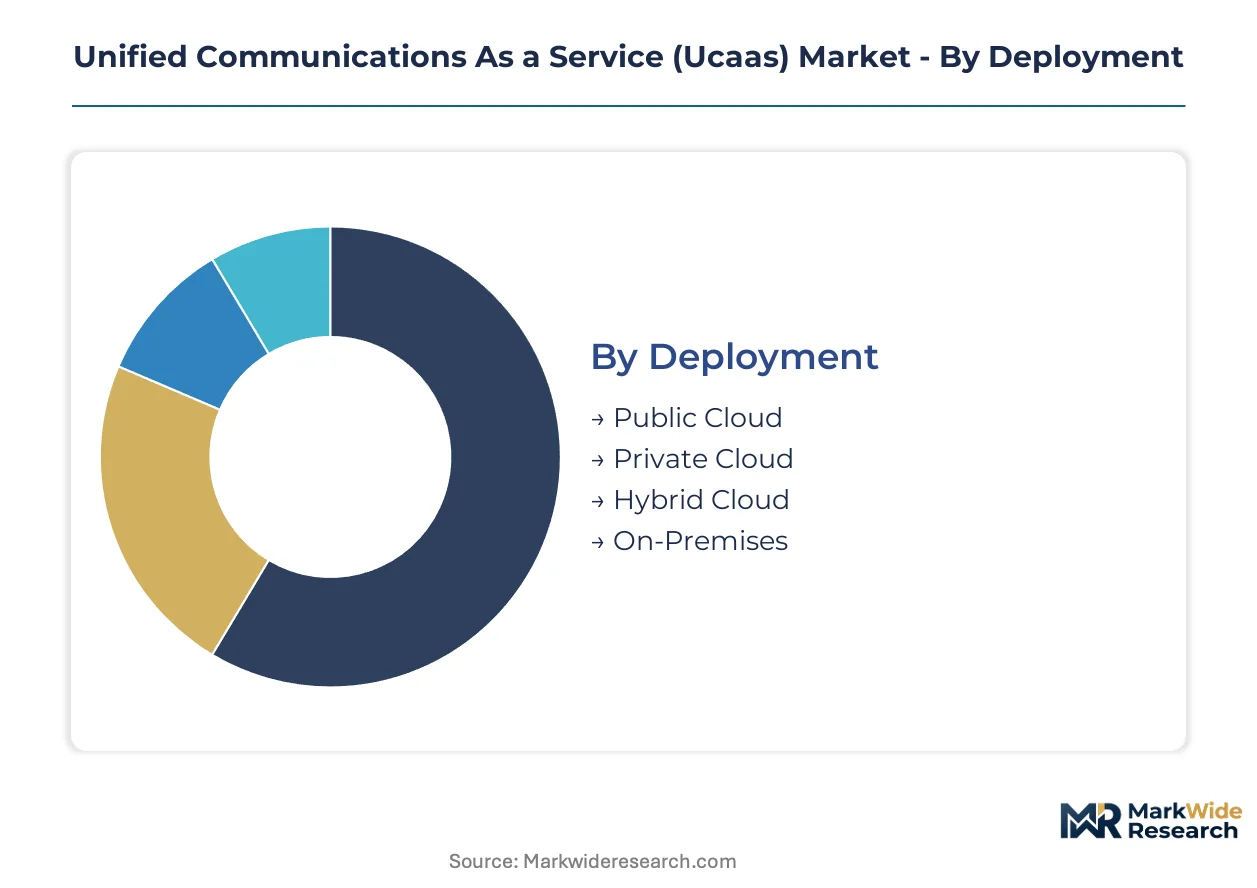
UCaaS procurement patterns diverge sharply across deployment architectures and organizational scale, with compliance requirements and legacy infrastructure dictating migration velocity. Technology choices determine interoperability boundaries and latency performance for real-time workloads.
Deployment:
Maturity varies from elastic public infrastructure to captive on-premises estates, with hybrid configurations capturing expanding investment as data residency mandates proliferate.
- Public Cloud:Multi-tenant infrastructure delivers elastic scaling and rapid provisioning through web-native dashboards. Healthcare providers in Germany and France are consolidating telemedicine workloads onto sovereign-hosted public instances to satisfy GDPR and EU AI Act localization requirements without capital expenditure.
- Hybrid Cloud:Split architectures retain session border controllers on-premises while leveraging cloud elasticity for collaboration tools. Mittelstand manufacturers across Bavaria and Baden-Württemberg prioritize this model to satisfy works council data residency demands while accessing AI-assisted transcription services.
- Private Cloud:Single-tenant deployments isolate voice and video infrastructure for regulated financial and legal sectors requiring dedicated security certifications.
- On-Premises:Captive PBX and UC platforms persist in defense and intelligence applications where air-gapped networks are mandatory.
Public cloud handles the majority of throughput; hybrid cloud is gaining share fastest as compliance-sensitive verticals seek jurisdictional control without sacrificing cloud economics.
End User:
Procurement sophistication scales with organizational complexity, from standardized SaaS subscriptions to negotiated enterprise frameworks with custom SLA terms.
- Large Enterprises:Multi-year contracts incorporate dedicated support tiers, custom integration roadmaps, and negotiated data residency clauses. German automotive suppliers and French banking conglomerates drive demand for sovereign-hosted instances with certified carbon-neutral operations under CSRD disclosure requirements.
- SMEs:Standardized per-seat subscriptions dominate, with rapid deployment and minimal IT overhead as primary selection criteria. Mid-market professional services firms across the United States and United Kingdom favor video-first platforms with native CRM connectors.
- Government:National security certifications and FedRAMP or equivalent compliance frameworks govern vendor selection for federal and state agencies.
- Educational Institutions:Volume licensing agreements accommodate semester-based staffing volatility and multi-campus federation requirements.
Large enterprises anchor contract value; SMEs are expanding most quickly as vendor land-and-expand motions penetrate underserved verticals.
Service Type:
Revenue composition shifts from commoditized voice connectivity toward AI-enhanced collaboration suites that embed workflow automation.
- Collaboration Tools:Integrated project management, document co-editing, and AI-assisted transcription create platform stickiness through CRM and ERP embedding. Financial services firms in London and New York deploy GPU-equipped branch appliances for sub-10-millisecond compliance monitoring.
- Voice Services:Cloud PBX and SIP trunking constitute the mature revenue base, with quality-of-service prioritization under FCC net neutrality rulings legitimizing carrier-grade SLAs for VoIP traffic.
- Video Conferencing:4K and spatial audio capabilities differentiate premium tiers, though commoditization pressures mount as baseline quality becomes table stakes.
- Messaging:Persistent chat and EHR-integrated secure messaging consolidate patient care coordination in HIPAA-covered healthcare deployments.
Voice services retains volume leadership; collaboration tools show the steepest expansion trajectory as vendors merge meeting analytics with workflow automation platforms.
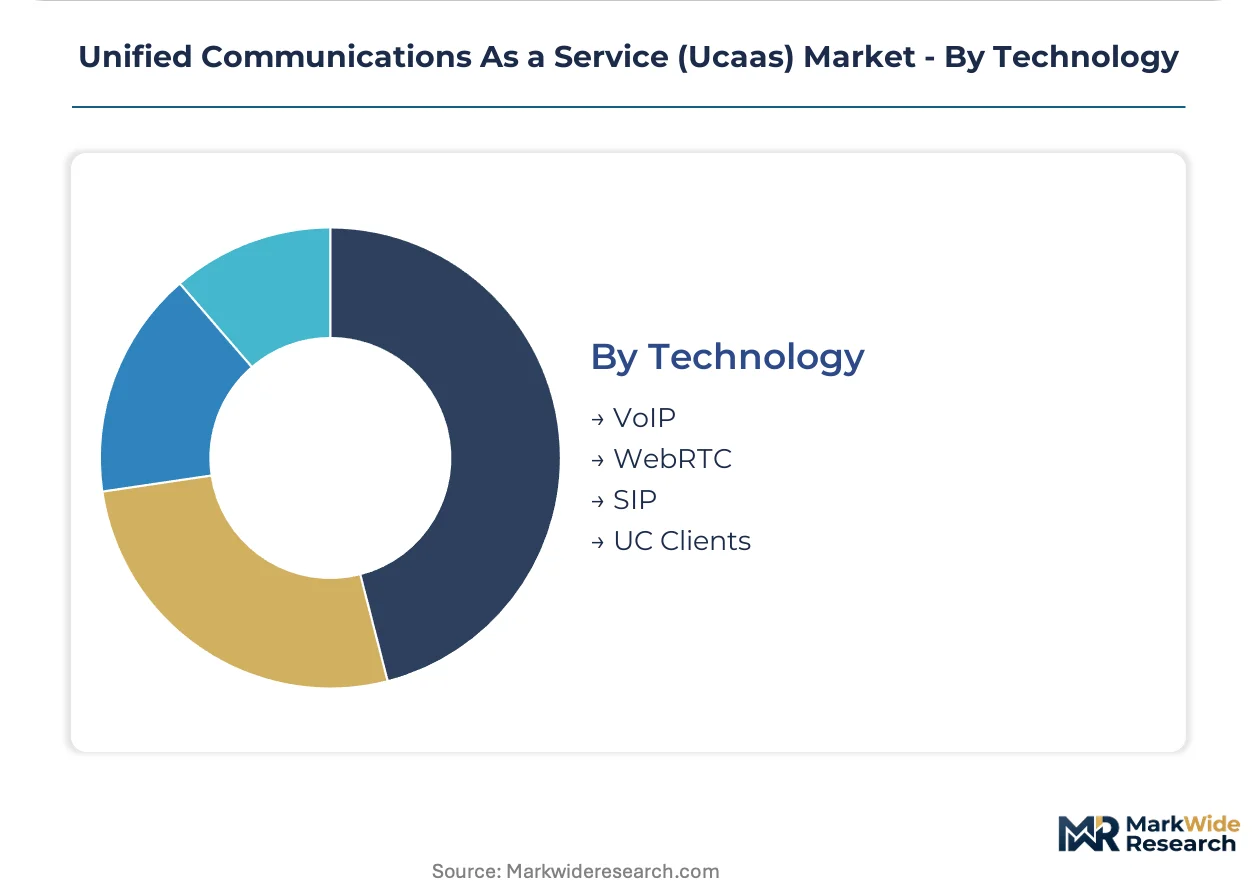
Technology:
Protocol choices determine interoperability scope, security posture, and hardware endpoint compatibility across heterogeneous vendor environments.
- VoIP:Packet-switched voice over IP remains foundational, with G.722 and Opus codecs enabling HD audio across broadband and mobile networks.
- WebRTC:Browser-native real-time communication eliminates client installation friction, accelerating mid-market adoption and guest-access scenarios.
- SIP:Session Initiation Protocol trunking interconnects cloud platforms with carrier networks and legacy PBX infrastructure, though national security certification backlogs in France and Germany delay encrypted gateway approvals.
- UC Clients:Native desktop and mobile applications deliver optimized performance for complex multi-stream video and advanced telephony features.
SIP dominates carrier interconnection; WebRTC is climbing the fastest as browser-based deployment reduces IT administration overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UCaaS consumption patterns diverge sharply by jurisdiction, with German manufacturers demanding hybrid sovereignty while American healthcare systems prioritize HIPAA-integrated telemedicine stacks and Indian BPOs scale from basic VoIP toward full collaboration suites.
United States
Healthcare systems in Texas and Florida are consolidating telemedicine workflows onto unified cloud platforms to eliminate vendor fragmentation in patient care coordination. FCC net neutrality rulings legitimize carrier-grade SLAs for VoIP traffic traversing public internet infrastructure. The Dallas-Fort Worth metro anchors hybrid cloud voice deployments where financial services firms deploy GPU-equipped branch appliances for sub-10-millisecond compliance monitoring.
Germany
Mittelstand manufacturers across Bavaria and Baden-Württemberg procure UCaaS with local session border controllers to satisfy works council data residency requirements. GDPR and the EU AI Act force vendors to maintain separate algorithmic model versions for EU deployments with full audit trails. Stuttgart's automotive supplier ecosystem drives sovereign-hosted instances with certified carbon-neutral operations under CSRD disclosure requirements.
United Kingdom
Mid-market professional services firms in London favor video-first platforms with native CRM connectors for rapid client engagement. The Information Commissioner's Office enforces GDPR-aligned data localization for meeting recordings and biometric analytics. The City of London's financial district concentrates demand for edge-resident media processing that enables real-time compliance monitoring without post-call batch delays.
India
Domestic outsourcing providers in Bangalore and Hyderabad upgrade from basic VoIP to full collaboration suites as TRAI regulations ease international cloud interconnect restrictions. The country's central bank mandates data localization for financial services communications, pushing vendors toward sovereign-hosted instances. The National Capital Region anchors large enterprise deployments where seasonal staffing volatility drives consumption-based licensing negotiations.
France
Banking conglomerates in Paris demand sovereign-hosted instances with algorithmic transparency documentation under EU AI Act risk classification systems. ANSM and CNIL jointly enforce biometric data processing restrictions that disable voiceprint authentication features standard elsewhere. The Île-de-France region concentrates hybrid deployments delayed by national security agency queuing for encrypted voice gateway hardware approvals.
Unified Communications As a Service (Ucaas) Market Vendor Landscape
Capability concentration sits with infrastructure-integrated platforms; scale advantage sits with video-native challengers. The vendor base stratifies across three tiers: hyperscale cloud providers anchoring enterprise retention through identity fabric integration, telecom carriers leveraging network ownership for quality-of-service guarantees, and pure-play collaboration specialists dominating mid-market land-and-expand motions. Dominant competitive moves include strategic partnerships embedding communication tools into CRM and ERP workflows, plus geographic expansion through sovereign cloud footprint construction.
Within the hyperscale tier, Microsoft Corporation and Cisco Systems Inc. anchor enterprise positioning through platform breadth and security certifications respectively. Zoom Video Communications Inc. occupies the video-first specialist archetype that has captured mid-market expansion velocity. These three entities exemplify the competitive fault line between infrastructure-integrated suites and best-of-breed collaboration tools.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Microsoft Corporation |
| RingCentral Inc. |
| 8x8 Inc. |
| Zoom Video Communications Inc. |
| Avaya Inc. |
| IBM Corporation |
| Oracle Corporation |
| Verizon Communications Inc. |
| Others |
Supply Flow & Price Mechanics
GDPR data localization mandates and the EU AI Act's algorithmic transparency requirements create a regulatory chokepoint that compresses both pricing tier spreads and supply chain geography. Vendors must maintain separate infrastructure footprints for sovereign-hosted instances, fragmenting economies of scale while premium positioning attaches to certified carbon-neutral operations under CSRD disclosure requirements.
Pricing Analysis
Long-term subscription contracts anchor enterprise procurement, with metered consumption billing displacing per-seat models in contact center deployments where seasonal staffing volatility renders fixed commitments uneconomic. Price differentiation rests on certification grade—FedRAMP, HIPAA Business Associate Agreements, and EU sovereign cloud attestations—and vertical integration depth into identity fabrics and hardware endpoints. Cost compression in mid-market tiers intensifies as WebRTC browser-native deployment eliminates client installation friction and IT administration overhead. SMEs exhibit highest price sensitivity, negotiating standardized SaaS subscriptions with minimal customization, while large enterprises absorb premium tiers for negotiated data residency clauses and dedicated support tiers.
Supply Chain Analysis
Contract manufacturing concentration for session border controllers and encrypted voice gateways sits with Foxconn, Jabil, and Flex in Taiwan, Mexico, and Malaysia facilities serving North American and European demand. Component sourcing draws from South Korean memory suppliers, Chinese PCB fabricators, and German precision acoustic hardware specialists. Single-source vulnerability concentrates in transatlantic submarine cable landing stations at Virginia and Cornwall, creating latency risk for real-time video routing. Distribution runs through carrier-direct channels for telecom-integrated suites, hyperscaler marketplaces for cloud-native platforms, and value-added resellers serving regulated verticals with compliance consulting bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large German automotive suppliers and French banking conglomerates that negotiate multi-year sovereign-hosted frameworks with custom SLA terms, compressing vendor margin pools.
For Market Incumbents: Entrench platform stickiness through AI-assisted transcription convergence with CRM and ERP workflows, deepening integration debt that raises switching costs. Defend against video-first challengers by accelerating WebRTC browser-native deployment to match mid-market land-and-expand velocity. Prioritize certification investment in FedRAMP High and EU sovereign cloud attestations to maintain premium positioning in regulated verticals. For New Entrants and Emerging Players: Build out sovereign cloud footprints in Germany and France where GDPR and EU AI Act compliance requirements delay hyperscaler responsiveness. Target Indian BPO sector expansion as TRAI regulations ease international cloud interconnect, offering consumption-based licensing that matches seasonal staffing volatility. Pursue channel partnerships with domestic outsourcing providers rather than direct enterprise sales to bypass incumbent relationship density. For Investors and Strategic Acquirers: The market sits at a compliance-differentiation phase that favors vertical-specialist platforms with certified security postures over horizontal collaboration tools. Long-term viability across the projection horizon hinges on AI infrastructure integration and carbon-neutral data center operations under CSRD mandates. Monitor session border controller certification backlogs at French and German national security agencies as an inflection indicator for hybrid deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Footprint Expansion | GDPR and EU AI Act localization requirements force jurisdictional infrastructure isolation in Germany and France. |
| AI-Assisted Transcription Platform Integration | Meeting analytics engines merging with Salesforce and ServiceNow create workflow automation stickiness in financial services. |
| Consumption-Based Licensing Introduction | Metered billing tied to interaction minutes accommodates seasonal staffing volatility in North American retail contact centers. |
| Carbon-Neutral Data Center Certification | CSRD disclosure requirements favor vendors with certified sustainable operations among Stuttgart automotive suppliers. |
| Session Border Controller Certification Acceleration | ANSM and BSI queuing delays for encrypted voice gateways bottleneck hybrid deployments in Paris and Munich. |
Methodological Framework
A standing panel of CTOs, IT procurement officers, platform engineers, and channel partners provided ongoing calibration across primary fieldwork. Secondary validation drew from SEC filings, hyperscaler capex disclosures, carrier interconnection agreements, and sovereign cloud certification registries. Bottom-up sizing of deployment architectures and service types triangulated against top-down market aggregation from vendor revenue disclosures and GPO contract analysis.
Scenario-bracketing anchored projections across conservative, baseline, and aggressive adoption curves for hybrid cloud configurations and AI-embedded collaboration tools. Segmentation modeling spanned deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted penetration rates and replacement-cycle timing for legacy PBX estates, with voice quality SLA legitimization under FCC net neutrality rulings and biometric data processing restrictions under GDPR Article 9 as key demand shapers.
The forecast holds incumbent behavior within observed patterns; aggressive sovereign cloud construction by hyperscalers or rapid TRAI liberalization in India would shift outcomes beyond modeled bounds. Quarterly review of session border controller certification queues, carrier-grade SLA adoption rates, and consumption-based licensing penetration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Unified Monitoring Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
Ucaas in the Manufacturing Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Unified Communication Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
Business Cloud Voip and UC Services Market
Unified Communications
United States SMS and MMS Market
Unified Communications
Ucaas in Energy Market
Unified Communications
High Definition HD Voice Market