
 Ucaas in Energy Market | 2026-2036
Ucaas in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Ucaas in Energy Market Analytics
FERC Order 2222 is hardening the cost-of-entry calculus for energy sector communications infrastructure, forcing utilities to demonstrate real-time interoperability across distributed energy resources. Microsoft Corporation leverages its Azure cloud backbone to anchor utility-grade UCaaS deployments with built-in compliance tooling. Cisco Systems, Inc. competes through hardened edge networking that sustains voice and video continuity across geographically dispersed generation sites. Zoom Video Communications, Inc. differentiates by specializing in low-bandwidth video delivery for field crews operating in remote transmission corridors.
Unified Communications as a Service for energy denotes a cloud-delivered platform integrating voice, video, messaging, and collaboration tools over IP networks with guaranteed uptime thresholds, typically architected for sub-50 millisecond latency to support SCADA-adjacent operations. The primary purpose centers on replacing legacy TDM circuits with elastic, API-ready communication fabrics that synchronize control room dispatch, field maintenance teams, and inter-utility coordination. Cloud-based deployment models are capturing the fastest expansion as utilities retire capital-intensive on-premises switches, while hybrid architectures retain durable share among operators bridging legacy OT systems with modern IT stacks. Voice services maintain the largest revenue pool due to regulatory recording mandates, though collaboration tools are ascending fastest as integrated work management becomes standard across EPC contractor workflows.
FERC, NERC, and the EPA collectively shape UCaaS demand through reliability standards, cybersecurity directives, and emissions reporting protocols that require timestamped, auditable communications. The EU AI Act and GDPR add compliance layers for multinational energy firms routing European operator data through global UCaaS instances. Stakeholders must weigh sovereign cloud requirements against interoperability gains as grid edge intelligence decentralizes decision-making authority.
Market Dynamics
Grid edge intelligence is fragmenting command hierarchies across energy utilities, forcing UCaaS architectures to synchronize thousands of distributed generation nodes with sub-50 millisecond latency requirements. This decentralization is compressing procurement timelines and reshaping vendor qualification criteria.
Growth Catalysts
- NERC CIP Cybersecurity Mandates:North American utilities must replace legacy on-premises PBX systems with cloud-compliant alternatives, creating immediate replacement demand for hardened UCaaS platforms.
- Distributed Solar and Storage Proliferation:Renewable energy providers operating geographically dispersed assets require elastic communication fabrics to coordinate field crews across remote transmission corridors.
- API-Ready Integration:SCADA-adjacent operations demand programmable communication layers that bridge control room dispatch with mobile maintenance teams.
Market Restraints
- OT-IT Convergence Friction:Operational technology systems with decades-long depreciation cycles resist rapid cloud migration, trapping capital in hybrid architectures.
- Sovereign Cloud Fragmentation:EU GDPR and AI Act requirements force multinational energy firms to maintain data residency boundaries, complicating global UCaaS deployments.
- Bandwidth Asymmetry:Remote generation sites in the US Southwest and Australian Outback lack fiber backhaul, constraining real-time video collaboration.
Strategic Opportunities
- Offshore Wind Coordination:European North Sea operators need maritime-optimized UCaaS with satellite failover for turbine maintenance fleets.
- Virtual Power Plant Orchestration:FERC Order 2222 compliance creates demand for timestamped, auditable communications aggregating thousands of behind-the-meter assets.
- AI-Native Compliance Tooling:Automated transcription and sentiment analysis for regulatory recording mandates opens premium pricing tiers.
Industry Challenges
- Cybersecurity Talent Scarcity:Utilities struggle to hire cloud security architects capable of hardening voice and video streams against nation-state targeting.
- Legacy TDM Circuit Retirement:Copper decommissioning timelines misalign with cloud migration budgets, forcing parallel infrastructure maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ucaas in Energy Market |
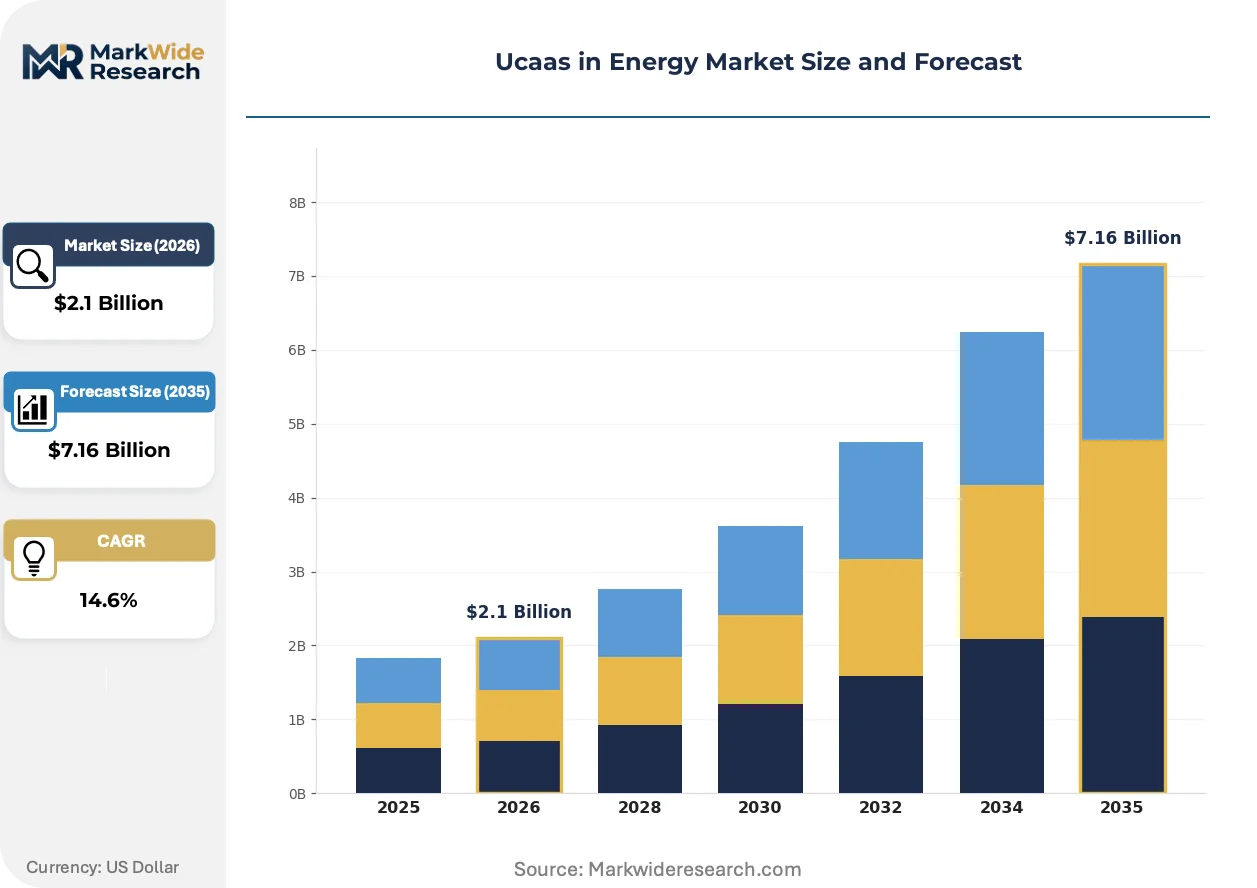
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice Services, Video Conferencing, Messaging Solutions, Collaboration Tools Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Tenant End User: Utilities, Industrial Manufacturers, Renewable Energy Providers, EPC Contractors Integration Level: API Integration, CRM Integration, ERP Integration, Custom Integrations |
| Companies Covered | Microsoft Corporation, Cisco Systems, Inc., Zoom Video Communications, Inc., Verizon Enterprise Solutions, LLC, 8x8, Inc., Avaya Inc., RingCentral, Inc., West Corporation, BT Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ucaas in Energy Market Evolving Landscape
Artificial intelligence is embedding into UCaaS stacks, converting passive communication logs into predictive operational intelligence. This shift is redefining vendor value propositions beyond connectivity toward actionable grid analytics.
Natural language processing is automating incident classification from control room voice traffic, extracting equipment failure signatures before SCADA alerts trigger. Investor-owned utilities in Texas and California are piloting these capabilities during wildfire season. The technology is automating shift handover documentation, compressing knowledge transfer from hours to minutes.
EPA emissions reporting protocols now require timestamped audio verification of fuel-switching decisions at combined-cycle plants. This mandate is forcing UCaaS providers to append immutable blockchain anchors to voice recordings. Gas turbine operators in the US Gulf Coast are upgrading platforms first, driven by state-level methane regulations.
Subscription-based procurement is displacing perpetual licensing for voice services as utilities prioritize operational expenditure flexibility. Engineering-procurement-construction contractors now bundle UCaaS into turnkey plant commissioning packages. This consolidation is most visible in US independent power producer markets, where project finance constraints favor predictable monthly costs.
Ucaas in Energy Market Segmentation
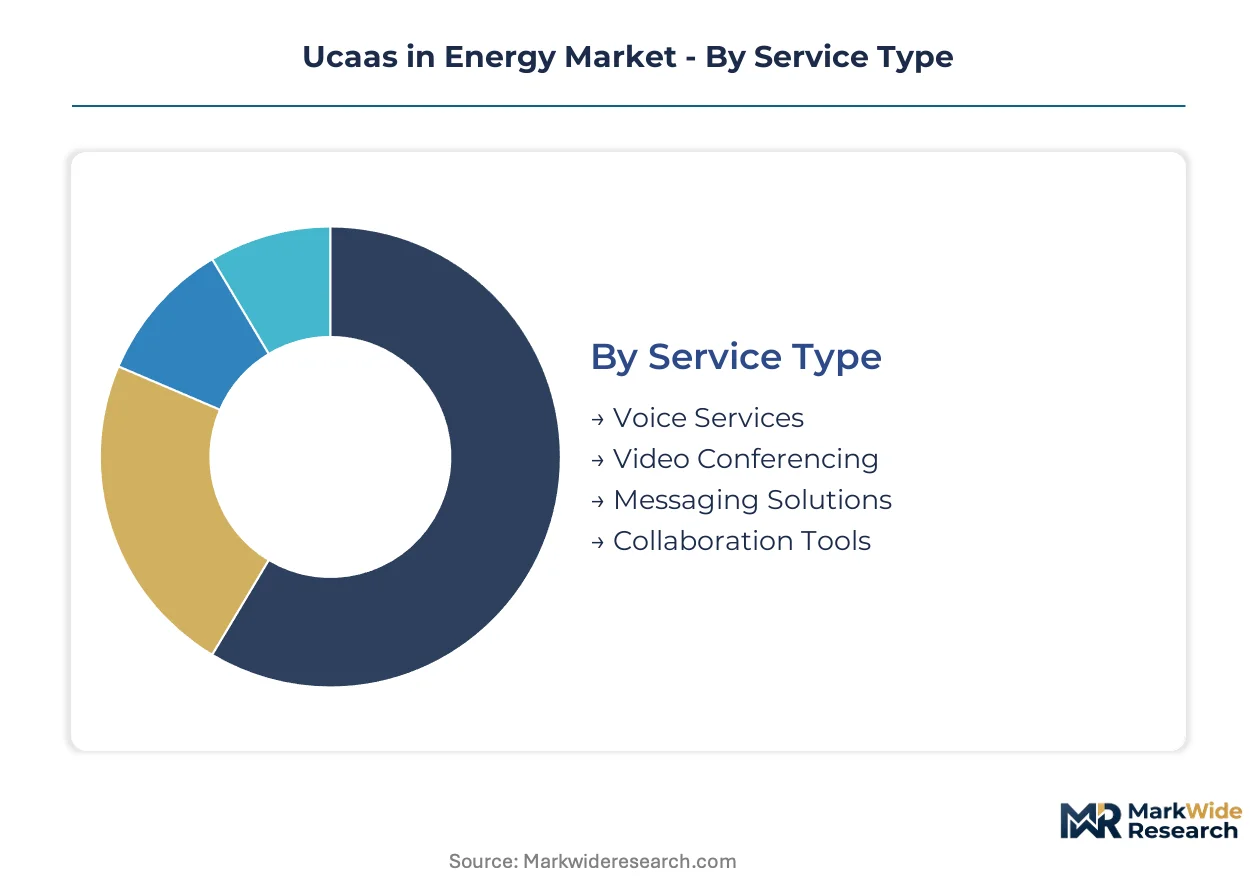
UCaaS procurement in energy diverges sharply by operational maturity and regulatory exposure, with replacement cycles for legacy TDM infrastructure creating divergent upgrade timelines across service categories. Segmentation reveals where capital budgets concentrate versus where subscription models displace perpetual licenses.
Service Type:
Replacement cycles for legacy voice infrastructure are compressing procurement timelines as NERC CIP deadlines force hard cutovers from on-premises PBX systems.
- Voice Services:Circuit-switched replacement platforms with guaranteed uptime thresholds and regulatory call recording capabilities. Demand concentrates among US investor-owned utilities facing NERC CIP compliance deadlines, with EPA emissions protocols requiring timestamped audio verification for fuel-switching decisions.
- Video Conferencing:Low-latency visual collaboration platforms engineered for sub-50 millisecond response times in SCADA-adjacent operations. Renewable energy providers in remote US Southwest transmission corridors drive procurement, constrained by fiber backhaul asymmetry at distributed solar sites.
- Messaging Solutions:Encrypted asynchronous communication with audit trails for shift handover documentation.
- Collaboration Tools:Integrated work management platforms bundling task orchestration with real-time presence indicators.
Voice Services sits at the top of the volume ranking, with Collaboration Tools climbing the fastest.
Deployment Model:
Cost tier differentiation separates capital-intensive perpetual licensing from operational expenditure flexibility favored by project-financed independent power producers.
- Cloud-Based:Fully managed subscription platforms with elastic capacity scaling and built-in compliance tooling. US utilities retiring copper TDM circuits drive fastest expansion, with grid modernization programs mandating API-ready communication fabrics.
- Hybrid:Bridged architectures preserving legacy OT system connectivity while modernizing IT stacks. European multinational firms favor this model to satisfy GDPR data residency requirements without sacrificing interoperability.
- On-Premises:Dedicated infrastructure with full operational control retained by operators with decades-long depreciation cycles.
- Multi-Tenant:Shared infrastructure instances with logical isolation between utility tenants.
Cloud-Based deployment commands the largest addressable base, though Hybrid architectures retain durable share among operators with stranded OT assets.
End User:
Customer type segmentation tracks divergent procurement authority between regulated utilities and project-driven EPC contractors.
- Utilities:Investor-owned and municipal operators with centralized procurement functions and cybersecurity governance mandates. US grid operators facing FERC Order 2222 interoperability requirements represent the core demand concentration.
- EPC Contractors:Engineering-procurement-construction firms bundling UCaaS into turnkey plant commissioning packages. Independent power producers in deregulated US markets favor subscription models to preserve project finance flexibility.
- Renewable Energy Providers:Distributed generation operators coordinating geographically dispersed maintenance fleets.
- Industrial Manufacturers:Cogeneration and captive power operators with hybrid IT-OT environments.
Utilities anchor procurement volume, with EPC Contractors expanding most quickly through bundled service packaging.
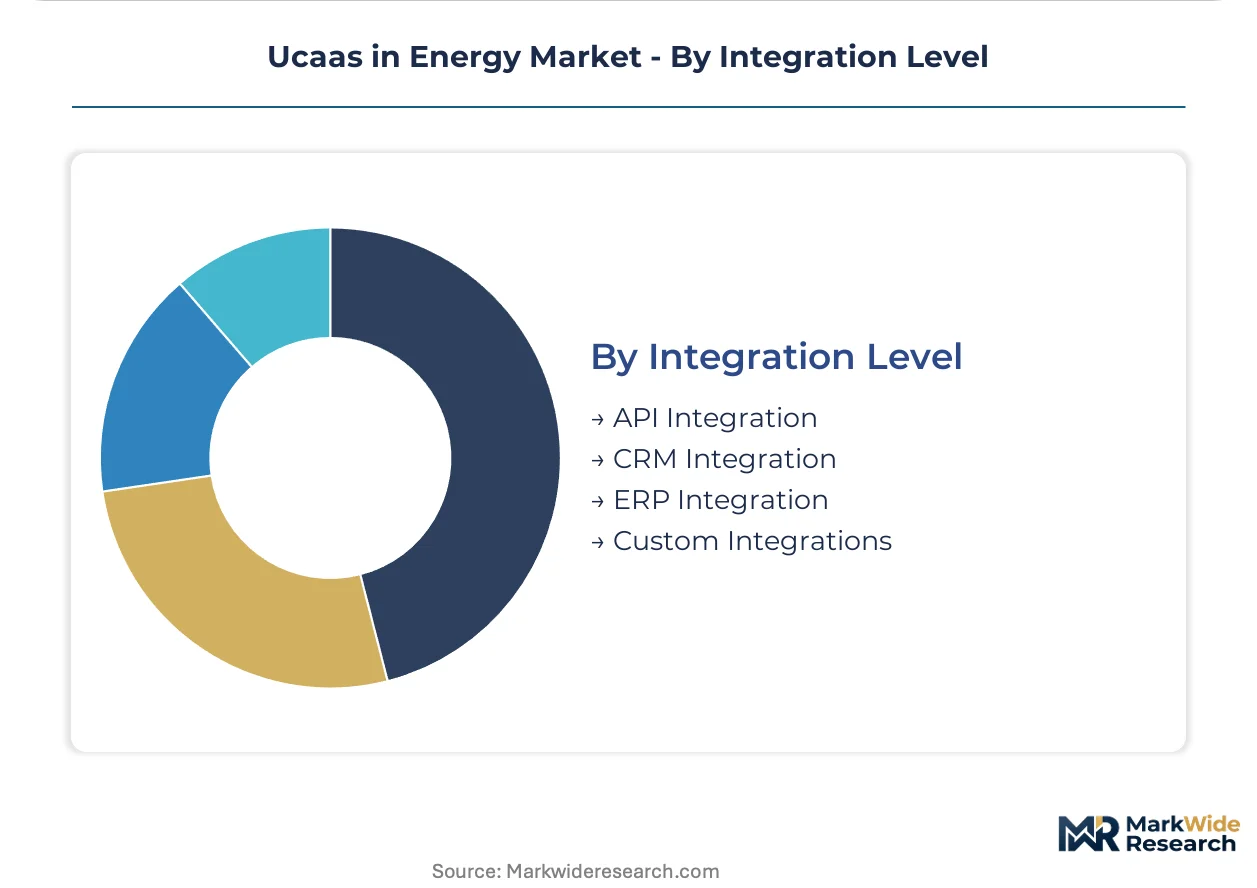
Integration Level:
Application depth determines platform stickiness, with API-ready architectures commanding premium positioning against point-solution alternatives.
- API Integration:Programmable communication layers enabling SCADA system adjacency and automated incident response. Texas and California investor-owned utilities pilot natural language processing for control room voice traffic classification.
- ERP Integration:Financial and asset management system connectivity for maintenance cost tracking and work order synchronization.
- CRM Integration:Customer interaction platforms for retail utility call centers and outage notification systems.
- Custom Integrations:Bespoke development for proprietary operational technology stacks with non-standard protocols.
API Integration leads deployment complexity, with ERP Integration gaining traction fastest among utilities consolidating vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Unified Communications as a Service for energy originated in North American utility control rooms during the 2010s smart grid buildout, then diffused to European renewable operators and Asia-Pacific industrial zones as distributed generation architectures matured.
United States
Grid modernization programs and FERC Order 2222 interoperability mandates are accelerating UCaaS procurement across investor-owned utilities and independent power producers. NERC CIP cybersecurity standards compel replacement of legacy on-premises PBX systems with cloud-compliant alternatives. The Texas ERCOT grid and California ISO control centers represent concentrated deployment zones for SCADA-adjacent communication platforms.
Germany
Offshore wind coordination in the North Sea and Baltic Sea drives maritime-optimized UCaaS demand with satellite failover requirements. The EU AI Act and GDPR impose data residency constraints that favor hybrid deployment architectures over pure cloud models. Industrial clusters in Lower Saxony and Schleswig-Holstein anchor turbine maintenance fleet communication infrastructure.
United Kingdom
Ofcom regulatory frameworks and national cybersecurity strategies shape procurement specifications for critical national infrastructure operators. The North Sea energy transition and decommissioning programs create demand for ruggedized field communication systems. Aberdeen and the Scottish Highlands concentrate deployment activity among offshore service vessel operators.
Australia
Remote generation assets in the Southwest and Outback regions face bandwidth asymmetry constraints that favor low-bandwidth video and voice optimization. The Australian Energy Market Operator's reliability standards mandate timestamped, auditable communications for distributed energy resource aggregation. Western Australia's Pilbara mining-energy corridor and Queensland's solar belt represent high-priority deployment zones.
Japan
METI grid flexibility directives and post-Fukushima resilience mandates drive UCaaS adoption for decentralized power system coordination. The country's stringent telecommunications regulations require domestic data processing for critical infrastructure communications. Tokyo Electric's service territory and Kyushu's renewable energy zones concentrate vendor engagement activity.
Ucaas in Energy Market Competitive Landscape
The competitive structure tilts toward cloud-native platform providers with utility-grade compliance tooling, though legacy telecommunications carriers retain durable positions through existing infrastructure relationships. Market concentration is moderate, with three to five dominant platforms capturing the majority of enterprise utility deployments alongside a long tail of specialized regional providers. Strategic archetypes include hyperscale cloud anchors, hardened networking specialists, and verticalized SaaS vendors. Competitive dynamics center on API ecosystem breadth and compliance automation capabilities rather than raw connectivity pricing.
Among hyperscale platform providers, Microsoft Corporation and Cisco Systems, Inc. occupy anchor positions representing divergent architectural philosophies—cloud-native elasticity versus edge-hardened continuity. Zoom Video Communications, Inc. exemplifies the specialized SaaS archetype, targeting bandwidth-constrained field operations with optimized video delivery. These three entities collectively illustrate how vendor selection in energy UCaaS hinges on latency requirements, legacy system adjacency, and regulatory jurisdiction rather than generic collaboration feature sets.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Zoom Video Communications, Inc. |
| Verizon Enterprise Solutions, LLC |
| 8x8, Inc. |
| Avaya Inc. |
| RingCentral, Inc. |
| West Corporation |
| BT Group plc |
| Others |
Value Network & Pricing Analysis
Cloud-native platform providers rolled up through private-equity consolidation now anchor pricing discipline across utility-grade UCaaS deployments, with subscription economics favoring operational expenditure models that compress supplier margins while extending customer lifetime value.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates UCaaS procurement, with differentiation driven by API integration depth and NERC CIP certification tier. Premium tiers command substantial uplift for automated compliance tooling and sub-50 millisecond latency guarantees. Cost compression in standard tiers is intensifying because hyperscale cloud providers bundle communication services with existing enterprise agreements. Independent power producers exhibit highest price sensitivity due to project finance constraints, while investor-owned utilities prioritize reliability over unit cost.
Supply Chain Analysis
Hyperscale cloud infrastructure rests on concentrated data center capacity in the United States, Ireland, and Singapore, with submarine cable networks and satellite failover systems as critical inputs. Single-source vulnerability in submarine cable landing stations creates geographic chokepoint exposure for offshore wind coordination. Distribution runs through direct enterprise sales teams and systems integrators serving EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UCaaS in energy market compounds steadily as regulatory mandates harden compliance requirements across North American utilities.
For Market Incumbents: Deploy API ecosystem expansion to deepen SCADA system adjacency and automate NERC CIP audit trails. Harden edge networking capabilities to sustain voice continuity across bandwidth-constrained generation sites. Consolidate vendor relationships with EPC contractors through bundled commissioning packages. Address emerging threat from verticalized SaaS vendors targeting renewable energy providers with specialized field crew optimization. For New Entrants and Emerging Players: Begin with maritime-optimized UCaaS for European offshore wind maintenance fleets, where satellite failover requirements and EU data residency constraints fragment incumbent positioning. Target Australian distributed solar operators facing fiber backhaul asymmetry in the Pilbara and Queensland solar belt. Pursue white-label partnerships with EPC contractors to embed communication services into turnkey plant commissioning. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid deployment specialists bridging legacy OT systems with cloud-native stacks, as stranded asset complexity deters pure-play cloud entrants. Long-term viability hinges on compliance automation capabilities deepening regulatory moats. Watch FERC Order 2222 implementation velocity as inflection indicator for virtual power plant orchestration demand.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Architecture | Enables SCADA-adjacent operations with sub-50 millisecond latency for Texas and California grid operators. |
| Compliance Automation Layer | Automates NERC CIP audit trails and EPA emissions timestamping for Gulf Coast gas turbine operators. |
| Maritime Connectivity Bundle | Combines satellite failover with ruggedized hardware for North Sea offshore wind maintenance fleets. |
| EPC Channel Partnership | Embeds UCaaS into turnkey commissioning packages for US independent power producer markets. |
| Hybrid Deployment Bridge | Preserves legacy OT connectivity while modernizing IT stacks for GDPR-constrained European multinationals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, grid operators, and cybersecurity governance leads with secondary validation from EIA data, FERC filings, IEA reports, and project development databases. Bottom-up deployment tracking across investor-owned utilities and independent power producers was triangulated against top-down market sizing from hyperscaler enterprise revenue disclosures.
Segment-weighted modeling applied deployment model, end-user type, integration complexity, and regional regulatory framework as primary stratification dimensions across the analysis window. CAGRs were derived from fitted growth curves calibrated to NERC CIP compliance deadline schedules and copper TDM circuit retirement timelines. Forecast inputs incorporated grid modernization program budgets and FERC Order 2222 implementation trajectories.
Caveats apply where NERC CIP deadline extensions or sovereign cloud fragmentation could materially shift the outlook. Forecasts reflect assumptions about OT-IT convergence velocity and bandwidth infrastructure buildout in remote generation corridors. A small set of named triggers—including FERC interoperability rulemaking, EU AI Act enforcement patterns, and hyperscale cloud pricing actions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Business Cloud Voip and UC Services Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
United States SMS and MMS Market
Unified Communications
Cloud UC Calling Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
Ucaas in Banking Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
High Definition HD Voice Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Unified Monitoring Market