
 Global Mobile Voip Market | 2026-2036
Global Mobile Voip Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Voip Market Foresight
South Korea's gigabit broadband expansion is reconfiguring how carriers bundle VoIP with fiber subscriptions. Google LLC leverages its Android ecosystem to pre-integrate Google Meet dial-in capabilities across Samsung and Xiaomi devices. Microsoft Corporation anchors enterprise migration from Skype for Business to Teams Phone, sustaining recurring revenue through E5 licensing tiers. Zoom Video Communications Inc. competes by extending its carrier-grade SBC partnerships to guarantee PSTN interoperability in regulated jurisdictions.
Mobile VoIP transmits voice and multimedia communications over IP networks using codecs such as Opus and AMR-WB, compressing audio to 6-128 kbps while maintaining toll-quality mean opinion scores above 3.5. The technology replaces circuit-switched telephony with packetized delivery, enabling unified communications platforms to merge voice, video, and messaging into single-client experiences. Cloud-based deployment leads in new implementations as hyperscalers absorb infrastructure capex, though hybrid architectures persist among financial services firms with latency-sensitive contact centers. Video calls within the application segment are displacing standalone conferencing tools as native mobile OS dialers embed visual communication by default.
The FCC enforces CALEA lawful intercept mandates on U.S. VoIP providers, while the EU's GDPR and proposed ePrivacy Regulation constrain metadata retention for consumer-grade services. India's TRAI imposes domestic routing requirements on international VoIP gateways, complicating cross-border service delivery for foreign platforms. Stakeholders must monitor how Brazil's ANATEL spectrum auctions and Saudi Arabia's CITC cloud localization rules alter the cost structure of regional mobile VoIP expansion.
Market Dynamics
Enterprise migration from legacy PBX infrastructure to cloud-native unified communications is compressing carrier revenue models while redistributing value toward over-the-top platform providers. The FCC's net neutrality rulings and the EU's Digital Markets Act are simultaneously reconfiguring interconnection economics and platform access obligations.
Growth Catalysts
- India's TRAI domestic routing mandates:Local data center requirements for international gateways are accelerating indigenous infrastructure buildout and reducing latency for mass-market VoIP services.
- Enterprise distributed workforce normalization:Video-first collaboration protocols are displacing audio-only conferencing as default communication standards across financial services and technology sectors.
- Opus codec adoption:Adaptive bitrate compression algorithms are enabling toll-quality voice delivery over congested last-mile networks previously unsuitable for real-time IP communications.
Market Restraints
- CALEA lawful intercept compliance:The FCC mandates real-time surveillance capabilities that increase operational complexity and capital expenditure for U.S.-based service providers.
- Spectrum auction concentration:Brazil's ANATEL licensing processes favor incumbent mobile network operators with sufficient balance sheet capacity to bid for exclusive 5G bands.
- Legacy PSTN interoperability costs:Carrier-grade session border controller maintenance and SS7 gateway fees persist as structural cost anchors for hybrid deployment architectures.
Strategic Opportunities
- Saudi Arabia CITC cloud localization rules:Data sovereignty requirements are creating first-mover advantages for regional hyperscale partnerships and sovereign cloud infrastructure.
- Embedded dialer convergence:Native mobile OS integration of visual communication protocols is opening distribution channels previously controlled by hardware manufacturers.
- South Korea gigabit fiber bundling:KT Corporation and SK Broadband are redefining subscriber economics by packaging VoIP with symmetric broadband at price points inaccessible to copper-based competitors.
Industry Challenges
- GDPR metadata retention constraints:The EU's proposed ePrivacy Regulation creates operational friction for consumer-grade services requiring call detail record analytics for fraud detection.
- Real-time media engineering talent scarcity:Deep expertise in WebRTC optimization, jitter buffer management, and packet loss concealment remains concentrated among a limited pool of specialists.
- Hybrid architecture integration complexity:Financial services contact centers with sub-150 millisecond latency requirements struggle to reconcile cloud elasticity with on-premises session control reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Voip Market |
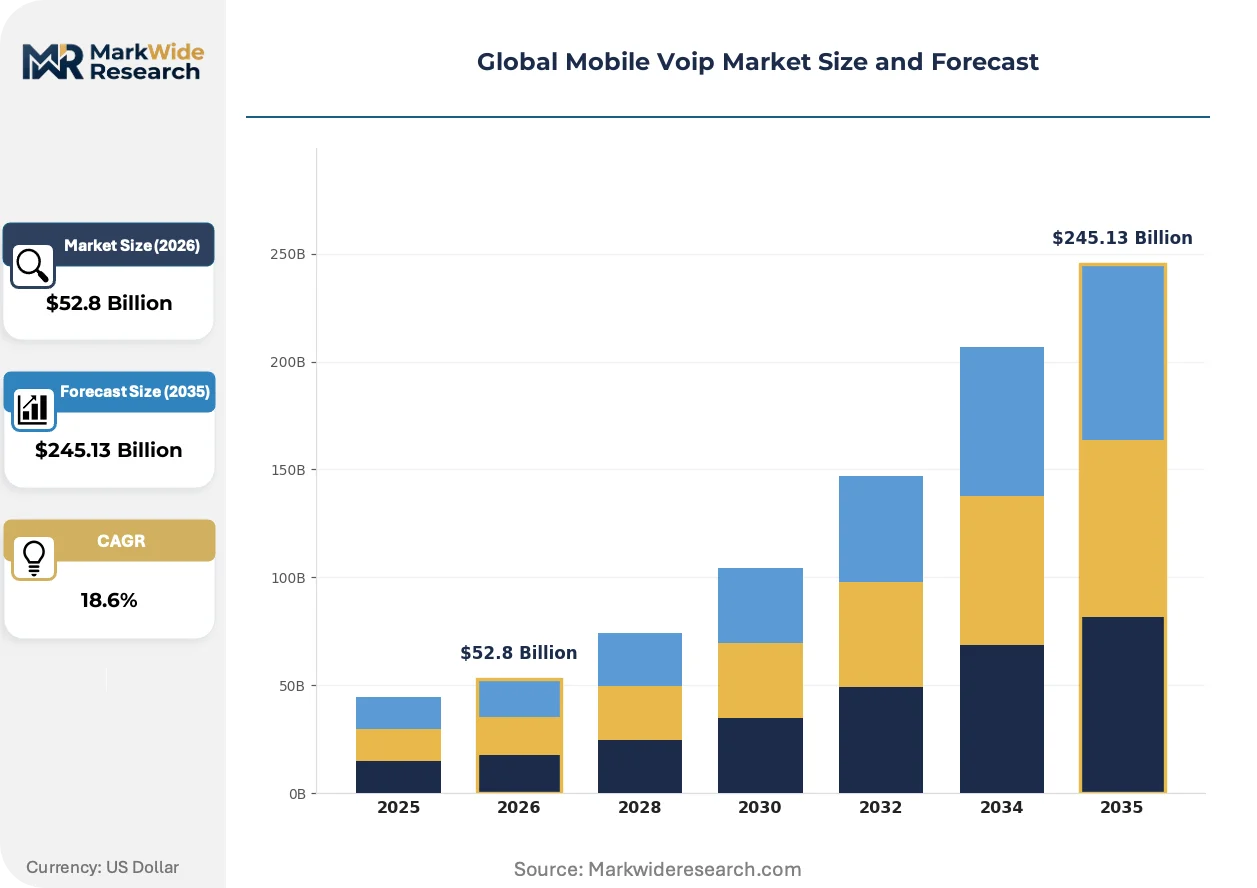
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $245.13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice Calls, Video Calls, Conference Calling, Messaging, Presence Services Deployment: Cloud-Based, On-Premises, Hybrid, Hosted PBX, Managed Services End User: Telecommunication Operators, Enterprises, Call Centers, Individual Consumers, Government Agencies Application: Unified Communications, Customer Support, Remote Workforce, Social Networking, Education |
| Companies Covered | Meta Platforms Inc., Apple Inc., Google LLC, Microsoft Corporation, Zoom Video Communications Inc., RingCentral Inc., Cisco Systems Inc., 8x8 Inc., Vonage Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Voip Market Shifts & Advancements
Codec virtualization and edge computing redistribution are converging to collapse the distinction between carrier infrastructure and application-layer services. Regulatory fragmentation across data localization mandates is forcing architectural decisions that prioritize geographic compliance over technical optimization.
WebRTC is virtualizing browser-based real-time communications without requiring dedicated client installations. Enterprise IT departments are adopting it for customer-facing contact centers and internal collaboration tools alike. The technology is virtualizing traditional session border controller functions into software-defined perimeter architectures that scale horizontally across commodity cloud infrastructure.
The EU's Digital Markets Act interoperability mandates are compelling dominant messaging platforms to expose APIs for cross-platform voice and video connectivity. This industrial consequence is eroding proprietary ecosystem lock-in that previously protected incumbent communication service providers. Regulated industries in Germany and France are responding by pre-negotiating technical standards through ETSI working groups before national implementations crystallize.
Consumption patterns among Indian mass-market subscribers are shifting from metered voice minutes toward unlimited data plans that normalize VoIP as default telephony. Reliance Jio's pricing architecture has compressed switching costs to near-zero, displacing traditional prepaid recharge behaviors. This behavioral pivot is most visible in Mumbai and Delhi metropolitan clusters where smartphone penetration exceeds feature phone retention among price-sensitive demographics.
Global Mobile Voip Market Segmentation
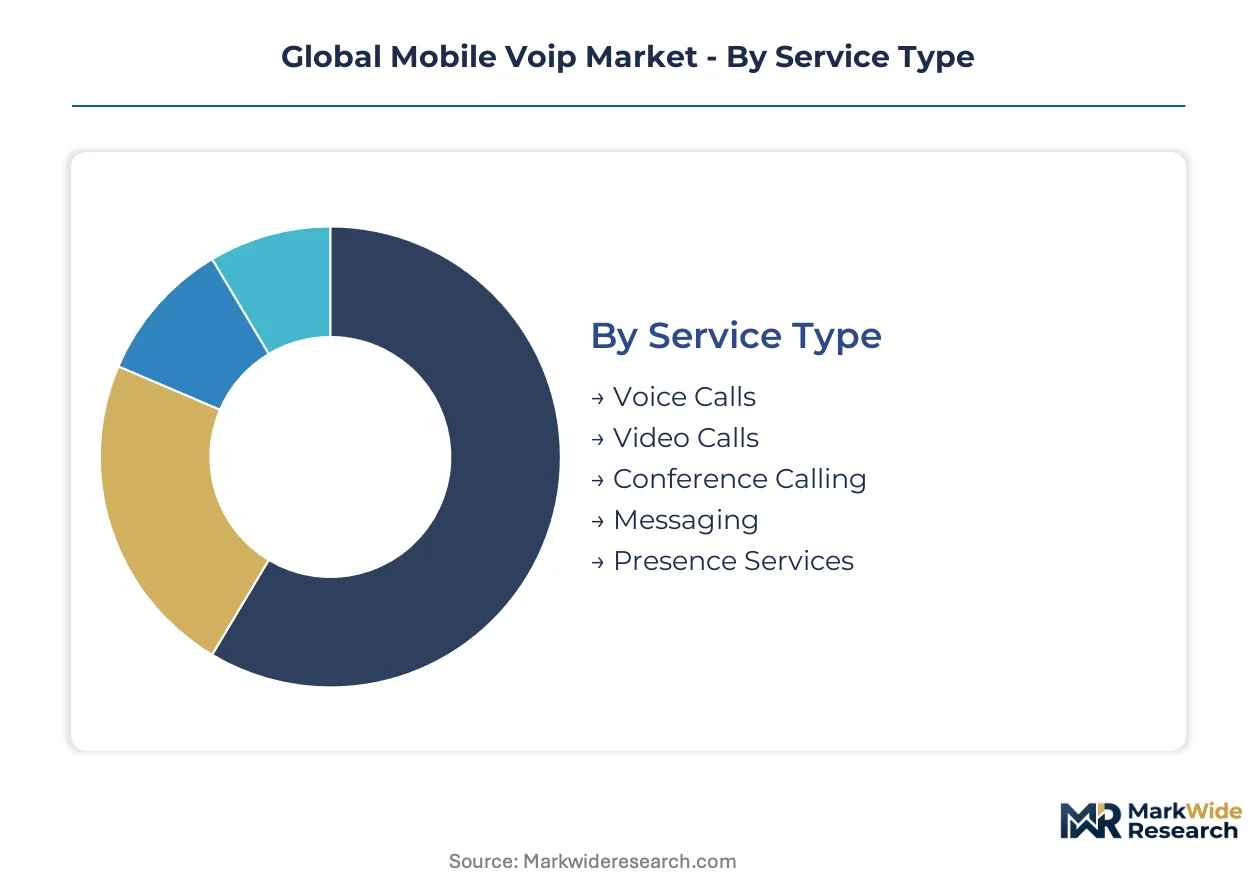
Mobile VoIP market segmentation reveals distinct technical requirements and procurement patterns across service architectures. Deployment choices directly determine latency sensitivity, compliance scope, and integration complexity for end users.
Service Type:
After-sales-service intensity varies sharply across service modalities, with real-time media troubleshooting demanding specialized engineering support that messaging services rarely require.
- Video Calls:Adaptive bitrate protocols consume 500-2000 kbps while maintaining sub-200ms latency thresholds for perceptual synchrony. Demand concentrates among distributed enterprises in Germany and France where ETSI-standardized interoperability mandates are compressing proprietary ecosystem advantages.
- Conference Calling:Multi-party bridging architectures require centralized mixing or selective forwarding units that scale participant counts beyond 50 without degradation. Financial services contact centers in Mumbai and Delhi metropolitan clusters are displacing audio-only legacy systems as default collaboration infrastructure.
- Voice Calls:Narrowband and wideband codec selection determines toll-quality delivery over congested last-mile networks.
- Messaging:Asynchronous text and rich media exchange operates with relaxed latency requirements compared to real-time services.
- Presence Services:Availability status broadcasting enables intelligent routing decisions across unified communications platforms.
Video Calls holds the largest share; momentum sits with Conference Calling.
Deployment:
Cost tier stratification separates hyperscale cloud absorption of infrastructure capex from capital-intensive on-premises ownership models.
- Cloud-Based:Hyperscalers absorb server, storage, and network infrastructure costs while delivering elastic scaling through API-driven orchestration. Technology sector enterprises in the United States are migrating contact center workloads to avoid FCC-mandated CALEA compliance hardware investments.
- Hybrid:Split architectures maintain session control on-premises while bursting media processing to cloud edge nodes during demand spikes. Financial services firms with sub-150 millisecond latency requirements in São Paulo are preserving on-premises session border controllers while offloading transcoding.
- On-Premises:Complete infrastructure ownership persists where data sovereignty or latency constraints prohibit external processing.
- Hosted PBX:Third-party management of private branch exchange functionality without customer facility equipment.
- Managed Services:Outsourced operational responsibility including monitoring, patching, and capacity planning.
Cloud-Based deployment dominates new implementations; Hybrid architectures are expanding most quickly among regulated industries.
End User:
Customer type determines procurement authority, with enterprise IT departments negotiating E5 licensing tiers while individual consumers respond to prepaid data pricing.
- Enterprises:Multi-site organizations with centralized IT governance and recurring software licensing budgets. Microsoft Corporation's Teams Phone migration programs are capturing share across North American and European headquarters locations.
- Individual Consumers:Mass-market subscribers with price-sensitive usage patterns and minimal switching costs. Reliance Jio's unlimited data plans in India have normalized VoIP as default telephony among Mumbai and Delhi smartphone users.
- Telecommunication Operators:Carrier wholesale requirements for PSTN interconnection and lawful intercept compliance.
- Call Centers:High-volume inbound and outbound operations with workforce management integration needs.
- Government Agencies:Classified and unclassified communication requirements with domestic routing mandates.
Enterprises command the largest revenue pool; Individual Consumers are gaining share fastest through emerging market data plan normalization.
Application:
Volume concentration tracks workforce distribution patterns, with remote collaboration tools displacing co-located communication infrastructure.
- Remote Workforce:Home and mobile employee connectivity requiring VPN-agnostic session establishment and bandwidth adaptation. Enterprise adoption accelerated as distributed workforces replaced legacy PBX infrastructure across technology and financial services sectors.
- Unified Communications:Integrated voice, video, messaging, and presence within single-client experiences. Google LLC's Android ecosystem pre-integration across Samsung and Xiaomi devices is collapsing standalone application procurement decisions.
- Customer Support:Agent-facing contact center integration with CRM and workforce optimization platforms.
- Social Networking:Consumer-grade peer-to-peer communication embedded within platform ecosystems.
- Education:Institutional learning management system integration for virtual classroom delivery.
Remote Workforce applications hold the largest share; Unified Communications demonstrates the steepest expansion trajectory as native OS dialers embed visual protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India treats mobile VoIP as default telephony through unlimited data plans, while the United States and Germany preserve enterprise-grade PSTN interconnection as a distinct premium tier. This consumption-mix differential shapes infrastructure investment priorities and regulatory compliance burdens across national markets.
United States
Enterprise distributed workforces drive cloud-native unified communications adoption across technology and financial services sectors. The FCC enforces CALEA lawful intercept mandates that increase operational complexity for domestic service providers. San Francisco and New York metropolitan clusters concentrate demand for carrier-grade session border controller deployments among latency-sensitive contact centers.
Germany
ETSI-standardized interoperability mandates compress proprietary ecosystem advantages for enterprise video collaboration platforms. The EU's Digital Markets Act and proposed ePrivacy Regulation constrain metadata retention for consumer-grade fraud detection systems. Munich and Frankfurt financial services hubs sustain hybrid architecture demand reconciling cloud elasticity with sub-150 millisecond session control reliability.
India
Reliance Jio's pricing architecture has normalized VoIP as default telephony among mass-market smartphone subscribers. TRAI imposes domestic routing requirements on international gateways that accelerate indigenous data center buildout. Mumbai and Delhi metropolitan clusters exhibit complete displacement of traditional prepaid recharge behaviors among price-sensitive demographics.
South Korea
KT Corporation and SK Broadband bundle symmetric gigabit fiber with VoIP at price points inaccessible to copper-based competitors. The country's national telecommunications regulator shapes spectrum allocation for 5G standalone networks enabling ultra-reliable low-latency communication. Seoul Capital Area subscribers consume video-first protocols as default communication standards across enterprise and consumer segments.
Brazil
Financial services contact centers in São Paulo preserve on-premises session border controllers while offloading transcoding to cloud edge nodes. ANATEL spectrum auction processes favor incumbent mobile network operators with sufficient balance sheet capacity for exclusive 5G band acquisition. São Paulo's enterprise technology corridor concentrates hybrid deployment demand among regulated institutions with sub-150 millisecond latency requirements.
Global Mobile Voip Market Competitive Landscape
Capability concentration sits with specialized real-time media engineering firms; scale advantage sits with hyperscale cloud platforms absorbing infrastructure capex. The vendor base stratifies across three tiers: native mobile OS ecosystem owners, enterprise unified communications platform providers, and carrier-grade infrastructure specialists. Dominant competitive moves include strategic partnerships for PSTN interoperability certification and embedded dialer pre-integration across device manufacturer supply chains.
Within the hyperscale platform tier, Google LLC and Microsoft Corporation exemplify divergent ecosystem strategies. Meta Platforms Inc. occupies a position bridging consumer social networking with enterprise communication migration. Zoom Video Communications Inc. anchors the carrier-grade interoperability specialist archetype through session border controller partnerships. These three entities collectively represent the competitive tension between application-layer service virtualization and traditional telecommunications infrastructure retention.
| Leading Market Players |
|---|
| Meta Platforms Inc. |
| Apple Inc. |
| Google LLC |
| Microsoft Corporation |
| Zoom Video Communications Inc. |
| RingCentral Inc. |
| Cisco Systems Inc. |
| 8x8 Inc. |
| Vonage Holdings Corporation |
| Others |
Supply & Pricing Matrix
Hyperscaler cloud infrastructure concentration in the United States and Western Europe concentrates margin capture downstream with platform providers rather than component vendors. This upstream consolidation enables subscription-tiered pricing models that compress legacy carrier revenue pools while redistributing value toward application-layer service virtualization.
Pricing Analysis
Long-term enterprise offtake contracts dominate procurement for cloud-native unified communications platforms, while spot-based consumption persists among individual consumers responding to prepaid data pricing. Three-tier pricing structure across premium, standard, and economy levels differentiates by codec quality, compliance certification tier, and after-sales engineering support intensity. Pricing pressure stems from Reliance Jio's unlimited data plans in India normalizing VoIP as default telephony at near-zero marginal cost. Enterprise IT departments demonstrate lowest price sensitivity due to E5 licensing budget authority, while mass-market smartphone subscribers in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Upstream feedstock for real-time media infrastructure draws from Taiwan for semiconductor fabrication, South Korea for memory components, and the United States for hyperscaler cloud orchestration platforms. Session border controller hardware, WebRTC optimization chipsets, and edge computing nodes constitute critical component dependencies. Supply chain risk centers on single-source vulnerability for specialized real-time media engineering talent concentrated among limited specialist pools. Distribution runs through direct enterprise sales channels for unified communications platforms and bundled fiber subscriptions for consumer-grade services in South Korea and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global Mobile VoIP sits in early-cycle expansion as enterprise distributed workforces displace legacy PBX infrastructure and emerging market data plans normalize VoIP as default telephony. Mass-market adoption tailwinds in India and South Korea justify capacity positioning ahead of saturation.
For Market Incumbents: Pre-empt margin compression from open-source WebRTC virtualization by deepening proprietary codec optimization and embedded dialer pre-integration across Samsung and Xiaomi device supply chains. Threat substitution from browser-based real-time communications without dedicated client installations demands defensive certification investment in carrier-grade PSTN interoperability. Priority lever sits with vertical integration into session border controller hardware to preserve hybrid architecture revenue streams. For New Entrants and Emerging Players: Pursue sovereign cloud infrastructure partnerships in Saudi Arabia where CITC localization rules create first-mover data sovereignty advantages unavailable to hyperscale incumbents. Most penetrable white-space targets regional hyperscale partnerships and indigenous data center buildout for TRAI-compliant international gateways. Go-to-market angle emphasizes latency-optimized domestic routing for financial services contact centers in São Paulo and Mumbai metropolitan clusters. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed carrier-grade infrastructure specialists possessing session border controller partnerships and SS7 gateway certification depth. Long-term viability frames around 5-10 year enterprise migration from on-premises PBX to cloud-native unified communications with hybrid persistence among regulated industries. Acquisition target archetype combines real-time media engineering expertise with regulatory compliance certification in multiple jurisdictions. Signal to watch is ANATEL spectrum auction outcomes altering 5G standalone network economics for ultra-reliable low-latency communication.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Google LLC's Android ecosystem pre-integration collapses standalone application procurement decisions across Samsung and Xiaomi devices. |
| Strategic Partnership | Zoom Video Communications Inc.'s carrier-grade SBC partnerships guarantee PSTN interoperability in FCC-regulated and EU jurisdictions. |
| Acquisition of Specialist Firm | Real-time media engineering talent scarcity makes WebRTC optimization and jitter buffer management firms attractive consolidation targets. |
| Geographic Expansion | Microsoft Corporation's Teams Phone migration programs capture enterprise share across North American and European headquarters locations. |
| Product Launch | Reliance Jio's unlimited data plan architecture normalizes VoIP as default telephony among Mumbai and Delhi smartphone subscribers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners; and secondary validation through SEC filings, hyperscaler capex disclosures, App Annie mobile application data, and regulatory filings with the FCC and TRAI. Bottom-up triangulation across service type, deployment model, and end-user segments reconciled with top-down macroeconomic framing.
Forecast inputs considered enterprise distributed workforce normalization, Opus codec adoption curves, and domestic routing mandate implementation across the projection horizon. Segmentation dimensions modeled include service type, deployment architecture, end-user category, and regional regulatory cluster. CAGRs derived from historical penetration rates adjusted for technology substitution effects and compliance cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in emerging market data pricing, spectrum auction timing, or hyperscaler infrastructure investment cycles would shift the trajectory. Forecasts reflect assumptions about regulatory implementation pace and enterprise IT budget authority persistence. Cross-checking against hyperscaler earnings call commentary and carrier capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
High Definition HD Voice Market
Unified Communications
Unified Monitoring Market
Unified Communications
United States SMS and MMS Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Unified Communication Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
Ucaas in the Manufacturing Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
Business Cloud Voip and UC Services Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Ucaas in Banking Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market