
 Unified Communication (UC) and Business Headsets Market | 2026-2036
Unified Communication (UC) and Business Headsets Market Size, Share, and Industry Trends Forecast 2026-2036
Unified Communication (UC) and Business Headsets Market Insights
Enterprise procurement is rotating from contact center bulk buyers toward corporate IT departments outfitting hybrid workforces. GN Store Nord A/S (Jabra) leverages its wireless engineering heritage to dominate premium noise-cancellation tiers. Logitech anchors mid-market volume through deep retail and e-commerce channel control. Sennheiser Electronic GmbH & Co. KG differentiates on broadcast-grade audio fidelity for executive and creative professional segments.
Unified Communication and Business Headsets comprise audio peripheral hardware engineered for enterprise voice and video workflows, typically incorporating electret condenser microphones with 100 Hz–10 kHz frequency response, active noise cancellation algorithms, and USB-C or Bluetooth 5.x connectivity for seamless platform integration. Wireless headsets lead product type revenue due to enterprise mobility mandates, while speakerphones represent the fastest-growing category as huddle room deployments multiply. Corporate offices anchor end user demand, though remote worker segments are expanding fastest as employers standardize home office equipment stipends.
FCC equipment authorization and CE marking frameworks enforce electromagnetic compatibility and RF exposure thresholds that shape hardware design cycles and market access timelines. Ecodesign regulations under the EU Green Deal are pressuring manufacturers toward modular construction and repairable architectures. Stakeholders must monitor how UC platform certification programs from Microsoft Teams and Zoom evolve their peripheral compatibility requirements, as these gatekeeper standards increasingly determine which headset models qualify for enterprise procurement shortlists.
Market Dynamics
Enterprise IT departments are displacing contact center bulk buyers as the primary procurement authority, with hybrid workforce mandates forcing hardware refresh cycles and platform certification requirements dictating vendor shortlists.
Growth Catalysts
- Contact center modernization:Corporate office retrofits in the United States, Germany, and Japan are accelerating hardware replacement timelines as legacy desk phone systems reach end-of-life.
- FCC equipment authorization rules:Tightening electromagnetic compatibility standards in the United States are filtering out non-compliant suppliers and consolidating procurement toward certified vendors.
- Bluetooth 5.x connectivity:Enterprise mobility mandates are pulling wireless headset adoption ahead of tethered alternatives across knowledge worker segments.
Market Restraints
- RF component concentration:Bluetooth chipset supply concentrates among a limited supplier base, exposing lead time volatility for headset manufacturers.
- CE marking friction:European electromagnetic compatibility testing timelines extend market access windows by four to six months for new product introductions.
- Smartphone speaker substitution:Improved built-in audio quality in mobile devices reduces peripheral necessity for casual video calls in remote worker segments.
Strategic Opportunities
- EU Green Deal ecodesign regulations:Modular construction mandates are creating first-mover advantage for manufacturers with repairable architectures and circular supply chains.
- Huddle room speakerphone demand:Small meeting space deployments represent an underpenetrated application segment with faster replacement cycles than desk-bound headsets.
- Home office equipment stipends:Employer standardization of remote worker allowances is opening direct-to-employee channel models bypassing traditional IT procurement.
Industry Challenges
- UC platform certification timelines:Microsoft Teams and Zoom peripheral compatibility programs require six to nine month validation cycles that compress product launch windows.
- Active noise cancellation algorithm talent:Acoustic engineering and DSP firmware expertise scarcity constrains feature parity for mid-tier manufacturers.
- Legacy PBX integration complexity:Hybrid cloud-on-premise voice environments demand backward compatibility engineering that dilutes R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unified Communication (UC) and Business Headsets Market |
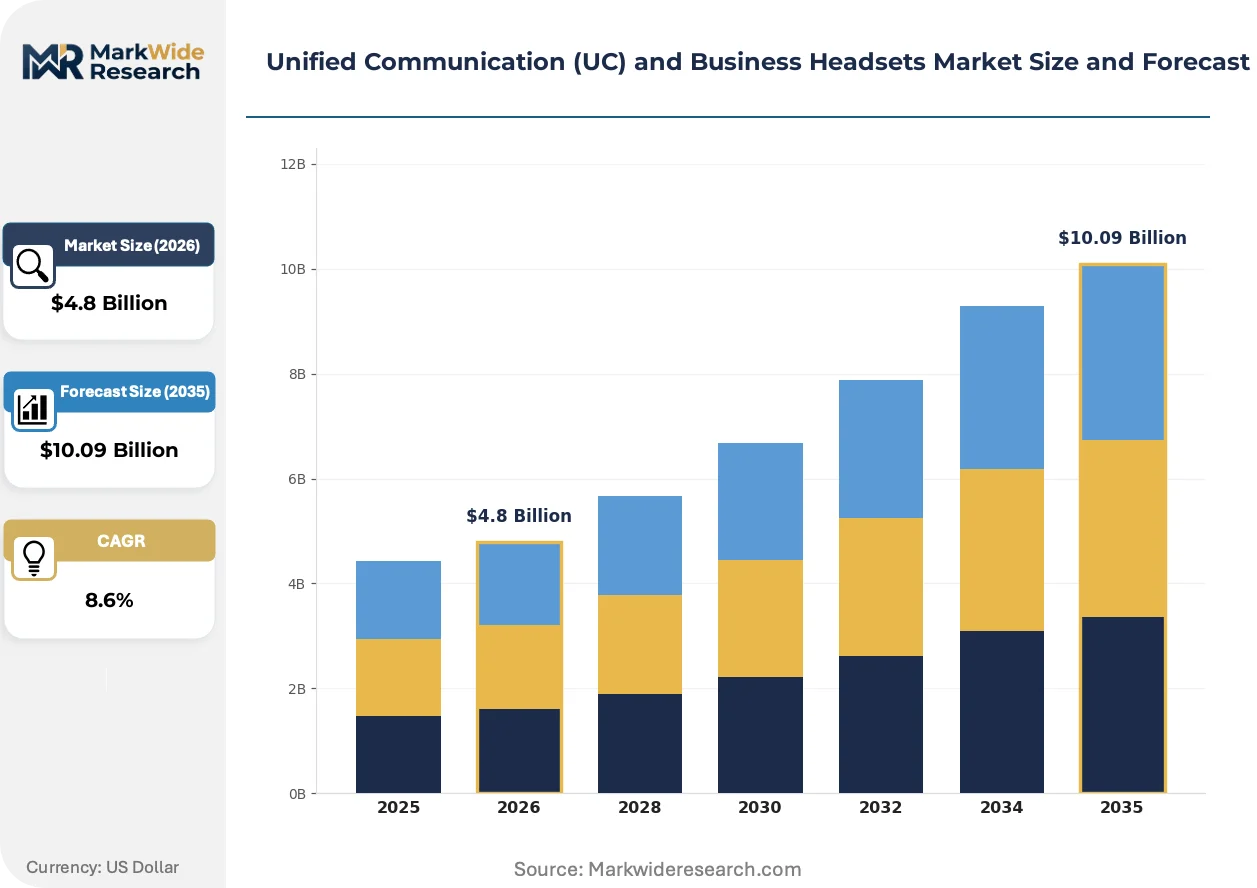
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Headsets, Wireless Headsets, Speakerphones, Conference Phones End User: Corporate Offices, Remote Workers, Contact Centers, SMEs Technology: Bluetooth, VoIP, UC Platforms, Analog Application: Video Conferencing, Voice Calls, Team Collaboration, Customer Support |
| Companies Covered | Sennheiser Electronic GmbH & Co. KG, Audio-Technica Corporation, GN Store Nord A/S (Jabra), Shure Incorporated, Bose Corporation, Logitech, EPOS, Yealink Network Technology Co. Ltd., Poly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unified Communication (UC) and Business Headsets Market Trends and Innovations
Audio peripheral architecture is converging with software-defined functionality, with firmware-upgradable features and AI-driven signal processing replacing fixed hardware specifications as the primary value determinant.
Beamforming microphone arrays with AI-powered voice isolation is supplanting traditional electret condenser configurations in premium tiers. Financial services and legal sector buyers are adopting these systems at accelerated pace to meet confidentiality requirements. The technology is compressing acceptable noise floor thresholds and raising baseline specifications across mid-market segments.
EU Green Deal ecodesign regulations are mandating modular battery replacement and standardized repair documentation for electronic peripherals. Manufacturers must redesign internal layouts to accommodate tool-free disassembly and component accessibility. Premium tier products face the steepest compliance engineering costs, while economy tier suppliers risk market exclusion.
Employer home office equipment stipends are fragmenting centralized IT procurement authority across enterprise segments. Individual employees now select peripherals through approved catalogs, with platform certification badges replacing brand loyalty as the primary selection filter. This pattern is most visible in United States technology and professional services verticals where hybrid work policies are most entrenched.
Unified Communication (UC) and Business Headsets Market Segmentation
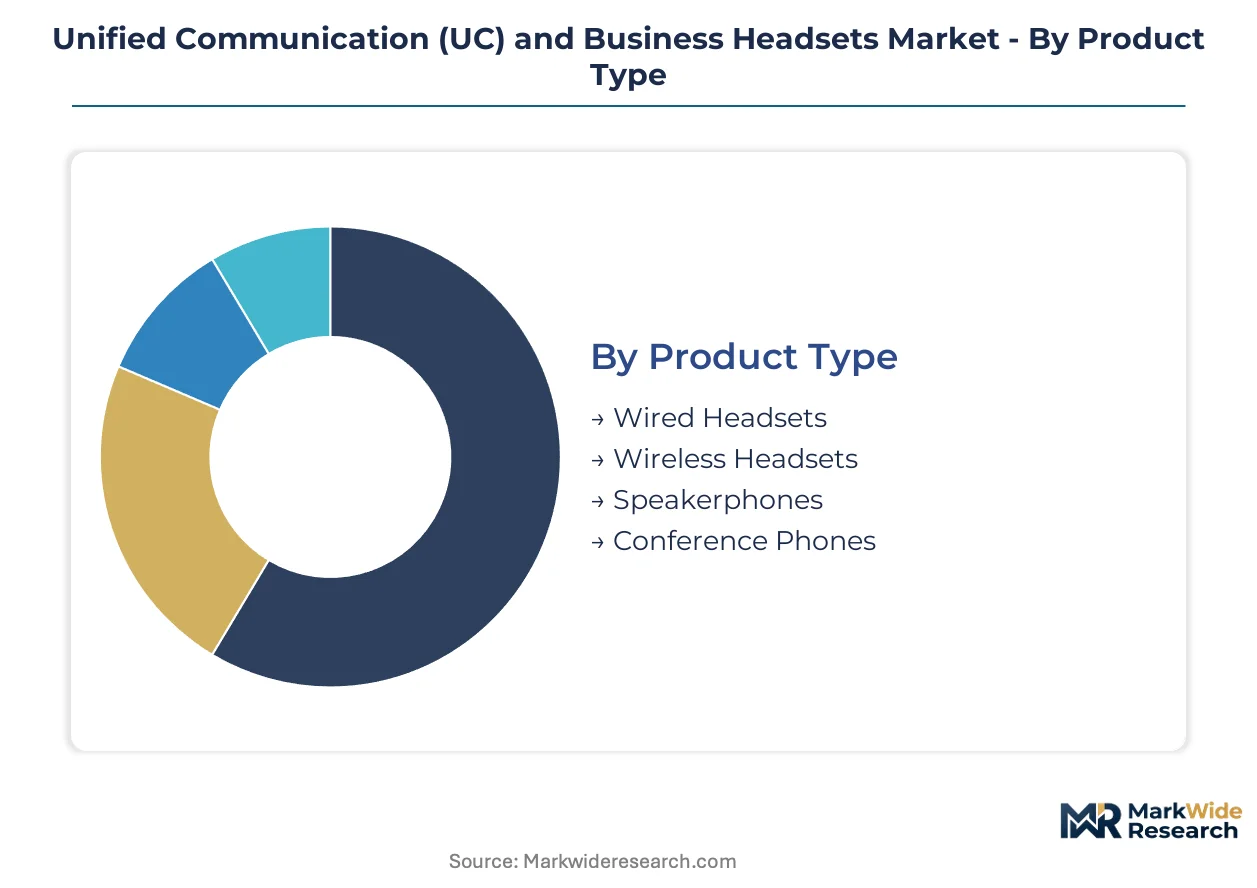
Enterprise procurement patterns fragment across four distinct segmentation axes, each carrying unique certification burdens and price elasticity profiles. Platform compatibility requirements and regulatory compliance thresholds reshape vendor prioritization within every category.
Product Type:
FCC equipment authorization rules and CE marking frameworks enforce divergent electromagnetic compatibility testing timelines across hardware form factors, filtering market access for uncertified entrants.
- Wireless Headsets:Bluetooth 5.x chipsets with active noise cancellation algorithms dominate enterprise mobility mandates. Corporate IT departments in the United States and Germany prioritize these for hybrid workforce standardization, though RF component concentration exposes manufacturers to supply volatility.
- Speakerphones:Beamforming microphone arrays with AI-powered voice isolation are supplanting traditional configurations. Huddle room deployments across Japan accelerate replacement cycles faster than desk-bound alternatives, with financial services buyers adopting at premium pace for confidentiality compliance.
- Wired Headsets:USB-C connectivity with electret condenser microphones retains cost-sensitive contact center volume.
- Conference Phones:Legacy PBX integration demands constrain R&D allocation for hybrid cloud-on-premise environments.
Established volume favors wired configurations; emerging adoption favors speakerphone arrays.
End User:
Procurement authority concentrates differently across buyer types, with IT departments displacing traditional bulk purchasing functions and home office stipends fragmenting centralized decision-making.
- Corporate Offices:Platform certification badges from Microsoft Teams and Zoom determine shortlist eligibility, with six-to-nine month validation cycles compressing product launch windows. Retrofits in the United States, Germany, and Japan anchor replacement demand as legacy desk phone systems reach end-of-life.
- Remote Workers:Employer equipment stipends bypass traditional IT procurement through direct-to-employee channel models. United States technology and professional services verticals exhibit the most entrenched hybrid policies, though smartphone speaker substitution erodes peripheral necessity for casual video calls.
- Contact Centers:Bulk buying authority erodes as enterprise IT assumes procurement control.
- SMEs:Price sensitivity dominates with minimal platform certification requirements.
Legacy demand anchors contact centers; steepest expansion trajectory appears in remote worker segments.
Technology:
Connectivity protocols carry distinct regulatory exposure profiles, with Bluetooth RF emission thresholds and VoIP encryption standards shaping hardware design cycles.
- Bluetooth:Firmware-upgradable features and AI-driven signal processing replace fixed hardware specifications as primary value determinants. EU Green Deal ecodesign regulations mandate modular battery replacement and standardized repair documentation, imposing steepest compliance engineering costs on premium tier products.
- UC Platforms:Peripheral compatibility programs operate as gatekeeper standards determining enterprise procurement qualification. Acoustic engineering and DSP firmware expertise scarcity constrains feature parity for mid-tier manufacturers attempting certification.
- VoIP:Hybrid cloud-on-premise integration complexity dilutes R&D resource allocation.
- Analog:Legacy PBX backward compatibility sustains residual demand in retrofitted corporate environments.
Installed base favors analog connectivity; certification-driven switching favors UC platform-integrated hardware.
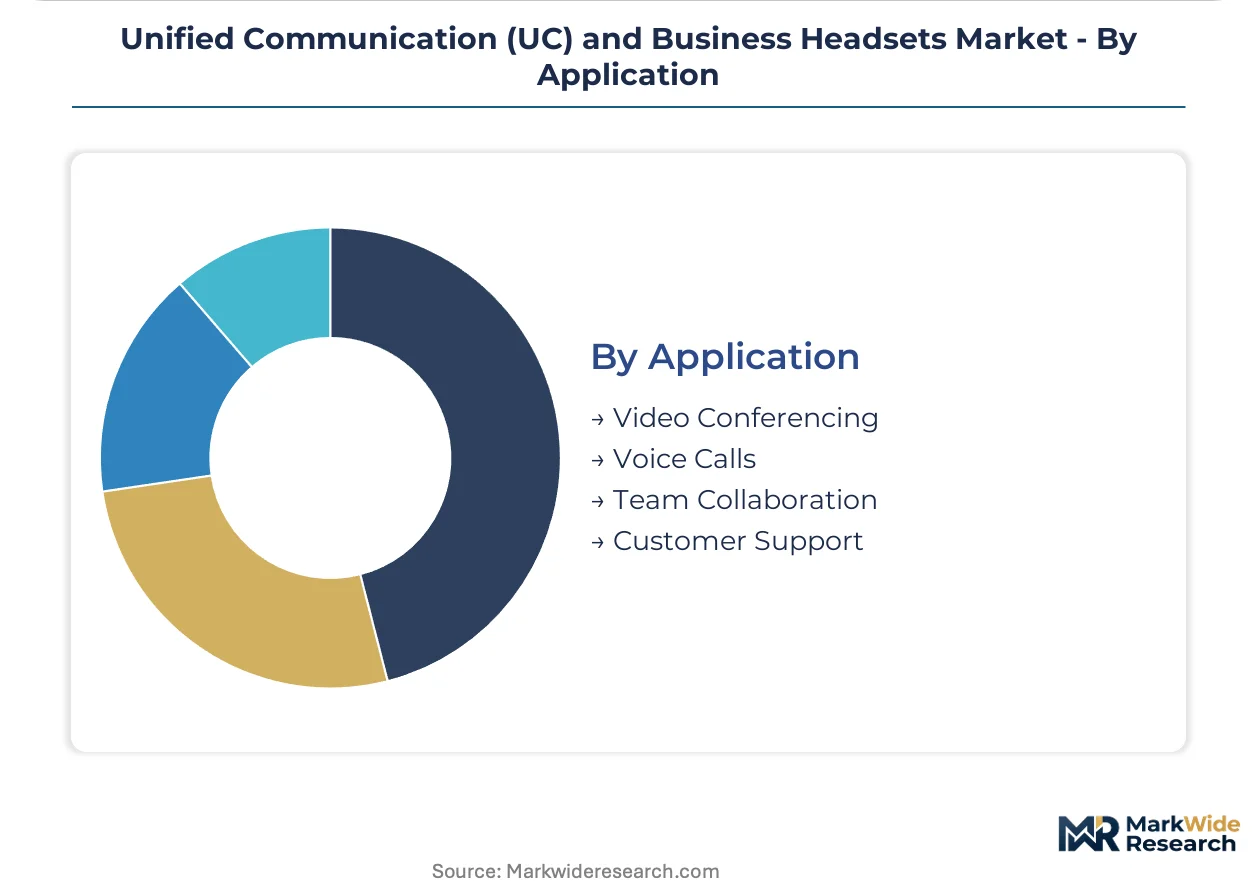
Application:
Use case intensity determines acoustic specification thresholds and confidentiality compliance requirements across vertical segments.
- Video Conferencing:Broadcast-grade audio fidelity requirements differentiate executive and creative professional segments. Sennheiser Electronic GmbH & Co. KG anchors this tier through engineering heritage, while Logitech controls mid-market volume via retail channel depth.
- Customer Support:Noise floor thresholds compress as beamforming arrays with AI-powered voice isolation raise baseline specifications. Legal sector buyers adopt these systems at accelerated pace to meet confidentiality requirements.
- Voice Calls:Standardized specifications dominate with minimal differentiation.
- Team Collaboration:Platform-native integration drives selection over hardware performance metrics.
Transaction volume concentrates in voice calls; specification intensity climbs fastest in video conferencing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable landing stations at Virginia Beach and Bude anchor North American and European data flow infrastructure that underwrites enterprise communication hardware procurement patterns across both continents.
United States
Contact center modernization in financial services hubs drives hardware replacement cycles. FCC equipment authorization rules tighten electromagnetic compatibility standards, filtering non-compliant suppliers from procurement shortlists. Dallas-Fort Worth enterprise corridors anchor corporate IT department standardization for hybrid workforces.
Germany
Industrial Mittelstand office retrofits accelerate as legacy PBX systems reach end-of-life. CE marking requirements under EU Green Deal ecodesign regulations mandate modular battery replacement architectures. Munich and Stuttgart technology clusters concentrate broadcast-grade audio fidelity demand from executive segments.
Japan
Huddle room deployments in Tokyo and Osaka financial districts multiply faster than desk-bound headset replacement. METI energy efficiency guidelines shape standby power consumption specifications for Bluetooth-enabled peripherals. Nagoya manufacturing corridors sustain precision engineering supply chains for active noise cancellation components.
United Kingdom
Professional services verticals in London and Southeast England entrench hybrid work policies with standardized home office equipment stipends. GDPR compliance requirements influence VoIP encryption standards in headset firmware design. Manchester and Birmingham corporate office retrofits follow capital-region procurement patterns with six-month lag cycles.
India
BPO and IT services export hubs in Bengaluru and Hyderabad expand contact center infrastructure with cost-sensitive volume procurement. BIS certification timelines for Bluetooth RF emission thresholds extend market access windows for new entrants. Delhi-NCR enterprise corridors pilot UC platform certification programs for multinational back-office operations.
Unified Communication (UC) and Business Headsets Market Competitive Landscape
Concentration sits with heritage audio engineering specialists and consumer electronics scale players competing across tiered certification-driven segments. The vendor base stratifies between premium noise-cancellation engineering houses, mid-market retail channel controllers, and volume-oriented contact center suppliers. Strategic archetypes include platform certification specialists, acoustic fidelity heritage brands, and retail distribution scale operators. Dominant competitive moves encompass UC platform partnership deepening and modular repairable architecture development for EU regulatory compliance.
Within the heritage engineering tier, GN Store Nord A/S (Jabra) and Sennheiser Electronic GmbH & Co. KG exemplify acoustic R&D depth that anchors premium positioning, while Logitech represents retail channel scale that controls mid-market volume access. These three occupy positions across the certification-badge hierarchy that determines enterprise procurement shortlist eligibility.
| Leading Market Players |
|---|
| Sennheiser Electronic GmbH & Co. KG |
| Audio-Technica Corporation |
| GN Store Nord A/S (Jabra) |
| Shure Incorporated |
| Bose Corporation |
| Logitech |
| EPOS |
| Yealink Network Technology Co. Ltd. |
| Poly |
| Others |
Pricing and Supply Chain Analysis
Ninety-day Bluetooth chipset lead times concentrate procurement leverage among RF component suppliers, compressing margin buffers for headset manufacturers while amplifying pricing power for certified vendors with secured allocation.
Pricing Analysis
Volume-discount tiering structures separate enterprise IT procurement blocks from contact center bulk contracts and individual stipend purchases. Pricing stratifies across premium noise-cancellation tiers, mid-market platform-certified models, and economy wired configurations. Cost compression in economy tiers intensifies as smartphone speaker substitution erodes peripheral necessity. Contact centers exhibit highest price sensitivity; executive segments demonstrate lowest elasticity due to confidentiality compliance mandates.
Supply Chain Analysis
China and Taiwan anchor Bluetooth chipset fabrication and electret condenser microphone component supply. Vietnam and Mexico feed final assembly operations for North American market access. Manufacturers draw from concentrated RF semiconductor sources, lithium-ion cell suppliers, and acoustic driver specialists. Single-source vulnerability in Bluetooth 5.x baseband silicon exposes lead time volatility. Distribution runs through enterprise IT procurement channels, retail e-commerce platforms, and direct-to-employee stipend portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as employer home office stipends displace centralized IT procurement authority, creating niche entry points for specialized vendors outside incumbent channel control.
For Market Incumbents: Compound platform certification depth with modular repairable architectures to defend against EU Green Deal compliance disruption. Deepen Microsoft Teams and Zoom partnership engineering to extend validation cycle advantages. Secure captive supply of active noise cancellation DSP firmware talent through targeted acoustic R&D facility expansion in Germany and Japan. For New Entrants and Emerging Players: Anchor in huddle room speakerphone deployments across Japanese financial districts, where replacement cycles outpace desk-bound headset saturation. Target direct-to-employee channels in United States technology verticals with platform-certified economy-tier SKUs. Pursue white-label manufacturing partnerships with established RF component suppliers to bypass six-to-nine month peripheral compatibility validation timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from consumer electronics parents with stranded audio peripheral divisions lacking UC platform certification infrastructure. Long-term viability hinges on firmware-upgradable feature architectures and circular supply chain positioning under tightening ecodesign mandates. Monitor Microsoft Teams and Zoom peripheral compatibility badge expansion rates as inflection signal for procurement shortlist consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| UC Platform Certification Deepening | Six-to-nine month Microsoft Teams and Zoom validation cycles compress competitor launch windows. |
| Modular Repairable Architecture Development | EU Green Deal ecodesign mandates impose steepest compliance costs on non-adapted premium tier products. |
| RF Component Supply Security | Captive allocation agreements with Taiwan and China chipset fabricators insulate against lead time volatility. |
| Direct-to-Employee Channel Buildout | Employer stipend fragmentation in United States technology verticals bypasses traditional IT procurement gatekeepers. |
| AI-Driven Signal Processing R&D | Beamforming microphone arrays with voice isolation raise baseline specifications for financial services confidentiality compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, CE marking compliance registries, and hyperscaler peripheral compatibility program documentation. Interviews with enterprise IT procurement officers, contact center operations directors, acoustic engineering leads, and UC platform integration specialists informed demand-side validation. Secondary sources include customs trade data for Bluetooth chipset flows, SEC 10-K filings of listed audio peripheral manufacturers, and EU Ecodesign Directive implementation tracking. Bottom-up shipment estimates triangulate against top-down enterprise hardware refresh cycle modeling.
Segmentation dimensions modeled include product type, end user archetype, connectivity technology, and application intensity across the projection horizon. Volume and value outputs derive from enterprise mobility mandate penetration curves, contact center modernization replacement schedules, and home office stipend standardization rates. CAGRs incorporate platform certification timeline compression effects and regulatory compliance cost pass-through assumptions.
Decision-makers should treat outputs as directional under stable FCC electromagnetic compatibility enforcement and unchanged Microsoft Teams peripheral badge requirements; material deviation would warrant model refresh. Specific risk factors include Bluetooth chipset supply disruption, accelerated EU Green Deal ecodesign timeline adoption, and smartphone speaker substitution threshold acceleration in remote worker segments. Recalibration cycles align with material shifts in UC platform certification program expansion and electromagnetic compatibility regulatory threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Cloud UC Calling Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Global Mobile Voip Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
Ucaas in Banking Market
Unified Communications
High Definition HD Voice Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
Unified Monitoring Market
Unified Communications
Ucaas in Energy Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Ucaas in the Manufacturing Market
Unified Communications
United States SMS and MMS Market