
 Underwater Communication System Market | 2026-2036
Underwater Communication System Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Communication System Market Intelligence
The premium-commodity split in underwater communication hardware is shifting toward divergence in signal processing capability versus cost-optimized transducer arrays. L3Harris Technologies leverages proprietary acoustic modem architectures to sustain high-margin defense contracts. Teledyne Technologies Incorporated anchors its position through captive sensor manufacturing and deep integration with oceanographic research vessels.
Underwater communication systems transmit data through acoustic pressure waves, optical pulses, or electromagnetic fields across conductive seawater, with acoustic methods dominating beyond 100-meter depths due to minimal signal attenuation in the kilohertz range. These systems enable real-time command links for autonomous underwater vehicles, seabed infrastructure monitoring, and diver coordination in GPS-denied environments. Acoustic technology occupies the largest installed base while optical methods represent the fastest-expanding segment for short-range, high-bandwidth applications. Defense end users command the deepest procurement budgets, whereas environmental monitoring applications are emerging as a concentrated margin pool for specialized integrators.
The U.S. Navy's certification requirements under NAVAIR specifications, NATO's STANAG interoperability protocols, and the International Telecommunication Union's underwater acoustic frequency allocations collectively shape product development roadmaps and market access conditions for non-aligned suppliers. Stakeholders must weigh sovereign content mandates against the technical advantages of multinational subsystem sourcing when configuring bid strategies for next-generation programs.
Market Dynamics
Acoustic-to-optical technology migration is compressing procurement cycles for high-bandwidth subsea links, while sovereign content mandates in defense procurement are fragmenting supplier qualification pathways across NATO and Indo-Pacific fleets.
Growth Catalysts
- STANAG Interoperability Protocols:NATO standardization accelerates fleet-wide technology refresh cycles, forcing member navies toward unified acoustic modem architectures and cross-border maintenance networks.
- Autonomous Underwater Vehicle Deployment:Military and scientific AUV fleets require real-time command links in GPS-denied environments, pulling demand for resilient acoustic positioning and optical burst-communication systems.
- Seabed Infrastructure Monitoring:Offshore energy operators and cable consortia deploy permanent subsea sensor grids, creating recurring hardware and service revenue pools for integrated communication-telemetry packages.
Market Restraints
- Rare-Earth Magnet Supply Concentration:High-performance acoustic transducers depend on neodymium-dysprosium alloys sourced through concentrated Asian supply chains, exposing procurement to export quota volatility.
- Acoustic Frequency Allocation Friction:ITU underwater acoustic spectrum management creates licensing bottlenecks for commercial operators in congested littoral zones, particularly near major port clusters.
- Optical Signal Attenuation Limits:Seawater turbidity and particulate density constrain optical communication to sub-100-meter depths, preventing unified technology platforms across full ocean depth ranges.
Strategic Opportunities
- Indo-Pacific Territorial Monitoring:Exclusive economic zone surveillance requirements in contested waters drive sovereign demand for indigenous underwater communication manufacturing and maintenance capabilities.
- Environmental Monitoring Convergence:Climate research consortia and fisheries management agencies adopt hybrid acoustic-optical networks for real-time oceanographic data collection, opening non-defense procurement channels.
- AI-Enhanced Signal Processing:Machine learning algorithms for multipath interference cancellation enable higher data rates through legacy acoustic hardware, extending platform lifecycles without full replacement.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Acoustic propagation modeling requires expertise in fluid-structure interaction and oceanographic physics, with limited university pipeline output matching defense-industry hiring velocity.
- NAVAIR Certification Timelines:U.S. Navy airworthiness and underwater system qualification protocols impose multi-year validation cycles, compressing effective contract execution windows for development-heavy programs.
- Legacy Platform Integration Complexity:New modem architectures must interface with fielded sonar and navigation systems using proprietary protocols, forcing costly adapter development or full-stack replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Communication System Market |
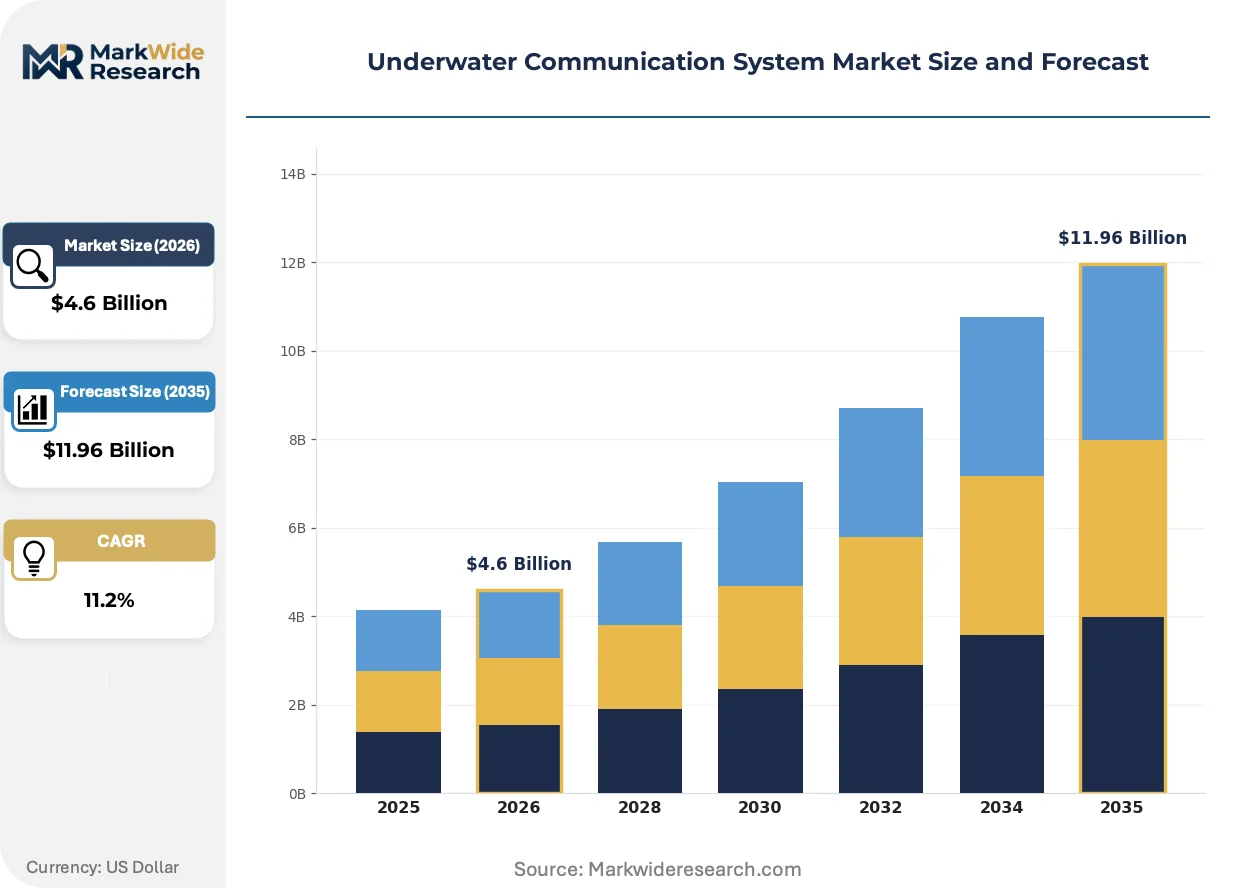
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $11.96 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Acoustic, Optical, Electromagnetic, Hybrid End User: Defense, Maritime, Research Institutions, Commercial Diving Application: Underwater Navigation, Environmental Monitoring, Communication, Surveillance Deployment: Fixed Installations, Portable Systems, AUV-based Solutions, ROV-based Solutions |
| Companies Covered | L3Harris Technologies, Inc., Thales Group, Kongsberg Discovery, Teledyne Technologies Incorporated, Saab AB, Sonardyne International Ltd., EvoLogics GmbH, DSPComm, Hydromea SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Communication System Market Strategic Shifts & Innovations
Signal processing architectures and platform autonomy levels are advancing faster than hardware refresh rates, compressing the effective lifecycle of installed acoustic communication infrastructure.
Photonic-acoustic hybrid modems are integrating silicon photonics-based optical transmitters with conventional piezoelectric acoustic arrays, enabling seamless handoff between high-bandwidth short-range optical links and long-range acoustic channels. Naval research laboratories and offshore energy operators are piloting these systems for diver-to-vehicle coordination and subsea robotics. This convergence is integrating previously separate procurement categories into unified platform specifications, pressuring pure-play acoustic modem suppliers to expand optical capabilities or exit high-growth segments.
EU CSRD sustainability disclosure requirements are mandating environmental impact documentation for seabed-deployed hardware, including end-of-life retrieval protocols and rare-earth material provenance tracking. Equipment suppliers must now embed circular design principles into transducer housings and cable assemblies. Defense contractors with established NATO supply chains are adapting faster than commercial entrants, creating compliance-driven segmentation between qualified and non-qualified vendor pools.
Buyer consolidation among offshore wind developers is compressing vendor qualification timelines and demanding turnkey communication-telemetry packages rather than discrete modem procurement. Developers in the North Sea and Baltic markets now specify integrated seabed monitoring networks with decade-long service commitments. This bundling is displacing component-level suppliers who lack installation and maintenance capabilities, favoring vertically integrated system houses with vessel access and subsea engineering expertise.
Underwater Communication System Market Segmentation
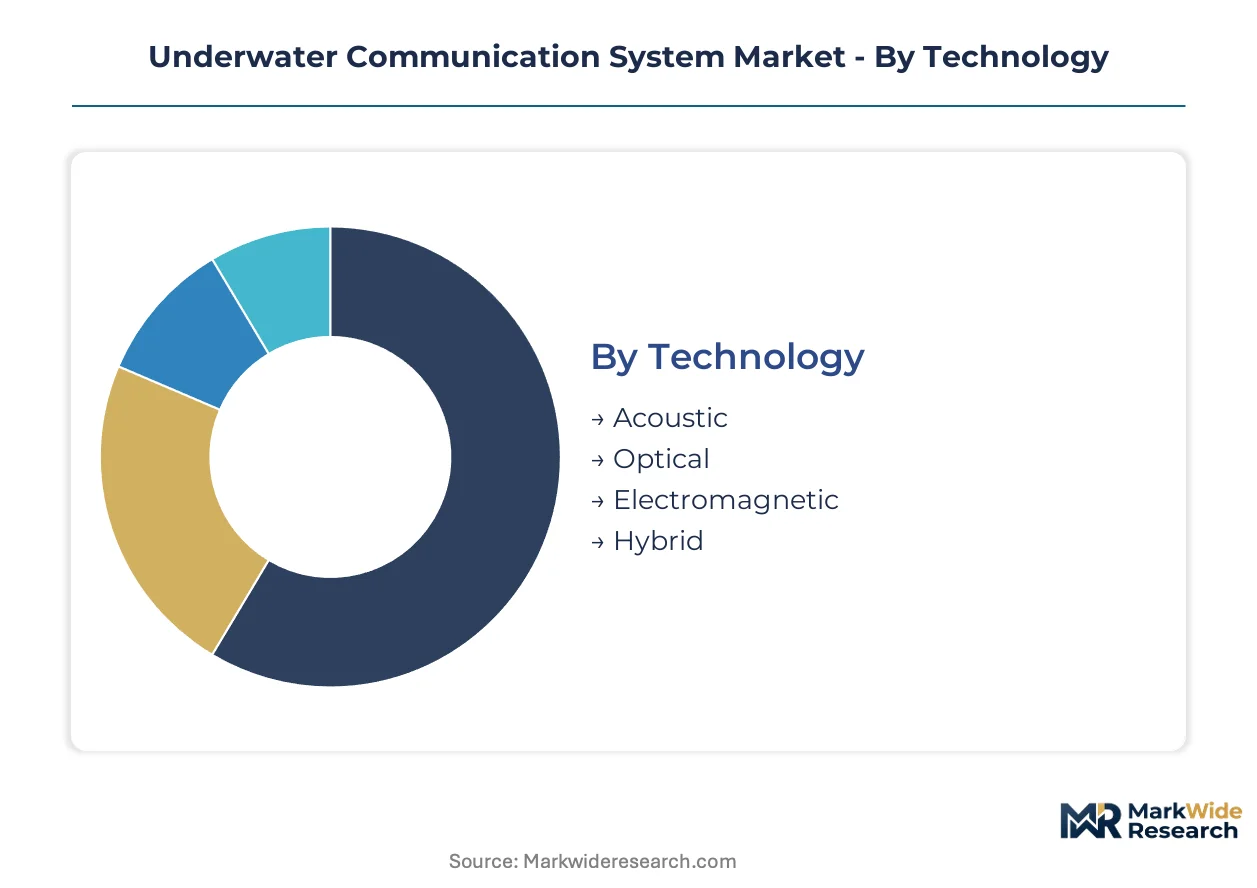
Technology selection in underwater communication systems determines integration architecture, with acoustic and optical platforms demanding fundamentally different vessel-side processing infrastructure and maintenance protocols. End-use requirements across defense, maritime, and research verticals create divergent procurement specifications that reshape supplier qualification pathways.
Technology:
Acoustic platforms dominate standalone deployments where hull-mounted arrays operate independently of auxiliary sensor networks, while hybrid architectures embed communication modules within integrated subsea robotics stacks.
- Acoustic:Piezoelectric transducer arrays transmit data through pressure waves in the kilohertz range with minimal attenuation beyond 100-meter depths. Naval fleets in the United States and NATO member states concentrate procurement for command links in GPS-denied environments, constrained by ITU frequency allocation bottlenecks in congested littoral zones.
- Optical:Silicon photonics-based transmitters pulse light through seawater for high-bandwidth short-range links. Offshore energy operators in the North Sea and Baltic markets deploy these for subsea robotics coordination, limited by turbidity-induced signal attenuation that caps effective range below 100 meters.
- Electromagnetic:Conductive seawater propagation enables low-data-rate signaling across short distances with minimal hardware complexity.
- Hybrid:Photonic-acoustic modems integrate optical and acoustic channels for seamless handoff between range and bandwidth requirements.
Volume placements concentrate in Acoustic; the faster expansion belongs to Hybrid.
End User:
Defense procurement operates on sovereign-content mandates with multi-year certification timelines, while commercial segments prioritize cost-optimized transducer arrays with compressed vendor qualification cycles.
- Defense:Military specifications under NAVAIR protocols demand hardened acoustic modems with cross-platform interoperability. Procurement budgets from the United States Navy and Indo-Pacific fleets anchor revenue concentration, fragmented by STANAG compliance requirements across NATO supply chains.
- Maritime:Offshore energy and cable consortia deploy permanent seabed sensor grids with decade-long service commitments. North Sea and Baltic developers bundle communication-telemetry packages, displacing component suppliers lacking vessel access and subsea engineering capabilities.
- Research Institutions:Oceanographic programs require modular platforms compatible with multiple vessel classes and AUV fleets.
- Commercial Diving:Diver coordination systems prioritize portable acoustic positioning with minimal surface infrastructure.
Defense commands the deepest procurement budgets; Research Institutions show the steepest expansion trajectory as climate funding accelerates.
Application:
Navigation and surveillance applications embed communication functions within broader platform stacks, while environmental monitoring drives standalone sensor network deployments with distinct maintenance economics.
- Underwater Navigation:Acoustic positioning systems enable real-time tracking for AUVs and manned submersibles in denied-GPS zones. Military demand from Indo-Pacific territorial monitoring programs anchors installations, complicated by multipath interference requiring AI-enhanced signal processing.
- Environmental Monitoring:Hybrid acoustic-optical networks collect oceanographic data for climate research consortia and fisheries management. EU CSRD disclosure mandates now require end-of-life retrieval protocols and rare-earth provenance tracking, favoring contractors with established compliance infrastructure.
- Communication:Point-to-point links support diver-to-vehicle coordination and seabed infrastructure status transmission.
- Surveillance:Exclusive economic zone monitoring systems integrate passive acoustic arrays with active communication modems.
Communication holds the largest installed base; Environmental Monitoring gains share fastest on sustainability-linked procurement.
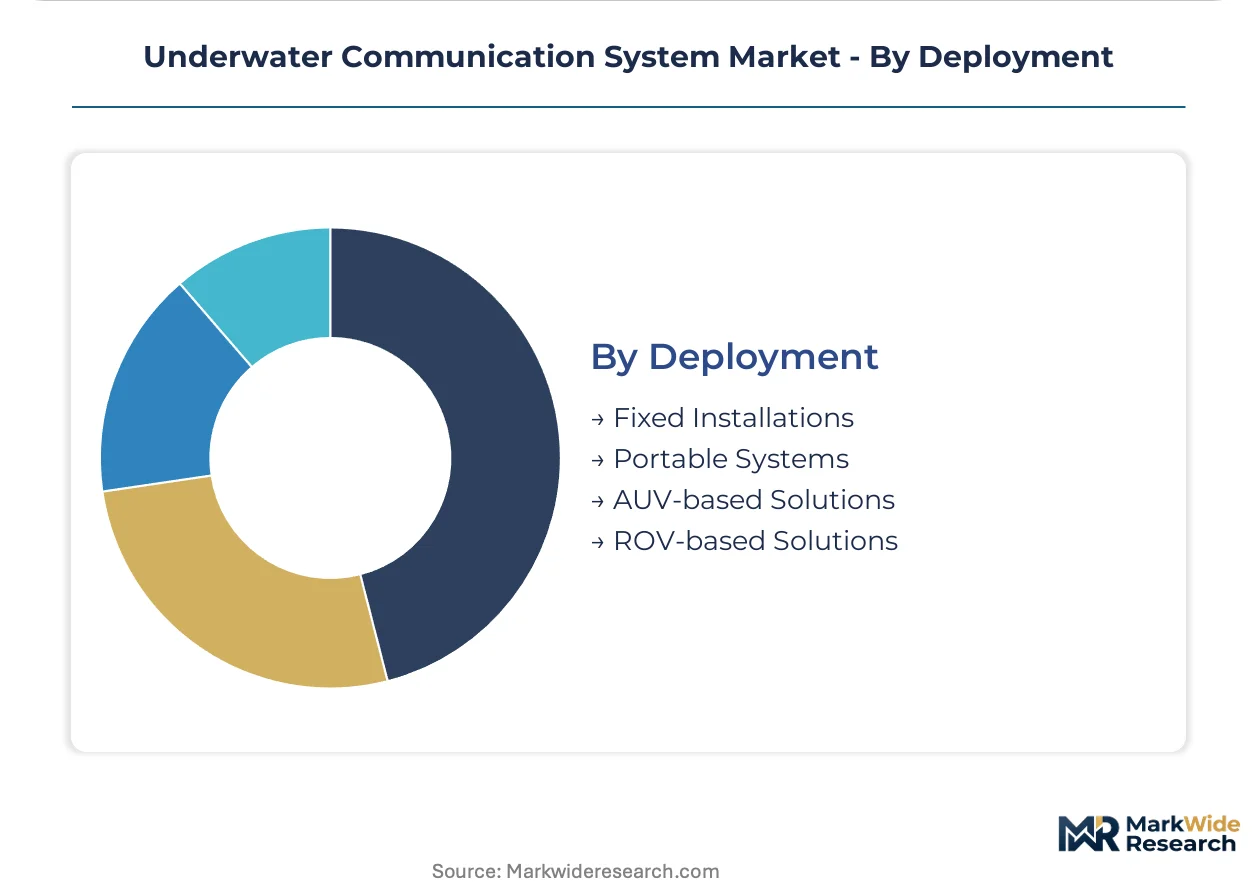
Deployment:
Fixed installations demand permanent seabed anchoring with cable termination infrastructure, while mobile platforms integrate communication payloads within vehicle pressure hulls.
- Fixed Installations:Cabled sensor arrays on offshore energy assets and telecommunications corridors provide continuous telemetry with shore-based power. Baltic and North Sea wind developers specify integrated monitoring networks, compressing vendor qualification timelines toward turnkey system houses.
- AUV-based Solutions:Autonomous underwater vehicles carry acoustic modems for mission-critical command links and data exfiltration. Military and scientific fleet expansion in the United States and Indo-Pacific regions pulls demand for resilient burst-communication architectures.
- Portable Systems:Battery-powered modems support temporary diver operations and rapid-deployment surveillance.
- ROV-based Solutions:Tethered vehicles rely on through-hull communication with surface vessels for real-time control.
Fixed Installations anchor replacement revenue; AUV-based Solutions climb the fastest on fleet autonomy trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors underwater communication system development through NAVAIR certification facilities and the U.S. Navy's submarine research complex. The city's concentration of defense contractors and acoustic testing infrastructure shapes procurement standards that propagate through allied fleets worldwide.
United States
NAVAIR specifications drive hardened acoustic modem procurement for GPS-denied submarine command links. The Department of Defense maintains sovereign-content mandates through the Buy American Act and DFARS regulations. San Diego and Newport News host the primary submarine construction and testing clusters where STANAG-compliant architectures undergo fleet integration.
United Kingdom
Royal Navy Astute-class submarine programs sustain demand for interoperable acoustic positioning systems. The UK Defense and Security Industrial Strategy mandates domestic supply chain participation for critical subsea technologies. Plymouth and Barrow-in-Furness concentrate underwater warfare engineering alongside QinetiQ testing facilities.
Germany
Thyssenkrupp Marine Systems submarine exports pull German acoustic modem specifications into NATO and Indo-Pacific fleets. The country's national security technology export controls under BAFA regulate subsystem transfer licensing. Kiel and Hamburg harbor specialized sonar engineering clusters serving both naval and commercial seabed survey markets.
Japan
Maritime Self-Defense Force submarine fleet expansion accelerates indigenous acoustic communication manufacturing. METI's critical technology protection frameworks restrict foreign subsystem access in defense procurement. Kobe and Yokosuka concentrate naval shipbuilding with integrated sonar-communication system development.
Australia
AUKUS submarine technology sharing agreements mandate acoustic system interoperability with U.S. and UK fleets. The country's defense industry development strategy under DIS prioritizes sovereign maintenance capabilities for subsea networks. Perth and Adelaide host the primary submarine construction and sustainment infrastructure.
Underwater Communication System Market Key Industry Players
Premium-margin players sit above commodity-margin players across defense certification depth versus commercial cost-optimization. The market structures into three tiers: NAVAIR-qualified system integrators commanding multi-year procurement cycles, STANAG-compliant European specialists serving NATO interoperability requirements, and commercial acoustic modem suppliers competing on transducer array pricing. Consolidation pressure intensifies as offshore energy developers demand turnkey communication-telemetry packages rather than discrete hardware procurement.
Within the defense-qualified tier, L3Harris Technologies and Teledyne Technologies Incorporated occupy positions sustained through proprietary acoustic architectures and captive sensor manufacturing. Thales Group represents the European specialist archetype with NATO-wide interoperability reach. Among emerging optical communication specialists, Hydromea SA exemplifies the hybrid-technology challenger segment addressing bandwidth-constrained subsea robotics applications.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| Thales Group |
| Kongsberg Discovery |
| Teledyne Technologies Incorporated |
| Saab AB |
| Sonardyne International Ltd. |
| EvoLogics GmbH |
| DSPComm |
| Hydromea SA |
| Others |
Cost & Logistics Intelligence
Defense contractor consolidation through private-equity-rolled-up specialists has tightened supply discipline across acoustic modem manufacturing, linking captive transducer production to multi-year NAVAIR contract pricing that resists spot-market volatility. Sovereign-content mandates in NATO and Indo-Pacific procurement further anchor pricing power with qualified system integrators who control rare-earth magnet sourcing through concentrated Asian supply chains.
Pricing Analysis
Value-based pricing anchored to mission-critical uptime guarantees dominates defense procurement, with NAVAIR-qualified suppliers commanding premium tiers against STANAG-compliant European specialists and cost-optimized commercial vendors. Price differentiation rests on certification depth versus transducer array performance, with offshore energy developers showing highest sensitivity to upfront hardware costs while military buyers prioritize lifecycle reliability over unit economics. Cost compression in commercial acoustic modems is intensifying because Baltic and North Sea wind developers bundle decade-long service commitments, squeezing component suppliers lacking installation capabilities.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale defense procurement from the United States, United Kingdom, and Japan, while distributor networks serve commercial maritime operators with compressed qualification timelines. Rare-earth magnet dependencies draw from concentrated Chinese and Vietnamese processing capacity, with neodymium-dysprosium alloy supply tethered to export quota volatility. Single-source vulnerability in high-performance piezoelectric ceramic substrates creates procurement risk for non-integrated modem manufacturers. Distribution runs through NATO-aligned system houses with captive sensor fabrication and vessel-access capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multiphysics simulation talent scarcity props pricing for defense-qualified integrators, constraining capacity expansion across acoustic propagation modeling and oceanographic physics expertise.
For Market Incumbents: Hedge against optical-technology substitution by embedding silicon photonics capabilities within legacy acoustic architectures, while securing backward integration into rare-earth magnet supply through offtake agreements with Japanese and Australian processors. STANAG interoperability mandates create switching costs that protect NATO contract positions against Indo-Pacific sovereign-manufacturing pushes. For New Entrants and Emerging Players: Launch via research-institution procurement channels where climate-funding acceleration and EU CSRD disclosure mandates favor modular hybrid acoustic-optical platforms over hardened military specifications. Environmental monitoring applications in fisheries management and oceanographic consortia offer lowest certification barriers and fastest vendor qualification cycles for optical communication specialists lacking NAVAIR pedigree. For Investors and Strategic Acquirers: AUKUS submarine fleet expansion announcements are the leading indicator that sovereign maintenance capabilities will command acquisition premiums across Perth and Adelaide industrial clusters. Five-to-ten year viability favors vertically integrated system houses with vessel access and subsea engineering expertise over pure-play modem suppliers facing bundling pressure from offshore wind developers. Watch for BAFA export-control relaxations on German acoustic subsystem transfers as signal of NATO supply-chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic-Acoustic Hybrid Modem Development | Integrates silicon photonics with piezoelectric arrays for seamless bandwidth-range handoff in subsea robotics. |
| Rare-Earth Supply Chain Securement | Captures neodymium-dysprosium alloy offtake through Australian and Japanese processor partnerships. |
| EU CSRD Compliance Infrastructure Buildout | Enables end-of-life retrieval protocols and provenance tracking for Baltic and North Sea seabed deployments. |
| AUV Fleet Communication Architecture Standardization | Locks in recurring revenue through burst-communication system integration with Indo-Pacific autonomous underwater vehicle programs. |
| Multiphysics Simulation Talent Acquisition | Addresses fluid-structure interaction expertise gaps constraining defense-industry hiring velocity. |
Research Approach
Defense procurement databases, NAVAIR specification filings, and EU CSRD sustainability disclosure records formed the secondary backbone, supplemented by customs data tracking rare-earth magnet trade flows and offshore wind development permits. Primary interviews with submarine program engineers, acoustic modem procurement officers at NATO naval commands, and subsea engineering directors at North Sea wind developers validated segment sizing and technology adoption timelines. Bottom-up unit economics for transducer arrays and top-down defense budget allocation analysis were triangulated against AUV fleet deployment schedules.
Bottom-up modeling tracked acoustic, optical, electromagnetic, and hybrid technology penetration across defense, maritime, research institution, and commercial diving end users, with deployment mode segmentation across fixed installations, AUV-based solutions, portable systems, and ROV-based solutions. CAGRs were derived from installed base replacement cycles and fleet autonomy trends, with AI-enhanced signal processing adoption and photonic-acoustic hybrid modem pilots serving as technology transition inputs. The analytical lens weighted sovereign-content mandate intensity against STANAG interoperability compliance costs across the projection horizon.
Export quota volatility in rare-earth supply chains, ITU acoustic frequency allocation bottlenecks in congested littoral zones, and AUKUS technology-sharing agreement implementation delays are the dominant revision risks to procurement volume assumptions. Forecasts reflect documented assumptions regarding NATO fleet refresh timing and offshore wind developer consolidation patterns. Periodic stress-testing of base assumptions against BAFA licensing decisions and METI critical technology protection framework adjustments is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Football Sportswear Market
Others
Server Market
Others
Cathode Battery Material Market
Others
Drum Motor Market
Others
Nuclear Power Cables Market
Others
Durian Market
Others
Space Cables Market
Others
Disposable Non Woven Sponge Market
Others
Crystal Growth Equipment Market
Others
Global Surface Analysis Market
Others
Embedded Computer Market
Others
Safety Instrumented System (SIS) Market
Others
AI in Home Automation Market
Others
Industrial Wearable Devices Market
Others
Palatants Market
Others
Thailand Commercial Vehicles Lubricants Market